
 AI Camera Market | 2026-2036
AI Camera Market Size, Share, and Industry Trends Forecast 2026-2036
AI Camera Market Intelligence
The shift toward on-device edge AI processing is reshaping the architecture of intelligent camera systems, moving computation from the cloud to the camera itself. This decentralization enables faster response times and enhanced data privacy. Hangzhou Hikvision Digital Technology dominates the security segment with its extensive product portfolio and manufacturing scale. Sony Corporation leverages its leadership in advanced image sensors for high-performance camera components. Hanwha Vision competes through specialized solutions for enterprise and government surveillance applications.
An AI camera integrates a neural processing unit to execute machine learning algorithms directly on the hardware. This capability enables real-time visual data analysis for tasks like object detection or facial recognition without constant server communication. Security cameras for enterprise and government end-users represent the largest product segment by volume. Within the technology stack, facial detection and object tracking algorithms are driving adoption in retail analytics and smart city surveillance applications.
The European Union's GDPR and its proposed AI Act impose strict rules on personal data processing and biometric surveillance. In China, national GB standards dictate technical specifications for security equipment, while the United States FTC scrutinizes data privacy claims. Vendors must navigate this complex and fragmented regulatory landscape to ensure compliant market access and build consumer trust.
Market Dynamics
Decentralization of AI processing from cloud infrastructure to on-device hardware is the central force defining the AI camera market. This shift to edge computing impacts system architecture, data privacy compliance, and real-time analytics capabilities.
Growth Catalysts
- Edge AI Processors:Power-efficient NPUs enable on-camera AI, critical for advanced driver-assistance systems (ADAS) in the automotive sector.
- Smart City Mandates:Public security initiatives in China, under national GB standards, create large-scale demand for surveillance cameras with embedded analytics.
- Retail Analytics Adoption:In-store customer analysis and stockout detection drive adoption in retail, where object tracking algorithms provide operational data.
Market Restraints
- Regulatory Headwinds:The EU's GDPR and proposed AI Act create compliance burdens and restrict uses like public facial recognition, slowing deployment.
- Thermal Management:High-performance edge AI generates significant heat, a hardware constraint that increases system cost and poses reliability challenges.
- System Cost:The higher cost of NPU-equipped cameras creates a barrier versus traditional IP cameras, slowing replacement cycles for cost-sensitive end-users.
Strategic Opportunities
- Industrial Automation:AI vision for defect detection on production lines and predictive maintenance monitoring is a key growth area in manufacturing.
- Sensor Fusion:Combining AI vision with LiDAR or radar creates more robust perception systems for autonomous vehicles and all-weather security applications.
- Precision Agriculture:In markets like India and Brazil, AI cameras for automated crop monitoring and livestock management can improve agricultural yields.
Industry Challenges
- Legacy System Integration:Ensuring interoperability between new AI cameras and customers' existing video management software (VMS) remains a major implementation hurdle.
- Algorithm Standardization:The lack of universal standards for AI model formats complicates procurement for end-users and can lead to vendor lock-in.
- Specialized Talent Gap:A shortage of engineers skilled in optimizing ML models for resource-constrained embedded systems bottlenecks new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Camera Market |
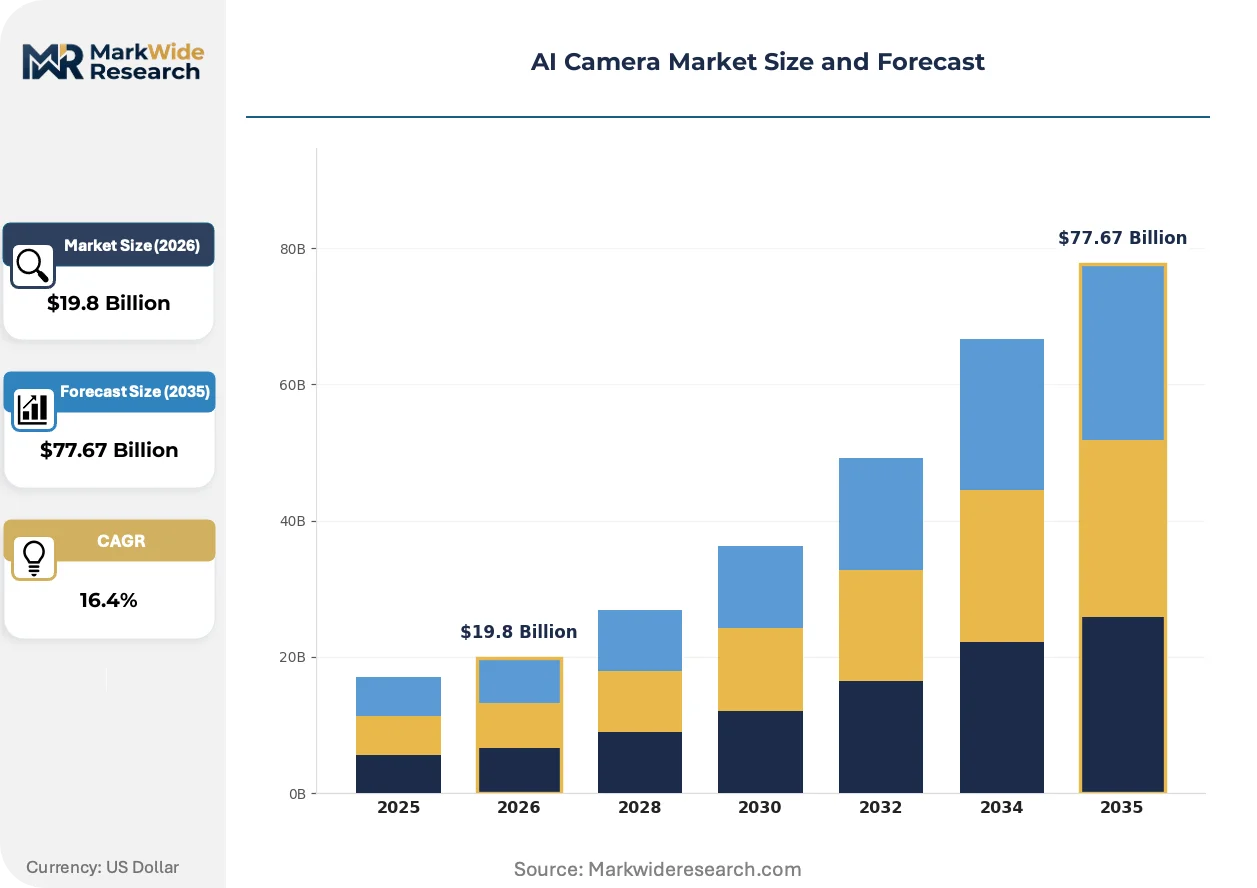
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $77.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, DSLRs, Action Cameras, Security Cameras End User: Consumers, Enterprises, Government, Retailers Technology: Image Recognition, Facial Detection, Object Tracking, Scene Analysis Application: Surveillance, Content Creation, Smart Homes, Automotive |
| Companies Covered | Canon Inc., Honeywell International Inc., Hangzhou Hikvision Digital Technology, DJI Technology, Hanwha Vision, Sony Corporation, Panasonic Corporation, Samsung Electronics, Dahua Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Camera Market Strategic Shifts & Innovations
The market's innovation axis is rotating from capturing and recording visual data to interpreting and predicting events before they occur. This evolution is driven by more sophisticated on-device analytics and new data governance frameworks.
Federated learning allows AI models to train on data across decentralized cameras without exposing raw footage. Healthcare and government sectors are adopting this privacy-preserving technique to meet stringent data handling rules. This method is rendering obsolete the reliance on large, centralized cloud servers for model refinement.
Proposed regulations like the European Union's AI Act are creating a risk-based legal framework for artificial intelligence systems. This directly impacts product design, requiring auditable data trails and clear documentation for systems deemed high-risk. Vendors targeting the EU must now build compliance into their development lifecycle, particularly for biometric identification technologies.
Enterprise procurement is shifting toward subscription-based services for video analytics, moving away from large, upfront hardware capital expenditures. This Video-Surveillance-as-a-Service (VSaaS) model disrupts traditional sales channels by bundling analytics with ongoing support. The shift is most apparent in multi-site retail and commercial property management, where operational budgets are preferred.
AI Camera Market Segmentation
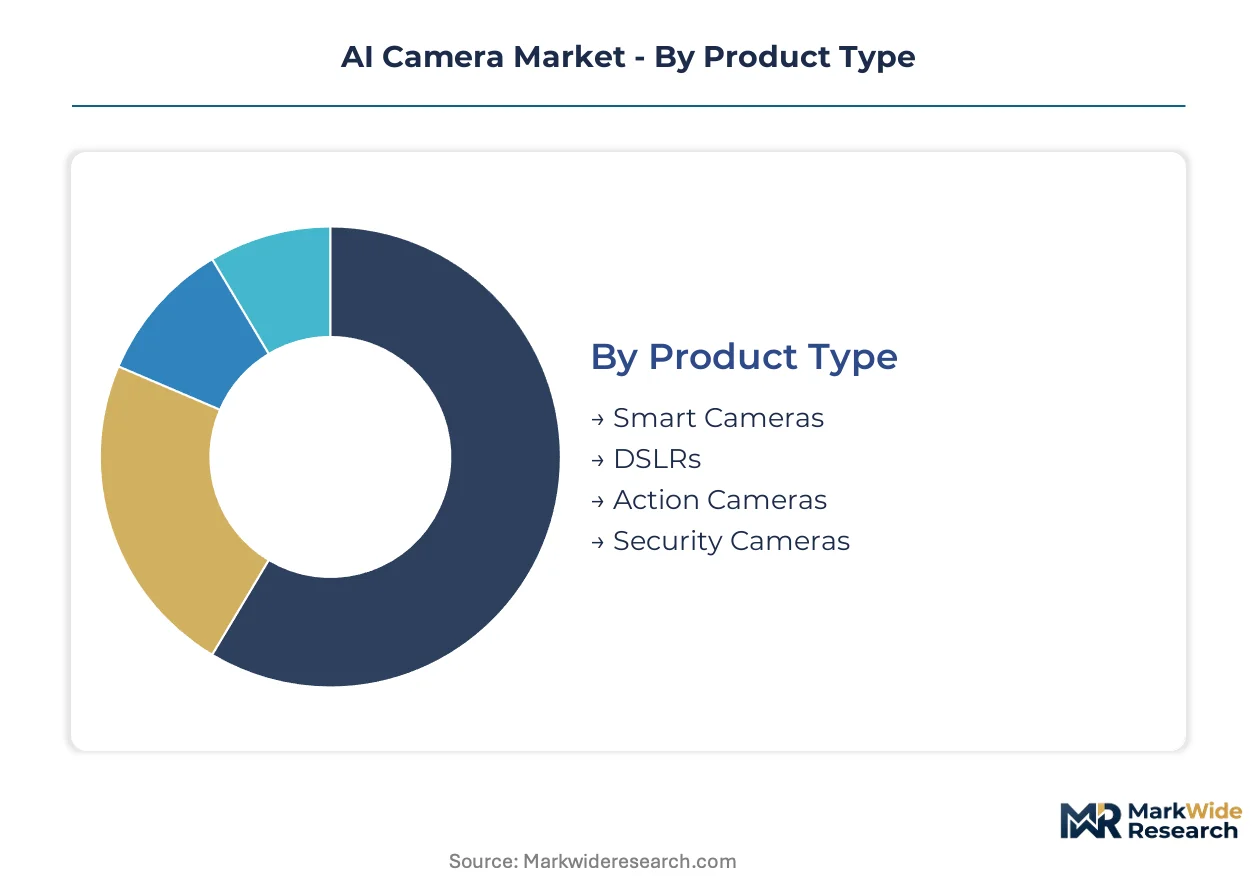
The AI camera market segments reveal distinct value propositions and demand drivers across various product categories, end-user groups, core technologies, and specific applications. Understanding these distinctions allows vendors to target development efforts and market strategies effectively for optimal penetration.
Product Type:
Product type segmentation differentiates camera hardware by its core design and intended function within an operational environment.
- Smart Cameras:These integrated devices feature embedded neural processing units for on-device AI inference, enabling real-time data analysis at the edge. Demand concentrates in industrial automation for quality control and predictive maintenance, driven by the need for immediate anomaly detection.
- Security Cameras:Designed for surveillance and monitoring, these cameras often incorporate advanced AI capabilities like object detection and facial recognition for enhanced threat assessment. The largest volume demand comes from government and enterprise sectors for public safety and asset protection, responding to mandates for intelligent monitoring.
- DSLRs:Digital single-lens reflex cameras primarily serve professional photography and videography, offering high-resolution imaging and manual controls.
- Action Cameras:Compact and rugged cameras capture immersive footage in dynamic environments, popular among sports enthusiasts and adventure travelers.
Security Cameras commands the established base. The steepest expansion runs through Smart Cameras.
End User:
Customer type segmentation highlights distinct purchasing behaviors and operational requirements across various organizational scales.
- Enterprises:Businesses deploy AI cameras for diverse functions including access control, inventory management, and employee safety monitoring across their facilities. Operational efficiency and data security compliance drive enterprise adoption in manufacturing and logistics.
- Government:Public sector entities utilize AI cameras for smart city initiatives, traffic management, and public security surveillance, often integrating with large-scale data platforms. China's national GB standards and public security mandates create significant government demand.
- Consumers:Individual users adopt AI cameras for smart home security, personal content creation, and recreational activities.
- Retailers:Retail businesses use AI cameras for customer analytics, loss prevention, and shelf monitoring to optimize store operations.
Enterprise and government segments drive significant volume, while consumer adoption shapes future interface design.
Technology:
The technology dimension categorizes AI camera capabilities based on the embedded machine learning algorithms they execute.
- Facial Detection:This technology identifies human faces within a camera's field of view, enabling applications such as access control, identity verification, and demographic analysis. Privacy regulations like the EU's GDPR significantly influence the deployment and ethical use of facial detection systems.
- Object Tracking:Object tracking algorithms follow specific objects or individuals across frames, crucial for surveillance, inventory management, and autonomous navigation systems. Retail analytics and smart city surveillance applications extensively use object tracking for operational insights.
- Image Recognition:This capability allows AI cameras to classify and identify objects, scenes, or patterns within visual data.
- Scene Analysis:Scene analysis interprets the overall context and activity within a camera's view, enabling event detection and behavioral anomaly identification.
Algorithm sophistication underpins competitive differentiation, with real-time processing capabilities driving value.
Application:
Application segmentation illustrates the diverse use cases where AI cameras provide specific functional value.
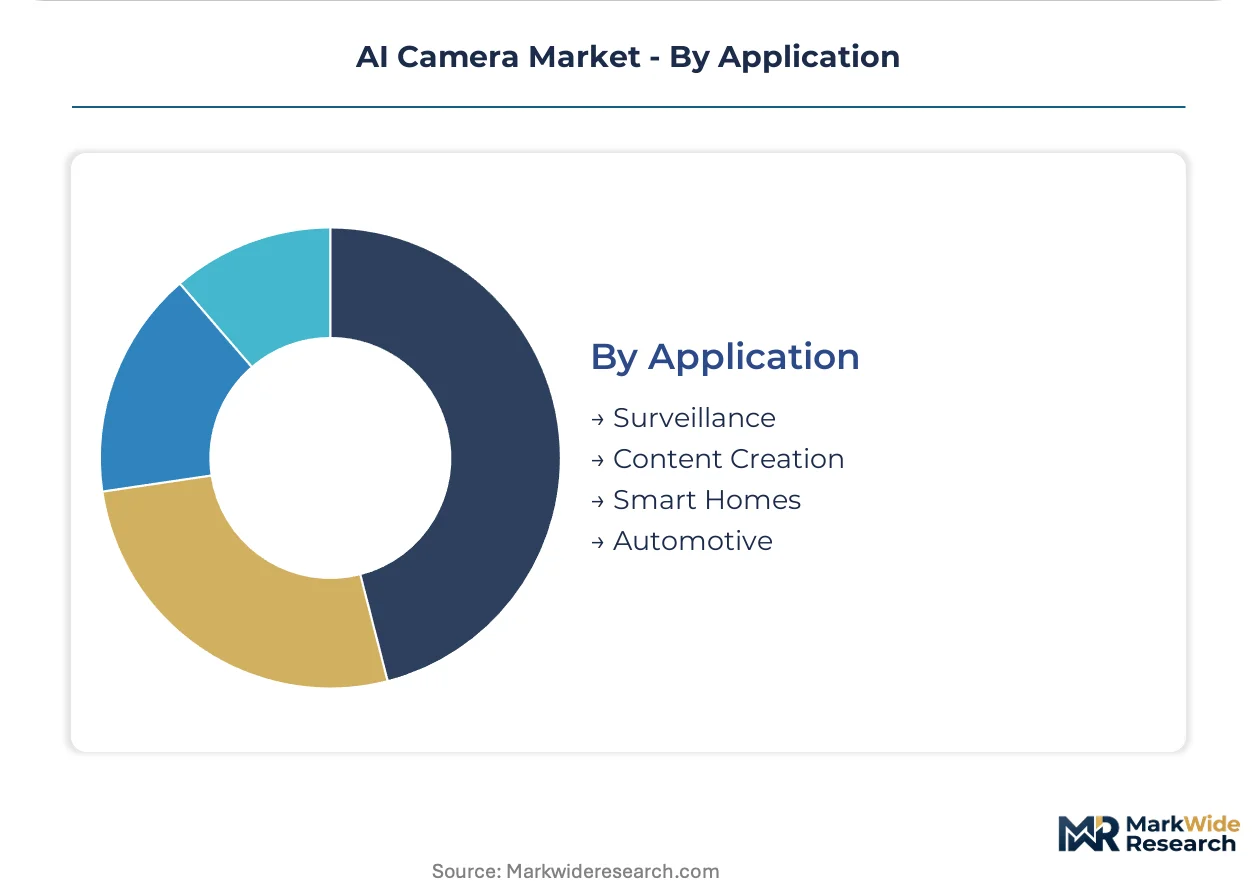
- Surveillance:AI cameras enhance security monitoring by providing intelligent threat detection, intrusion alerts, and forensic analysis capabilities for public and private spaces. Government agencies and large enterprises globally drive demand for advanced surveillance systems.
- Automotive:AI cameras are integral components of advanced driver-assistance systems (ADAS) and autonomous vehicles, performing tasks like lane keeping, traffic sign recognition, and pedestrian detection. The automotive sector's need for robust perception systems drives innovation in power-efficient edge AI processors.
- Content Creation:AI cameras assist in professional and amateur content production through intelligent framing, subject tracking, and automated scene optimization.
- Smart Homes:Consumers integrate AI cameras into smart home ecosystems for security, elderly monitoring, and automated comfort adjustments.
Surveillance applications remain foundational, but specialized deployments in automotive perception are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government and enterprise buyers drive AI camera adoption across diverse geographies. Demand for intelligent surveillance and advanced driver-assistance systems shapes regional market dynamics. Regulatory frameworks significantly influence product development and market access across continents.
China
China's extensive smart city initiatives and public security mandates create significant demand for AI cameras. National GB standards dictate technical specifications for surveillance equipment, ensuring market consistency. The Yangtze River Delta region, including cities like Shanghai and Hangzhou, serves as a hub for AI camera manufacturing and deployment in smart urban infrastructure projects.
United States
Enterprise security and autonomous vehicle development are primary demand drivers in the United States. The FTC scrutinizes data privacy claims, impacting how AI camera data is collected and used. Silicon Valley in California concentrates AI processor development and software integration for advanced vision systems.
Germany
Industrial automation and automotive ADAS applications fuel AI camera adoption in Germany. The EU AI Act significantly influences product design, demanding auditable data trails for high-risk AI systems. Bavaria, with its strong automotive sector, drives innovation in perception systems for connected and autonomous vehicles.
India
Precision agriculture and smart city projects are gaining momentum for AI camera deployment in India. National digital infrastructure policies support the integration of intelligent surveillance solutions. Bengaluru, a major tech hub, is a focal point for AI software development and system integration in the country.
AI Camera Market Key Industry Players
Channel-controlling players compete with product-specialist players across the AI camera market. The competitive landscape features integrated solution providers alongside component manufacturers. Strategic partnerships for sensor fusion and portfolio diversification are common competitive moves.
Within the integrated solution provider archetype, Hangzhou Hikvision Digital Technology and Hanwha Vision occupy strong positions. Hangzhou Hikvision Digital Technology, a Chinese entity, represents scale-driven manufacturing and extensive product portfolios in the security segment. Hanwha Vision offers specialized solutions for enterprise and government surveillance applications. Sony Corporation, a Japanese electronics conglomerate, exemplifies a component specialist, leveraging its leadership in advanced image sensors for high-performance camera components.
| Leading Market Players |
|---|
| Canon Inc. |
| Honeywell International Inc. |
| Hangzhou Hikvision Digital Technology |
| DJI Technology |
| Hanwha Vision |
| Sony Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| Dahua Technology |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's concentrated manufacturing capacity for AI camera components directly influences global pricing leverage for integrated systems. This supply concentration shapes the competitive landscape for major solution providers.
Pricing Analysis
Cost-plus contracts, often indexed to component costs for advanced image sensors and NPUs, define pricing for AI cameras. Price differentiation stems from NPU processing power, the sophistication of embedded analytics, and bundled software services. Pricing softness is emerging in the security camera segment due to increasing competition from Chinese manufacturers and a shift towards VSaaS models. Consumer buyers exhibit the highest price sensitivity for basic functionalities, while government and enterprise clients prioritize performance, compliance, and long-term support for critical surveillance deployments.
Supply Chain Analysis
Geopolitical tensions between major trade blocs represent a significant supply chain risk for AI camera manufacturers, impacting component availability. Geographic supply concentration centers on China for assembly and Japan and South Korea for advanced image sensors and optical lenses. The industry relies heavily on specialized NPUs, often single-sourced from a few key foundries. Distribution runs through direct sales channels for large government and enterprise projects, complemented by value-added resellers for smaller deployments and retail for consumer-grade devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI camera market faces a critical bottleneck in engineering talent, particularly for optimizing machine learning models on resource-constrained embedded systems. This talent scarcity limits new product development and feature expansion across the industry.
For Market Incumbents:Insulate core market share by deepening vertical integration into NPU design and proprietary image sensor manufacturing. This strategy mitigates the threat of commoditization from aggressive new entrants focusing on lower-cost hardware. Invest in advanced R&D for federated learning capabilities to address evolving data privacy regulations like the EU AI Act. Expanding channel control through strategic partnerships with large system integrators also secures long-term client relationships.
For New Entrants and Emerging Players:Underpenetration in industrial automation across emerging economies like India and Brazil presents a significant white-space opportunity. Focus on specialized AI vision solutions for defect detection and predictive maintenance, where immediate ROI is clear. Target mid-sized manufacturing facilities with subscription-based VSaaS models to reduce upfront capital expenditure barriers. A go-to-market angle emphasizing rapid deployment and seamless integration with existing operational technology systems will resonate with these buyers.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized AI software providers with deep expertise in embedded vision algorithms and privacy-preserving techniques like federated learning. The market demonstrates strong long-term viability over the next decade, driven by expanding applications in automotive and industrial sectors. Seek acquisition targets with proven intellectual property in NPU optimization and robust compliance frameworks for EU AI Act requirements. The signal to watch is increasing enterprise procurement of AI vision systems on a VSaaS model.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Power-Efficient Edge AI Processors | Enhances on-device processing capabilities, critical for ADAS applications in automotive. |
| Expand Federated Learning Capabilities | Addresses stringent data privacy regulations like GDPR, enabling compliant deployment in healthcare. |
| Secure Long-Term Image Sensor Supply | Ensures component availability and cost stability amidst global supply chain volatility for camera manufacturers. |
| Acquire Specialized AI Software Firms | Integrates advanced analytics and algorithms, differentiating product offerings in smart city surveillance. |
| Implement VSaaS Business Models | Shifts enterprise procurement from CAPEX to OPEX, appealing to multi-site retail and commercial property managers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, company financial filings, and industry reports. This approach combined in-depth interviews with ADAS engineers, smart city planners, and NPU architects. Secondary validation included analysis of national GB standards and EU AI Act legislative texts. A bottom-up and top-down triangulation process ensured data consistency and market sizing accuracy.
Forecast inputs considered include projected NPU manufacturing capacities and smart city infrastructure investment plans across the analysis window. The analytical framework modeled key segmentation dimensions: product type, end user, core technology, and application. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Automotive ADAS penetration rates served as a critical industry-specific input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large technology conglomerates or specialized AI startups would shift outcomes. Forecasts reflect documented assumptions regarding regulatory stability and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
High Dynamic Range Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Plenoptic Camera Market
Imaging
Global Computed Radiography Market
Imaging
Global Label-Free Array Systems Market
Imaging
Global 3D Imaging Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Photoconductor Drums Market
Imaging
Low-Light Imaging Market
Imaging
Microwave Imaging Market
Imaging
Mobile Camera Module Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Thermal Camera Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Instant Digital Cameras Market