
 Global Computed Radiography Market | 2026-2036
Global Computed Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computed Radiography Market Foresight
Phosphor plate technology is rebalancing product economics as reusable imaging plates replace single-use film across mid-tier healthcare facilities. Fujifilm Holdings Corporation leverages its chemical imaging heritage to sustain phosphor plate manufacturing scale in Asian markets. Konica Minolta anchors its position through specialized cassette designs that integrate with legacy equipment. Siemens Healthineers competes by extending its digital radiography portfolio into computed radiography retrofit solutions for cost-constrained hospitals.
Computed radiography captures X-ray images using photostimulable phosphor plates that release stored energy as visible light when scanned by a laser reader, producing digital images at spatial resolutions typically exceeding 10 line pairs per millimeter. The technology serves facilities requiring filmless workflow without the detector replacement costs of direct radiography. Phosphor plates and CR readers dominate hardware revenue due to replacement cycles and compatibility demands from installed bases. Software solutions represent the fastest-expanding margin pool as vendors bundle AI-assisted image enhancement and cloud-based archiving with hardware contracts. Deployment through integrated PACS architectures concentrates in hospital networks seeking unified imaging infrastructure.
The FDA's 21 CFR Part 1020 regulations govern X-ray system performance standards and reporting requirements for computed radiography devices marketed in the United States. EMA's Medical Device Regulation framework and CE marking requirements shape product design and post-market surveillance obligations across European markets. Japan's PMDA maintains distinct quality management system certifications that filter market access for foreign manufacturers. Stakeholders must monitor evolving cybersecurity standards for connected imaging systems as regulatory bodies integrate data protection into device approval criteria.
Market Dynamics
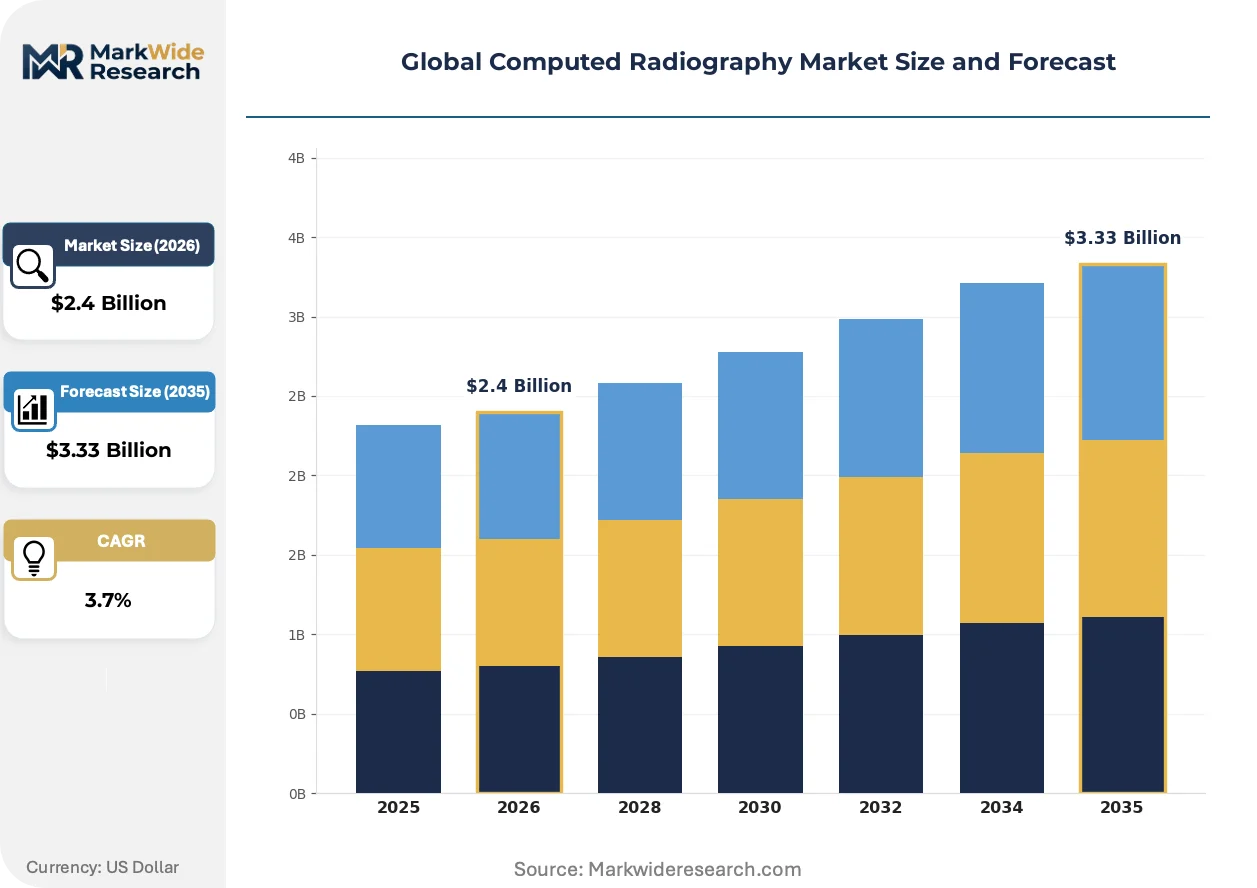
Phosphor plate replacement cycles and direct radiography cost barriers are locking mid-tier hospitals into hybrid imaging workflows, creating sustained demand for CR retrofit solutions that bridge analog infrastructure and digital PACS requirements.
Growth Catalysts
- Companion animal care standards:Veterinary clinics across Brazil and Mexico are upgrading diagnostic capabilities as pet insurance penetration rises and owners demand filmless radiography workflows.
- FDA 21 CFR Part 1020:Performance standards for X-ray systems are standardizing device reporting requirements, reducing certification friction for manufacturers entering the United States market.
- Storage phosphor technology:Reusable imaging plates are eliminating single-use film costs in India's tier-two cities where hospital infrastructure upgrades outpace metro saturation.
Market Restraints
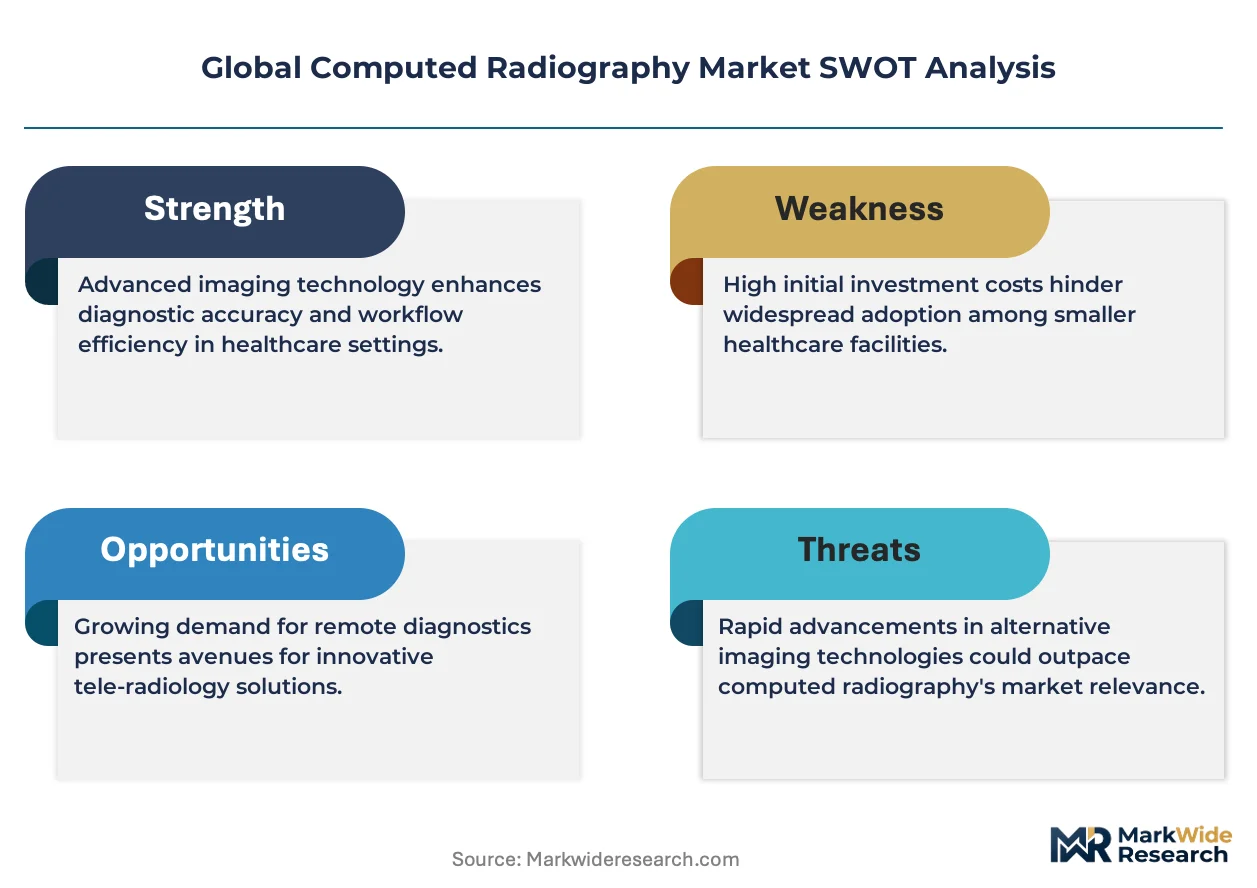
- Rare earth phosphor supply concentration:Europium-doped barium fluorohalide production clusters in Chinese chemical processing zones, exposing plate manufacturers to input volatility and export licensing delays.
- Direct radiography substitution:Flat-panel detector prices are compressing the total cost of ownership gap, threatening CR's position in new hospital construction projects.
- PMDA quality management certification:Japan's distinct QMS requirements filter market access for foreign manufacturers, extending approval timelines beyond European CE marking pathways.
Strategic Opportunities
- AI-assisted image enhancement:Software vendors are bundling machine learning algorithms with hardware contracts, expanding margin pools beyond phosphor plate and reader sales.
- Cloud-based PACS integration:Hospital networks seeking unified imaging infrastructure are creating demand for CR systems with native DICOM connectivity and remote archiving capabilities.
- EMA Medical Device Regulation:Post-market surveillance obligations are favoring vendors with established European service networks, creating barriers for new entrants without local technical support.
Industry Challenges
- Laser reader calibration expertise:Service technicians with photomultiplier tube alignment skills are scarce in emerging markets, extending equipment downtime and eroding customer retention.
- Legacy cassette integration:Retrofit solutions must maintain mechanical compatibility with existing wall-mounted bucky systems and mobile radiography units, constraining design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computed Radiography Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.33 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Imager, CR Reader, Phosphor Plates, Cassette, Software Solutions Application: Chest Imaging, Musculoskeletal Imaging, Dental Diagnostics, Veterinary Imaging, Oncology Screening End User: Diagnostic Centers, Ambulatory Care Facilities, Medical Imaging Clinics, Veterinary Clinics, Academic Research Institutions Deployment: Standalone Systems, Integrated PACS, Mobile Units, Cloud-based Platforms, Edge Computing |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Fujifilm Holdings Corporation, Konica Minolta, Agfa-Gevaert Group, Canon Medical Systems Corporation, Carestream Health, Jones X-Ray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computed Radiography Market Shifts & Advancements
Digital workflow convergence and regulatory data protection mandates are reshaping how CR systems integrate with hospital IT infrastructure and comply with evolving cybersecurity standards.
Wireless phosphor plate scanners are expanding into emergency departments and operating rooms where tethered readers constrain patient throughput. Rural hospitals with limited capital budgets are adopting these portable units to enable bedside radiography without fixed infrastructure investments. The technology is expanding into mobile health screening programs that require rapid deployment and minimal site preparation.
EMA's Medical Device Regulation framework is tightening post-market surveillance obligations for connected imaging systems across European markets. Manufacturers must now demonstrate clinical evidence for software updates and maintain technical documentation throughout product lifecycles. CR vendors with cloud-connected readers are restructuring quality management systems to address this expanded compliance scope.
Buyers are unbundling after-sales service contracts from hardware procurement, negotiating separate agreements for laser reader maintenance and phosphor plate replacement. Independent service organizations are capturing repair revenue previously retained by original equipment manufacturers. This pattern is most visible in Germany's hospital sector where procurement associations aggregate purchasing power across multi-site networks.
Global Computed Radiography Market Segmentation
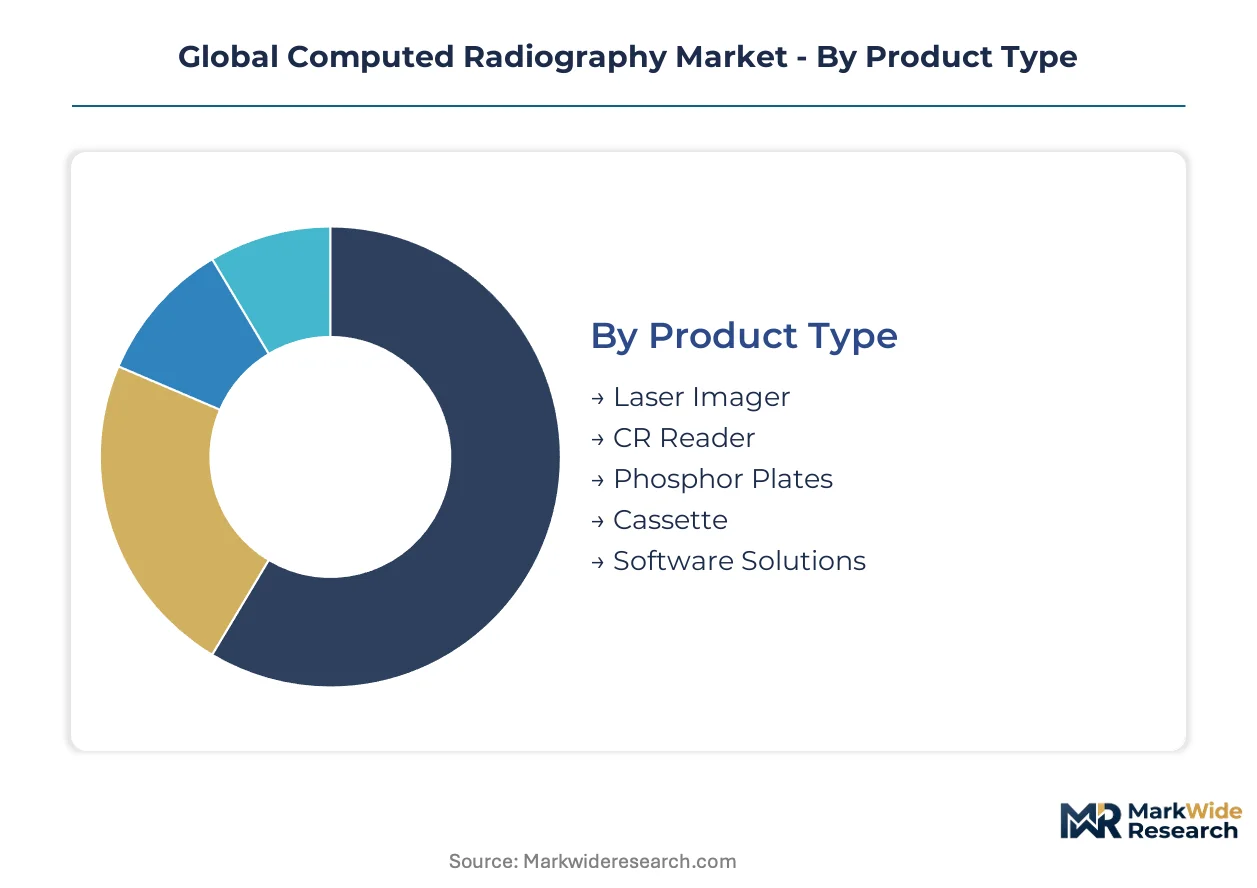
Computed radiography segmentation reveals how hardware replacement cycles, software bundling strategies, and infrastructure constraints fragment purchasing decisions across healthcare systems. Product type and deployment mode configurations determine total cost of ownership calculations for facilities balancing legacy compatibility against digital workflow integration.
Product Type:
Technology specifications define performance thresholds and replacement economics across the hardware stack.
- Phosphor Plates:Europium-doped barium fluorohalide plates store latent X-ray energy for laser-stimulated readout at spatial resolutions exceeding 10 line pairs per millimeter. India's tier-two hospitals concentrate plate demand where infrastructure upgrades outpace metro saturation and reusable plates eliminate recurring film costs.
- Software Solutions:AI-assisted image enhancement algorithms and cloud-based archiving modules bundle with hardware contracts to expand vendor margin pools beyond physical device sales. Diagnostic centers in Brazil and Mexico prioritize these packages as companion animal care standards rise and filmless workflows become mandatory.
- Laser Imager:Photomultiplier tube-based readers convert stored phosphor energy into digital signals with calibrated linearity across exposure ranges.
- CR Reader:Fixed-base scanning units dominate hospital radiology departments with high throughput requirements and established PACS connectivity.
- Cassette:Specialized mechanical housings integrate phosphor plates with legacy wall-mounted bucky systems and mobile radiography units.
Phosphor plates lead on scale; software solutions lead on momentum.
Application:
Clinical use cases impose distinct resolution, contrast, and workflow speed requirements that shape system configuration choices.
- Chest Imaging:High-volume pulmonary and cardiac screening demands rapid plate turnaround and superior contrast resolution for soft-tissue differentiation. Medical imaging clinics across Germany's hospital networks unbundle after-sales service contracts to negotiate separate laser reader maintenance agreements.
- Veterinary Imaging:Companion animal diagnostics requires portable cassette systems adaptable to non-standard patient positioning and variable anatomy sizes. Clinics in Brazil and Mexico are upgrading capabilities as pet insurance penetration rises.
- Musculoskeletal Imaging:Bone and joint radiography prioritizes edge definition and geometric accuracy for fracture detection and orthopedic planning.
- Dental Diagnostics:Intraoral and panoramic applications favor smaller format phosphor plates with specialized cassette designs.
- Oncology Screening:Tumor detection workflows integrate with longitudinal imaging databases requiring robust DICOM metadata handling.
Chest imaging leads on scale; veterinary imaging leads on momentum.
End User:
Facility type determines capital availability, technical staffing levels, and integration complexity with existing health IT infrastructure.
- Diagnostic Centers:High-volume standalone imaging facilities optimize throughput through dedicated CR readers and automated workflow software. Procurement associations across Germany's multi-site hospital networks aggregate purchasing power to capture pricing leverage.
- Veterinary Clinics:Companion animal practices in Brazil and Mexico adopt digital radiography as owner expectations shift toward filmless documentation and specialist referral capabilities.
- Ambulatory Care Facilities:Outpatient settings prioritize compact footprint systems with minimal site preparation requirements.
- Medical Imaging Clinics:Specialized radiology practices demand premium resolution specifications and rapid plate replacement logistics.
- Academic Research Institutions:University hospitals require flexible configurations supporting protocol development and teaching archive access.
Diagnostic centers lead on scale; veterinary clinics lead on momentum.
Deployment:
Infrastructure architecture choices reflect capital constraints, network reliability, and data sovereignty requirements across facility types.
- Integrated PACS:Hospital networks seeking unified imaging infrastructure deploy CR systems with native DICOM connectivity and centralized archiving. EMA's Medical Device Regulation post-market surveillance obligations favor vendors with established European service networks.
- Mobile Units:Wireless phosphor plate scanners enable bedside radiography and emergency department throughput without fixed reader infrastructure. Rural hospitals and mobile health screening programs adopt these for rapid deployment with minimal site preparation.
- Standalone Systems:Self-contained CR configurations serve facilities with limited IT support or isolated network requirements.
- Cloud-based Platforms:Remote archiving and software update delivery reduce on-premise hardware maintenance burdens.
- Edge Computing:Local processing architectures address cybersecurity standards for connected imaging systems as regulatory bodies integrate data protection into device approval criteria.
Integrated PACS leads on scale; mobile units lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital procurement networks concentrate computed radiography demand through multi-site purchasing associations that aggregate hardware and service contracts across federal states.
United States
Veterinary clinics and rural hospitals drive equipment refresh cycles as filmless workflow mandates spread beyond metropolitan radiology departments. FDA 21 CFR Part 1020 performance standards standardize X-ray system reporting requirements for domestic and imported devices. Texas and Florida medical imaging clusters see rising retrofit demand where legacy cassette infrastructure delays full direct radiography conversion.
Germany
Hospital procurement associations across North Rhine-Westphalia and Bavaria unbundle after-sales service from hardware purchases to negotiate separate laser reader maintenance agreements. EMA Medical Device Regulation post-market surveillance obligations favor established European service networks over new entrants. Berlin-Brandenburg diagnostic centers lead software bundling adoption for AI-assisted image enhancement modules.
Japan
PMDA quality management system certifications filter market access for foreign manufacturers, extending approval timelines beyond European pathways. Domestic university hospitals and specialized imaging clinics in the Kanto region maintain preference for phosphor plate systems with proven cassette compatibility. Osaka-based medical device distributors concentrate technical service capabilities for photomultiplier tube calibration.
India
Tier-two cities in Maharashtra and Gujarat outpace metro saturation for hospital infrastructure upgrades where reusable phosphor plates eliminate recurring film costs. CDSCO medical device regulations govern import licensing and quality standards for imaging equipment. Bangalore diagnostic chains adopt cloud-based PACS integration to connect satellite clinics with centralized archiving.
Brazil
Companion animal clinics in São Paulo and Rio de Janeiro upgrade digital radiography capabilities as pet insurance penetration rises and owner expectations shift toward filmless documentation. ANVISA medical device oversight shapes product registration pathways for manufacturers entering Latin America's largest healthcare market. Minas Gerais veterinary networks expand mobile screening programs using wireless phosphor plate scanners.
Global Computed Radiography Market Competitive Landscape
Global majors compete with regional champions across phosphor plate manufacturing scale and specialized cassette engineering capabilities. The vendor base separates into three tiers: diversified imaging conglomerates with full radiography portfolios, chemical heritage specialists leveraging phosphor material science, and regional service organizations capturing maintenance revenue from installed bases. Strategic archetypes include integrated healthcare technology providers, precision chemical imaging specialists, and independent service organizations. Capacity consolidation and software-hardware bundling represent the dominant competitive vectors reshaping margin capture.
Among diversified healthcare technology providers, Siemens Healthineers and GE Healthcare occupy positions spanning diagnostic imaging modalities with retrofit solutions for cost-constrained facilities. Fujifilm Holdings Corporation exemplifies the chemical heritage specialist archetype, anchoring phosphor plate manufacturing scale through legacy imaging material capabilities. Konica Minolta sits within the precision engineering tier, represented by specialized cassette designs that maintain mechanical compatibility with legacy wall-mounted bucky systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Konica Minolta |
| Agfa-Gevaert Group |
| Canon Medical Systems Corporation |
| Carestream Health |
| Jones X-Ray |
| Others |
Supply & Pricing Matrix
Hospital procurement associations across Germany's multi-site networks negotiate consolidated hardware and service contracts, anchoring pricing power in volume-based contract structures that bundle phosphor plate replacement cycles with reader maintenance agreements. This buyer concentration forces vendors to absorb europium-doped barium fluorohalide input volatility through long-term offtake commitments rather than spot-market exposure.
Pricing Analysis
Europium-doped barium fluorohalide plate costs pass through to end-users via three-tier pricing structure across premium, standard, and economy levels, with FDA 21 CFR Part 1020 certification tiers and PMDA quality management marks commanding measurable brand premiums. Price differentiation separates OEM-authorized service bundles from independent maintenance contracts, with India's tier-two hospitals exhibiting highest price sensitivity due to capital constraints. Cost compression in economy-tier readers is intensifying because flat-panel detector substitution threatens CR's position in new construction projects.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and Brazil's ANVISA local-content preferences are reshaping sourcing patterns for cassette assembly and laser reader final integration. Rare earth phosphor production concentrates in Chinese chemical processing zones, while precision photomultiplier tube manufacturing centers on Japan and Germany. Supply chain risk from single-source vulnerability in europium supply constrains plate manufacturer flexibility. Distribution runs through regional medical device distributors with technical service capabilities rather than direct OEM-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The computed radiography market functions as a geographic-arbitrage play where PMDA approval timelines in Japan extend beyond European CE marking pathways, creating cost differentials for vendors with established quality management systems in faster-regulatory jurisdictions.
For Market Incumbents: Anchor service network density in European hospital systems to capture post-market surveillance revenue under EMA Medical Device Regulation obligations. Deepen backward integration into phosphor plate manufacturing to defend margin position against rare earth input volatility. Counter direct radiography substitution threats by extending retrofit solution portfolios for legacy cassette infrastructure. For New Entrants and Emerging Players: FDA 21 CFR Part 1020 standardization in the United States opens a window for certification-focused entrants to bypass legacy regulatory fragmentation. Target veterinary imaging segments in Brazil and Mexico where companion animal care standards are upgrading fastest. Pursue cloud-based PACS integration partnerships as the primary go-to-market angle to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: Chemical heritage specialists with phosphor material science capabilities are the most active acquirer category in this space, seeking precision engineering targets for cassette compatibility expansion. Long-term viability hinges on software-hardware bundling economics rather than standalone reader sales. Monitor flat-panel detector price compression curves as the critical inflection signal for CR retrofit demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Image Enhancement Development | Software vendors bundle machine learning algorithms with hardware contracts to expand margin pools beyond physical device sales. |
| Cloud-Based PACS Integration | Hospital networks seeking unified imaging infrastructure demand CR systems with native DICOM connectivity and remote archiving capabilities. |
| Wireless Phosphor Plate Scanner Launch | Emergency departments and rural hospitals adopt portable units for bedside radiography without fixed infrastructure investments. |
| EMA MDR Compliance Restructuring | Manufacturers restructure quality management systems to address expanded post-market surveillance obligations for connected imaging systems. |
| After-Sales Service Unbundling | Independent service organizations capture repair revenue previously retained by original equipment manufacturers in Germany's hospital sector. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and veterinary clinic operators with secondary validation against FDA 510(k) filings, EMA medical device registration databases, CDSCO import licensing records, and hospital procurement contract aggregators. Bottom-up phosphor plate replacement cycle modeling and top-down imaging modality penetration analysis provided cross-verification.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product type, application, end user, and deployment architecture dimensions. CAGRs were derived from installed base turnover rates and direct radiography substitution elasticity. Forecast inputs incorporated PMDA approval timeline differentials, rare earth phosphor supply concentration risk, and AI software bundling attach rates.
Revisions become necessary when cybersecurity standards for connected imaging systems tighten beyond current EMA frameworks or when flat-panel detector pricing compresses total cost of ownership gaps below CR retrofit economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Phosphor Screen Scanner Market
Imaging
Camera with Flip Screen Market
Imaging
Plenoptic Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Photoconductor Drums Market
Imaging
Global Broadcast Cameras Market
Imaging
Global Digital Binoculars Market
Imaging
Raman-Imaging System Market
Imaging
Handheld Imager Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
360-Degree Camera Market
Imaging
PET Imaging Systems Market
Imaging
LCD Digital Microscope Market
Imaging
Widefield Imaging Systems Market
Imaging
Contact Image Sensor Market
Imaging
North America IP Camera Market