
 Global AI Processor Market | 2026-2036
Global AI Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI Processor Market Foresight
High-performance inference-grade silicon is reorganizing competitive hierarchies in AI compute. NVIDIA Corporation leverages its CUDA software ecosystem to sustain dominance in training workloads. AMD competes through chiplet-based architectures that extend price-performance advantages across cloud deployments. Intel Corporation anchors its position with foundry ambitions and x86-compatible AI accelerators for enterprise data centers.
AI processors are specialized integrated circuits designed to execute matrix multiplication, tensor operations, and neural network inference at throughputs exceeding 100 teraflops with power envelopes below 400 watts. Their primary purpose is to reduce latency and energy consumption in machine learning pipelines that general-purpose CPUs cannot execute efficiently. GPU segments lead in training revenue pools while ASIC architectures capture margin in hyperscaler-specific inference deployments. Edge computing deployment models are expanding fastest as manufacturers integrate AI accelerators into smartphones, vehicles, and industrial sensors.
FDA scrutiny of AI-enabled medical devices, EU AI Act risk-classification requirements, and FCC spectrum rules for AI-driven wireless systems are shaping product validation timelines and market access conditions across jurisdictions. ISO and IEC standards for AI system trustworthiness are becoming procurement gatekeepers for government and enterprise buyers. Stakeholders must monitor how export control regimes on advanced lithography equipment reshape foundry capacity allocation and regional supply security.
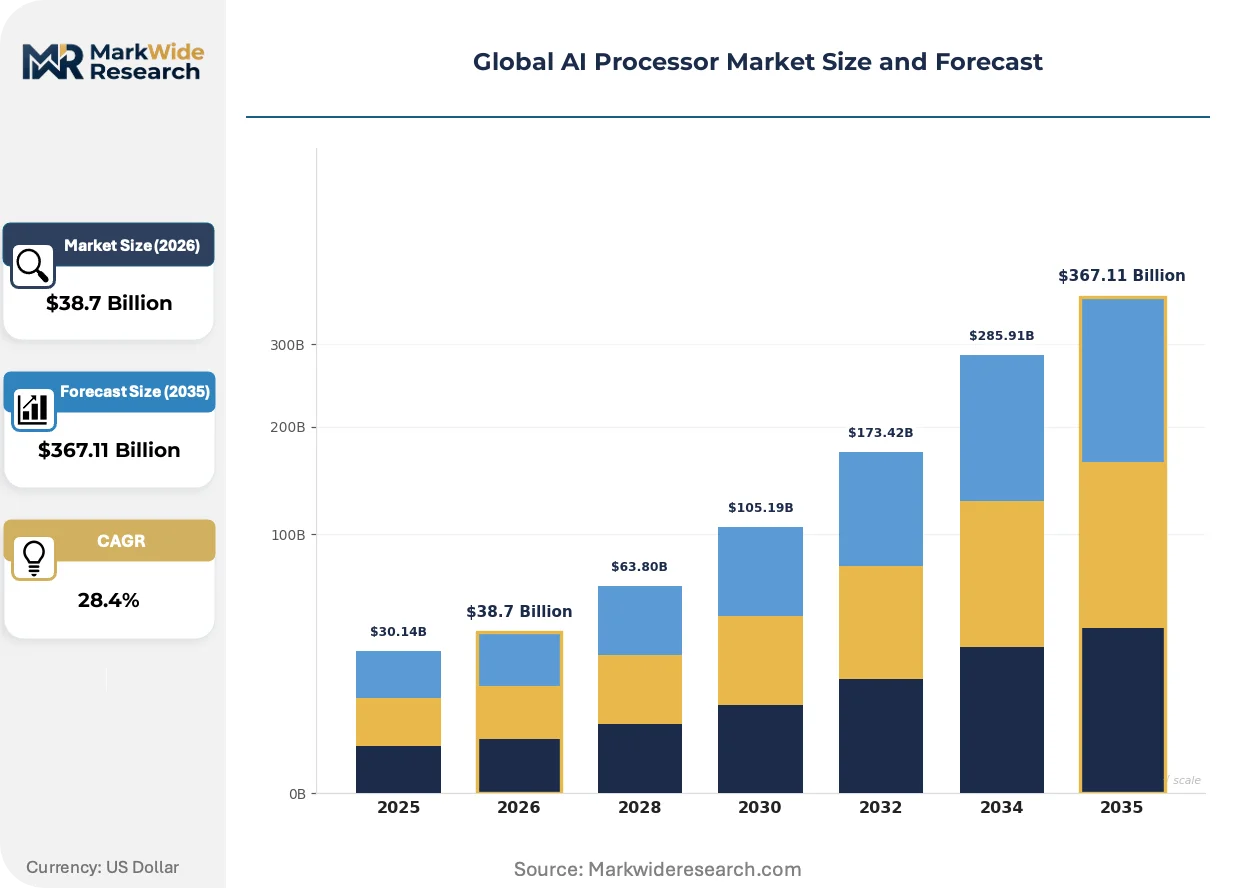
Market Dynamics
Hyperscaler demand for training-grade silicon is compressing foundry capacity allocation toward AI-specific nodes, forcing automotive and consumer electronics buyers into extended allocation queues.
Growth Catalysts
- EU AI Act risk-classification mandates:High-risk system deployers must maintain audit trails and human oversight, creating procurement pull for inference-grade chips with embedded monitoring capabilities.
- Automotive edge AI integration:NHTSA guidance on autonomous vehicle validation is accelerating chiplet-based accelerator adoption for real-time sensor fusion in Detroit and Stuttgart manufacturing clusters.
- Taiwan foundry cluster concentration:TSMC and UMC capacity expansion at the Tainan Science Park is resolving advanced packaging bottlenecks for CoWoS-enabled training processors.
Market Restraints
- Advanced lithography equipment export controls:Dutch and Japanese alignment with US semiconductor restrictions is constraining Chinese foundry access to EUV systems below 7nm.
- High-bandwidth memory supply concentration:SK Hynix and Samsung control 95% of HBM3 supply, exposing NVIDIA and AMD to single-source vulnerability during demand spikes.
- Neuromorphic silicon technical immaturity:Spiking neural network architectures lack mature compiler toolchains, blocking deployment beyond research environments at Intel Labs and IBM Research.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Gujarat and Karnataka state incentives are attracting OSAT investment for chip packaging serving Middle Eastern and African demand corridors.
- Photonic interconnect convergence:Ayar Labs and Lightmatter architectures are enabling optical I/O between chiplets, reducing thermal density in multi-die accelerators for exascale clusters.
- FCC spectrum reallocation for AI-driven wireless:6GHz band expansion is opening edge inference deployment in smart city infrastructure across Dallas, Atlanta, and Seattle metropolitan networks.
Industry Challenges
- Compiler and kernel engineer scarcity:CUDA and SYCL optimization expertise concentrates at NVIDIA, Google, and Meta, forcing second-tier vendors to recruit from academic ML systems programs at MIT, Stanford, and ETH Zurich.
- ISO/IEC 42001 certification timeline compression:AI management system audits require 12-18 month validation cycles that delay hyperscaler qualification for new accelerator generations.
- Legacy x86 data center integration friction:Enterprise buyers in Frankfurt and Chicago face firmware incompatibility when deploying Arm-based AI accelerators alongside existing VMware and SAP infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI Processor Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $367.11 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: GPU, FPGA, ASIC, TPU, DSP Application: Natural Language Processing, Computer Vision, Autonomous Systems, Predictive Analytics, Cybersecurity End User Industry: Telecommunications, Financial Services, Consumer Electronics, Government Defense, Research Institutions Deployment Model: Cloud-Based, Edge Computing, On-Premises, Hybrid Systems |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices (AMD), Intel Corporation, Google (Alphabet), Qualcomm Technologies, Samsung Electronics, Huawei Technologies, Apple Inc., Cerebras Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI Processor Market Shifts & Advancements
Silicon architectures are diverging into workload-specific optimizations as the training-inference economic split deepens, while regulatory compliance becomes a hardware design constraint rather than an afterthought.
Chiplet-based accelerator designs are fragmenting the monolithic GPU paradigm into modular compute, memory, and I/O tiles connected through standardized interconnects. Hyperscalers at Google, Amazon, and Microsoft are customizing these tiles for their internal TPU and Trainium roadmaps. This modularity is fragmenting vendor lock-in by enabling mix-and-match procurement from multiple foundry sources.
EU AI Act conformity assessment requirements are mandating hardware-level audit logging and deterministic execution paths for high-risk AI systems. Chip designers must now embed non-volatile event counters and tamper-evident secure enclaves. Medical device manufacturers in Ireland and the Netherlands are delaying product launches to qualify silicon meeting these MDR-aligned traceability standards.
Hyperscalers are consolidating accelerator procurement through direct foundry partnerships rather than merchant silicon vendors. AWS, Microsoft Azure, and Google Cloud are negotiating multi-year wafer agreements with TSMC and Samsung. This disintermediation is most visible in Washington State and Northern Virginia data center clusters, where custom silicon now dominates new capacity deployments.
Global AI Processor Market Segmentation
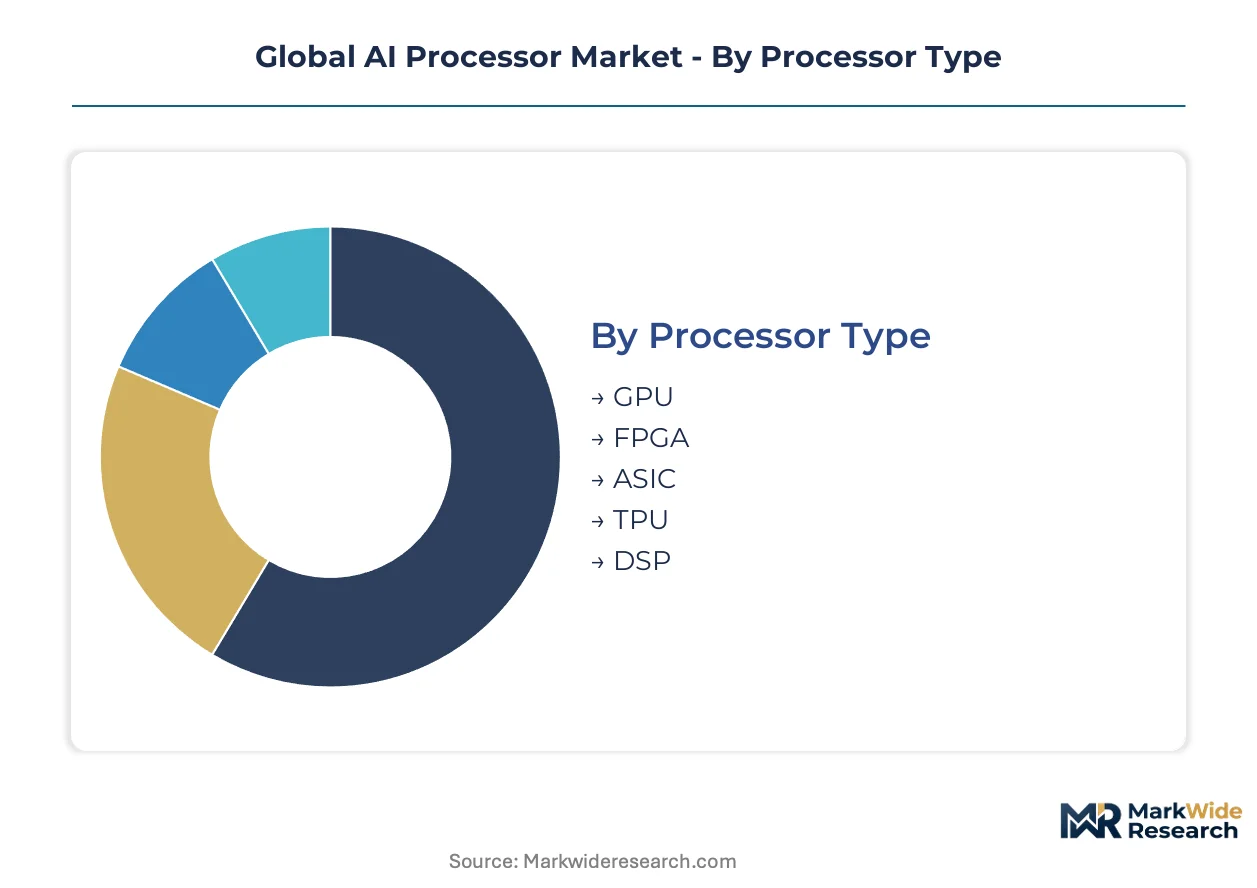
AI processor segmentation reveals distinct procurement channels and margin structures across hardware architectures. Each category maps to specific buyer workflows, from hyperscaler training clusters to embedded automotive inference engines.
Processor Type:
GPU volumes flow through NVIDIA's direct-to-hyperscaler channel, while ASIC procurement concentrates via custom foundry contracts with Google, Amazon, and Microsoft. FPGA and DSP shipments route through traditional distribution for enterprise and industrial buyers.
- GPU:Parallel processing architectures with thousands of CUDA cores execute matrix operations for training workloads. Demand concentrates in Northern Virginia and Washington State data center corridors where Microsoft Azure and Amazon Web Services expand capacity. CUDA software lock-in sustains premium pricing despite AMD MI300 competition.
- ASIC:Application-specific circuits deliver optimal inference efficiency per watt for fixed neural network architectures. Google TPU v5p and Amazon Trainium2 deployments at Pryor, Oklahoma and Boardman, Oregon facilities demonstrate hyperscaler vertical integration into custom silicon design.
- FPGA:Reconfigurable logic from Xilinx and Intel enables algorithm updates post-deployment for financial risk models and 5G baseband processing.
- TPU:Google's proprietary tensor processing units remain captive to internal cloud infrastructure and select academic research partnerships.
- DSP:Digital signal processors handle audio and sensor fusion workloads in automotive and industrial edge applications.
GPU dominates installed base. ASIC is where expansion concentrates.
Application:
Cost tier stratification separates training-grade silicon for large language models from inference-optimized chips for real-time deployment. Natural language processing commands the highest per-unit silicon spend, while cybersecurity applications prioritize low-latency edge inference at volume price points.
- Natural Language Processing:Transformer architectures demand high-memory bandwidth for attention mechanism computation. OpenAI GPT-4 and Anthropic Claude training runs at CoreWeave and Lambda facilities consume H100 clusters with CoWoS advanced packaging.
- Computer Vision:Convolutional and vision transformer networks process medical imaging and manufacturing quality inspection. FDA 510(k) clearance pathways for AI-enabled radiology devices at Massachusetts General Brigham and Stanford Medicine drive inference-grade silicon qualification.
- Autonomous Systems:Real-time sensor fusion for vehicles and drones requires deterministic latency below 10 milliseconds.
- Predictive Analytics:Financial services fraud detection and supply chain forecasting deploy on cloud FPGA instances for model retraining flexibility.
- Cybersecurity:Network intrusion detection and encrypted traffic analysis run on low-power edge accelerators at telecom central offices.
Natural language processing captures the steepest expansion trajectory. Computer vision holds the largest qualified installed base.
End User Industry:
Customer type determines procurement sophistication and contract structure. Financial services buyers negotiate enterprise licensing with dedicated support tiers, while government defense procurement follows classified supply chain requirements.
- Telecommunications:5G baseband processing and radio access network virtualization drive FPGA and DSP deployment at Ericsson and Nokia manufacturing. SK Telecom and Deutsche Telekom trials of AI-optimized RAN equipment in Seoul and Berlin metro areas validate inference acceleration at cell tower edge.
- Financial Services:Real-time fraud detection and algorithmic trading demand sub-microsecond latency. JPMorgan Chase and Goldman Sachs deployment of NVIDIA DGX systems for risk model training in New York and London data centers exemplifies high-frequency procurement patterns.
- Consumer Electronics:Smartphone neural engines from Apple and Qualcomm integrate inference acceleration for photography and voice assistants.
- Government Defense:Classified AI workloads at NSA and GCHQ facilities require trusted foundry sourcing and domestic packaging.
- Research Institutions:Academic access programs from NVIDIA and AMD supply discounted hardware to MIT, Stanford, and ETH Zurich for fundamental ML research.
Financial Services leads revenue per socket. Telecommunications is gaining share fastest.
Deployment Model:
Volume concentration shifts from cloud hyperscalers toward edge computing as manufacturing and automotive buyers internalize AI infrastructure. Maturity curves separate established cloud architectures from emerging hybrid configurations.
- Cloud-Based:Centralized training and inference at AWS, Azure, and Google Cloud facilities. Singapore and Frankfurt regions add dedicated AI accelerator zones to meet EU data sovereignty requirements under GDPR and proposed AI Act localization mandates.
- Edge Computing:Distributed inference at factory floors, retail locations, and vehicle onboard units. Tesla FSD hardware and BMW Leipzig manufacturing lines deploy NVIDIA Jetson and Qualcomm Snapdragon accelerators for real-time decision autonomy.
- On-Premises:Enterprise data center deployment for regulated industries with data residency constraints.
- Hybrid Systems:Split training-inference workloads across cloud and edge with orchestration layer management.
Cloud-Based dominates current capacity. Edge Computing is where deployment expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler procurement in the United States tolerates premium pricing for training-grade silicon, whereas Chinese and Indian buyers prioritize cost-optimized inference chips for edge deployment. European buyers occupy the middle ground, accepting moderate premiums for regulatory-compliant hardware.
United States
Microsoft Azure and Amazon Web Services drive concentrated demand for H100 clusters in Northern Virginia and Washington State data center corridors. FCC spectrum reallocation for 6GHz wireless expansion enables edge inference deployment in Dallas, Atlanta, and Seattle metropolitan networks. NHTSA autonomous vehicle guidance accelerates chiplet-based accelerator adoption in Detroit manufacturing clusters.
China
Domestic cloud providers and EV manufacturers generate substantial volume demand for inference-optimized silicon. MIIT domestic semiconductor self-sufficiency targets channel investment toward legacy node production and advanced packaging capabilities. Yangtze River Delta foundry clusters in Shanghai and Jiangsu face equipment access constraints from Dutch and Japanese lithography export controls.
Germany
Automotive OEMs in Stuttgart and Munich drive qualification of real-time sensor fusion processors for autonomous driving validation. EU AI Act risk-classification mandates require hardware-level audit logging for high-risk AI systems deployed in industrial automation. Bavarian manufacturing lines at BMW Leipzig integrate NVIDIA Jetson accelerators for quality inspection and predictive maintenance.
Japan
Consumer electronics manufacturers and robotics developers sustain demand for low-power edge accelerators. METI semiconductor industry revitalization programs subsidize domestic advanced packaging capacity expansion. Kyushu-based foundry operations focus on mature-node AI accelerators for automotive and industrial sensor applications.
India
Gujarat and Karnataka state incentives under the PLI scheme attract OSAT investment for chip packaging serving Middle Eastern and African demand corridors. CEA power sector mandates create procurement pull for grid-optimization AI processors in renewable energy management. Telangana's Hyderabad cluster hosts Microsoft and Google development centers customizing inference silicon for regional cloud deployment.
Global AI Processor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. CUDA-anchored incumbents command training-workload premiums while chiplet specialists capture price-sensitive inference deployments. Three archetypes dominate: software-ecosystem incumbents, custom-silicon hyperscalers, and modular-architecture challengers. Competitive moves concentrate on foundry partnership negotiations and compiler toolchain investments.
Within the software-ecosystem tier, NVIDIA Corporation anchors premium positioning through CUDA lock-in. AMD and Intel Corporation occupy challenger positions with x86-compatible and chiplet-based alternatives. Among hyperscaler-verticalized players, Google exemplifies captive silicon design for internal cloud infrastructure. These groupings represent strategic positioning rather than definitive market share claims.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices (AMD) |
| Intel Corporation |
| Google (Alphabet) |
| Qualcomm Technologies |
| Samsung Electronics |
| Huawei Technologies |
| Apple Inc. |
| Cerebras Systems |
| Others |
Supply & Pricing Matrix
Long-term wafer agreements between hyperscalers and Taiwan foundries lock in both CoWoS capacity allocation and price visibility across training-grade silicon procurement cycles. These contracts insulate buyers from spot-market volatility in high-bandwidth memory while exposing them to take-or-pay obligations when demand shifts toward inference-optimized architectures.
Pricing Analysis
EU AI Act risk-classification mandates dictate the pricing tier structure by embedding compliance costs into premium silicon tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical-grade chips from industrial automation silicon and consumer edge accelerators. Cost compression in standard-tier inference chips is intensifying because Chinese foundries are scaling legacy-node production for domestic EV manufacturers. Automotive OEMs in Stuttgart and Detroit exhibit highest price sensitivity due to volume procurement cycles, while NSA-classified workloads accept premiums for trusted foundry sourcing.
Supply Chain Analysis
EUV lithography equipment access underwrites foundry capacity allocation for sub-7nm AI accelerators. Manufacturing concentrates in Taiwan, South Korea, and the United States, with advanced packaging drawing from HBM3 supply controlled by SK Hynix and Samsung. Single-source vulnerability in high-bandwidth memory creates exposure during demand spikes for training clusters. Distribution runs through direct foundry partnerships rather than merchant silicon channels as AWS, Microsoft Azure, and Google Cloud consolidate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI processor demand is recovering from foundry capacity constraints as CoWoS bottlenecks ease at Tainan Science Park expansion. Hyperscaler capex cycles drive this recovery through multi-year accelerator deployment commitments.
For Market Incumbents: Compound software ecosystem lock-in by extending CUDA optimization tools to edge inference compilers before AMD and Intel close the toolchain gap. Defend position by securing multi-year HBM3 supply agreements with Samsung and SK Hynix to neutralize memory-constraint threats. Prioritize certification investment for EU AI Act and FDA 510(k) alignment to maintain premium pricing tiers.
For New Entrants and Emerging Players: Differentiate on photonic interconnect integration for exascale cluster thermal management where Ayar Labs and Lightmatter have established technical foundations. Target India PLI scheme beneficiaries in Gujarat and Karnataka for OSAT partnerships serving Middle Eastern and African demand corridors. Pursue academic licensing from MIT, Stanford, and ETH Zurich compiler programs to overcome kernel engineer scarcity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom-silicon hyperscalers with captive foundry partnerships rather than merchant vendors exposed to pricing cycles. Long-term viability hinges on backward integration into advanced packaging capabilities or optical I/O technology. Watch for TSMC CoWoS capacity expansion announcements as the inflection indicator for training-grade silicon supply relief.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Consolidation | AWS, Microsoft Azure, and Google Cloud bypass merchant silicon vendors through direct TSMC wafer agreements. |
| Compiler Toolchain Investment | NVIDIA sustains CUDA ecosystem dominance while AMD recruits from MIT and Stanford ML systems programs. |
| Photonic Interconnect Integration | Ayar Labs and Lightmatter enable optical I/O between chiplets for exascale cluster thermal management. |
| Regulatory Certification Alignment | EU AI Act and FDA 510(k) requirements embed hardware-level audit logging into premium silicon tiers. |
| Geographic Capacity Expansion | India PLI scheme attracts OSAT investment in Gujarat and Karnataka for Middle Eastern and African corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler capex disclosures, TSMC investor presentations, and EU AI Act regulatory filings. Semiconductor engineering executives, cloud infrastructure procurement officers, and foundry account managers provided operational validation. Customs data from Taiwan and South Korea, FDA 510(k) device databases, and ISO certification registries supplied secondary triangulation. Bottom-up wafer demand models and top-down cloud capex analysis converged on segment-level outputs.
Segmentation dimensions modeled include processor architecture, deployment model, end-use industry, and regional regulatory cluster across the projection horizon. GPU, ASIC, FPGA, and TPU categories were tracked separately with application splits across natural language processing, computer vision, and autonomous systems. CAGRs were derived from foundry capacity expansion schedules and hyperscaler infrastructure deployment timelines. HBM3 supply constraints and EU AI Act compliance timelines served as industry-specific forecast inputs.
Material uncertainties — export control alignment on EUV equipment, HBM3 supply concentration, and neuromorphic compiler maturity — sit outside the modeled envelope. Forecasts reflect assumptions about CoWoS capacity expansion and hyperscaler procurement continuity. Practitioners should keep alternative scenarios live as Dutch and Japanese lithography restriction enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Nano Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Mexico Data Center Processor Market