
 Global Label-Free Array Systems Market | 2026-2036
Global Label-Free Array Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Label-Free Array Systems Market Foresight
High-sensitivity surface plasmon resonance tiers are rotating toward the center of procurement decisions in biopharma. Sartorius AG leverages its long-standing bioprocess portfolio to anchor European demand for integrated label-free platforms. Danaher Corporation sustains competitive density through its Life Sciences segment's broad analytical instrumentation footprint. Bruker Corporation specializes in advanced detection architectures that differentiate its offerings in the high-performance research tier.
Label-free array systems detect biomolecular binding events without fluorescent, radioactive, or enzymatic tags, typically achieving detection limits in the picomolar to nanomolar range through optical, mechanical, or electrochemical transduction. These instruments serve primarily to quantify affinity, kinetics, and specificity in drug-target and antigen-antibody interactions. Surface plasmon resonance systems occupy the largest installed base among technology segments, while interferometry configurations are gaining traction where multiplexed throughput demands outpace single-channel legacy designs. Drug discovery applications command the deepest margin pools, though environmental monitoring is emerging as a structurally faster-growing application vertical as regulatory agencies tighten contaminant surveillance mandates.
The FDA's 21 CFR Part 11 electronic records requirements shape validation protocols for systems deployed in GMP-compliant pharmaceutical workflows, while the EMA's ICH Q5C guidelines on viral safety indirectly elevate demand for real-time binding verification in biologics manufacturing. Japan's PMDA maintains stringent analytical method validation standards that favor vendors with documented QMS certifications and local technical support infrastructure. Stakeholders must weigh the trade-off between modular benchtop flexibility and fully automated workstation integration as contract research organizations scale their screening operations.
Market Dynamics
Biopharma R&D facilities are consolidating procurement around high-throughput multiplexed platforms that compress screening timelines from weeks to days, forcing vendors to abandon single-channel legacy architectures.
Growth Catalysts
- EMA's ICH Q5C viral safety guidelines:Biologics manufacturers in Germany and Switzerland now mandate real-time binding verification during cell line characterization, expanding installed base requirements for surface plasmon resonance workstations.
- Environmental contaminant surveillance mandates:The EPA's expanded PFAS monitoring protocols are driving water quality laboratories toward picomolar-sensitivity detection platforms that operate without fluorescent tagging protocols.
- Japan's PMDA analytical method validation standards:Local technical support infrastructure and documented QMS certifications now function as gatekeepers for vendor market access, advantaging established service networks.
Market Restraints
- Gold nanostructure substrate costs:Precious metal price volatility directly compresses gross margins on consumable sensor chips, particularly affecting high-throughput screening operations.
- Optical component supply concentration:Precision interferometry-grade lasers and photodetector arrays originate from a concentrated supplier base in Bavaria and Tokyo prefecture, creating single-source vulnerability.
- Surface chemistry standardization gaps:Inconsistent immobilization protocols across instrument platforms force users to maintain redundant validation datasets, inflating operational overhead.
Strategic Opportunities
- India's CDSCO biosimilar approval pathway:Accelerated abbreviated biologics licensing is generating demand for comparability study infrastructure in Hyderabad and Bangalore R&D clusters.
- Electrochemical transduction convergence:Integration of impedimetric sensing with microfluidic sample handling is opening point-of-care diagnostic applications previously inaccessible to optical platforms.
- Contract research organization channel expansion:WuXi AppTec and Eurofins are unbundling instrument access from full-service contracts, creating subscription-based revenue models for platform vendors.
Industry Challenges
- Bioinformatics specialist scarcity:Kinetic modeling and binding curve interpretation require hybrid skill sets spanning surface chemistry and computational biophysics that academic pipelines undersupply.
- 21 CFR Part 11 validation timelines:Electronic records compliance for GMP workflows extends deployment cycles by four to eight months, straining CRO project scheduling.
- Legacy LIMS integration friction:Proprietary data formats from first-generation SPR systems resist seamless migration to modern cloud-based laboratory information management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Label-Free Array Systems Market |
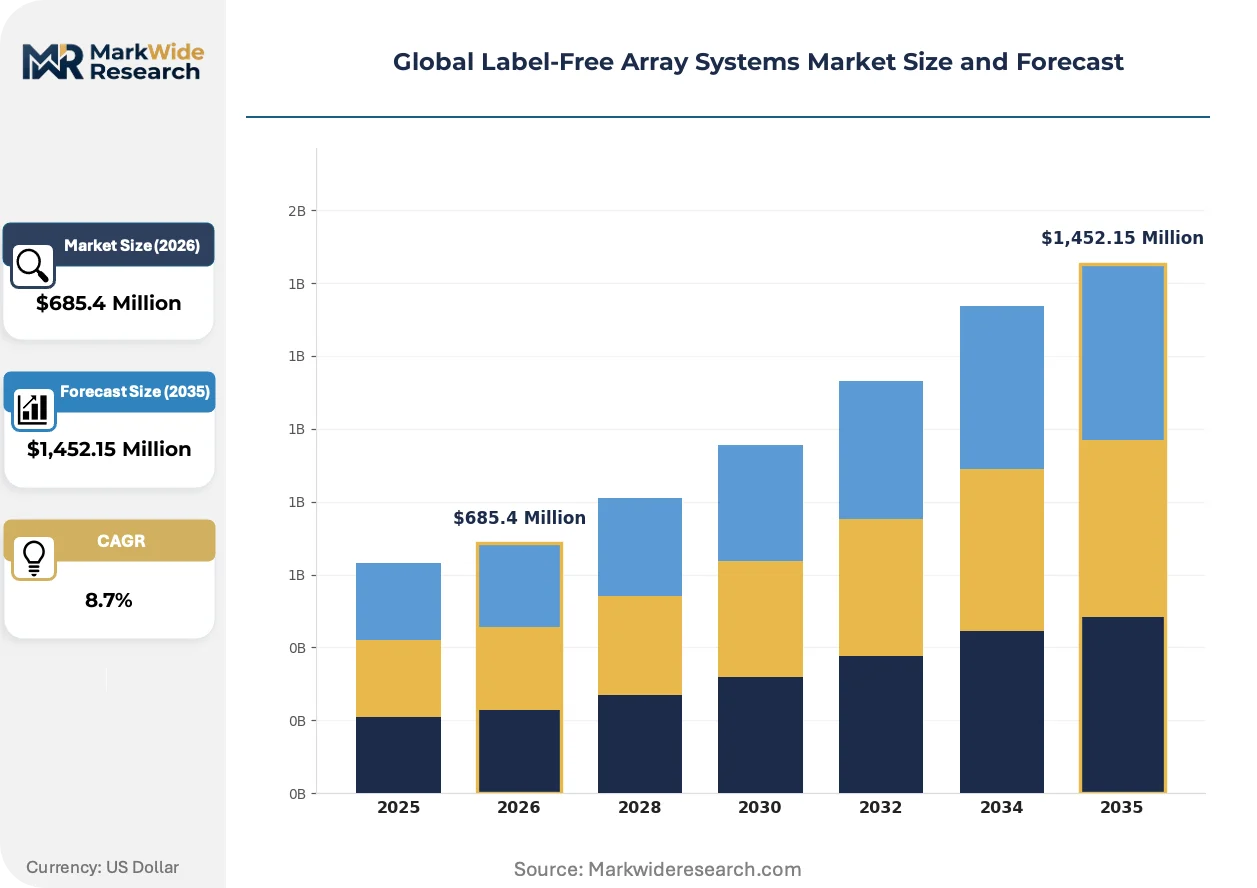
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surface Plasmon Resonance, Optical Waveguide, Quartz Crystal Microbalance, Interferometry, Microcantilever Application: Drug Discovery, Biomarker Identification, Environmental Monitoring, Food Safety Testing, Pathogen Detection Industry Vertical: Pharmaceutical Research, Biotechnology, Environmental Testing Laboratories, Food & Beverage, Academic Institutions Deployment: Benchtop Systems, Portable Devices, Integrated Platforms, Automated Workstations |
| Companies Covered | Sartorius AG, PerkinElmer Inc., Danaher Corporation, F. Hoffmann-La Roche AG, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., Bruker Corporation, Illumina Inc., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Label-Free Array Systems Market Shifts & Advancements
Instrumentation architectures are bifurcating between modular benchtop units for academic flexibility and fully automated workstations for industrial throughput, with software-defined control layers emerging as the decisive differentiator.
Interferometric biosensor arrays are fragmenting the installed base dominance of single-channel surface plasmon resonance systems. Contract research organizations in Massachusetts and Cambridge are adopting sixteen-plex and sixty-four-plex configurations to parallelize fragment screening campaigns. The shift is compressing per-compound characterization costs and forcing incumbent vendors to accelerate multi-channel roadmap development or retreat to specialized kinetic research niches.
The FDA's evolving biosimilar characterization guidance is elevating resolution requirements for affinity and kinetic data packages. Sponsors now face explicit expectations for full kinetic profiles rather than single-point equilibrium measurements, driving replacement demand for instruments with extended association phase capture windows. Biologics manufacturers in Maryland and North Carolina are prioritizing platforms with documented equivalence to reference methods in prior FDA submissions.
Equipment access models are displacing capital purchase dominance in mid-tier CRO segments. Eurofins and Charles River are expanding fleet leasing arrangements that bundle maintenance, reagent supply, and application scientist support into per-run pricing. The unbundling is most advanced in Germany and the United Kingdom, where biotech startup density outpaces internal capital allocation for analytical infrastructure.
Global Label-Free Array Systems Market Segmentation
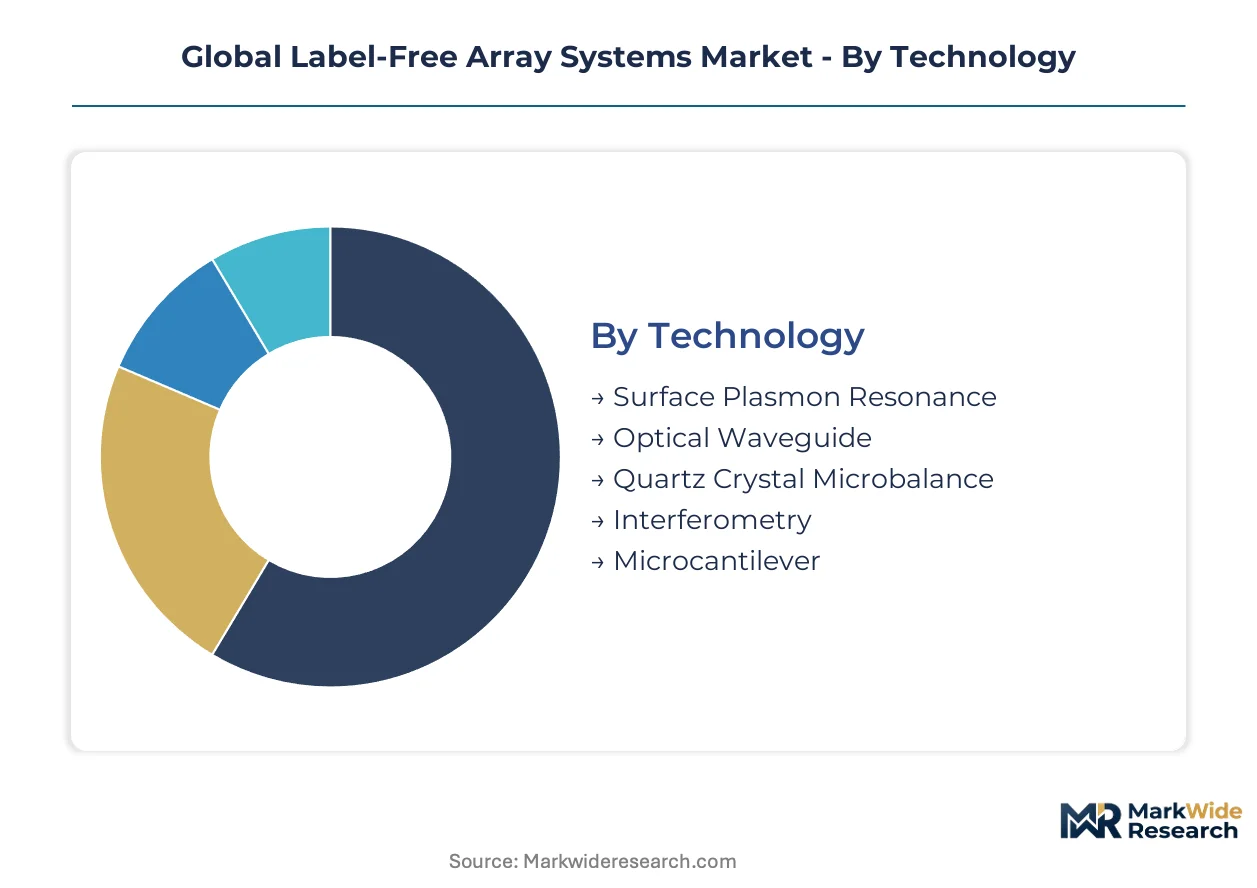
Label-free array systems fragment across detection physics, workflow integration depth, and regulatory compliance tier. Procurement patterns diverge sharply between GMP-validated pharmaceutical deployments and exploratory academic configurations.
Technology:
Surface plasmon resonance dominates domestic manufacturing footprints in Germany and Japan, while interferometry and microcantilever platforms concentrate export-led supply from Massachusetts and Bavaria clusters.
- Surface Plasmon Resonance:Gold-thin-film optical transduction achieves picomolar detection limits through evanescent field coupling at metal-dielectric interfaces. Pharmaceutical manufacturers in North Carolina and Maryland anchor procurement around FDA-validated SPR workstations for biosimilar kinetic characterization.
- Interferometry:White-light interferometric biosensors enable simultaneous 16-plex to 64-plex binding measurements through spatially resolved phase shift detection. Massachusetts contract research organizations compress fragment screening timelines by parallelizing compound libraries across high-density sensor arrays.
- Optical Waveguide:Planar waveguide architectures from Dutch and Swiss suppliers serve environmental monitoring stations requiring continuous unattended operation.
- Quartz Crystal Microbalance:Piezoelectric mass sensors from Japanese vendors dominate academic kinetic studies where cost sensitivity outweighs throughput requirements.
- Microcantilever:Silicon beam deflection systems from German nanofabrication specialists address mechanobiology research niches measuring cellular traction forces.
Surface plasmon resonance commands the established base. The steepest expansion runs through interferometry.
Application:
Drug discovery absorbs premium-tier pricing through fully automated workstations, while environmental monitoring and food safety applications concentrate demand in mid-range benchtop configurations.
- Drug Discovery:Lead optimization workflows quantify binding kinetics, affinity, and specificity across protein-target and antibody-antigen pairs. Biopharma R&D facilities in Germany and Switzerland mandate real-time interaction data under EMA ICH Q5C viral safety protocols.
- Environmental Monitoring:Picomolar-sensitivity detection of PFAS and heavy metal contaminants operates without fluorescent tagging protocols. EPA expanded monitoring mandates drive water quality laboratory procurement in California and Great Lakes states.
- Biomarker Identification:Clinical research organizations in Cambridge and Basel deploy label-free platforms for early-stage disease signature validation.
- Food Safety Testing:Pathogen and allergen screening in European Union member states follows EFSA rapid alert system requirements for unlabeled detection methods.
- Pathogen Detection:Hospital-acquired infection surveillance programs in Japanese medical centers prioritize platforms with PMDA analytical validation documentation.
Drug discovery retains the deepest margin pools. Environmental monitoring climbs fastest on regulatory tailwinds.
Industry Vertical:
Pharmaceutical research and biotechnology concentrate procurement in validated GMP-compliant systems, while academic institutions fragment demand across modular benchtop flexibility tiers.
- Pharmaceutical Research:Integrated workstations with 21 CFR Part 11 electronic records compliance anchor biologics manufacturing workflows. Maryland and North Carolina biologics clusters prioritize platforms with documented FDA submission equivalence.
- Biotechnology:Emerging biotechs in Cambridge and Basel lease instrument access through Eurofins and Charles River fleet arrangements rather than capital deployment.
- Environmental Testing Laboratories:Commercial labs in Germany and the United Kingdom standardize on mid-tier benchtop units for regulatory compliance screening.
- Food & Beverage:Quality control laboratories in Japan and Switzerland adopt portable devices for supply chain point-testing.
- Academic Institutions:University consortia in Massachusetts and Tokyo prefecture drive modular system demand for method development flexibility.
Pharmaceutical research sustains the premium tier. Biotechnology is gaining share fastest through access-model unbundling.
Deployment:
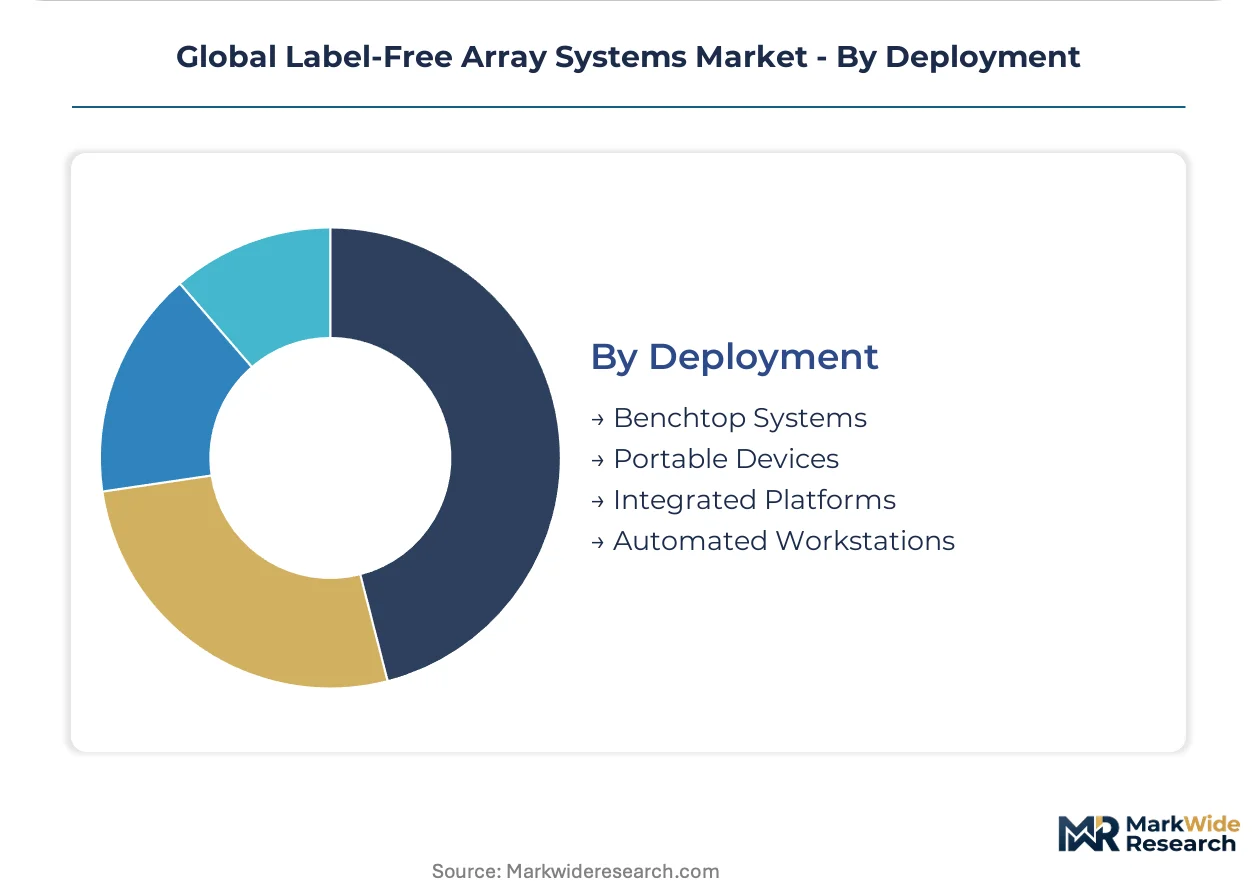
Benchtop systems dominate academic and mid-tier CRO procurement, while automated workstations consolidate in high-throughput pharmaceutical screening operations.
- Automated Workstations:Robotic sample handling, continuous flow injection, and integrated data analysis compress screening timelines from weeks to days. WuXi AppTec and Eurofins deploy these configurations across Hyderabad and Bangalore biosimilar comparability centers.
- Benchtop Systems:Modular optical and electrochemical platforms from German and Japanese vendors serve method development and teaching laboratories where reconfiguration flexibility outweighs throughput.
- Portable Devices:Battery-powered electrochemical sensors address field-deployed environmental monitoring and food safety point-testing.
- Integrated Platforms:Pre-configured microfluidic sample handling with cloud-connected data pipelines target distributed CRO networks requiring standardization.
Benchtop systems hold the volume base. Automated workstations are expanding most quickly on biopharma consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optical component fabrication clusters in Bavaria and Tokyo prefecture concentrate upstream supply for interferometry-grade systems. Biopharma R&D procurement flows through three dominant national markets shaped by distinct regulatory validation regimes.
United States
Maryland and North Carolina biologics manufacturing corridors anchor demand for FDA-validated SPR workstations. The FDA's evolving biosimilar characterization guidance mandates full kinetic profiles rather than single-point equilibrium measurements. Massachusetts contract research organizations in Cambridge and Boston deploy sixteen-plex interferometric arrays to compress fragment screening timelines.
Germany
EMA ICH Q5C viral safety guidelines compel real-time binding verification during cell line characterization. Swiss and German biologics manufacturers standardize on surface plasmon resonance platforms with documented QMS certifications. Bavaria's precision optics cluster supplies laser and photodetector components to domestic instrument assemblers.
Japan
PMDA analytical method validation standards function as gatekeepers for vendor market access. Tokyo prefecture hosts concentrated photonics manufacturing alongside Kansai region biopharma R&D facilities. Japanese medical centers prioritize platforms with local technical support infrastructure for hospital-acquired infection surveillance.
India
CDSCO accelerated biosimilar approval pathways generate demand for comparability study infrastructure. Hyderabad and Bangalore R&D clusters expand analytical capabilities to support abbreviated biologics licensing. WuXi AppTec and domestic CROs deploy automated workstations across southern Indian biotech corridors.
Switzerland
Swissmedic stringent analytical standards favor vendors with European QMS documentation and Basel-based service networks. The country's dense biotech startup ecosystem drives instrument access model adoption through Eurofins fleet leasing arrangements. Zurich and Basel clusters concentrate early-stage biologics development requiring kinetic characterization platforms.
Global Label-Free Array Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the label-free detection tier. The installed base fragments between premium-tier automated workstations and modular benchtop configurations serving academic flexibility requirements. Three strategic archetypes dominate: integrated bioprocess conglomerates with service network density, analytical instrumentation specialists with detection architecture depth, and life sciences conglomerates with broad portfolio coverage. Competitive dynamics center on multi-channel roadmap acceleration and subscription-based access model unbundling.
Within the integrated bioprocess tier, Sartorius AG anchors European demand through bioprocess portfolio adjacencies. Danaher Corporation exemplifies the life sciences conglomerate archetype with analytical instrumentation breadth across its operating segments. Bruker Corporation occupies a position among detection architecture specialists serving high-performance research applications. These three entities represent distinct competitive vectors: service-integrated workflows, portfolio diversification leverage, and technical performance differentiation.
| Leading Market Players |
|---|
| Sartorius AG |
| PerkinElmer Inc. |
| Danaher Corporation |
| F. Hoffmann-La Roche AG |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Illumina Inc. |
| Agilent Technologies Inc. |
| Others |
Supply & Pricing Matrix
Long-term reagent supply contracts with take-or-pay provisions lock in both consumable sensor chip access and predictable per-run cost structures for high-throughput screening operations, insulating biopharma procurement teams from gold nanostructure price volatility while committing CROs to minimum volume thresholds.
Pricing Analysis
FDA 21 CFR Part 11 compliance dictates the pricing tier structure across the installed base, separating GMP-validated automated workstations from exploratory benchtop configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, software validation depth, and bundled application scientist support. Cost compression in the mid-tier benchtop segment is intensifying because electrochemical transduction platforms are displacing optical legacy systems at lower price points. Academic consortia in Massachusetts and Tokyo prefecture exhibit the highest price sensitivity, while Maryland biologics manufacturers prioritize equivalence documentation over unit economics.
Supply Chain Analysis
Strategic stockpiling of precision interferometry-grade lasers and photodetector arrays characterizes vendor inventory posture given single-source concentration in Bavaria and Tokyo prefecture. Gold-thin-film substrates draw from German and Japanese nanofabrication specialists, while silicon microcantilever wafers rest on Dutch MEMS foundries. Single-source vulnerability in optical component supply creates exposure to logistics disruption at Frankfurt and Narita cargo hubs. Distribution runs through direct field service engineer networks for GMP-validated deployments, with benchtop units channeling through academic distributor consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from application scientist support contracts and reagent subscription programs is expanding faster than hardware unit sales, transforming vendor economics toward service-attach models that deepen customer switching costs.
For Market Incumbents: Fortify installed base retention by embedding multi-channel interferometry roadmaps into existing SPR customer workflows before fragment screening demand fully migrates. Accelerate backward integration into captive gold nanostructure substrate production to defend margins against precious metal volatility. Prioritize 21 CFR Part 11 pre-validation packages that compress CRO deployment timelines by four to eight months. For New Entrants and Emerging Players: Anchor in India's CDSCO biosimilar comparability infrastructure gap, where Hyderabad and Bangalore R&D clusters lack sufficient kinetic characterization capacity for accelerated licensing pathways. Target environmental monitoring verticals in California and Great Lakes states where EPA PFAS mandates are outpacing incumbent platform adaptation. Pursue electrochemical-microfluidic convergence as the go-to-market angle for point-of-care diagnostic white space previously inaccessible to optical incumbents. For Investors and Strategic Acquirers: Detection architecture specialists with documented PMDA QMS certifications and established Tokyo prefecture service infrastructure represent the most defensible acquisition profile for long-term Asia-Pacific exposure. Watch for inflection when subscription-based instrument access models surpass fifty percent of mid-tier CRO procurement decisions, signaling irreversible shift from capital purchase dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Channel Roadmap Acceleration | Sixteen-plex interferometric arrays compress fragment screening timelines for Massachusetts CROs. |
| Reagent Subscription Unbundling | Per-run pricing models displace capital purchases in Cambridge and Basel biotech clusters. |
| PMDA QMS Certification Investment | Documented quality management systems function as gatekeepers for Japanese hospital procurement. |
| Backward Integration into Substrates | Captive gold nanostructure production insulates margins from precious metal price volatility. |
| Electrochemical Transduction Convergence | Impedimetric sensing with microfluidic handling opens point-of-care diagnostic applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopharma R&D directors, CRO analytical services heads, regulatory affairs specialists, and environmental testing laboratory managers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA ICH Q5C viral safety guidelines, PMDA analytical method validation standards, EPA expanded PFAS monitoring protocols, and SEC filings of listed analytical instrumentation vendors. Bottom-up instrument shipment tracking triangulated against top-down biopharma R&D spending allocation models.
Across the projection horizon, the analytical framework modeled technology segmentation by detection physics, deployment configuration, and regulatory compliance tier alongside application vertical and end-user industry. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included CDSCO biosimilar approval velocity, EMA viral safety guideline enforcement intensity, and CRO fleet leasing arrangement penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained biopharma R&D consolidation and stable precious metal pricing; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Multimodal Imaging Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Handheld Retinal Scanners Market
Imaging
Acoustic Microscopy Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
LCD Digital Microscope Market
Imaging
Event Camera Market
Imaging
X-Ray Systems Market
Imaging
Digital Microscope Market
Imaging
India CCTV Camera Market
Imaging
Global Ingaas Camera Market
Imaging
EUV Mask Inspection System Market
Imaging
Computational Photography Market