
 Photoconductor Drums Market | 2026-2036
Photoconductor Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Photoconductor Drums Market Insights
Modular drum-cartridge bundling is pivoting as printer OEMs unbundle consumables to capture recurring revenue from enterprise fleets. Fuji Electric Co., Ltd. leverages its integrated polymer film production to control substrate quality from resin to finished drum. Mitsubishi Chemical Corporation anchors the premium OEM segment through proprietary charge-transport layer chemistry. Canon Inc. dominates replacement channel logistics with direct distribution to service networks across East Asia.
Photoconductor drums are cylindrical substrates coated with organic photoconductive layers, typically 20–40 micrometers thick, that convert optical signals into electrostatic latent images in laser and LED printing systems. The primary commercial purpose is to enable high-speed, high-resolution image transfer in office and industrial printing equipment. OEM drum configurations command the highest margin pools due to proprietary lock-in with printer engines, while aftermarket replacements compete on cost in mature installed bases. Polycarbonate-based photoconductors lead material demand for their charge stability under repeated cycling, though ceramic substrates are gaining traction in extreme-duty industrial printing environments.
Japan's METI enforces energy-efficiency standards that shape drum design specifications for domestic printer manufacturing, while China's SAMR administers GB standards governing electrophotographic equipment safety and electromagnetic compatibility. The EU REACH regulation constrains substance choices in photoconductive coatings, compelling reformulation of charge-generation materials. Stakeholders must monitor divergence between regional chemical compliance regimes and assess whether localized coating capacity or centralized export manufacturing better serves multi-jurisdiction cost structures.
Market Dynamics
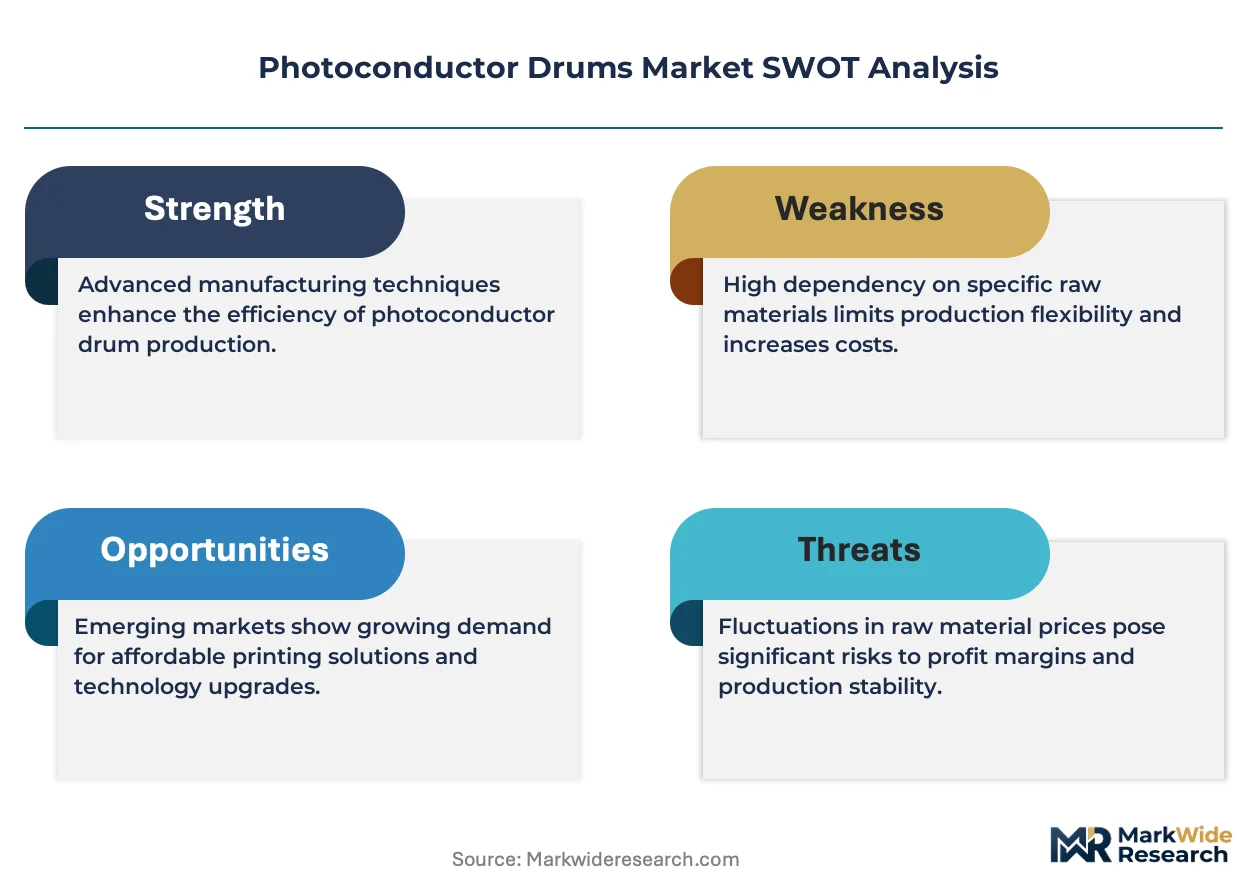
Modular drum-cartridge unbundling is compressing replacement cycle economics as printer OEMs recapture enterprise fleet revenue through proprietary consumable lock-in. This structural force is redistributing margin pools from hardware toward recurring coating formulations and direct service contracts.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated gas controls in imaging equipment manufacturing is accelerating laser-compatible photoconductor drum procurement across German commercial printing operations.
- Yangtze River Delta cluster:Domestic OEMs scaling precision coating capabilities for export markets are concentrating demand in China's industrial heartland.
- Organic photoconductive layer chemistry:Advances in charge-transport layer formulations are extending drum cycle life under high-speed LED printing conditions.
Market Restraints
- Polycarbonate resin volatility:Feedstock price swings for charge-stable substrate materials compress coating house margins during contract renewal periods.
- Charge-generation material constraints:EU REACH substance restrictions on legacy photoconductive compounds force costly reformulation cycles without performance guarantees.
- Ceramic substrate substitution:Extreme-duty industrial printing environments are piloting non-organic alternatives that bypass organic coating supply chains entirely.
Strategic Opportunities
- Industrial 3D printing integration:Hybrid additive-subtractive manufacturing workflows in precision tooling shops create demand for photoconductor drums in prototype-to-production workflows.
- Japan METI efficiency standards:Domestic energy-efficiency mandates for printer manufacturing are creating specification premiums for low-power charge-transport layer designs.
- Direct distribution bypass:Service network disintermediation through OEM-managed logistics platforms captures margin from fragmented aftermarket channels in East Asian replacement markets.
Industry Challenges
- Precision coating talent scarcity:Sub-micron layer deposition expertise concentrates in legacy Japanese and German chemical engineering programs, constraining capacity expansion.
- Multi-jurisdiction compliance timelines:Divergent GB standards under China's SAMR versus REACH substance lists force parallel certification tracks for export-oriented coating facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoconductor Drums Market |
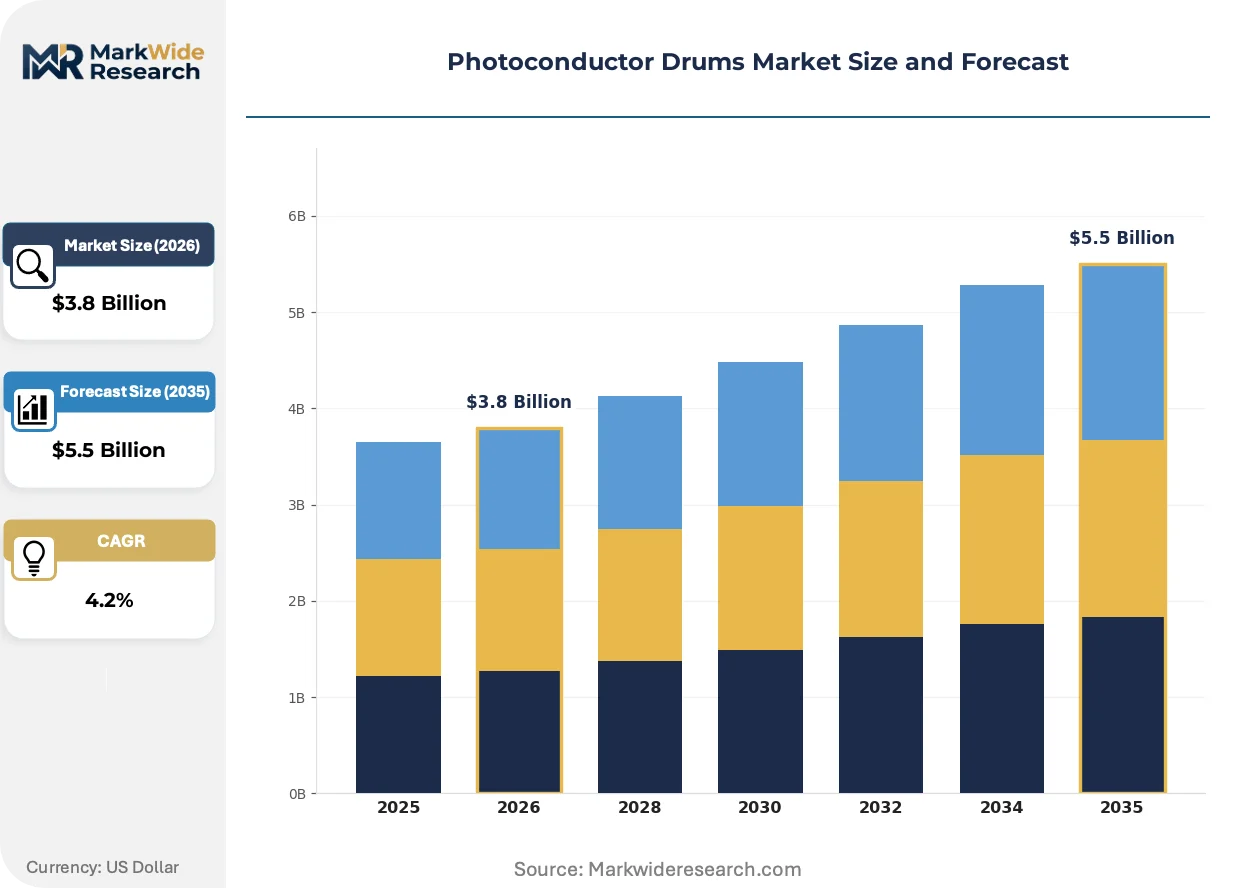
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM, Aftermarket, Multifunctional, Standard Material: Polyester, Polycarbonate, Steel, Ceramic Technology: Laser, LED, Inkjet, Thermal End User: Commercial Printing, Home Use, Industrial Printing, Educational Sector |
| Companies Covered | Mitsubishi Chemical Corporation, Fuji Electric Co., Ltd., Canon Inc., Konica Minolta, Inc., Brother Industries, Ricoh, Samsung, Suzhou Goldengreen Technologies, Xerox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoconductor Drums Market Trends and Innovations
Active coating formulation strategies are displacing passive material selection as the primary competitive variable. Drum performance differentiation now hinges on dynamic charge-transport layer engineering rather than substrate geometry alone.
Organic photoconductive chemistry is decentralizing coating production from centralized chemical conglomerates toward specialized regional formulators. Mid-scale coating houses in South Korea and Taiwan are adopting modular synthesis equipment to produce charge-generation materials in-house. This technology diffusion is compressing lead times for customized drum specifications while fragmenting intellectual property concentration.
EU REACH substance restrictions are compelling systematic reformulation of legacy charge-generation materials across photoconductive coating portfolios. ECHA's evolving candidate list is eliminating specific polycyclic aromatic compounds used in high-sensitivity layers. Coating houses serving European printer OEMs are accelerating alternative synthesis pathways, with premium OEM segments absorbing compliance costs faster than aftermarket suppliers.
Fleet management unbundling is separating drum replacement decisions from printer procurement authority. Enterprise IT departments are negotiating direct consumable contracts that bypass traditional channel distributors. This purchasing centralization is most visible in German and Japanese manufacturing conglomerates consolidating multi-site printing infrastructure under single-source service agreements.
Photoconductor Drums Market Segmentation
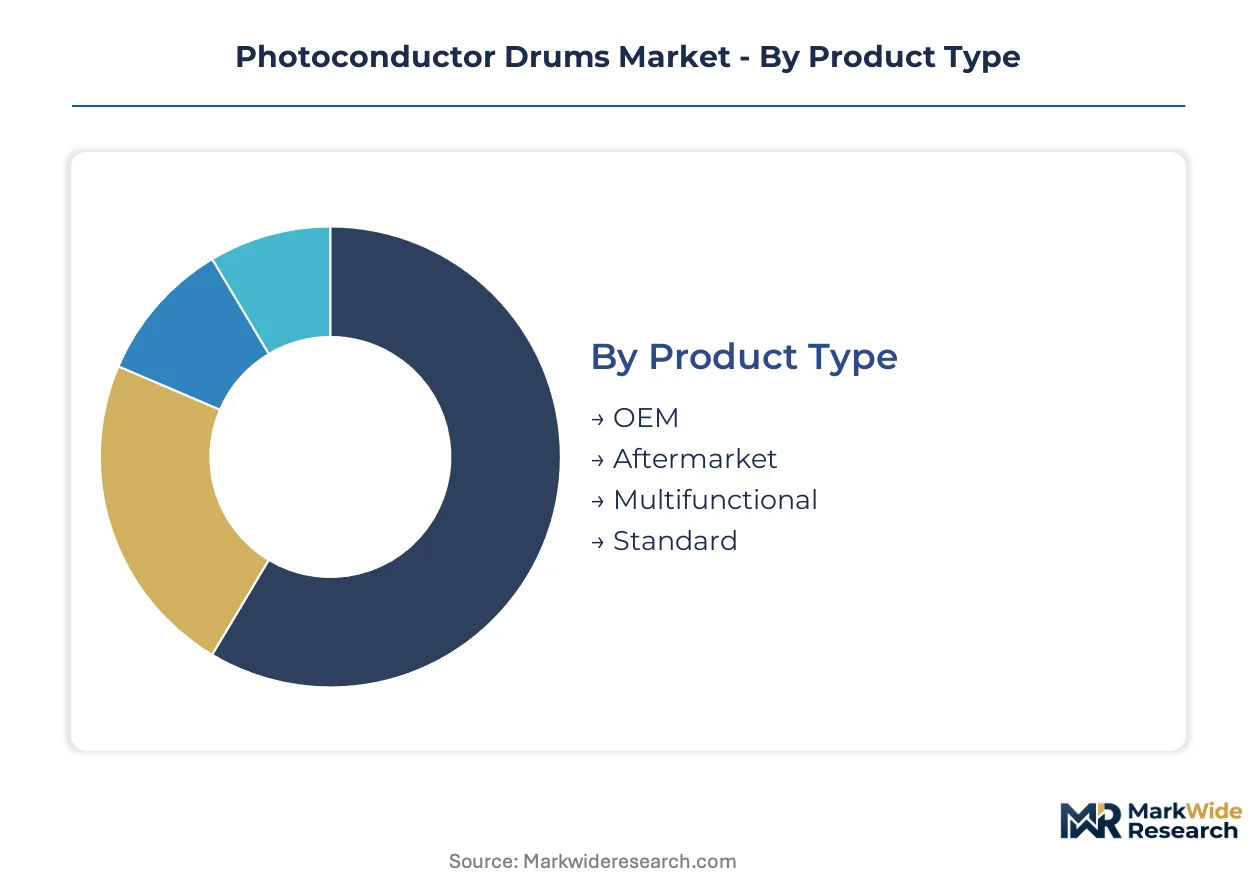
Photoconductor drum segmentation reveals how upgrade cycles, coating chemistry, and fleet management economics fragment procurement patterns across printer OEMs and aftermarket channels. Each dimension captures distinct margin pools tied to proprietary lock-in, material substitution, or service contract structures.
Product Type:
Replacement-cycle economics diverge sharply between captive OEM supply and independent aftermarket sourcing, with unbundling strategies reshaping who controls drum procurement decisions.
- OEM:Proprietary drum configurations integrate charge-transport layer formulations optimized for specific printer engine geometries. German commercial printing operations under tightening EU F-Gas Regulation procurement mandates favor OEM-locked consumables for compliance traceability.
- Aftermarket:Third-party drums compete on unit cost in mature installed bases where printer hardware deprecation cycles have concluded. China's Yangtze River Delta coating houses supply standardized substrates to fragmented service networks across East Asia.
- Multifunctional:Combined print-scan-fax devices require drums rated for higher duty cycles across mixed document workflows.
- Standard:Single-function laser printers utilize baseline drum specifications without extended-life coatings.
Volume placements concentrate in OEM configurations; the faster expansion belongs to aftermarket alternatives as enterprise fleets extend hardware refresh intervals.
Material:
Substrate selection determines charge stability under thermal cycling and directly impacts coating house margin structures through resin feedstock exposure.
- Polycarbonate:Dominant organic substrate delivering consistent charge transport across repeated imaging cycles. Mitsubishi Chemical Corporation's proprietary resin formulations anchor premium OEM supply chains serving Japanese printer manufacturers under METI efficiency mandates.
- Ceramic:Non-organic substrates eliminate REACH-regulated photoconductive compounds entirely. Extreme-duty industrial printing environments in German automotive documentation shops pilot alumina-based drums for 10-million-page lifecycle targets.
- Polyester:Lower-cost alternative for economy-tier aftermarket drums with reduced thermal tolerance specifications.
- Steel:Metallic substrates provide dimensional rigidity for high-speed LED printing systems in commercial production environments.
Polycarbonate commands the dominant revenue share; ceramic substrates are gaining share fastest among industrial end-users seeking chemical compliance simplification.
Technology:
Imaging modality dictates drum surface charge characteristics, exposure wavelength sensitivity, and the corresponding charge-generation layer chemistry.
- Laser:780-800nm wavelength exposure systems require photoconductive layers with precise spectral response curves. EU F-Gas Regulation compliance pressures are accelerating laser-compatible drum procurement across German commercial printing operations replacing solvent-based imaging systems.
- LED:Array-based solid-state exposure enables compact printer architectures with reduced mechanical complexity. South Korean printer OEMs source drums with modified charge-transport layers optimized for LED spectral output from specialized coating houses in Taiwan.
- Inkjet:Non-electrophotographic technology bypasses photoconductor drums entirely in relevant device categories.
- Thermal:Direct thermal printing systems utilize alternative imaging mechanisms without organic photoconductive coatings.
Laser technology sustains the largest installed base; LED-compatible drums are climbing the fastest as compact office equipment gains share in space-constrained Japanese and South Korean workplaces.
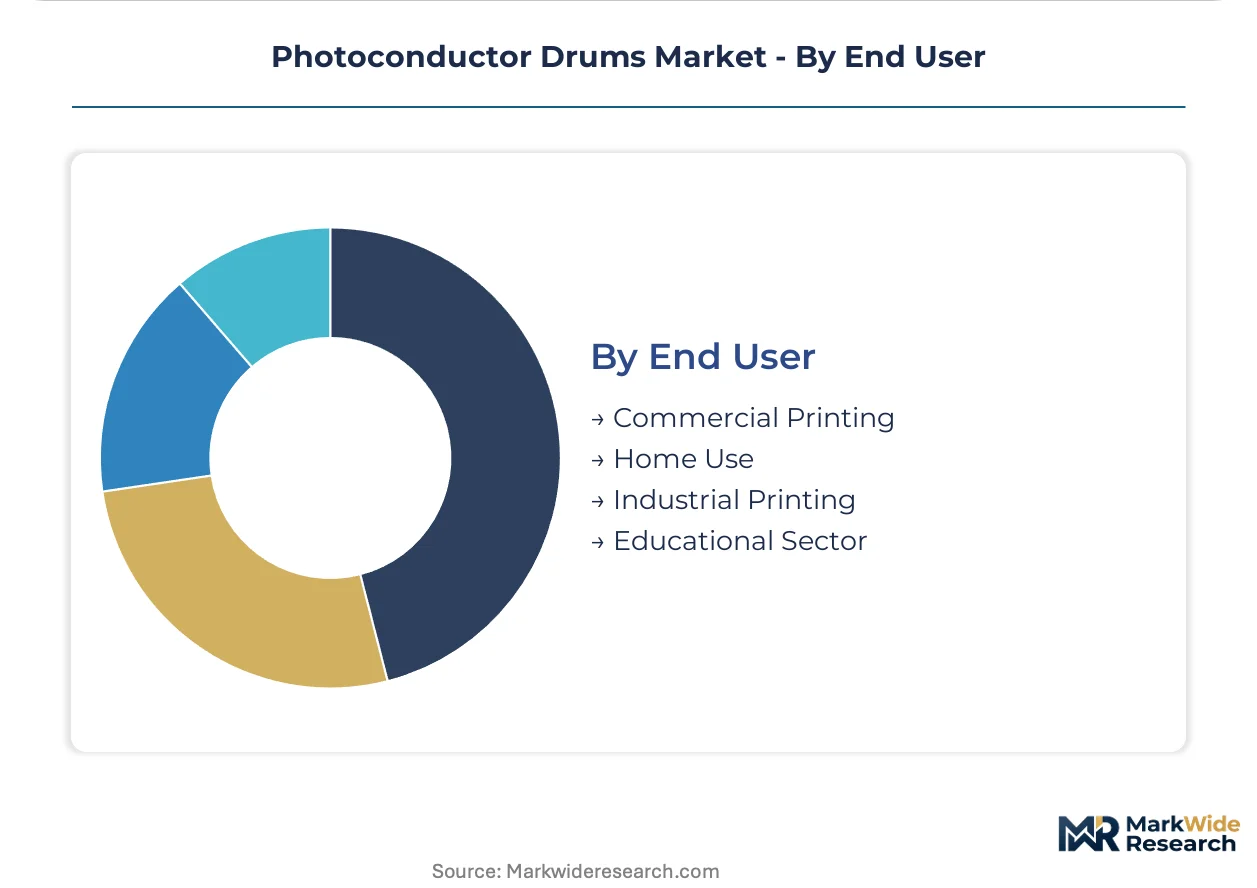
End User:
Fleet scale and document criticality determine whether drums are sourced through OEM service contracts, independent distributors, or direct procurement platforms.
- Commercial Printing:High-volume production environments demand drums with extended cycle life and consistent image density across long print runs. German commercial printing operations are expanding procurement of laser-compatible photoconductor drums as EU F-Gas Regulation tightens fluorinated gas controls.
- Industrial Printing:Extreme-duty applications in manufacturing documentation and labeling require ceramic or hardened-steel substrates. Automotive and electronics manufacturers in Japan's industrial corridors specify drums rated for continuous operation under METI-monitored energy-efficiency frameworks.
- Home Use:Low-duty-cycle printers in residential settings utilize economy-tier aftermarket drums with minimal coating sophistication.
- Educational Sector:Institutional procurement favors standardized drum specifications compatible with multi-vendor fleet management contracts.
Commercial printing generates the highest absolute drum consumption; industrial printing applications are expanding most quickly as manufacturing documentation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates precision coating capacity while Germany and China absorb the bulk of procurement volume. This production-consumption asymmetry shapes logistics networks and margin capture across the value chain.
Japan
METI energy-efficiency standards compel low-power charge-transport layer designs for domestic printer manufacturing. Kanto and Chubu industrial corridors host integrated polymer film production facilities supplying proprietary resin formulations. Fuji Electric Co., Ltd. leverages captive substrate quality control from resin to finished drum within these clusters.
Germany
Commercial printing operations expand laser-compatible drum procurement as EU F-Gas Regulation tightens fluorinated gas controls in imaging equipment. REACH substance restrictions force systematic reformulation of legacy charge-generation materials. Bavarian and Baden-Württemberg coating houses absorb compliance costs faster than aftermarket suppliers serving adjacent markets.
China
Domestic OEMs scale precision coating capabilities for export markets from the Yangtze River Delta industrial cluster. SAMR-administered GB standards govern electrophotographic equipment safety and electromagnetic compatibility. Suzhou and Shanghai coating facilities fragment intellectual property concentration through modular synthesis equipment adoption.
South Korea
Printer OEMs source modified charge-transport layers optimized for LED spectral output from specialized Taiwan-based coating houses. The country's national industrial regulator shapes domestic manufacturing specifications for compact office equipment. Seoul Capital Area electronics conglomerates consolidate multi-site printing infrastructure under single-source service agreements.
United States
Enterprise IT departments negotiate direct consumable contracts bypassing traditional channel distributors. EPA and OSHA frameworks govern chemical handling in coating operations without REACH-equivalent substance restrictions. Midwest and Southeast manufacturing documentation requirements intensify demand for extreme-duty industrial printing substrates.
Photoconductor Drums Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin pools. The vendor base stratifies into three tiers: integrated chemical conglomerates controlling substrate supply, precision coating houses with proprietary formulation expertise, and regional fabricators competing on unit cost. Consolidation pressure concentrates among mid-scale coating operations seeking scale economies. Dominant competitive moves include backward integration into polymer resin production and direct distribution platform construction.
Among Japanese chemical conglomerates, Mitsubishi Chemical Corporation anchors the premium OEM segment through proprietary charge-transport layer chemistry representation. Fuji Electric Co., Ltd. exemplifies integrated production control spanning resin to finished drum. Canon Inc. occupies a position in replacement channel logistics through direct distribution to service networks across East Asia. These three entities illustrate the archetype spectrum from materials science dominance to service network capture.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Fuji Electric Co., Ltd. |
| Canon Inc. |
| Konica Minolta, Inc. |
| Brother Industries |
| Ricoh |
| Samsung |
| Suzhou Goldengreen Technologies |
| Xerox |
| Others |
Pricing and Supply Chain Analysis
Enterprise fleet procurement consolidation in German manufacturing conglomerates drives contract-based long-term offtake pricing with volume-scaled discounts. This buyer concentration forces coating houses to absorb REACH compliance costs while competing on unit economics in standardized drum specifications.
Pricing Analysis
Margin tightening in aftermarket tiers reflects polycarbonate resin feedstock volatility compressing coating house profitability during contract renewals. Three-tier pricing structure across premium OEM, standard compatible, and economy refurbished levels segments buyers by certification grade and after-sales service bundling. Price differentiation hinges on proprietary charge-transport layer formulations versus standardized substrate geometries. OEM-locked enterprise fleets show least price sensitivity; independent service networks in China's Yangtze River Delta cluster exhibit highest cost-down pressure.
Supply Chain Analysis
Japan's METI domestic-content preferences and China's SAMR localization mandates are reshaping raw material sourcing toward regional resin production. Coating capacity concentrates in Japan, Germany, and China's Yangtze River Delta industrial corridor. Production draws from polycarbonate resin, charge-generation pigments, and precision aluminum substrates. Single-source vulnerability in Japanese polymer film supply creates exposure to Kanto corridor logistics disruptions. Distribution runs through OEM captive networks for premium tiers and fragmented independent channels for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU REACH substance restrictions erect barrier-to-entry moats favoring coating houses with accelerated reformulation capabilities and regulatory affairs infrastructure.
For Market Incumbents: Anticipate ceramic substrate substitution threats in extreme-duty industrial segments by deepening proprietary charge-transport layer chemistry differentiation. Secure backward integration into polymer resin production to buffer polycarbonate feedstock volatility. Prioritize direct distribution platform construction in East Asian replacement channels to capture margin from fragmented service networks. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for laser-compatible drum specialists with pre-certified REACH-compliant coating formulations. Target aftermarket procurement consolidation in China's Yangtze River Delta export-oriented coating facilities. Pursue white-label supply partnerships with South Korean printer OEMs seeking LED-optimized charge-transport layer alternatives. For Investors and Strategic Acquirers: The window for entry favors mid-scale coating houses with modular synthesis equipment and regional formulator positioning. Long-term viability rests on capturing recurring revenue from enterprise fleet unbundling rather than commoditized hardware attachment. Monitor divergence between ECHA candidate list expansions and SAMR GB standard harmonization as inflection signal for multi-jurisdiction compliance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Fuji Electric's captive substrate quality control from resin to finished drum insulates margin from feedstock volatility. |
| Direct Distribution Platform Construction | Canon Inc.'s service network logistics bypass captures margin pools from fragmented East Asian aftermarket channels. |
| REACH-Compliant Reformulation Acceleration | German coating houses absorbing ECHA substance restriction costs faster than aftermarket suppliers secure OEM lock-in. |
| LED-Optimized Charge-Transport Layer Development | South Korean printer OEM sourcing from Taiwan coating houses fragments intellectual property concentration. |
| Ceramic Substrate Pilot Production | German automotive documentation shops piloting alumina-based drums bypass organic coating supply chain compliance entirely. |
Research Methodology
Independent corroboration across primary interviews with coating house technical directors, printer OEM procurement leads, and aftermarket service network managers underwrites the qualitative findings. Secondary validation draws from METI efficiency standard filings, ECHA REACH candidate list updates, SAMR GB standard publications, and customs trade data for photoconductor drum substrate materials. Bottom-up demand modeling from enterprise fleet installation bases triangulates against top-down chemical industry capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, material substrate, imaging technology, and end-use vertical. CAGRs derive from regression analysis of historical procurement patterns adjusted for regulatory inflection points. Forecast inputs incorporate EU F-Gas Regulation implementation timelines, Yangtze River Delta coating capacity expansion announcements, and METI energy-efficiency mandate compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for ceramic substrate substitution in extreme-duty industrial printing would alter the outlook. Forecasts reflect assumptions about REACH substance list evolution and SAMR GB standard divergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Global 3D Imaging Market
Imaging
Global Camera Module Market
Imaging
Europe CT Market
Imaging
Machine Vision System and Services Market
Imaging
SDI Camera Market
Imaging
Pocket Video Camera Market
Imaging
Global Cell Imagers Market
Imaging
Latin America IP Camera Market
Imaging
Electron Microscopy Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Holotomographic Imaging Market
Imaging
Phosphor Screen Scanner Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Global Ingaas Camera Market