
 Voice Communication Equipment Market | 2026-2036
Voice Communication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Communication Equipment Market Analysis
Multi-source component procurement is restructuring supply relationships across the voice communication equipment sector. Motorola Solutions leverages captive semiconductor sourcing to sustain delivery reliability for public safety clients. Cisco Systems anchors enterprise market presence through deep channel partnerships with systems integrators. Hytera Communications competes aggressively on price in emerging markets while navigating component qualification hurdles.
Voice communication equipment encompasses audio transmission hardware and software systems engineered for real-time interpersonal exchange, typically operating across frequency ranges from 300 Hz to 3.4 kHz for intelligible speech reproduction with signal-to-noise ratios exceeding 25 dB. These systems serve commercial, institutional, and mission-critical applications where synchronous verbal coordination remains essential. IP-based technology segments are capturing margin pools as analog infrastructure ages out of service contracts across installed bases. Wireless deployment modes within the installation category are expanding fastest in healthcare and education end-user segments where mobility requirements override fixed-position legacy constraints.
FCC Part 15 emissions standards, EU Radio Equipment Directive 2014/53/EU, and ISO/IEC 27001 information security frameworks collectively determine market access and product certification pathways for equipment vendors. FCC testing mandates impose recurring compliance costs that favor established laboratories with accredited test ranges, while RED conformity assessment requirements in Europe compel module-level documentation that slows Asian original equipment manufacturer entry. Stakeholders must monitor spectrum reallocation proceedings in major economies and evaluate cloud-hosted migration strategies against on-premises residual demand in regulated verticals.
Market Dynamics
IP-based infrastructure migration is compressing replacement cycles across enterprise and public safety installed bases, forcing vendors to reconfigure service revenue models around software subscriptions rather than hardware refresh schedules.
Growth Catalysts
- EU Radio Equipment Directive 2014/53/EU:Module-level certification harmonization is accelerating cross-border procurement for equipment vendors serving multiple member states, reducing redundant testing expenditures.
- Healthcare mobility requirements:Wireless voice systems are displacing fixed-nurse-call infrastructure in US hospital expansion projects, creating dedicated procurement verticals for integrated communication platforms.
- Public safety narrowbanding mandates:FCC spectrum reallocation proceedings are compelling municipal agencies to accelerate equipment replacement timelines, concentrating demand in the United States.
Market Restraints
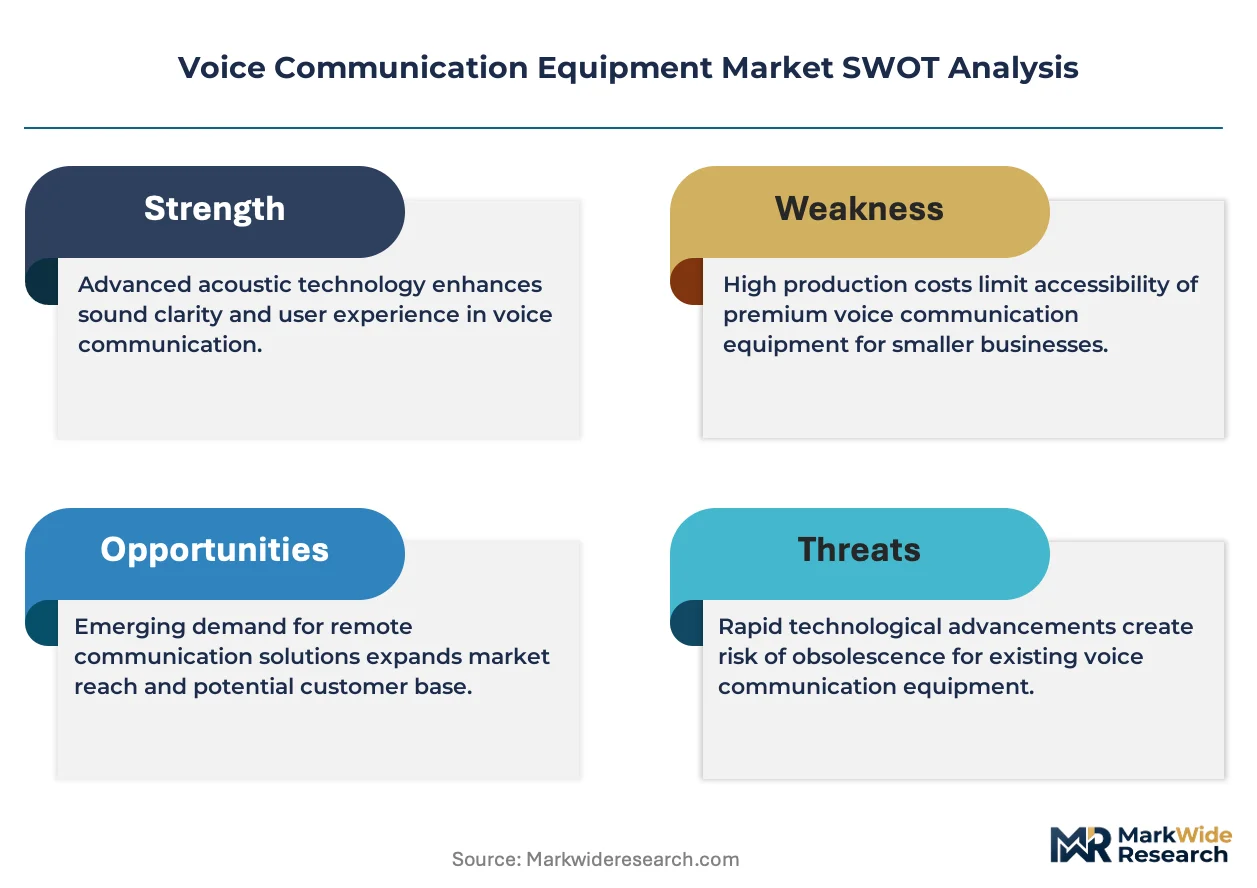
- Semiconductor supply concentration:Captive foundry capacity at Taiwanese and South Korean suppliers creates delivery volatility for codec and RF component sourcing.
- Legacy analog amortization:Extended depreciation schedules for installed base equipment in German manufacturing facilities delay IP migration decisions.
- Substitution by unified collaboration platforms:Microsoft Teams and Zoom Phone are capturing internal enterprise voice traffic, compressing addressable market for dedicated hardware endpoints.
Strategic Opportunities
- India critical infrastructure:Smart city deployments and railway modernization programs are creating first-time demand for mission-critical voice networks in underpenetrated municipalities.
- AI-noise suppression integration:Convergence of machine learning inference chips with voice processing hardware is enabling premium tiering for contact center deployments.
- Cloud-hosted dispatch:Software-as-a-service delivery models are opening public safety procurement to smaller agencies previously excluded by capital constraints.
Industry Challenges
- FCC Part 90 certification timelines:Public safety equipment approval queues at accredited laboratories extend market entry schedules by 8-14 months.
- Legacy PBX integration complexity:Hybrid deployment scenarios require specialized engineering talent scarce in systems integrator channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Communication Equipment Market |
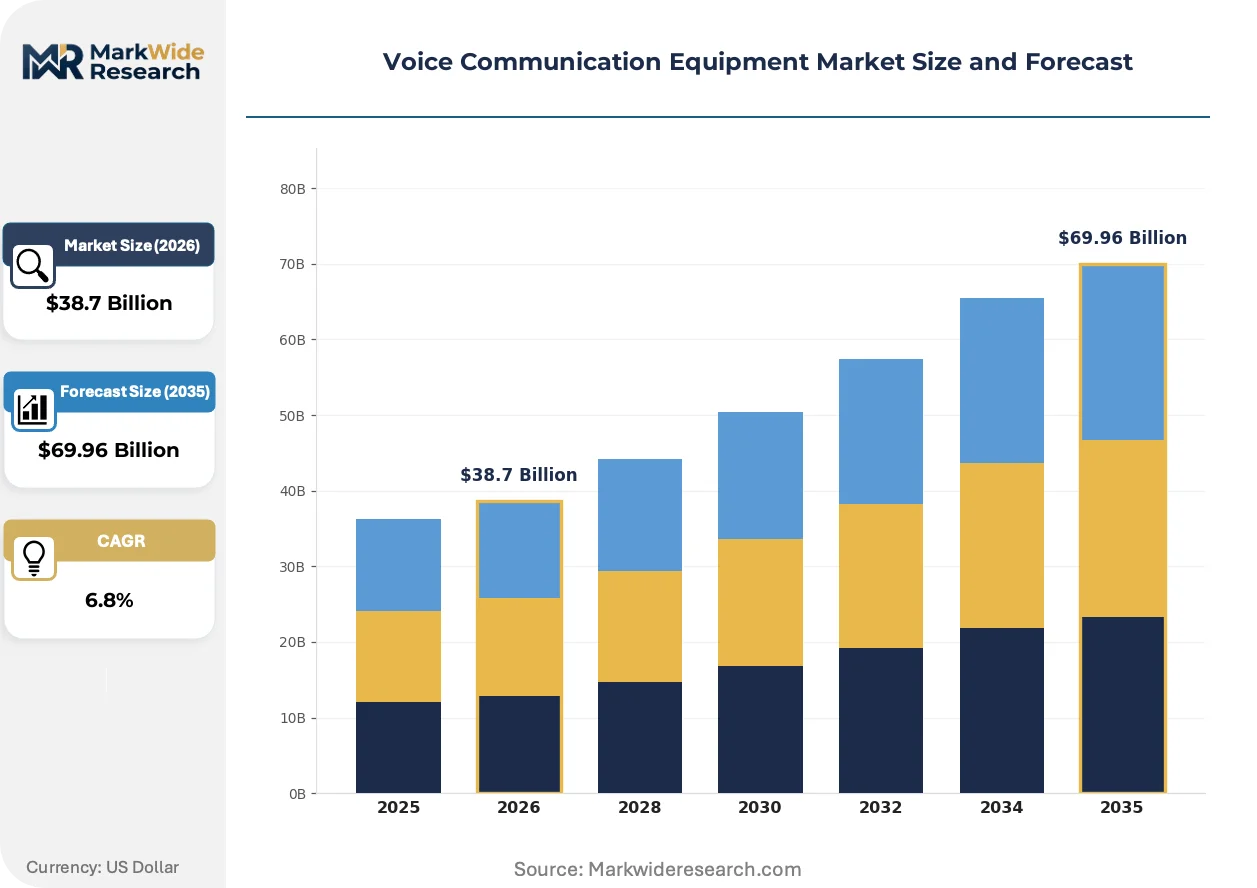
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Conferencing Devices, VoIP Phones, Intercom Systems Technology: Analog, Digital, IP-based, Wireless End User: Corporate, Education, Healthcare, Government Installation: On-premises, Cloud-hosted, Hybrid, Mobile |
| Companies Covered | Motorola Solutions, Cisco Systems, Hytera Communications, Avaya, Microsoft Corporation, L3Harris Technologies, Honeywell International, JVCKENWOOD Corporation, Frequentis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Communication Equipment Market Emerging Trajectories
Software-defined architecture is dissolving hardware-software boundaries across voice communication platforms, enabling feature delivery through firmware updates rather than physical replacement.
Software-defined radio is consolidating baseband processing functions onto general-purpose compute platforms, collapsing discrete component counts in land-mobile-radio handsets. Public safety agencies in the United States are adopting these platforms to enable over-the-air encryption key management without depot returns. The technology is consolidating vendor margins into software licensing streams, compressing hardware profitability benchmarks.
EU Cybersecurity Act certification requirements are mandating formal incident response documentation for voice equipment handling emergency services traffic. Manufacturers serving European public safety markets must demonstrate continuous vulnerability monitoring capabilities to maintain CE marking validity. German federal police procurement specifications now exclude vendors without certified security development lifecycles.
Subscription-based endpoint provisioning is displacing capital purchase models in North American healthcare systems, unbundling hardware ownership from service delivery. Hospital IT departments in the United States are contracting communication platforms as operational expenditures, transferring obsolescence risk to vendor balance sheets. This shift concentrates purchasing authority at health system headquarters, fragmenting departmental autonomy over technology selection.
Voice Communication Equipment Market Segmentation
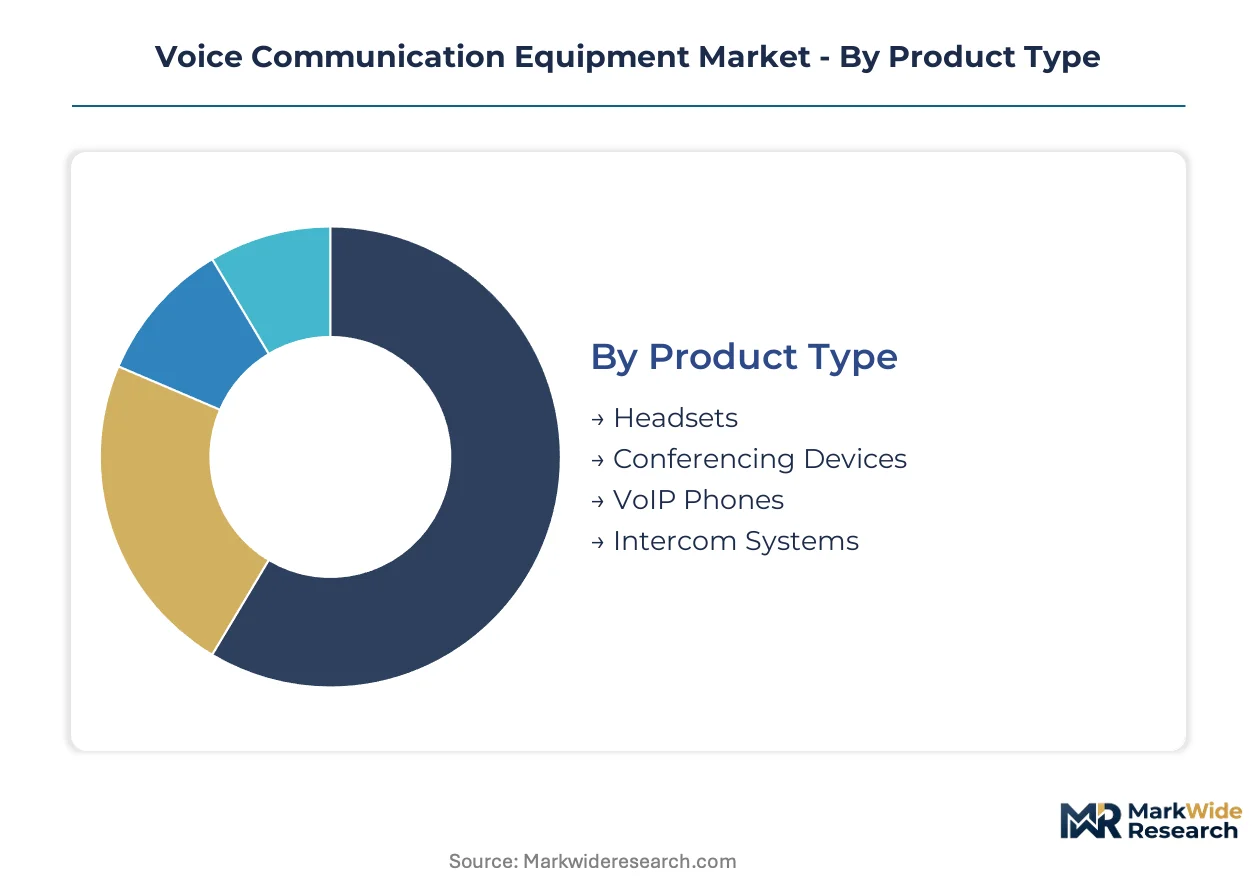
Equipment heterogeneity in voice communication markets demands granular segmentation to align procurement specifications with deployment environments. Distinct technical architectures, regulatory compliance tiers, and integration requirements fragment addressable demand across multiple orthogonal dimensions.
Product Type:
Capital intensity varies substantially across hardware categories, with conferencing devices requiring the highest upfront investment due to multi-microphone arrays, acoustic processing chipsets, and room-scale integration engineering.
- Headsets:Wearable audio terminals integrating noise-canceling microphones and 300 Hz to 3.4 kHz voice-optimized drivers. Demand concentrates in United States contact center expansions where OSHA hearing conservation guidelines drive premium over-ear specifications.
- Conferencing Devices:Multi-party audio endpoints with beamforming microphone arrays and acoustic echo cancellation processors. German enterprise procurement dominates this segment as Mittelstand manufacturers modernize meeting infrastructure to support hybrid work arrangements.
- VoIP Phones:IP-enabled desktop handsets with codec support for G.711 and G.729 compression standards. Japanese financial institutions sustain replacement cycles for these endpoints.
- Intercom Systems:Point-to-point voice terminals deployed for security and operational coordination. Indian smart city initiatives generate first-time demand for IP-intercom networks in municipal infrastructure.
Conferencing devices absorb the bulk of installed capacity; headsets are expanding most quickly as distributed workforces displace fixed-location collaboration.
Technology:
Migration timelines diverge sharply across technology generations, with legacy analog installations in German manufacturing facilities carrying depreciation schedules that delay IP conversion decisions by multiple years.
- Analog:Circuit-switched transmission systems using frequency-division multiplexing with 25 dB minimum signal-to-noise thresholds. German industrial facilities retain these systems due to extended capital amortization policies.
- Digital:TDM-based voice switching with compressed 64 kbps channels. Japanese healthcare institutions maintain digital infrastructure for compatibility with existing nurse-call integrations.
- IP-based:Packet-switched voice transport leveraging SIP signaling and RTP media streams. United States enterprise adoption accelerates as Microsoft Teams and Zoom Phone capture internal voice traffic.
- Wireless:Radio-frequency voice terminals operating across unlicensed 2.4 GHz and licensed public safety bands. Healthcare mobility requirements in US hospital expansions drive procurement for integrated wireless platforms.
IP-based technology claims the steepest expansion trajectory; analog retains residual share in regulated verticals with lengthy equipment lifecycles.
End User:
Procurement authority and budget cycles vary dramatically by institutional category, with government agencies navigating FCC Part 90 certification queues that extend delivery timelines.
- Corporate:Enterprise deployments spanning headquarters, branch offices, and remote worker endpoints. United States technology sector firms drive demand for AI-noise suppression integration in contact center environments.
- Education:Campus-wide communication systems serving administrative, classroom, and emergency notification functions. Wireless deployment modes gain share in US K-12 districts where mobility requirements override fixed-position constraints.
- Healthcare:Clinical voice systems integrating with electronic health records and nurse-call infrastructure. Subscription-based endpoint provisioning displaces capital purchases in North American health systems.
- Government:Mission-critical networks for public safety, transportation, and emergency services. FCC narrowbanding mandates concentrate United States municipal agency replacement cycles.
Corporate end users absorb the bulk of installed capacity; healthcare is climbing the fastest as operational expenditure models transfer obsolescence risk to vendors.
Installation:
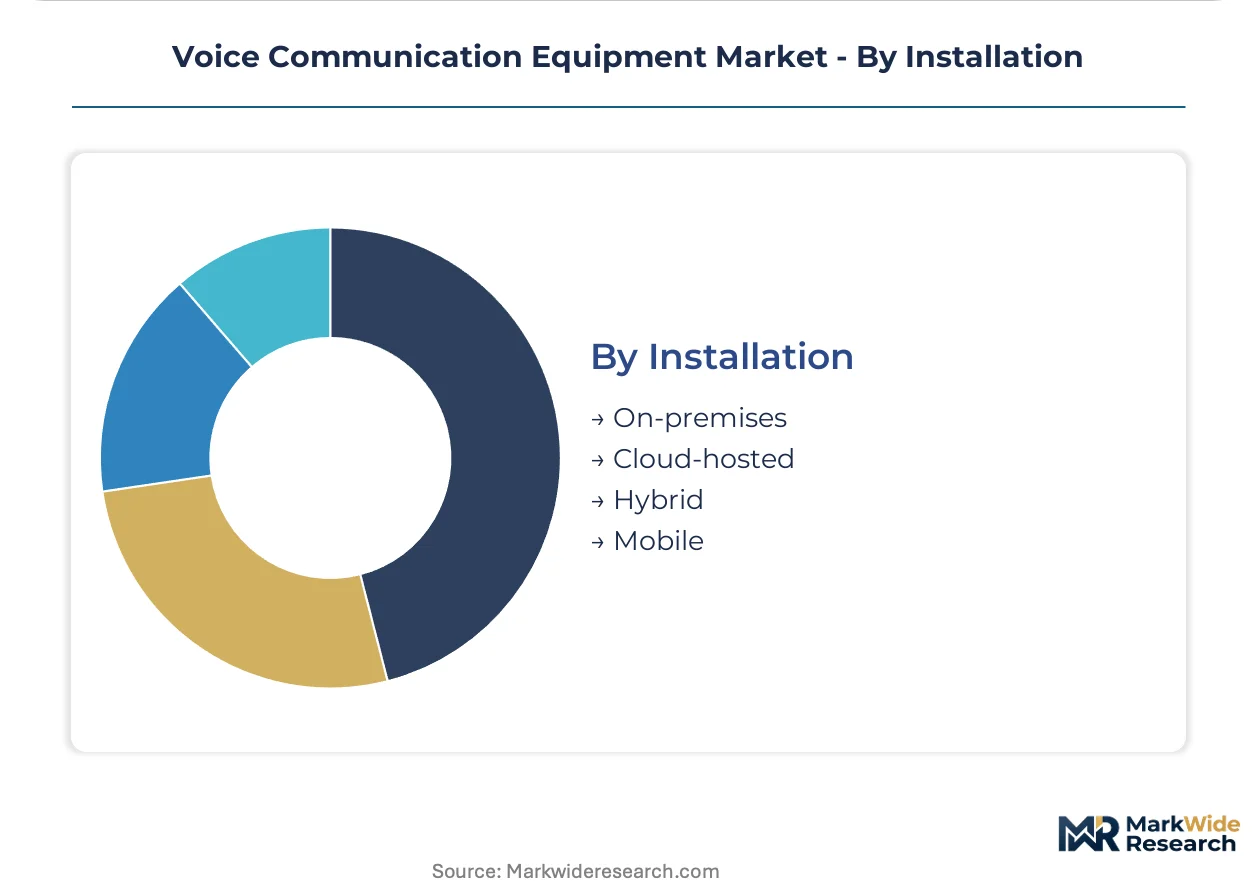
Delivery architecture determines ongoing operational control, with cloud-hosted models opening public safety procurement to smaller agencies previously excluded by capital constraints.
- On-premises:Equipment housed within customer-controlled data centers with dedicated PBX infrastructure. German federal specifications require on-premises retention for emergency services traffic.
- Cloud-hosted:Software-as-a-service delivery with vendor-managed infrastructure and over-the-air feature updates. United States healthcare systems adopt this model to convert communication platforms to operational expenditures.
- Hybrid:Mixed deployment combining legacy PBX integration with cloud trunking services. Systems integrator channels scarce engineering talent complicate these implementations.
- Mobile:Portable voice terminals operating across cellular and private radio networks. Public safety agencies in the United States adopt software-defined radio platforms for over-the-air encryption management.
On-premises installations retain the bulk of legacy capacity; cloud-hosted architectures are gaining share fastest as subscription economics restructure procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan and South Korea anchors component supply for voice communication equipment, while end-market demand concentrates in industrialized economies with aging public safety infrastructure and enterprise modernization mandates.
United States
FCC narrowbanding mandates and public safety spectrum reallocation are compressing replacement cycles for municipal land-mobile-radio systems. OSHA hearing conservation guidelines drive premium headset specifications in contact center expansions. Texas and California health systems lead adoption of subscription-based wireless voice platforms for clinical mobility.
Germany
Mittelstand manufacturers sustain conferencing device procurement as hybrid work arrangements reshape meeting infrastructure. EU Radio Equipment Directive 2014/53/EU module-level certification harmonization reduces redundant testing for vendors serving multiple member states. Bavarian industrial facilities retain analog systems due to extended capital amortization policies that delay IP migration.
Japan
Financial institutions maintain replacement cycles for VoIP desktop handsets with G.711 and G.729 codec support. METI standards frameworks influence procurement specifications for enterprise communication platforms. Tokyo and Osaka metropolitan clusters concentrate demand for integrated nurse-call digital infrastructure in healthcare institutions.
India
Smart city deployments and railway modernization programs generate first-time demand for mission-critical voice networks in underpenetrated municipalities. TRAI regulations shape spectrum allocation for private radio networks. Maharashtra and Gujarat urban clusters drive procurement for IP-intercom systems in municipal security infrastructure.
United Kingdom
Enterprise adoption of cloud-hosted collaboration platforms is displacing dedicated hardware endpoints in corporate headquarters. GDPR and emerging UK cybersecurity frameworks impose documentation requirements for voice systems handling sensitive communications. London financial services firms sustain demand for encrypted trading floor communication equipment.
Voice Communication Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors reconfigure service revenue models around software subscriptions rather than hardware refresh schedules. The market structure exhibits tiered consolidation with distinct capability clusters across mission-critical public safety, enterprise collaboration, and emerging economy price-competitive segments. Three strategic archetypes prevail: integrated platform providers with captive semiconductor sourcing, channel-anchored enterprise specialists, and cost-optimized challengers navigating component qualification hurdles. M&A activity and cloud service portfolio diversification represent the dominant competitive moves reshaping vendor positioning.
Within the integrated platform tier, Motorola Solutions and Cisco Systems exemplify divergent approaches to market presence. Motorola Solutions occupies a position anchored in public safety mission-critical networks with emphasis on delivery reliability through captive supply chain control. Cisco Systems represents the channel-partnership model for enterprise market penetration through systems integrator relationships. Hytera Communications sits within the emerging market challenger archetype, competing on price positioning while managing component sourcing complexity.
| Leading Market Players |
|---|
| Motorola Solutions |
| Cisco Systems |
| Hytera Communications |
| Avaya |
| Microsoft Corporation |
| L3Harris Technologies |
| Honeywell International |
| JVCKENWOOD Corporation |
| Frequentis AG |
| Others |
Supply Flow & Price Mechanics
Municipal public safety procurement programs in the United States anchor pricing power for mission-critical land-mobile-radio equipment, where FCC Part 90 certification requirements and extended warranty bundling sustain premium positioning against commoditized enterprise endpoints.
Pricing Analysis
Warranty and service bundling separates certified public safety tiers from standard commercial offerings, with Motorola Solutions and L3Harris commanding substantial premiums through depot-level maintenance commitments and over-the-air encryption management. Three-tier pricing structure across mission-critical, enterprise-grade, and economy levels reflects certification depth, acoustic processing capability, and integration complexity. Pricing pressure stems from Microsoft Teams and Zoom Phone capturing internal enterprise voice traffic, compressing hardware endpoint margins. Healthcare systems exhibit highest price sensitivity as subscription models convert capital expenditures to operational outlays, while public safety agencies remain least sensitive due to statutory reliability mandates.
Supply Chain Analysis
Engineering talent shortages in Taiwan and South Korean semiconductor fabrication constrain codec and RF component throughput for voice processing hardware. Taiwanese foundry capacity and South Korean memory supply anchor component sourcing, with Japanese precision acoustic components feeding final assembly. Raw material dependencies span silicon wafers, rare-earth magnets for speaker drivers, and lithium-ion cells for portable terminals. Single-source vulnerability concentrates in 2.4 GHz and sub-GHz RF transceiver supply. Distribution runs through systems integrator channels for enterprise deployments and direct government contracting for public safety verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IP-based infrastructure migration is displacing analog and digital-TDM installed bases, forcing vendors to reconfigure revenue models around software subscriptions rather than hardware refresh schedules.
For Market Incumbents: To counter Microsoft Teams and Zoom Phone capturing internal enterprise voice traffic, Motorola Solutions and Cisco Systems should deepen captive semiconductor sourcing for delivery reliability while accelerating software-defined radio firmware monetization. Certification investment in EU Cybersecurity Act frameworks and FCC Part 15 emissions standards preserves market access against Asian OEM challengers.
For New Entrants and Emerging Players: Cloud-hosted dispatch platforms offer the most penetrable entry vector for smaller public safety agencies previously excluded by capital constraints. Target Indian smart city deployments and railway modernization programs for first-time mission-critical voice network demand. Pursue channel partnerships with regional systems integrators lacking hybrid deployment engineering capacity.
For Investors and Strategic Acquirers: The window for entry favors software-defined architecture specialists with AI-noise suppression integration capabilities. Long-term viability hinges on recurring revenue conversion and over-the-air feature delivery infrastructure. Monitor FCC spectrum reallocation proceedings as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Launch | Enables over-the-air encryption management without depot returns for US public safety agencies. |
| AI-Noise Suppression Integration | Premium tiering for contact center deployments leverages machine learning inference chips with voice processing hardware. |
| Cloud-Hosted Dispatch Service | SaaS delivery opens public safety procurement to smaller municipal agencies constrained by capital limitations. |
| EU Cybersecurity Act Certification | CE marking validity for European emergency services traffic requires continuous vulnerability monitoring capabilities. |
| Backward Integration into RF Components | Captive codec sourcing insulates delivery reliability against Taiwanese and South Korean foundry volatility. |
Methodological Framework
Document review covered FCC equipment authorization databases, EU Radio Equipment Directive conformity assessment records, and public safety procurement disclosures, complemented by interviews with Motorola Solutions and Cisco Systems channel partners, systems integrator engineering directors, hospital IT procurement managers, and municipal radio communications officers. Secondary validation drew from SEC 10-K filings, OSHA hearing conservation guideline updates, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up segment sizing and top-down macroeconomic reconciliation ensured cross-verification.
Market size outputs reflect equipment shipment analysis across hardware categories and technology generations, segmented by product type, deployment architecture, end-user vertical, and geographic adoption cluster. The analytical framework modeled IP migration velocity, wireless penetration in healthcare mobility applications, and public safety narrowbanding replacement cycles across the projection horizon. CAGRs were derived from regression analysis against historical equipment refresh patterns and regulatory mandate timelines.
The model holds under stable spectrum allocation and certification processing capacity; deviation in FCC reallocation acceleration or EU Cybersecurity Act enforcement stringency would shift replacement cycle assumptions. Forecasts reflect documented procurement patterns and vendor revenue disclosures. Material deviation in semiconductor supply availability or unified collaboration platform substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Base Station Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Infiniband Market