
 Plenoptic Camera Market | 2026-2036
Plenoptic Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Plenoptic Camera Market Outlook
Asset-light leasing models for high-end light-field equipment is fragmenting competitive access across the plenoptic camera landscape. Canon Inc leverages its optical manufacturing scale to sustain cost advantages in professional-grade hardware. Sony Corporation anchors its position through sensor fabrication dominance, while Intel RealSense competes by integrating depth-perception software with modular camera platforms.
A plenoptic camera captures light-field data through an array of microlenses placed before the image sensor, enabling computational refocusing and depth mapping from a single exposure. This architecture serves industrial inspection, autonomous navigation, and volumetric content creation where post-capture focal adjustment eliminates reshoot costs. Industrial cameras command the steepest price premiums due to sub-micron measurement tolerances in semiconductor and automotive quality control. Computational technology segments expand fastest as GPU-accelerated rendering pipelines reduce hardware dependency, while consumer cameras remain nascent outside specialist photography circles.
FCC equipment authorization requirements constrain radio-enabled plenoptic modules in the US, while CE marking under the EU MDR elevates validation burdens for medical camera deployments in Europe. Japan's METI standards for optical instrument precision further shape export compliance for manufacturers targeting East Asian industrial buyers. Stakeholders must track whether computational imaging advances trigger reclassification of light-field devices under emerging AI hardware regulations before committing to regional manufacturing footprints.
Market Dynamics
Computational refocusing algorithms are virtualizing optical hardware functions, compressing the traditional premium attached to physical lens arrays while enabling software-defined imaging pipelines across industrial and medical deployments.
Growth Catalysts
- EU MDR CE marking pathways:Streamlined validation for post-capture focus adjustment in diagnostic imaging accelerates hospital procurement cycles for light-field surgical cameras.
- GPU-accelerated rendering pipelines:Real-time depth map generation from single exposures eliminates dedicated processing hardware, lowering entry barriers for metrology system integrators.
- German precision engineering clusters:Concentrated demand from automotive semiconductor inspection creates captive testbeds for sub-micron measurement tolerances.
Market Restraints
- Microlens array fabrication:Sub-wavelength etching precision requires specialized foundry capacity concentrated in East Asian optical component suppliers, creating single-source vulnerabilities.
- FCC equipment authorization:Radio-enabled plenoptic modules face 12-18 month approval timelines for wireless data transmission in US industrial deployments.
- Conventional stereoscopic systems:Mature depth-perception hardware at 40-60% lower unit cost displaces light-field alternatives in cost-sensitive autonomous navigation trials.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor packaging create localized assembly opportunities for industrial camera modules.
- Volumetric content creation for surgical training:Light-field capture of operative procedures enables haptic-integrated simulation platforms for medical education institutions.
- Convergence of neuromorphic sensors with light-field architectures:Event-based readout combined with microlens arrays promises 1000x reduction in data bandwidth for mobile robotics.
Industry Challenges
- Computational imaging specialist scarcity:Cross-disciplinary expertise spanning optics, GPU programming, and inverse problem mathematics commands 40% wage premiums above conventional machine vision engineers.
- Legacy metrology system integration:Retrofitting light-field cameras into existing semiconductor inspection lines requires custom calibration protocols that extend deployment timelines by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plenoptic Camera Market |
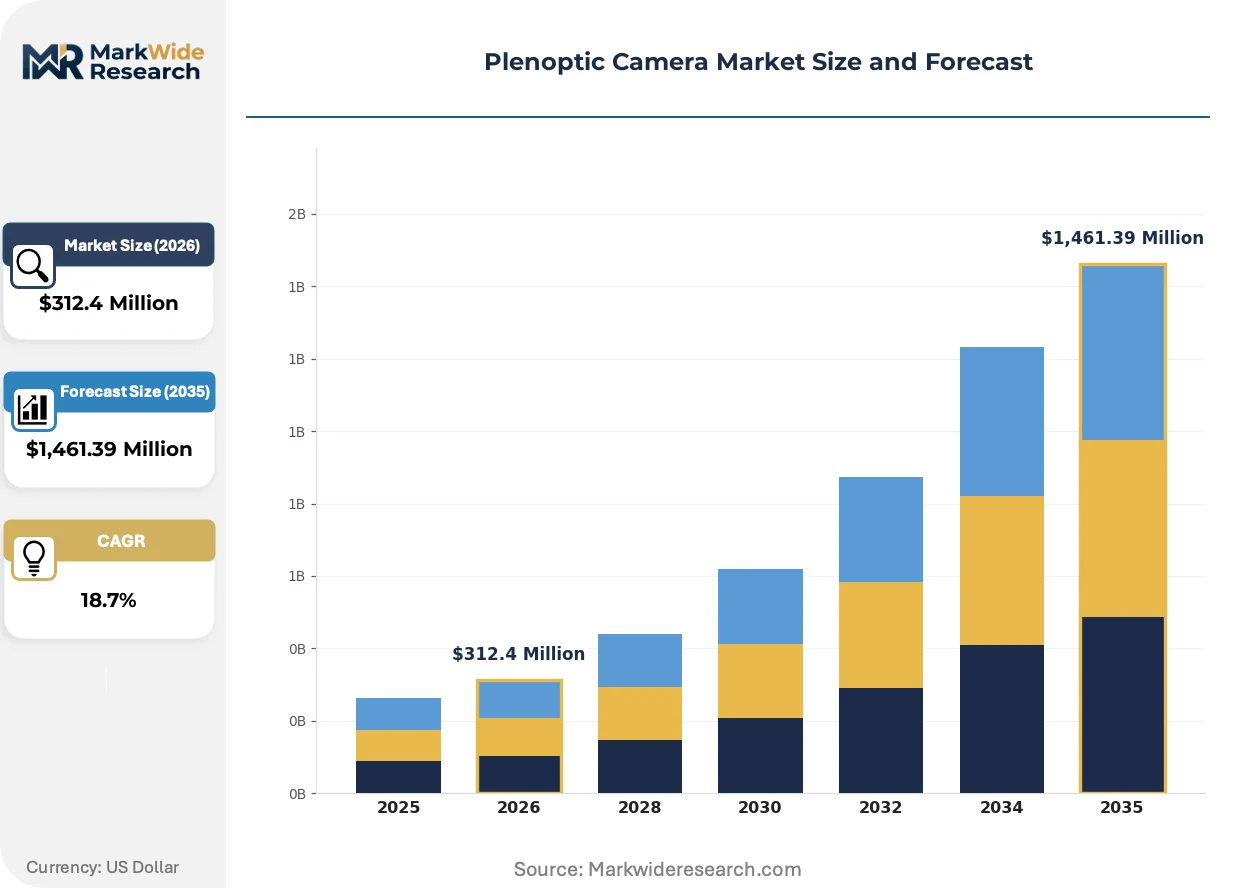
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Cameras, Industrial Cameras, Scientific Cameras, Medical Cameras Technology: Digital, Analog, Hybrid, Computational Application: Photography, Surveillance, Research, Aerospace End User: Professional Photographers, Hobbyists, Researchers, Healthcare Providers |
| Companies Covered | Raytrix GmbH, Lytro, Pelican Imaging Corp, Canon Inc, Panasonic Corporation, Sony Corporation, Intel RealSense, Axiom Optics, OTOY Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plenoptic Camera Market Strategic Shifts
Software-defined imaging architectures are dissolving the historical boundary between optical hardware and computational processing, enabling function migration from glass to algorithms.
Sub-aperture image fusion is virtualizing depth extraction that previously required multi-camera rigs or structured light projectors. Industrial automation integrators in Bavaria and Michigan are deploying single-plenoptic systems for robotic bin-picking at throughput rates matching conventional stereo setups. This compression of hardware count is collapsing the bill-of-materials gap between light-field and legacy 3D vision systems.
Japan's METI precision standards for optical instruments are mandating traceable calibration certificates for export-bound industrial cameras, effective for shipments after Q3 2025. German and Swiss metrology equipment suppliers are pre-certifying light-field modules to maintain access to Japanese automotive OEM qualification programs. The compliance burden favors established sensor manufacturers with captive calibration laboratories over modular camera assemblers.
Asset-light leasing models for high-end light-field equipment are displacing capital purchase patterns in North American research institutions. University imaging core facilities and contract research organizations now access sub-micron measurement capabilities through 24-36 month operational expenditure contracts rather than depreciation-heavy acquisitions. This preference shift concentrates demand among lessors with integrated field service capabilities.
Plenoptic Camera Market Segmentation
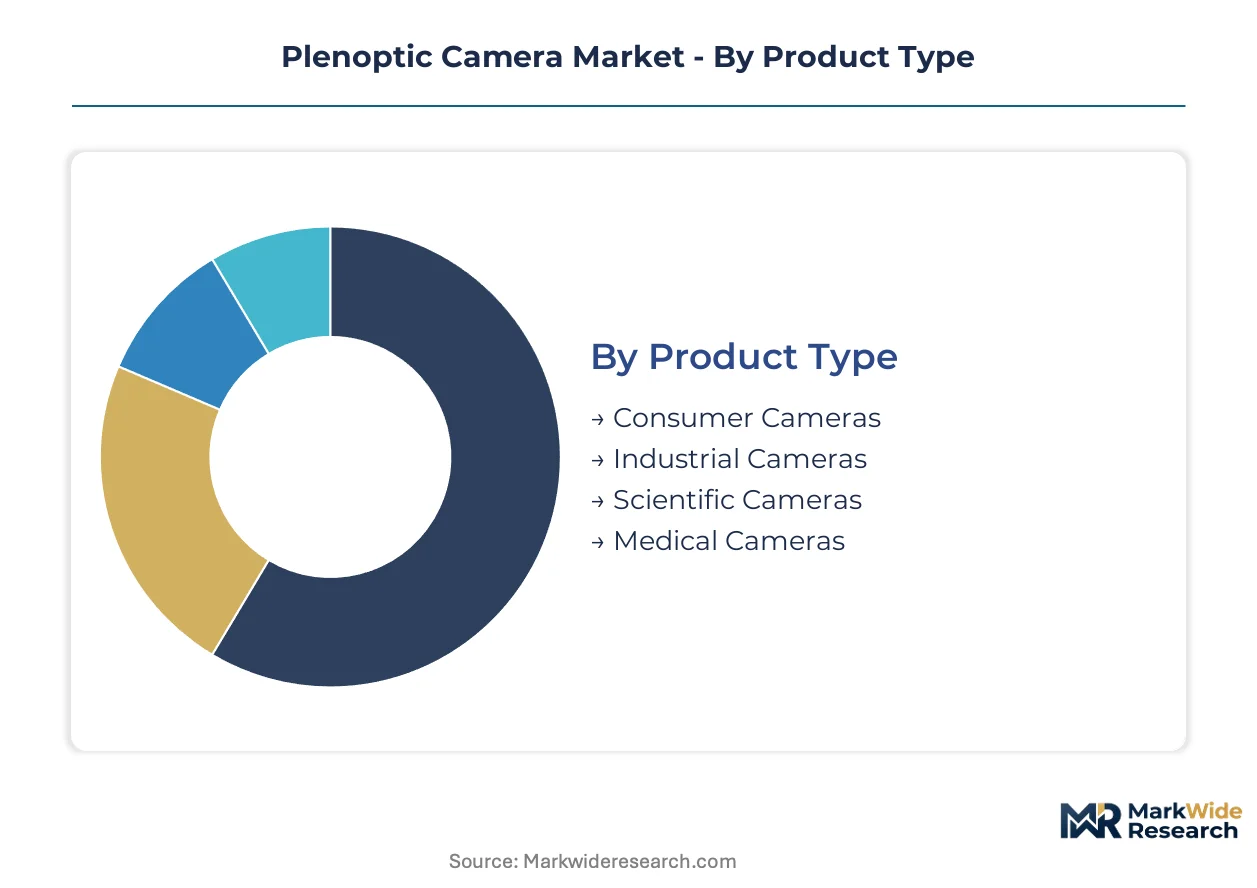
Plenoptic camera segmentation reveals how computational imaging value migrates across hardware tiers and use cases. Product architecture, underlying technology, and end-user sophistication create distinct competitive arenas with diverging margin structures and procurement cycles.
Product Type:
Cost tier determines the balance between specialized optical hardware and software-defined functionality across deployment contexts.
- Industrial Cameras:Sub-micron measurement tolerances demand precision microlens arrays and thermally stabilized sensor housings. German automotive semiconductor inspection lines in Bavaria generate concentrated demand for factory-calibrated units with traceable certification chains.
- Medical Cameras:Surgical light-field systems enable post-capture focus adjustment for diagnostic precision, with EU MDR CE marking pathways streamlining hospital procurement cycles for compliant devices.
- Scientific Cameras:Laboratory-grade units prioritize quantum efficiency and raw data fidelity for academic research institutions.
- Consumer Cameras:Enthusiast photography segments remain nascent outside specialist circles due to premium pricing versus conventional mirrorless alternatives.
Industrial cameras hold installed capacity. Medical cameras are rotating up the share rankings.
Technology:
Application requirements dictate the trade-off between physical optical complexity and computational processing overhead.
- Computational:GPU-accelerated rendering pipelines eliminate dedicated processing hardware, lowering entry barriers for metrology system integrators deploying software-defined depth extraction.
- Digital:Standard CMOS sensor architectures with microlens overlays dominate volume manufacturing through foundry-scale compatibility.
- Hybrid:Combined optical-digital approaches bridge legacy inspection infrastructure with modern algorithmic capabilities.
- Analog:Specialized film-based light-field capture persists in archival and artistic documentation niches.
Computational platforms command the steepest expansion trajectory. Digital architectures anchor current shipment volumes.
Application:
Customer type shapes whether plenoptic capabilities replace existing depth-perception stacks or enable entirely new imaging workflows.
- Surveillance:Post-capture refocusing reduces camera count in perimeter monitoring installations, with depth-map extraction enabling automated threat classification without multi-sensor fusion.
- Research:Academic laboratories leverage light-field microscopy for volumetric biological specimen capture without mechanical focusing stages.
- Photography:Commercial studios adopt plenoptic systems for product visualization where iterative focus adjustment accelerates client approval cycles.
- Aerospace:Satellite and drone payloads utilize light-field sensors for terrain mapping through turbulent atmospheric conditions.
Surveillance applications concentrate near-term deployment velocity. Research installations build longer-term platform loyalty.
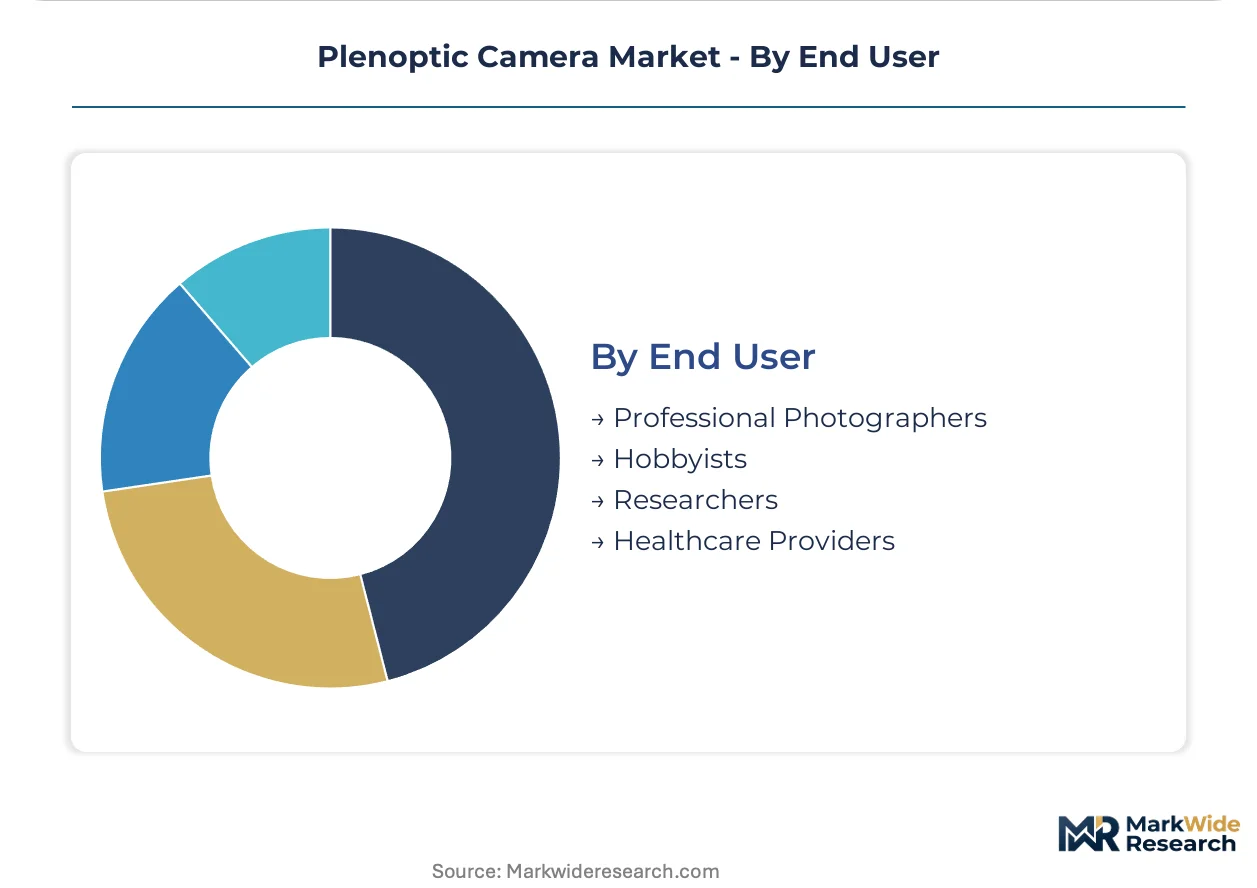
End User:
Volume concentration varies dramatically between capital-intensive institutional procurement and discretionary individual purchasing.
- Healthcare Providers:Hospital imaging departments and surgical centers prioritize regulatory-validated systems with integrated field service support over acquisition cost minimization.
- Researchers:University core facilities and national laboratories drive demand for open-architecture platforms with raw data access and custom calibration protocols.
- Professional Photographers:Commercial studios evaluate plenoptic systems against established medium-format workflows on total cost-of-ownership metrics including post-processing time.
- Hobbyists:Enthusiast segments remain price-sensitive, with adoption constrained by software complexity and limited retail channel presence.
Healthcare providers dominate revenue per unit. Researchers expand the addressable base through technology demonstration effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for electronics manufacturing are reshaping regional competitive positioning across the plenoptic camera landscape. Germany's precision engineering clusters anchor European industrial demand, while Asia-Pacific foundry capacity concentrates microlens array supply. Regulatory divergence between FCC equipment authorization in the United States and EU MDR CE marking pathways is fragmenting go-to-market strategies.
United States
Autonomous navigation trials and aerospace terrain mapping drive institutional procurement of light-field sensors. FCC equipment authorization imposes 12-18 month approval timelines for radio-enabled plenoptic modules in industrial deployments. Research institutions in Greater Boston and the Pacific Northwest are adopting asset-light leasing models for sub-micron measurement capabilities.
Germany
Automotive semiconductor inspection lines in Bavaria generate concentrated demand for factory-calibrated industrial cameras with traceable certification chains. EU MDR CE marking pathways streamline hospital procurement cycles for surgical light-field systems. Raytrix GmbH anchors industrial metrology applications in precision engineering clusters across Baden-Württemberg and North Rhine-Westphalia.
China
MIIT standards for optical instrument precision shape export compliance requirements for industrial camera manufacturers. Sub-wavelength etching foundry capacity concentrates in East Asian optical component suppliers, creating single-source vulnerabilities for microlens arrays. Yangtze River Delta packaging facilities are expanding assembly capacity for computational imaging modules.
Japan
METI precision standards mandate traceable calibration certificates for export-bound industrial cameras effective Q3 2025. Japanese automotive OEM qualification programs are pre-certifying light-field modules from German and Swiss metrology equipment suppliers. Kanto region sensor manufacturers maintain captive calibration laboratories to satisfy compliance burdens.
India
The PLI scheme for electronics manufacturing creates localized assembly opportunities for industrial camera modules in semiconductor packaging facilities. CDSCO regulatory pathways for diagnostic imaging equipment are streamlining hospital procurement for medical-grade plenoptic systems. Karnataka and Tamil Nadu research institutions are deploying GPU-accelerated rendering pipelines for metrology applications.
Plenoptic Camera Market Competitive Environment
On the supply side, the industry is consolidating around sensor fabrication scale and optical manufacturing heritage. Three strategic archetypes dominate: diversified electronics conglomerates with captive sensor foundries, specialized industrial metrology equipment suppliers, and modular depth-perception platform providers. Competitive moves center on backward integration into microlens array fabrication and strategic partnerships with GPU-accelerated rendering software developers.
Within the diversified electronics tier, Canon Inc and Sony Corporation exemplify scale-driven positioning through optical manufacturing and sensor fabrication dominance respectively. Raytrix GmbH occupies a specialist position in industrial metrology applications. Intel RealSense represents the modular platform archetype, integrating depth-perception software with camera hardware for system integrators.
| Leading Market Players |
|---|
| Raytrix GmbH |
| Lytro |
| Pelican Imaging Corp |
| Canon Inc |
| Panasonic Corporation |
| Sony Corporation |
| Intel RealSense |
| Axiom Optics |
| OTOY Inc |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in sub-wavelength etching foundries across East Asia tightens microlens array availability, compressing margins for modular camera assemblers while amplifying pricing power for integrated sensor manufacturers with captive optical fabrication.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between industrial tiers. Three-tier pricing structure across medical-grade, industrial-calibrated, and research-laboratory levels separates hospital-validated systems from factory-floor units. Cost compression in research-laboratory tiers intensifies because GPU-accelerated rendering pipelines reduce hardware dependency. Healthcare providers demonstrate lowest price sensitivity due to regulatory validation requirements, while academic institutions negotiate aggressively on total cost-of-ownership metrics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for radio-enabled plenoptic modules. Microlens array fabrication concentrates in Taiwan, South Korea, and Japan, drawing from specialized photoresist chemicals, precision glass substrates, and deep-UV lithography equipment. Single-source vulnerability persists for sub-wavelength etching capacity. Distribution runs through direct OEM relationships for industrial volumes and imaging core facility lessors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as software-defined imaging architectures dissolve traditional hardware boundaries, creating niches for specialized computational imaging boutiques alongside integrated sensor conglomerates.
For Market Incumbents: Insulate factory-calibrated industrial camera margins through backward integration into microlens array fabrication, neutralizing single-source vulnerabilities from East Asian optical component suppliers. Deepen captive calibration laboratory networks to satisfy Japan's METI precision standards and pre-empt regulatory reclassification risks from emerging AI hardware regulations. For New Entrants and Emerging Players: Establish a beachhead in volumetric content creation for surgical training, where light-field capture of operative procedures enables haptic-integrated simulation platforms with minimal incumbent presence. Target India's PLI scheme for electronics manufacturing to access localized assembly subsidies and CDSCO-streamlined hospital procurement pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among asset-light lessors with integrated field service capabilities serving North American research institutions. Long-term viability centers on computational imaging specialist teams commanding wage premiums above conventional machine vision engineers. Watch for neuromorphic sensor convergence with light-field architectures as inflection signal for next-generation mobile robotics applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microlens Fabrication | Captive sub-wavelength etching capacity neutralizes East Asian single-source dependency for industrial camera manufacturers. |
| GPU-Accelerated Rendering Pipeline Partnership | Software-defined depth extraction lowers entry barriers for metrology system integrators deploying computational platforms. |
| EU MDR CE Marking Pre-Certification | Streamlined validation accelerates hospital procurement cycles for surgical light-field systems in German precision engineering clusters. |
| Asset-Light Leasing Model Expansion | Operational expenditure contracts concentrate demand among lessors serving university imaging core facilities and contract research organizations. |
| Neuromorphic Sensor Architecture Convergence | Event-based readout combined with microlens arrays promises radical data bandwidth reduction for mobile robotics applications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with computational imaging specialists, GPU programming engineers, hospital procurement managers, and industrial metrology system integrators; and secondary validation through SEC filings from sensor manufacturers, EU MDR device registration databases, FCC equipment authorization records, and trade customs data for optical component flows. Bottom-up segment sizing triangulated against top-down market reconstructions.
Forecast inputs considered product type tiering, technology architecture, application workflow, and end-user procurement pattern across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro technology adoption curves. Industry-specific inputs included GPU compute cost decline trajectories and regulatory validation timeline assumptions for medical device classifications.
Sensitivities concentrate around computational imaging algorithm maturation timelines and potential reclassification of light-field devices under emerging AI hardware regulations. Forecasts reflect documented assumptions subject to revision from foundry capacity constraints or trade policy shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Side View Camera System Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Uncooled Thermal Imaging Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Fiducial Markers Market
Imaging
Low-Light Imaging Market
Imaging
Holographic Imaging Market
Imaging
Digitizer Market
Imaging
Digital Microscope Market
Imaging
Hybrid Imaging Systems Market
Imaging
360-Degree Camera Market
Imaging
Global Digital Photography Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Handheld Thermal Imaging Equipment Market