
 Global 3D Imaging Market | 2026-2036
Global 3D Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Imaging Market Foresight
EU MDR is broadening the cost-of-entry calculus for 3D imaging device manufacturers seeking European market access. GE Healthcare leverages its installed base of diagnostic hardware to sustain service revenue streams across hospital networks. Siemens Healthineers anchors its competitive position through deep R&D integration in photon-counting CT technology. Autodesk differentiates by controlling software workflows that bridge capture hardware and downstream engineering applications.
3D imaging encompasses volumetric data acquisition systems that reconstruct spatial coordinates from multiple sensor inputs, typically achieving sub-millimeter resolution through laser triangulation, time-of-flight, or structured light modulation. The technology serves industrial metrology, medical diagnostics, and spatial computing by converting physical geometries into manipulable digital models. CT scanners and MRI systems dominate medical revenue pools where capital replacement cycles and software upgrade paths sustain margin concentration. LiDAR sensors represent the fastest-expanding hardware category as automotive and mobile mapping applications scale manufacturing volumes. Structured light scanners occupy a specialized niche in heritage preservation and forensic documentation where portability and color fidelity command premium pricing.
FDA premarket notification requirements and EU MDR conformity assessment procedures shape product development timelines and clinical validation burdens for device manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety frameworks govern cross-border commercialization pathways. Japan's PMDA operates parallel review tracks that reward prior FDA or EMA clearance with accelerated domestic approval. Stakeholders must monitor evolving cybersecurity guidance from FDA and harmonization progress between MDR and international regulator work-sharing agreements to anticipate compliance cost trajectories.
Market Dynamics
Photon-counting CT detectors are compressing scan times and radiation exposure thresholds, forcing incumbent manufacturers to accelerate R&D timelines or cede hospital procurement cycles to early movers with validated clinical pipelines.
Growth Catalysts
- EU MDR Article 10 technical documentation:Stringent clinical evaluation requirements for Class IIa and above devices are consolidating vendor pools, advantaging established manufacturers with in-house regulatory affairs capacity.
- Automotive LiDAR integration:Tier-1 suppliers in Germany and Japan are qualifying solid-state sensors for Level 3+ autonomous platforms, absorbing capacity from industrial metrology lines.
- Digital twin infrastructure:Aerospace and precision manufacturing clusters in the United States are mandating volumetric inspection data for supplier qualification, embedding 3D imaging into quality assurance workflows.
Market Restraints
- Rare earth magnet supply concentration:MRI system manufacturers face input cost volatility from Chinese export quotas on neodymium and dysprosium, with limited near-term substitution pathways.
- EU MDR notified body capacity:Conformity assessment bottlenecks at designated bodies in Germany and the Netherlands are extending time-to-market for novel 3D diagnostic hardware by 12-18 months.
- Structured light resolution ceiling:Sub-surface feature detection remains beyond optical triangulation limits, restricting forensic and heritage applications to surface-bound geometries.
Strategic Opportunities
- India CDSCO accelerated approval:Parallel track recognition for prior FDA-cleared CT and MRI devices is compressing regulatory timelines for manufacturers with existing 510(k) portfolios.
- AI-assisted reconstruction software:Deep learning denoising algorithms are converging with photon-counting hardware, enabling diagnostic-quality imaging at reduced radiation doses for pediatric applications.
- Direct-to-clinic leasing models:Mobile CT providers in rural United States markets are bypassing traditional distributor networks, capturing outpatient imaging volumes outside hospital capital budgets.
Industry Challenges
- Cross-functional talent scarcity:Computational imaging specialists with simultaneous expertise in hardware physics and FDA premarket submission protocols command premium compensation, constraining mid-tier vendor expansion.
- Legacy PACS integration friction:Hospital IT departments face technical debt from decades-old DICOM infrastructure, complicating deployment of cloud-native 3D visualization platforms.
- ISO 13485 audit backlogs:Certification body scheduling delays are postponing quality management system renewals, freezing supplier qualification for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Imaging Market |
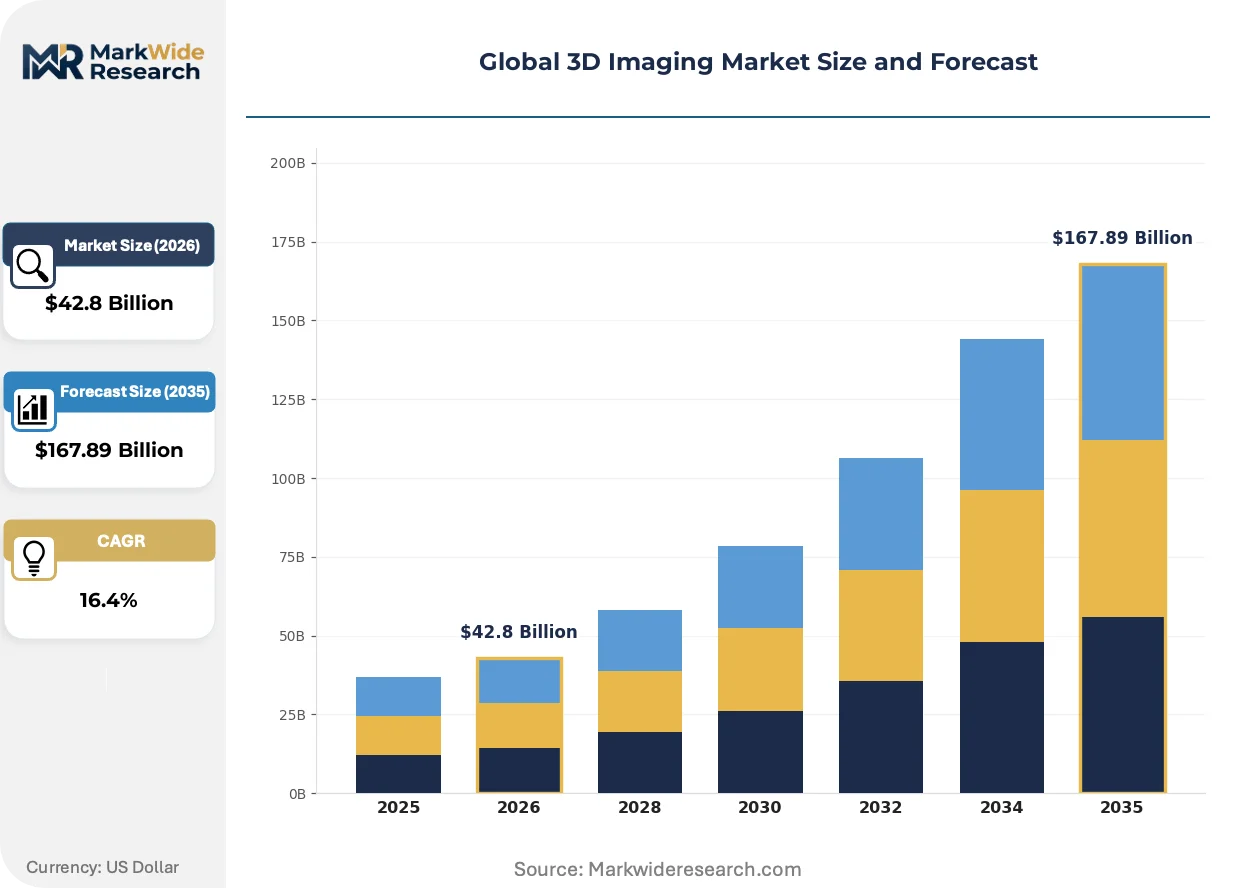
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $167.89 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, Ultrasound Devices, LiDAR Sensors, Structured Light Scanners Technology: Laser Triangulation, Time-of-Flight, Photogrammetry, Stereovision, Confocal Microscopy Application: Quality Control, Virtual Reality, Heritage Preservation, Topographic Mapping, Forensics End User: Manufacturing Facilities, Research Laboratories, Archaeological Institutes, Entertainment Studios, Law Enforcement Agencies |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Autodesk, FARO, Trimble, STMicroelectronics, Canon, 3D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Imaging Market Shifts & Advancements
Computational reconstruction methods are displacing hardware-centric performance differentiation, compressing the value capture window for pure equipment vendors while extending margins for software-integrated platform providers.
Photon-counting detector arrays are absorbing the functional role of dual-energy CT systems in material decomposition tasks. Siemens Healthineers and GE Healthcare are deploying these sensors across premium scanner tiers in the United States and Germany. The technology is absorbing service revenue from contrast-agent suppliers by reducing iodine dosage requirements.
EU MDR Article 117 software classification rules are redefining borderline determinations for AI-enabled diagnostic tools. Manufacturers must now submit clinical evidence for algorithm-assisted reconstruction modules previously treated as accessories. Radiology departments in France and Italy are delaying procurement cycles pending clarity on notified body jurisdiction.
Subscription-based access models are displacing capital purchase structures for mid-tier CT installations. Independent imaging centers in Texas and Florida are adopting per-scan pricing from equipment lessors, transferring utilization risk to vendors. Hospital procurement committees in Japan are piloting equivalent arrangements for MRI upgrade pathways.
Global 3D Imaging Market Segmentation
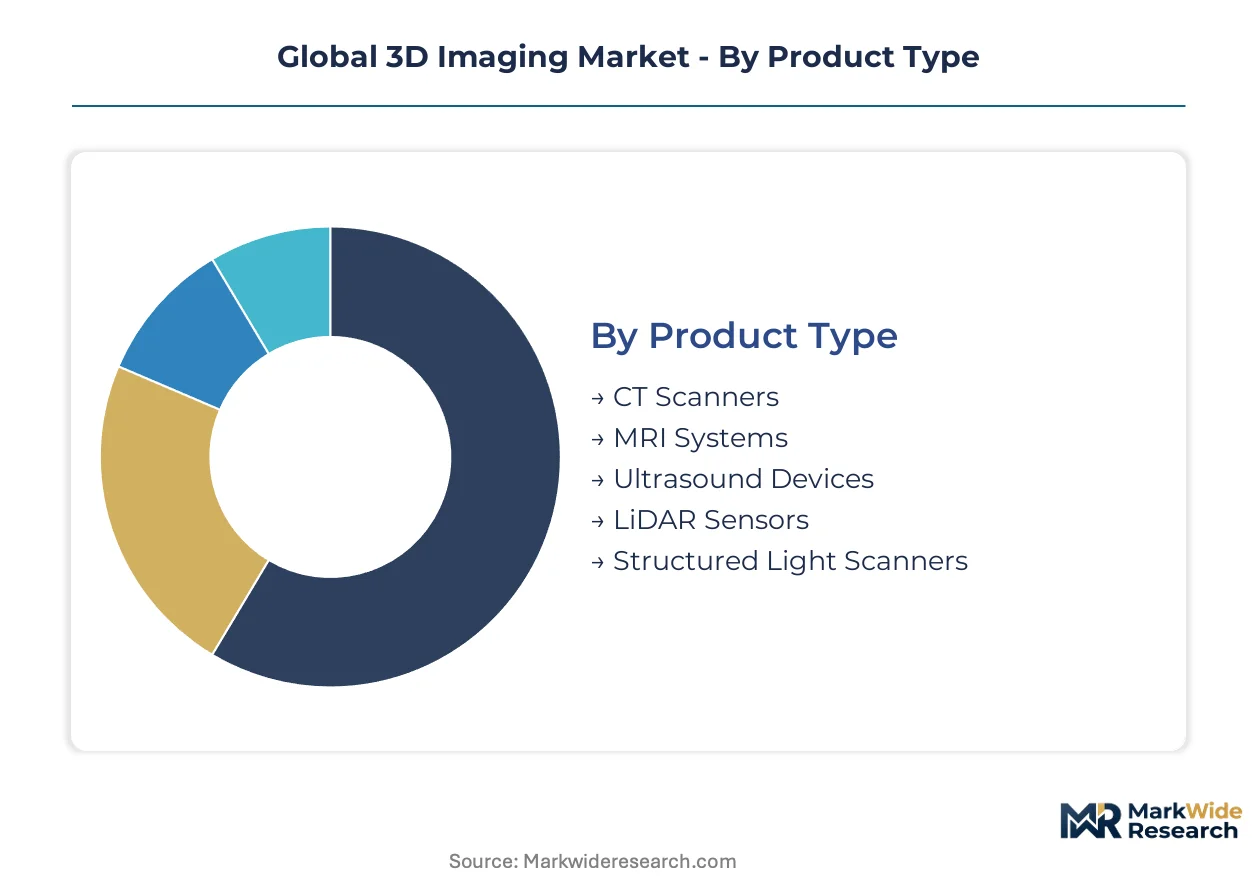
Segmentation in 3D imaging reveals how hardware physics, software reconstruction algorithms, and end-use precision requirements partition revenue pools across radically different customer workflows and capital deployment cycles.
Product Type:
Supply concentration in detector manufacturing and specialized optics creates divergent margin profiles across hardware categories.
- CT Scanners:Rotating gantry systems with multi-slice detector arrays generate volumetric datasets through X-ray attenuation mapping. Hospital procurement committees in Germany and Japan prioritize photon-counting configurations for cardiac and oncology protocols, compressing replacement cycles for energy-integrating legacy platforms.
- LiDAR Sensors:Solid-state and mechanical scanning units emit pulsed laser beams to measure time-of-flight returns for distance calculation. Automotive qualification programs in Germany absorb manufacturing capacity as Tier-1 suppliers integrate these sensors into Level 3 autonomous vehicle platforms, displacing industrial metrology demand.
- MRI Systems:Superconducting magnet assemblies with cryogenic cooling enable proton resonance imaging without ionizing radiation.
- Ultrasound Devices:Piezoelectric transducer arrays generate real-time volumetric imaging through acoustic wave propagation.
- Structured Light Scanners:Projected fringe patterns and camera triangulation capture surface geometries with color texture mapping.
CT Scanners absorb the bulk of installed capacity; LiDAR Sensors are expanding most quickly.
Technology:
Cost tier stratification separates premium photon-counting modalities from commodity depth-sensing approaches in consumer electronics.
- Photon-Counting CT:Direct conversion semiconductor detectors register individual X-ray photons by energy level, enabling material decomposition and dose reduction. Siemens Healthineers and GE Healthcare deploy these arrays across premium scanner tiers in the United States, absorbing service revenue from contrast-agent suppliers through reduced iodine protocols.
- Laser Triangulation:Angular displacement between projected laser lines and sensor arrays calculates surface elevation with sub-millimeter accuracy. Industrial metrology vendors in Germany supply automotive powertrain manufacturers with gantry-mounted systems for cylinder block inspection, embedding volumetric data into digital twin workflows.
- Time-of-Flight:Pulsed illumination and synchronized detection measure photon transit times for depth mapping.
- Photogrammetry:Multi-viewpoint image correlation reconstructs 3D geometry from overlapping 2D captures.
- Stereovision:Disparate camera perspectives compute depth through pixel correspondence algorithms.
- Confocal Microscopy:Pinhole apertures eliminate out-of-focus light for optical sectioning at cellular scales.
Laser Triangulation retains the largest installed base for industrial dimensional inspection; Photon-Counting CT is gaining share fastest in medical replacement cycles.
Application:
Volume concentration in manufacturing quality assurance contrasts with fragmented demand in cultural heritage and entertainment verticals.
- Quality Control:In-line dimensional verification and defect detection integrate 3D imaging into automated production workflows. Aerospace suppliers in the United States mandate volumetric inspection data for turbine blade qualification, embedding metrology into supplier certification requirements.
- Virtual Reality:Photorealistic environment reconstruction and human avatar capture demand real-time depth sensing at consumer price points. Entertainment studios in Japan deploy light stage arrays for volumetric video production, driving sensor miniaturization for portable capture rigs.
- Heritage Preservation:Non-contact documentation of archaeological sites and museum collections prioritizes color accuracy and portability.
- Topographic Mapping:Aerial and terrestrial LiDAR surveys generate digital elevation models for civil engineering and forestry management.
- Forensics:Crime scene documentation and ballistic analysis require courtroom-admissible measurement precision.
Quality Control commands the majority of industrial imaging expenditure; Virtual Reality is climbing the fastest as content production scales.
End User:
Customer type determines procurement modality, with capital-budget hospitals contrasting with grant-funded research institutes and operational-budget law enforcement.
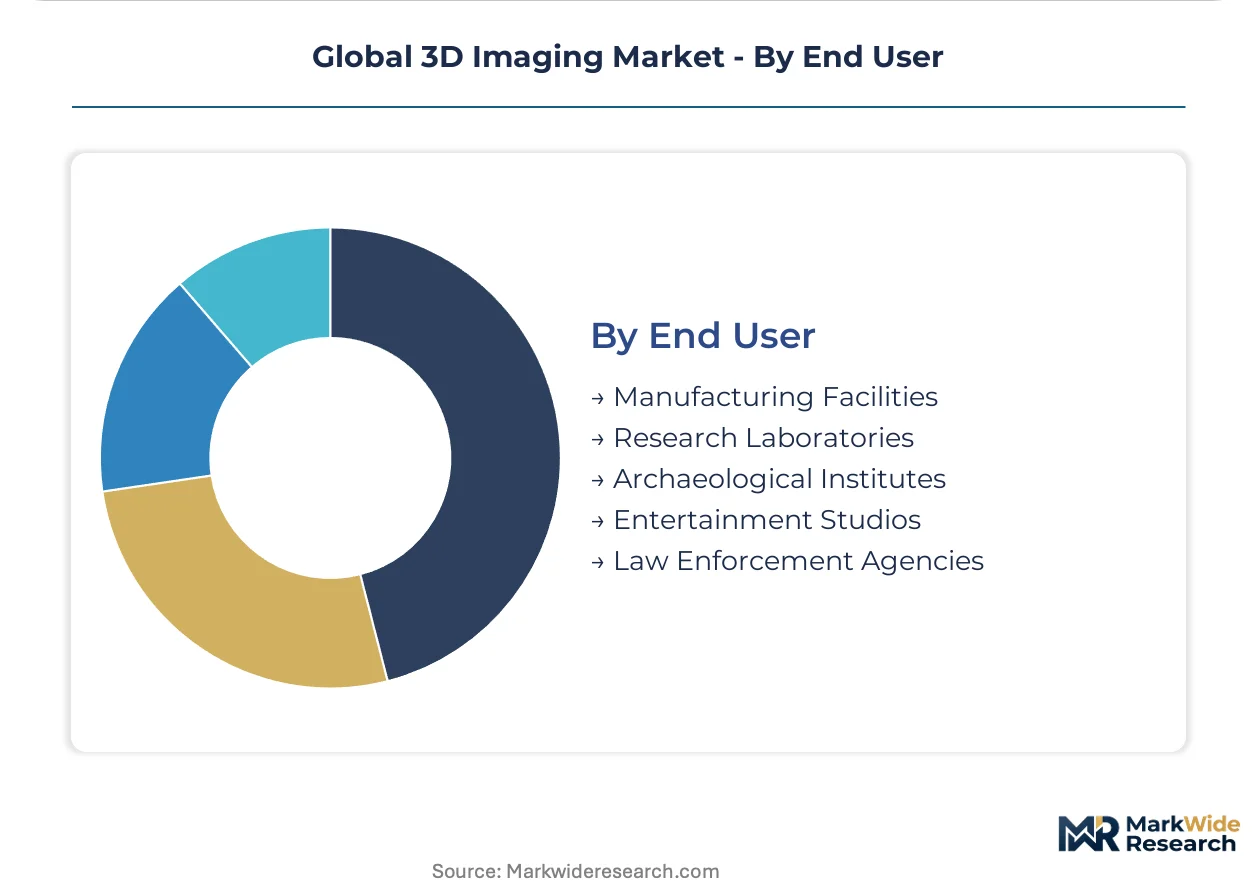
- Manufacturing Facilities:Automated production lines integrate 3D inspection stations for real-time process control. Automotive assembly plants in Germany deploy robotic-guided laser triangulation systems for body-in-white dimensional verification, closing feedback loops with stamping press parameters.
- Research Laboratories:Multi-modal imaging platforms serve materials science and biomedical investigation with customizable acquisition protocols. National laboratories in the United States operate synchrotron-based phase-contrast CT systems for battery electrode characterization, driving detector development partnerships.
- Archaeological Institutes:Field-deployable scanning systems prioritize battery operation and environmental sealing for site documentation.
- Entertainment Studios:Volumetric capture stages and virtual production volumes demand synchronized multi-camera arrays.
- Law Enforcement Agencies:Crime scene documentation and accident reconstruction require training certification and chain-of-custody protocols.
Manufacturing Facilities represent the dominant revenue pool; Research Laboratories are expanding most rapidly through federal funding cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate LiDAR component manufacturing, while medical imaging clusters in Bavaria and North Rhine-Westphalia absorb precision metrology demand from automotive and aerospace supply chains.
United States
FDA 510(k) clearance pathways and NIH research funding sustain CT and MRI replacement cycles at academic medical centers. The Inflation Reduction Act's domestic manufacturing incentives are redirecting semiconductor detector production toward Arizona and Texas fabs. Aerospace suppliers in Wichita and Hartford mandate volumetric inspection data for turbine blade qualification, embedding 3D imaging into supplier certification workflows.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich qualify solid-state LiDAR for Level 3 autonomous platforms, absorbing capacity from industrial metrology lines. EU MDR notified body bottlenecks in Berlin and Hamburg extend time-to-market for novel diagnostic hardware by 12-18 months. The KBA operates parallel technical standards for automotive sensor validation, accelerating domestic deployment timelines.
Japan
PMDA accelerated review tracks reward prior FDA clearance with compressed domestic approval timelines for CT and MRI devices. METI funding for digital twin infrastructure in Nagoya and Osaka manufacturing clusters drives demand for in-line dimensional verification systems. Entertainment studios in Tokyo deploy light stage arrays for volumetric video production, driving sensor miniaturization for portable capture rigs.
China
NMPA streamlined registration pathways for domestically manufactured CT systems are displacing imported equipment in tier-two hospital networks. MIIT industrial internet initiatives in Shanghai and Suzhou mandate volumetric data integration for smart factory certification. Rare earth processing concentration in Inner Mongolia creates input cost leverage for domestic MRI magnet manufacturers.
India
CDSCO parallel track recognition for prior FDA-cleared devices compresses regulatory timelines for manufacturers with existing 510(k) portfolios. PLI scheme incentives for medical electronics manufacturing in Karnataka and Tamil Nadu are attracting CT component assembly operations. Research laboratories in Hyderabad and Bengaluru operate synchrotron partnerships driving detector development collaborations.
Global 3D Imaging Market Competitive Landscape
United States and German producers anchor the premium medical imaging tier; Chinese and Japanese specialists hold component supply positions. The vendor base stratifies across three tiers: integrated platform providers with in-house regulatory affairs capacity, pure-play hardware vendors dependent on distributor networks, and software-integrated workflow specialists. Consolidation pressure concentrates among mid-tier CT manufacturers facing EU MDR compliance cost escalation. Dominant competitive moves include strategic partnerships for AI-assisted reconstruction modules and geographic expansion through direct-to-clinic leasing models.
Within the integrated platform tier, GE Healthcare and Siemens Healthineers exemplify archetypes combining hardware installed bases with service revenue streams. Among software-integrated specialists, Autodesk occupies a position bridging capture hardware and downstream engineering applications. These three companies represent distinct competitive vectors: diagnostic equipment incumbency, photon-counting detector R&D integration, and workflow control across industrial design pipelines.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Autodesk |
| FARO |
| Trimble |
| STMicroelectronics |
| Canon |
| 3D Systems |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up LiDAR specialists in Germany and Japan anchor supply discipline through consolidated component sourcing, translating captive manufacturing capacity into pricing power over automotive Tier-1 procurement committees while compressing margins for pure-play hardware vendors dependent on spot-market detector availability.
Pricing Analysis
Short lead-time premiums dominate CT scanner procurement in the United States, where hospital systems facing EU MDR compliance deadlines pay elevated pricing for FDA-cleared photon-counting systems with immediate installation slots. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting configurations from energy-integrating legacy platforms and refurbished installed base units. Cost compression in mid-tier industrial metrology is intensifying because automotive qualification programs in Germany are absorbing solid-state sensor capacity. Research laboratories exhibit lowest price sensitivity due to federal funding cycles, while independent imaging centers in rural United States markets demand per-scan leasing arrangements.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia are forcing Siemens Healthineers and GE Healthcare to co-locate detector development with university research partnerships, embedding talent pipelines into manufacturing geography decisions. Supply concentrates in China for rare earth magnet processing, Germany for precision optics, and Japan for semiconductor detector arrays. MRI system production draws from neodymium and dysprosium feedstock vulnerable to Chinese export quota volatility. Single-source vulnerability in EU MDR notified body certification creates 12-18 month bottlenecks for novel hardware commercialization. Distribution runs through hospital GPO contracts in the United States, direct-to-clinic leasing networks in Texas and Florida, and national distributor arrangements in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global 3D Imaging Market sits in a technology-transition phase as photon-counting detector arrays displace energy-integrating legacy platforms across cardiac and oncology imaging protocols, compressing replacement cycles and redistributing value capture toward software-integrated reconstruction workflows.
For Market Incumbents: Anticipate consolidation pressure among mid-tier CT manufacturers facing EU MDR compliance cost escalation by accelerating in-house regulatory affairs capacity and securing notified body relationships in Germany and the Netherlands. Defend service revenue streams through predictive maintenance contracts on photon-counting installed bases, as reduced iodine dosage requirements threaten contrast-agent supplier margins. For New Entrants and Emerging Players: Begin with mobile CT leasing models in rural United States markets bypassing traditional distributor networks, capturing outpatient imaging volumes outside hospital capital budgets. Target AI-assisted reconstruction software partnerships with academic medical centers seeking pediatric dose reduction protocols, leveraging deep learning denoising algorithms as the primary go-to-market wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-integrated workflow specialists with FDA-cleared AI modules in the United States and Germany, as hardware pure-plays face margin compression from semiconductor detector cost inflation. Long-term viability hinges on controlling reconstruction algorithms rather than sensor manufacturing. Monitor EU MDR notified body capacity expansion as the critical inflection signal for hardware commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Deployment | Siemens Healthineers and GE Healthcare absorb service revenue from contrast-agent suppliers through reduced iodine protocols. |
| AI-Assisted Reconstruction Software | Deep learning denoising algorithms enable diagnostic-quality imaging at reduced radiation doses for pediatric applications. |
| Direct-to-Clinic Leasing Models | Mobile CT providers in Texas and Florida bypass distributor networks, capturing outpatient volumes outside hospital capital budgets. |
| EU MDR Regulatory Affairs Investment | In-house notified body relationships in Germany and the Netherlands compress time-to-market for novel diagnostic hardware. |
| Digital Twin Infrastructure Partnership | Aerospace suppliers in Wichita and Hartford mandate volumetric inspection data for turbine blade qualification workflows. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, NIH research funding disclosures, and hospital procurement databases, complemented by interviews with biomedical engineers at academic medical centers, regulatory affairs leads at device manufacturers, GPO contracts managers, and CT procurement committee members. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification records, and semiconductor trade flow statistics. Bottom-up installed base modeling and top-down spending allocation triangulated volume estimates.
Segment-level outputs across the projection horizon reflect hardware category, technology tier, end-use application, and customer type dimensions. CAGRs derived from replacement cycle analysis, software upgrade pathway penetration, and federal funding trajectory assumptions incorporate photon-counting detector adoption curves and AI reconstruction module attach rates as primary forecast inputs.
Underlying measurement precision varies by segment; CT scanner and MRI system revenue pools carry tighter precision than heritage preservation and forensic documentation verticals due to established procurement reporting channels. Forecasts assume continued EU MDR notified body capacity constraints, stable rare earth export quotas, and sustained NIH funding levels. Material deviation in notified body expansion timelines, Chinese magnet export policy, or federal research appropriations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Widefield Imaging Systems Market
Imaging
Global Thermal Imager Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Infrared Imaging Software Market
Imaging
Europe Image Sensors Market
Imaging
APAC Image Sensors Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Pico Projector Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Holotomographic Imaging Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Photography Equipment Market
Imaging
Computational Photography Market
Imaging
Thermal Imaging Market