
 Digital Impression Stand Alone Scanners Market | 2026-2036
Digital Impression Stand Alone Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Impression Stand Alone Scanners Market Analysis
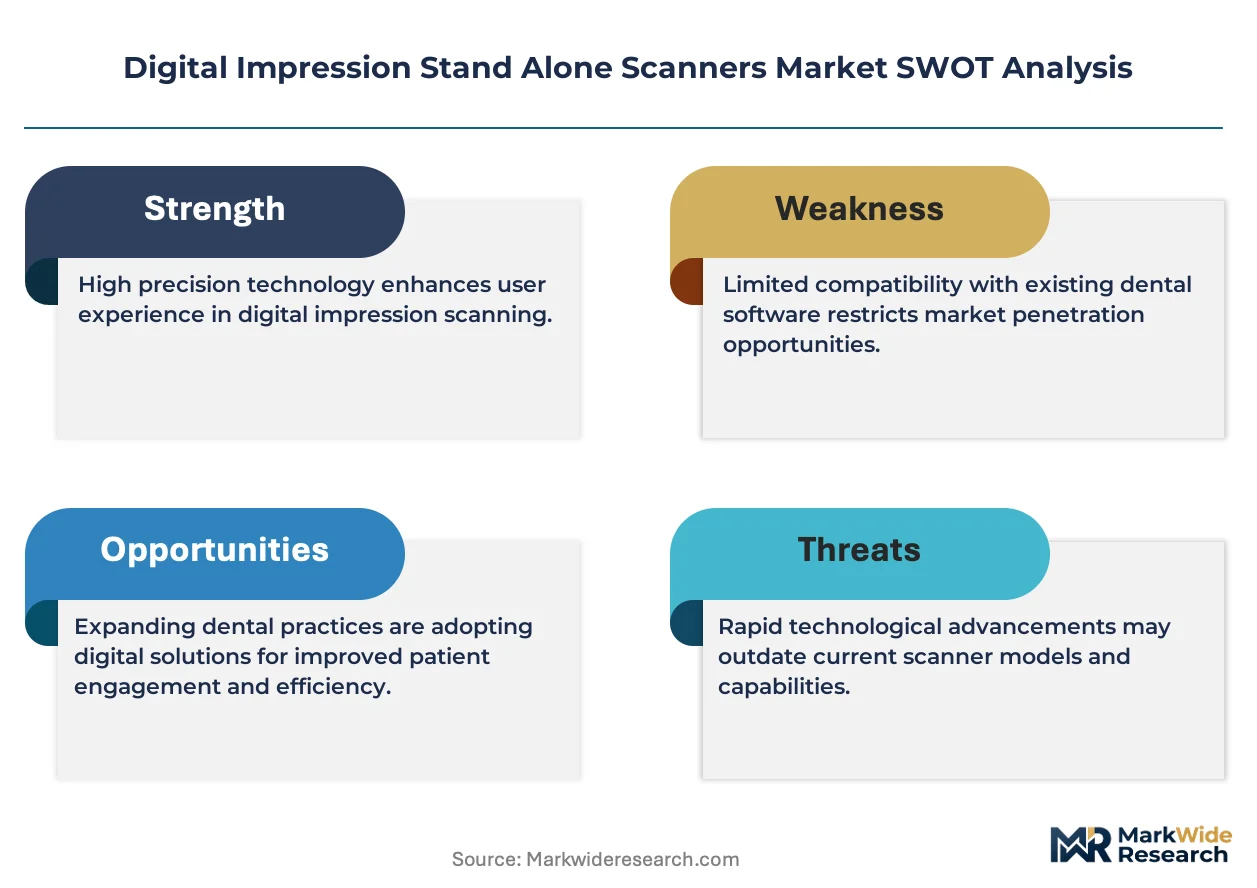
Orthodontic practices are collapsing the traditional dental-laboratory intermediary model by bringing digital impression capture chairside. Align Technology leverages direct-to-practitioner channel control to sustain recurring consumable revenue streams. 3Shape A/S anchors European scanner supply through open-architecture software ecosystems that interoperate with third-party mills. Dentsply Sirona competes via vertically integrated CAD/CAM workflows spanning acquisition through restoration fabrication.
Digital impression stand alone scanners employ optical triangulation, confocal microscopy, or structured light projection to generate sub-50-micron accuracy three-dimensional dental models without physical elastomeric impressions. These devices serve restorative dentistry, orthodontics, and implantology by digitizing tooth morphology for crown, bridge, aligner, and surgical guide production. Intraoral scanners dominate unit shipments while extraoral scanners command premium pricing in dental laboratories handling high-throughput prosthodontics. Hybrid scanners are gaining fastest among multi-site dental service organizations seeking flexible platform deployment across clinic and lab settings.
FDA Class II medical device clearance governs market entry in the United States, while the EU Medical Device Regulation (MDR) and CE marking framework enforce clinical evidence requirements for European commercialization. Japan's PMDA and METI coordinate standards alignment through JIS certification pathways that condition reimbursement eligibility. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under MDR as software-enabled scanners integrate cloud-based treatment planning platforms.
Market Dynamics
Chairside digital workflows are collapsing the traditional dental-laboratory intermediary layer, forcing scanner manufacturers to capture recurring revenue through software subscriptions and consumable lock-in rather than hardware margins alone.
Growth Catalysts
- FDA Class II clearance pathways:Streamlined premarket notification for optical scanning devices accelerates product launch timelines in the United States, reducing regulatory friction for intraoral platform introductions.
- Orthodontic aligner fabrication:Clear aligner production requires high-throughput digital models, driving scanner deployment across orthodontic practices seeking in-house treatment planning control.
- German dental technology clusters:Concentrated precision manufacturing ecosystems in Southern Germany enable rapid prototyping and component sourcing for scanner OEMs serving European demand.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication concentrates among Taiwanese and South Korean foundries, creating vulnerability to semiconductor allocation disruptions.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations under the Medical Device Regulation lengthen certification timelines and inflate documentation costs for European market entry.
- Physical elastomeric impression persistence:Conventional polyether and silicone materials retain cost advantages in resource-constrained settings, delaying digital substitution in price-sensitive segments.
Strategic Opportunities
- Japan's PMDA reimbursement alignment:JIS certification pathways tied to national health insurance coverage create incentive structures for scanner adoption within Japanese dental clinics.
- Implantology surgical guide production:Convergence of intraoral scanning with CBCT imaging enables same-day surgical guide printing, opening high-margin service revenue streams.
- Direct-to-practitioner distribution platforms:Bypassing traditional dental distributor networks through manufacturer-owned digital sales channels reduces margin leakage and accelerates customer acquisition.
Industry Challenges
- CAD/CAM integration complexity:Multi-vendor software environments create interoperability failures between scanner acquisition units and third-party milling systems, requiring costly middleware development.
- Biocompatibility certification timelines:Repeated autoclave sterilization validation for intraoral scanner tips extends FDA 510(k) review cycles and delays product refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Impression Stand Alone Scanners Market |
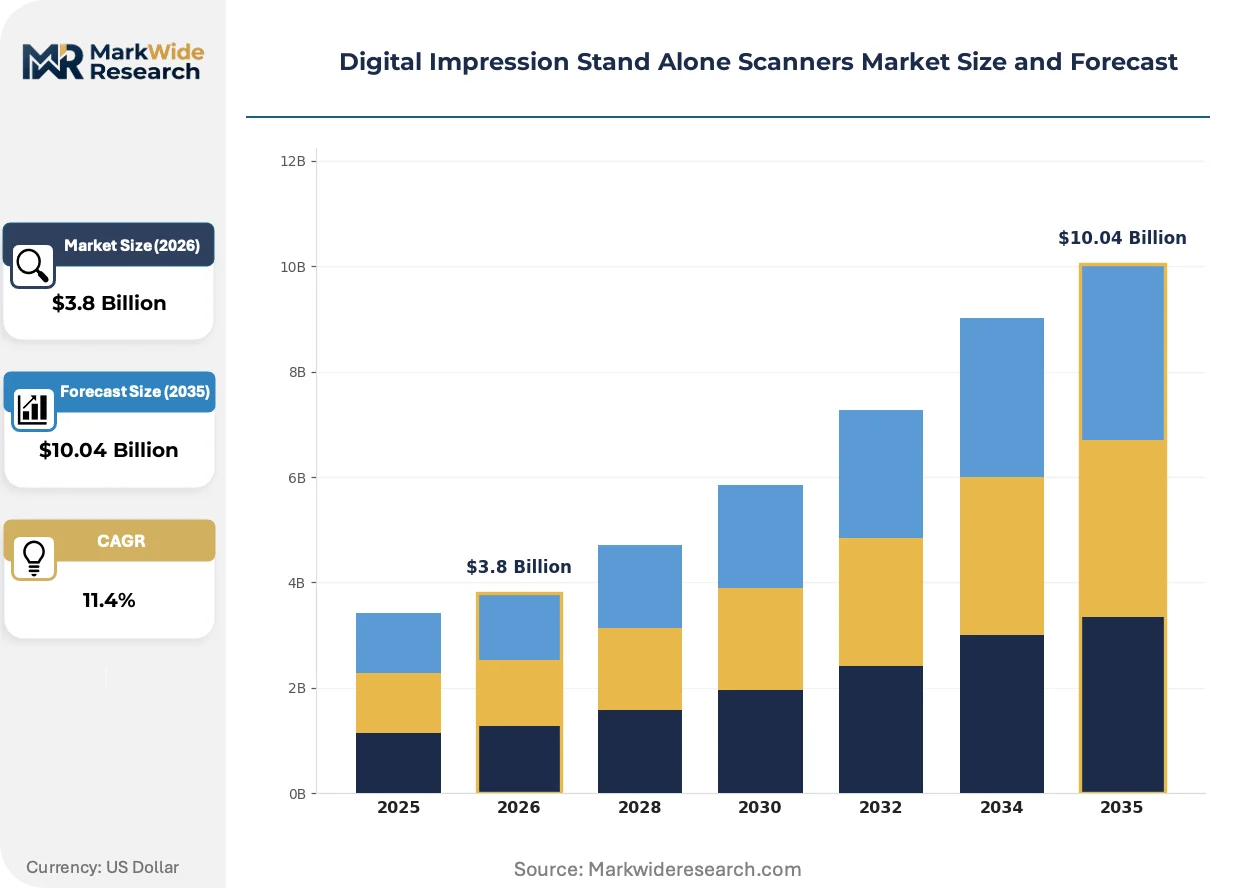
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Extraoral Scanners, Hybrid Scanners, 3D Scanners End User: Dental Clinics, Orthodontic Practices, Dental Laboratories, Hospitals Technology: Triangulation, Confocal Microscopy, Time-of-Flight, Structured Light Application: Restorative Dentistry, Orthodontics, Implantology, Prosthodontics |
| Companies Covered | Align Technology, 3Shape A/S, Dentsply Sirona, Carestream Health, Planmeca Oy, 3M Company, Densys3D Ltd., Glidewell Laboratories, Ormco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Impression Stand Alone Scanners Market Emerging Trajectories
Active scanning modalities are bifurcating market positioning, with confocal microscopy architectures commanding laboratory premiums while structured-light systems penetrate high-volume clinic deployment through cost engineering.
Confocal microscopy is supplanting traditional optical triangulation in high-accuracy prosthodontic applications. German dental laboratories handling full-arch reconstructions now specify sub-10-micron precision requirements that only confocal architectures reliably deliver. This specification shift is compressing margins for legacy structured-light platforms in premium laboratory segments.
Japan's PMDA and METI coordinate cybersecurity guidance for cloud-connected treatment planning platforms, mandating encryption standards for patient data transmission. Scanner manufacturers must now embed hardware security modules to maintain JIS certification eligibility. Japanese dental service organizations are responding by consolidating vendor relationships to reduce compliance audit burden.
Subscription-based software licensing is displacing perpetual purchase models across European orthodontic practices. Aligner treatment planning platforms now bundle scanner hardware with per-case fees, transferring capital expenditure to operational budgets. This financing restructuring is most visible in Germany and France, where multi-site dental groups negotiate enterprise software agreements spanning fifty-plus chairside units.
Digital Impression Stand Alone Scanners Market Segmentation
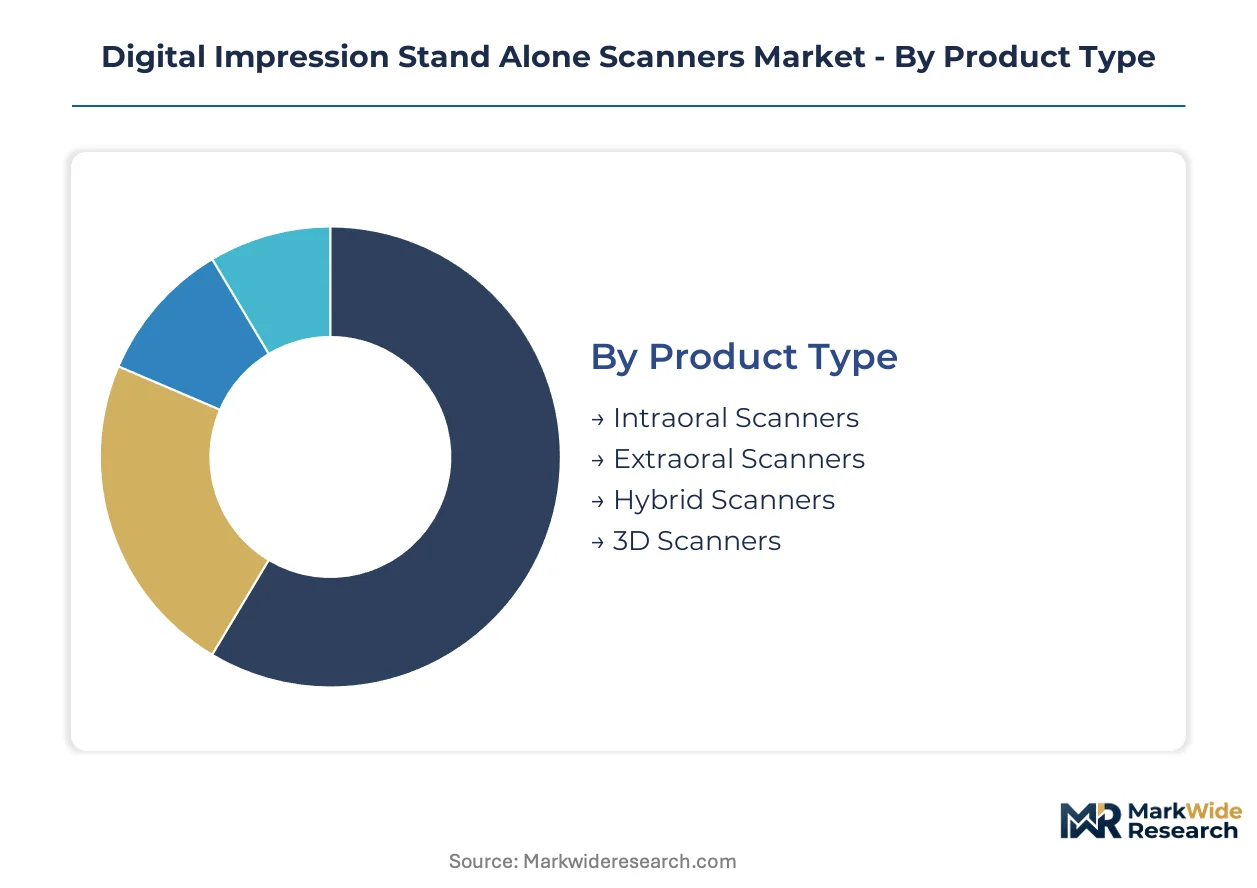
Scanner procurement patterns diverge sharply across clinical settings and technical specifications. Manufacturers calibrate platform architectures to match the precision-volume trade-offs demanded by each segment.
Product Type:
Intraoral and extraoral platforms face divergent substitution pressures from chairside milling systems and laboratory automation respectively.
- Intraoral Scanners:Handheld optical acquisition units capture direct digital impressions at the dental chair, eliminating elastomeric material costs and patient discomfort. Orthodontic practices in Germany deploy these for same-day aligner fabrication, though tip sterilization validation extends FDA 510(k) clearance timelines.
- Extraoral Scanners:Laboratory-grade systems process physical models and impressions through high-resolution optical triangulation or confocal microscopy. Dental laboratories in Southern Germany leverage these for full-arch prosthodontics where sub-10-micron precision justifies premium hardware investment.
- Hybrid Scanners:Multi-site dental service organizations favor convertible platforms that shift between intraoral and extraoral configurations.
- 3D Scanners:General-purpose digitization systems serve lower-volume clinics with reduced feature specificity.
Intraoral scanners retain volume leadership; hybrid scanners hold the steepest expansion curve.
End User:
Procurement authority is fragmenting as group purchasing organizations consolidate dental clinic networks while independent laboratories resist vendor lock-in.
- Dental Clinics:General practitioners drive high unit shipments through routine crown and bridge workflows, constrained by capital budget cycles and software subscription fatigue.
- Orthodontic Practices:Clear aligner production demands dominate scanner utilization, with Align Technology's direct channel bypassing traditional distributors. Japanese orthodontic groups negotiate enterprise agreements spanning fifty-plus chairside units under PMDA reimbursement alignment.
- Dental Laboratories:High-throughput prosthodontic facilities command premium pricing tolerance for confocal microscopy architectures.
- Hospitals:Academic medical centers integrate scanners into surgical guide production for implantology departments.
Dental clinics retain volume leadership; orthodontic practices hold the steepest expansion curve.
Technology:
Cost tier stratification is compressing margins for legacy architectures as confocal systems penetrate mid-market laboratories.
- Confocal Microscopy:Laser-based focal plane scanning achieves sub-10-micron accuracy for full-arch reconstructions. German dental laboratories specify this architecture exclusively for premium prosthodontic segments.
- Structured Light:Projected pattern triangulation enables cost-engineered clinic deployment with adequate accuracy for single-unit restorations. Volume manufacturers source CMOS sensors from Taiwanese foundries, creating supply concentration vulnerability.
- Triangulation:Established optical geometry serves price-sensitive entry-level platforms.
- Time-of-Flight:Pulse-based depth measurement offers speed advantages for extraoral model scanning.
Structured light retains volume leadership; confocal microscopy holds the steepest expansion curve.
Application:
Margin capture varies by procedure complexity, with implantology commanding premium software bundling.
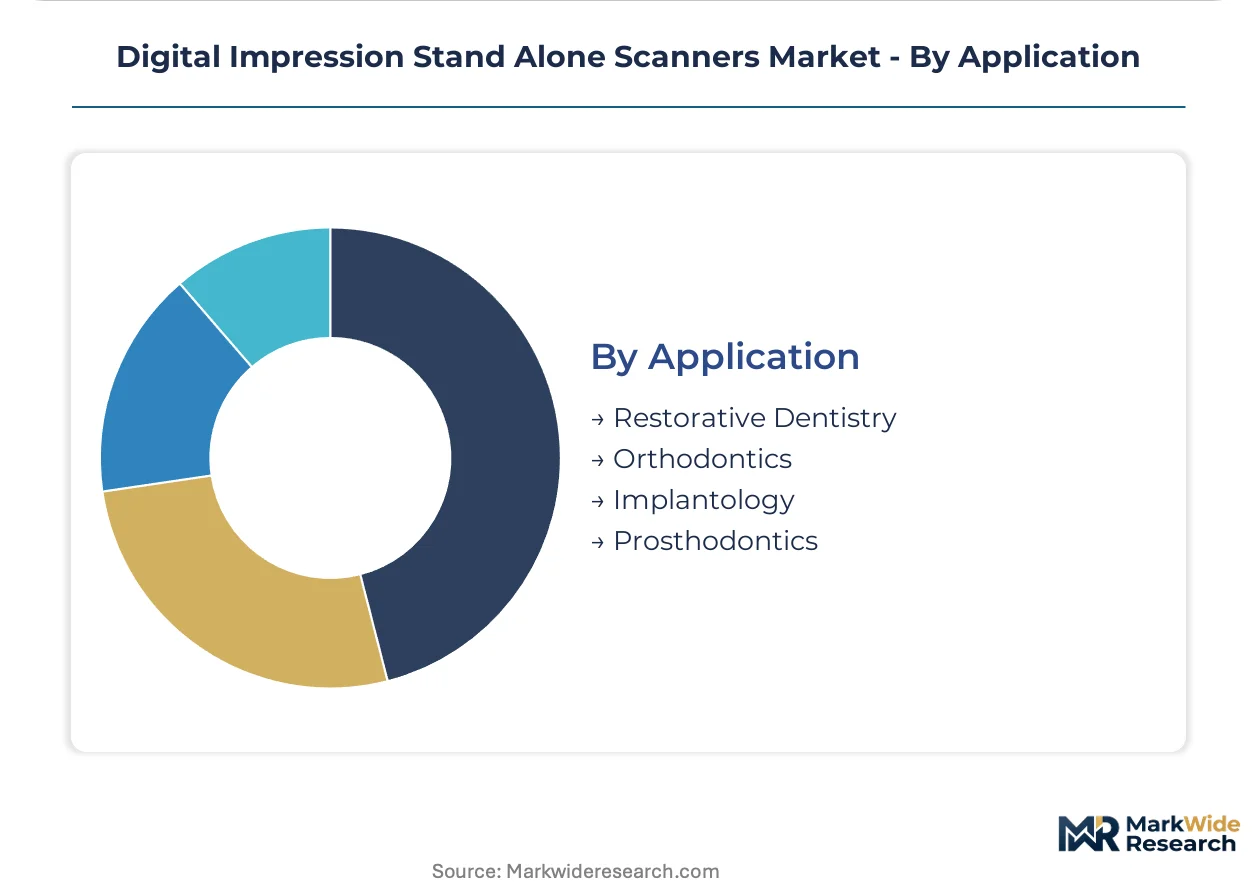
- Orthodontics:Clear aligner fabrication requires high-throughput digital model production, driving scanner-per-chair deployment ratios. Subscription-based treatment planning platforms transfer capital expenditure to per-case operational budgets.
- Implantology:Convergence with CBCT imaging enables same-day surgical guide printing, opening high-margin service revenue streams. FDA Class II clearance pathways govern integrated software platforms in the United States.
- Restorative Dentistry:Routine crown and bridge work sustains baseline scanner utilization across general practice.
- Prosthodontics:Full-arch reconstructions demand laboratory-grade precision specifications.
Restorative dentistry retains volume leadership; implantology holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dental laboratories and multi-site clinic networks concentrate procurement authority in markets where reimbursement alignment and precision manufacturing clusters coexist. Buyer archetypes span orthodontic practices seeking chairside control, German prosthodontic facilities demanding sub-10-micron accuracy, and Japanese dental service organizations consolidating vendor relationships under cybersecurity mandates.
United States
Orthodontic practices drive scanner deployment through clear aligner fabrication demand, with group purchasing organizations consolidating clinic networks under enterprise software agreements. FDA Class II premarket notification pathways govern optical scanning device introductions, streamlining 510(k) clearance timelines for intraoral platforms. The Greater Boston corridor hosts precision optics suppliers serving scanner OEMs with CMOS sensor integration expertise.
Germany
Dental laboratories in Southern Germany specify confocal microscopy architectures exclusively for full-arch reconstruction workflows, compressing margins for legacy structured-light systems. EU Medical Device Regulation post-market surveillance obligations lengthen certification timelines while inflating documentation costs for European commercialization. The Stuttgart precision manufacturing cluster enables rapid prototyping and component sourcing for scanner OEMs serving continental demand.
Japan
Dental service organizations negotiate enterprise agreements spanning fifty-plus chairside units under PMDA reimbursement alignment tied to JIS certification pathways. METI coordinates cybersecurity guidance mandating encryption standards for cloud-connected treatment planning platforms, requiring hardware security module integration. The Nagoya medical device manufacturing corridor concentrates scanner assembly operations serving domestic and Asia-Pacific export markets.
China
Multi-site dental clinic chains accelerate procurement of cost-engineered structured-light platforms for high-volume single-unit restoration workflows. NMPA medical device registration requirements condition market entry timelines for optical scanning equipment, with provincial reimbursement pilots expanding in Yangtze River Delta municipalities. The Shenzhen electronics manufacturing ecosystem supplies CMOS sensors and optical components to domestic scanner assemblers.
South Korea
Dental laboratories serving the Seoul Capital Area adopt hybrid scanner configurations enabling flexible deployment across clinic and laboratory settings. MFDS medical device approval pathways align with international standards, facilitating export-oriented manufacturing strategies for regional scanner OEMs. The Busan precision optics cluster supports confocal microscopy component fabrication for premium laboratory-grade systems.
Digital Impression Stand Alone Scanners Market Vendor Landscape
Player mix skews toward vertically integrated dental technology conglomerates and specialized optical equipment fabricators. Market structure exhibits moderate consolidation with tiered competitive positioning separating premium confocal microscopy specialists from volume structured-light manufacturers. Strategic archetypes span CAD/CAM workflow integrators, open-architecture software platform providers, and direct-to-practitioner channel operators. Dominant competitive moves include backward integration into optical component supply and strategic partnerships with aligner treatment planning platforms.
Among North American technology conglomerates, Align Technology and 3M Company exemplify divergent channel strategies—Align Technology represents the direct-to-practitioner archetype while 3M Company occupies a position within diversified healthcare portfolios. Danish-based 3Shape A/S anchors the open-architecture software ecosystem tier, interoperating with third-party milling systems. German-Swiss conglomerate Dentsply Sirona sits within the vertically integrated CAD/CAM workflow category, spanning acquisition through restoration fabrication.
| Leading Market Players |
|---|
| Align Technology |
| 3Shape A/S |
| Dentsply Sirona |
| Carestream Health |
| Planmeca Oy |
| 3M Company |
| Densys3D Ltd. |
| Glidewell Laboratories |
| Ormco Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with Taiwanese CMOS foundries lock in component access and price visibility for scanner OEMs navigating semiconductor allocation cycles. These contractual structures tether hardware margins to sensor supply security while insulating premium confocal microscopy platforms from spot-market volatility.
Pricing Analysis
Cost-plus contracts with Taiwanese sensor foundries index component pricing to wafer fabrication capacity utilization, creating transparency in hardware cost stacks. Three-tier pricing structure across premium confocal, standard structured-light, and economy triangulation levels separates German laboratory-grade specifications from high-volume clinic deployment. Cost compression in structured-light segments intensifies as Chinese assemblers source Shenzhen-sourced optical components, eroding margin buffers for mid-tier manufacturers. Orthodontic practices exhibit highest price sensitivity due to subscription fatigue from aligner treatment planning platforms, while German prosthodontic laboratories tolerate premium positioning for sub-10-micron accuracy specifications.
Supply Chain Analysis
Taiwan and South Korea anchor CMOS sensor fabrication for intraoral scanner optics, with German precision mechanics suppliers providing confocal microscopy motion stages. Image sensor wafers, laser diodes, and autoclavable tip housings constitute critical input dependencies. Single-source vulnerability concentrates in Taiwanese foundry capacity allocation decisions affecting scanner OEM production schedules. Distribution runs through manufacturer-direct digital channels for orthodontic practices, while dental laboratories procure through specialized dental equipment distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fewer than twelve qualified suppliers worldwide can deliver sub-10-micron confocal architectures, concentrating premium platform capability among German and Danish optical specialists. This scarcity dynamic rewards early certification investment and captive component supply.
For Market Incumbents: Consolidate backward integration into CMOS sensor supply through long-term foundry partnerships or captive wafer allocation, defending against Chinese cost-engineered entrants penetrating structured-light segments. Prioritize FDA 510(k) pre-submission pathways for scanner tip sterilization validation to compress product refresh cycles against regulatory delay risks. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-tracks market entry for implantology-integrated platforms combining intraoral scanning with CBCT surgical guide workflows. Target Japanese dental service organizations under PMDA reimbursement alignment, where enterprise agreements spanning fifty-plus units create volume traction absent in fragmented European clinic networks. Deploy direct-to-practitioner digital sales channels to bypass established distributor margin structures. For Investors and Strategic Acquirers: Open-architecture software platform specialists with third-party mill interoperability represent the most defensible acquisition profile, capturing recurring subscription revenue independent of hardware refresh cycles. Long-term viability hinges on cloud-connected treatment planning platform penetration, with cybersecurity certification breadth serving as the inflection indicator for enterprise customer consolidation trends.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Pathway | Accelerates scanner tip sterilization clearance timelines for intraoral platform refreshes. |
| CE Marking Under EU MDR | Conditions European commercialization on expanded clinical evidence documentation. |
| Hospital System Partnership | Integrates scanners into academic implantology departments for surgical guide production. |
| Software Companion Development | Aligns hardware deployment with cloud-based treatment planning subscription revenue. |
| Reimbursement Strategy Alignment | Ties scanner adoption to PMDA JIS certification eligibility in Japanese dental clinics. |
Methodological Framework
Operator-level perspectives from orthodontic practice owners, dental laboratory technical directors, biomedical equipment procurement managers, and GPO contracts specialists anchored the qualitative base. These primary insights combined with FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA reimbursement bulletins, and CMOS sensor foundry capacity disclosures. Bottom-up unit shipment modeling triangulated against top-down dental clinic capital expenditure surveys.
Sensitivity analysis tested scanner adoption curves across confocal microscopy, structured-light, and triangulation technology tiers, with segmentation spanning intraoral, extraoral, and hybrid platform configurations. Volume projections incorporated orthodontic aligner case growth, implantology surgical guide penetration, and prosthodontic laboratory automation rates. CAGRs derived from logistic diffusion curves calibrated to historical Class II medical device adoption patterns.
Underlying assumptions cover FDA clearance timeline stability, Taiwanese foundry allocation continuity, and EU MDR post-market surveillance cost trajectories, with deviation risk concentrated in semiconductor supply disruptions and cybersecurity certification scope expansion. Recalibration cycles align with material shifts in reimbursement policy, regulatory guidance issuance, and component supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Micro Computed Tomography Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Photoacoustic Microscope Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Side View Camera System Market
Imaging
Handheld Retinal Scanners Market
Imaging
In Vivo Imaging Systems Market
Imaging
X-Ray Systems Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
360-Degree Camera Market
Imaging
Industrial Camera Market
Imaging
Raman-Imaging System Market
Imaging
CCD Image Sensors Market
Imaging
North America Image Sensors Market
Imaging
Europe Image Sensors Market