
 Pocket Video Camera Market | 2026-2036
Pocket Video Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Video Camera Market Outlook
Cloud-based editing subscription tiers and firmware-unlocked resolution upgrades is consolidating how manufacturers monetize hardware relationships. Sony Corporation leverages its cinema-grade sensor R&D to sustain premium positioning across mirrorless and action camera lines. Canon Inc. anchors its strategy through professional videographer loyalty and broadcast-compatible codec ecosystems. GoPro Inc. competes aggressively in outdoor adventure capture through ruggedized industrial design and direct-to-consumer channel control.
A pocket video camera denotes a handheld, battery-powered imaging device engineered for spontaneous video acquisition, typically incorporating CMOS sensors between one-third and full-frame formats, integrated optical or electronic stabilization, and flash-based storage media. Its primary commercial purpose spans personal documentation, social media content generation, and lightweight professional B-roll capture where larger cinema rigs prove impractical. Action camera formats lead volume shipments due to waterproof housings and mountable form factors, while mirrorless segments command the deepest margin pools through interchangeable lens ecosystems and professional color science. Compact camcorders retain residual demand among amateur filmmakers prioritizing extended recording times and ergonomic grips over sensor size.
FCC equipment authorization requirements in the United States govern wireless transmission modules embedded for live streaming and remote control functionality. Japan's METI enforces energy efficiency standards that influence battery chemistry selection and standby power budgets across export-bound product lines. The EU AI Act and GDPR intersect with devices incorporating facial recognition autofocus and cloud-synced metadata tagging, compelling manufacturers to architect opt-in consent flows and on-device processing alternatives. Stakeholders must monitor how emerging right-to-repair mandates across multiple jurisdictions reshape firmware lock-in strategies and aftermarket accessory revenue architectures.
Market Dynamics
Creator economy monetization is compressing upgrade cycles as content producers replace hardware to meet platform algorithmic preferences for higher-resolution uploads. This demand pull forces manufacturers to accelerate sensor and stabilization roadmaps while maintaining backward compatibility with existing accessory ecosystems.
Growth Catalysts
- YouTube Partner Program thresholds:Platform monetization requirements above one thousand subscribers push hobbyists toward professional-grade capture hardware. Creators invest in 4K-capable devices to qualify for premium ad tiers.
- Sensor miniaturization:Backside-illuminated CMOS architectures now deliver cinema-grade dynamic range in sub-full-frame formats. This technology migration enables professional B-roll acquisition from pocketable form factors.
- German action-sports documentation:Alpine and watersports communities in Bavaria and Baden-Württemberg sustain replacement demand through seasonal equipment refresh patterns tied to insurance documentation requirements.
Market Restraints
- Image sensor supply concentration:Advanced CMOS fabrication capacity clusters in Taiwan and South Korea, exposing manufacturers to single-source risk during geopolitical disruptions or foundry allocation constraints.
- Lithium-polymer chemistry volatility:Battery raw material price swings directly impact bill-of-materials stability for compact devices where thermal management limits alternative cell formats.
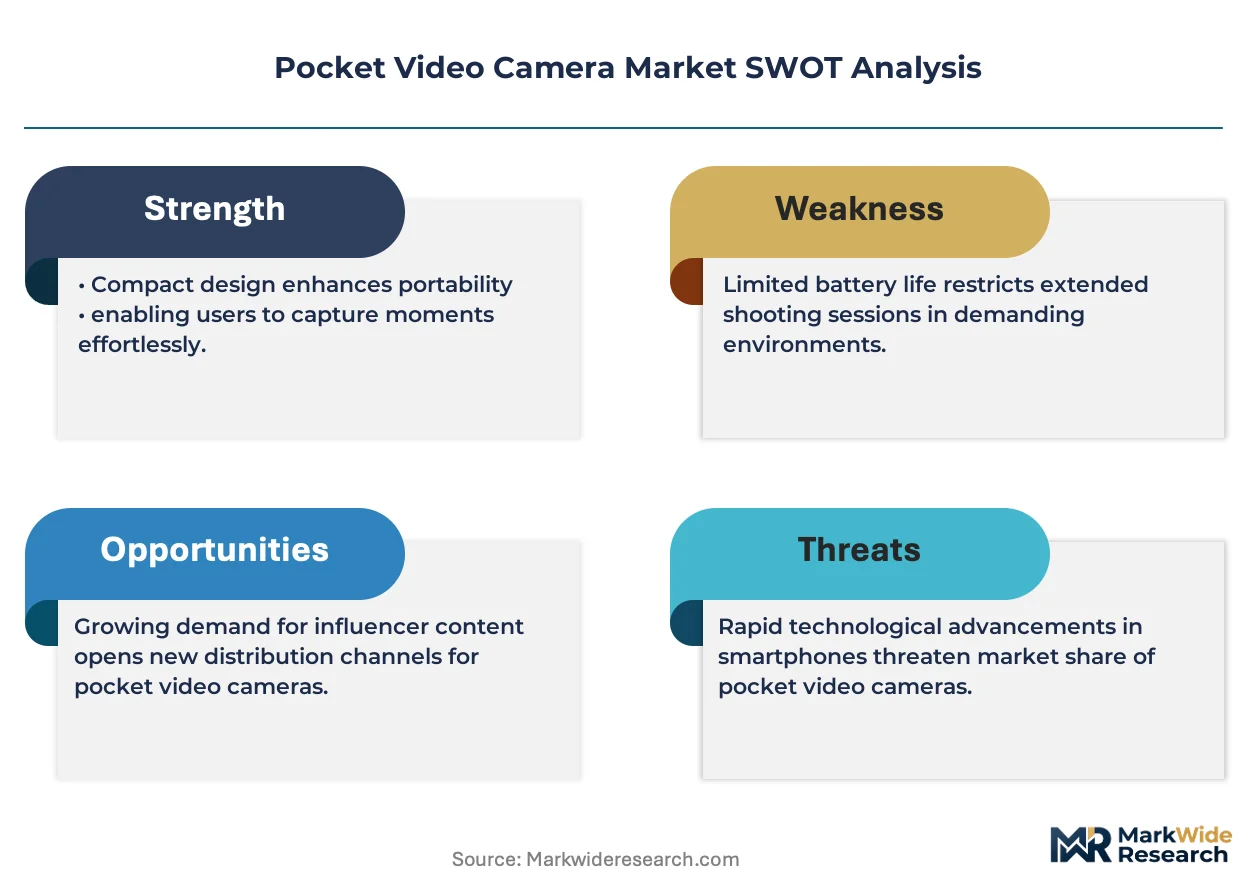
- Smartphone computational photography:Multi-frame stacking and neural processing in flagship handsets substitute for dedicated hardware among casual documentarians, eroding entry-tier addressable market.
Strategic Opportunities
- Indian creator economy expansion:Regional language content platforms drive first-time professional hardware adoption among tier-two city influencers previously limited to smartphone capture.
- EU AI Act compliance tooling:Facial recognition autofocus systems require opt-in consent architectures, creating aftermarket firmware and software service revenue for manufacturers architecting privacy-by-design workflows.
- Live commerce integration:Direct-to-consumer retail channels in China combine product demonstration with immediate purchase, collapsing traditional distributor margins and capturing full value chain economics.
Industry Challenges
- Color science talent scarcity:Professional videographer loyalty depends on manufacturer-specific logarithmic gamma curves and LUT ecosystems, requiring specialized imaging engineers with cinema post-production experience.
- FCC modular certification timelines:Wireless transmission modules for live streaming functionality face extended equipment authorization review periods, delaying product launches and compressing effective sales windows.
- Accessory ecosystem fragmentation:Proprietary mounting interfaces and battery formats lock users into brand-specific hardware, complicating cross-platform standardization efforts and inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Video Camera Market |
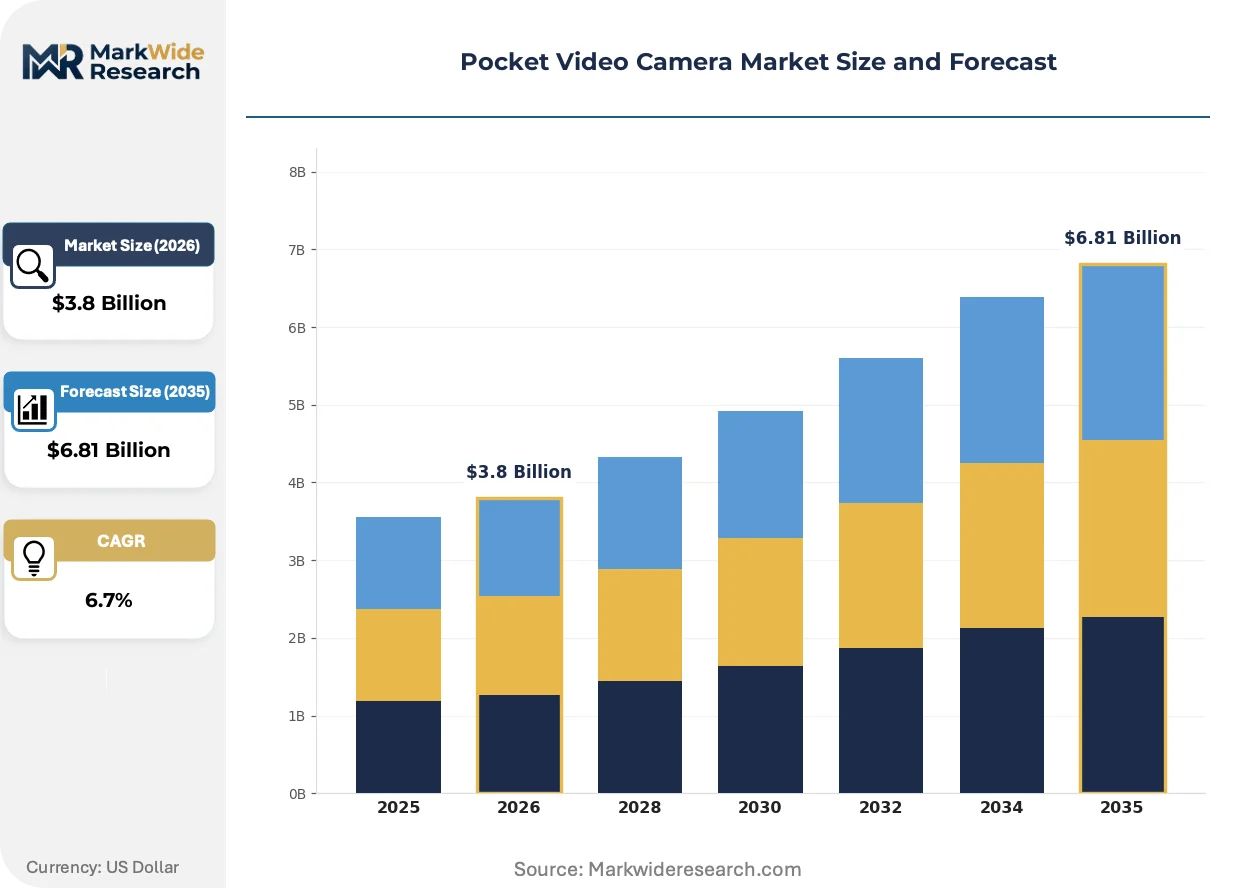
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Camcorder, Action Camera, DSLR, Mirrorless Camera End User: Amateur Filmmakers, Vloggers, Content Creators, Professional Videographers Technology: 4K Recording, Optical Stabilization, Wi-Fi Connectivity, Slow Motion Usage Scenario: Outdoor Adventures, Family Events, Travel Vlogging, Professional Productions |
| Companies Covered | Sony Corporation, Canon Inc., Panasonic Corporation, GoPro Inc., DJI Technology Co. Ltd., Nikon Corporation, FUJIFILM Holdings Corporation, Blackmagic Design Pty. Ltd., Insta360, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Video Camera Market Strategic Shifts
Computational imaging pipelines are redistributing professional-grade output capabilities downward through the price spectrum, collapsing traditional tier boundaries. Hardware differentiation now concentrates on thermal management, ingress protection, and wireless transmission reliability rather than raw sensor specifications.
On-device neural processing is decentralizing post-production workflows previously requiring desktop editing suites. Content creators in the United States and Japan now execute real-time background replacement and subject tracking without external hardware. This capability compression eliminates intermediate upgrade steps between entry and professional tiers, forcing manufacturers to defend margin through software subscription attach rates rather than hardware segmentation.
Japan's METI energy efficiency standards are reshaping battery chemistry selection across export-bound product lines. Manufacturers must optimize standby power budgets and thermal dissipation profiles to maintain market access. Action camera segments face the steepest redesign costs due to waterproof housing constraints that limit passive cooling options, pushing development toward solid-state battery prototypes.
Direct-to-consumer channel disintermediation is collapsing traditional retail margin structures. Outdoor adventure buyers in Germany and the United States now research through platform-native content before purchasing through manufacturer storefronts. This behavior shift concentrates brand equity in owned media production capabilities and compresses distributor relevance to logistics fulfillment rather than demand generation.
Pocket Video Camera Market Segmentation
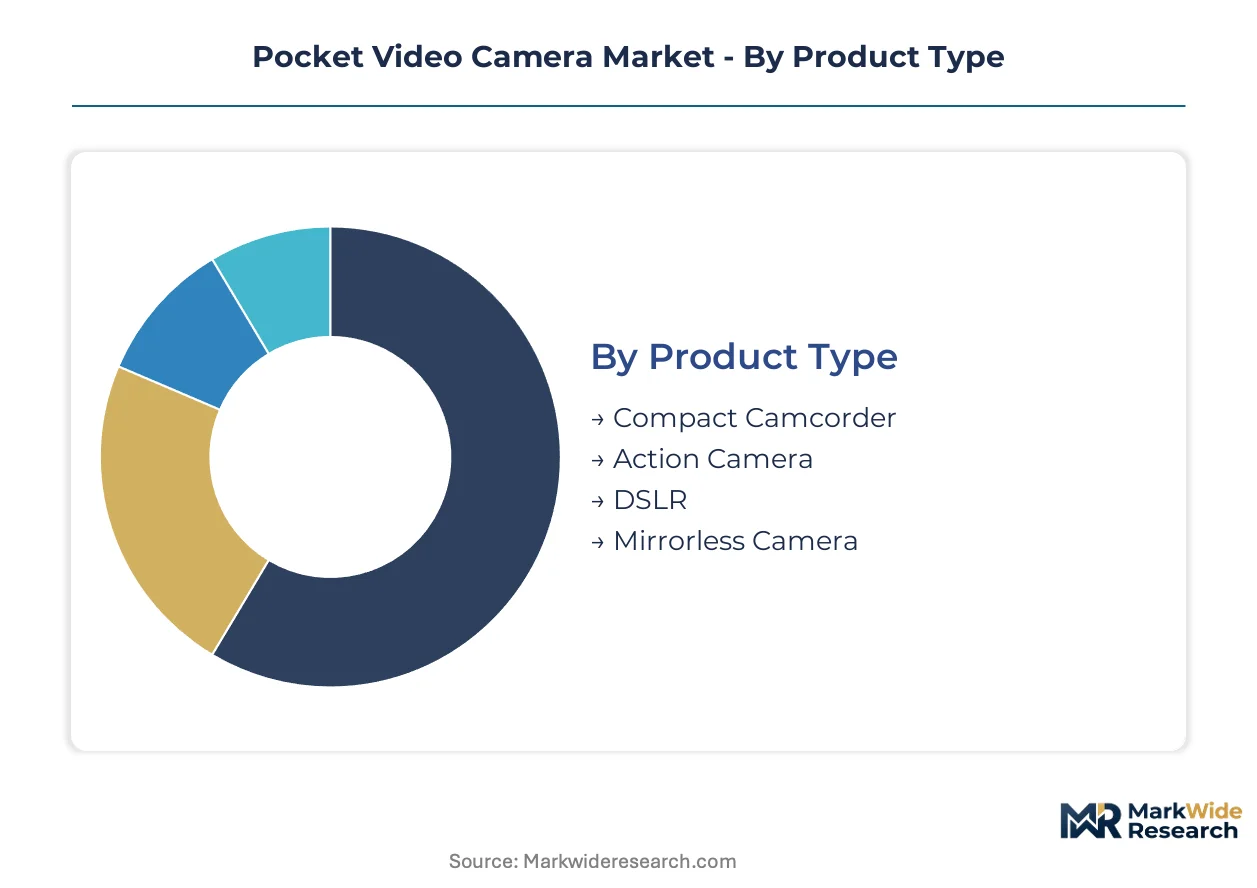
Pocket video camera segmentation reveals how manufacturers architect price-performance ladders across divergent capture workflows. Each dimension—product format, user sophistication, embedded technology, and deployment context—creates distinct margin pools and upgrade pathways that shape competitive strategy.
Product Type:
Standalone capture devices dominate unit economics, while embedded imaging systems in smartphones erode the entry tier from below.
- Action Camera:Ruggedized waterproof housings and universal mounting interfaces define this format. Demand clusters in Germany's Alpine regions and United States national park systems where insurance documentation mandates seasonal equipment refresh.
- Mirrorless Camera:Interchangeable lens ecosystems with cinema-grade color science command the deepest margin pools. Professional videographers in Japan and the United States drive replacement cycles tied to sensor roadmap advances and firmware-unlocked resolution tiers.
- Compact Camcorder:Ergonomic grips and extended recording times serve amateur filmmakers prioritizing usability over sensor specifications.
- DSLR:Optical viewfinder architectures retain residual demand among legacy equipment holders delaying mirrorless migration.
Action Camera leads volumes today; Mirrorless Camera is gaining share fastest.
End User:
Professional credential requirements fragment purchasing authority across individual creators and institutional procurement departments.
- Content Creators:Platform algorithmic preferences for higher-resolution uploads compress hardware replacement cycles. YouTube Partner Program thresholds above one thousand subscribers push this segment toward 4K-capable devices qualifying for premium ad tiers.
- Professional Videographers:Broadcast-compatible codec ecosystems and manufacturer-specific logarithmic gamma curves lock in brand loyalty. Talent scarcity in color science engineering reinforces switching costs across post-production workflows.
- Vloggers:Real-time background replacement and subject tracking demands prioritize on-device neural processing capabilities.
- Amateur Filmmakers:Extended recording times and intuitive interfaces outweigh raw sensor performance in purchase decisions.
Content Creators expand most quickly; Professional Videographers anchor premium pricing.
Technology:
Feature integration depth determines whether capabilities ship as baseline specifications or firmware-locked upgrade revenue streams.
- 4K Recording:Backside-illuminated CMOS architectures now deliver cinema-grade dynamic range in sub-full-frame formats. FCC equipment authorization requirements for wireless transmission modules govern live streaming implementations.
- Optical Stabilization:Mechanical gimbal systems and sensor-shift architectures differentiate professional B-roll acquisition from electronic alternatives. Japan's METI energy efficiency standards influence actuator power budgets across export-bound product lines.
- Wi-Fi Connectivity:Remote control functionality and cloud-synced metadata tagging intersect with EU AI Act consent requirements for facial recognition autofocus systems.
- Slow Motion:High frame-rate capture demands specialized memory buffer architectures and thermal management solutions.
4K Recording leads adoption today; Optical Stabilization drives replacement demand fastest.
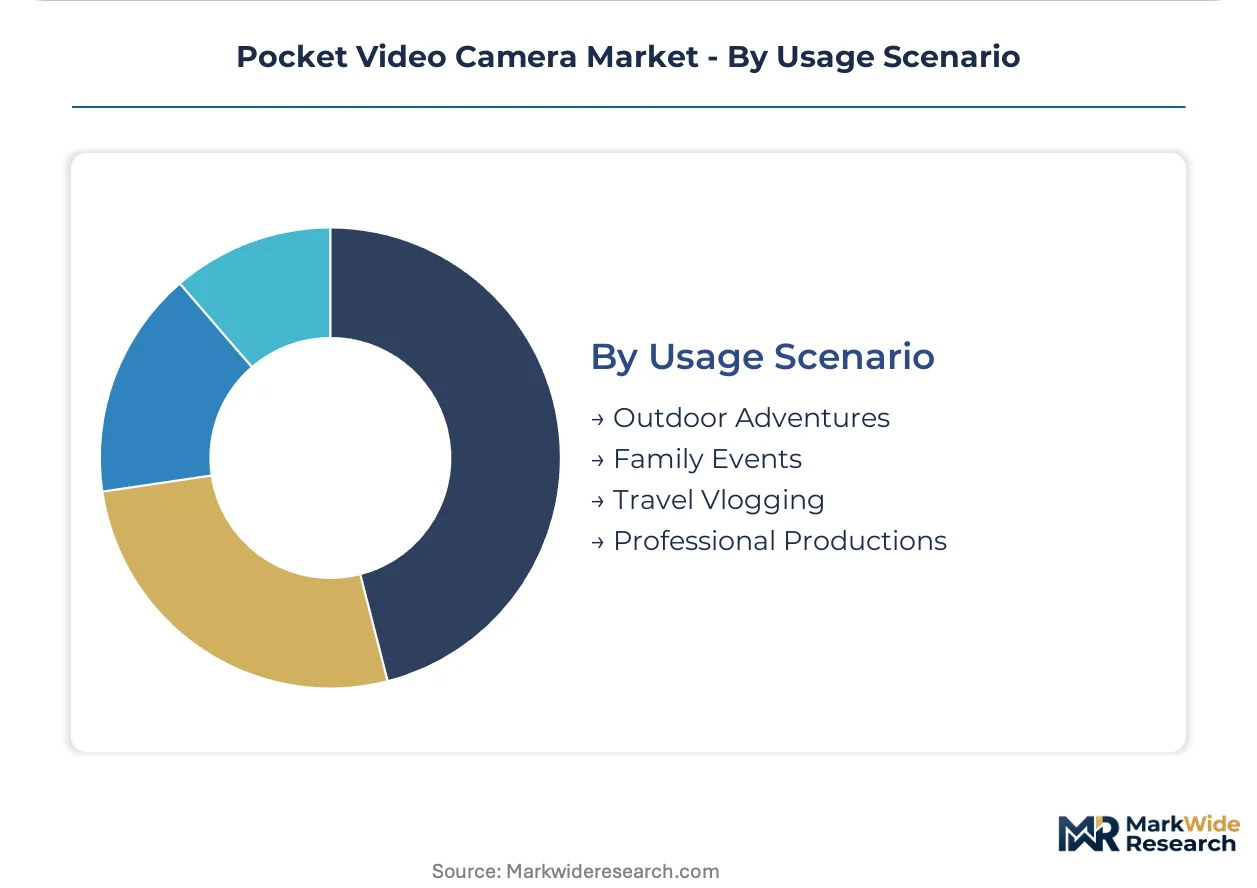
Usage Scenario:
Environmental exposure severity dictates ingress protection ratings and accessory ecosystem requirements.
- Outdoor Adventures:Waterproof housings and mountable form factors dominate. German watersports communities in Bavaria and Baden-Württemberg sustain replacement patterns tied to seasonal insurance documentation.
- Professional Productions:Lightweight B-roll capture where cinema rigs prove impractical drives interchangeable lens demand. Color science consistency with primary camera systems determines brand selection.
- Travel Vlogging:Compact form factors and rapid deployment capabilities prioritize one-handed operation and flip-screen articulation.
- Family Events:Extended battery life and simple sharing workflows outweigh advanced manual controls in purchase criteria.
Outdoor Adventures leads shipment volumes today; Professional Productions commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator economy monetization in the United States outpaces German replacement cycles by nearly eighteen months, while Japanese sensor innovation clusters concentrate export-bound manufacturing decisions.
United States
YouTube Partner Program thresholds above one thousand subscribers drive 4K-capable hardware adoption among Los Angeles and New York-based content creators. FCC equipment authorization requirements govern wireless transmission modules for live streaming functionality. Austin and Denver outdoor adventure communities sustain seasonal action camera refresh patterns tied to insurance documentation mandates.
Germany
Alpine and watersports documentation in Bavaria and Baden-Württemberg compresses equipment replacement cycles through liability-driven refresh requirements. KBA transportation safety standards influence mountable camera housing durability specifications for automotive documentation applications. Munich imaging technology clusters anchor professional videographer procurement decisions across broadcast-compatible codec ecosystems.
Japan
METI energy efficiency standards reshape battery chemistry selection and standby power budgets across export-bound product lines. Tokyo and Osaka sensor fabrication clusters concentrate backside-illuminated CMOS R&D for cinema-grade dynamic range in compact formats. Nagoya precision engineering hubs supply optical stabilization actuator systems to global camera manufacturers.
India
Regional language content platforms drive first-time professional hardware adoption among tier-two city influencers previously limited to smartphone capture. BIS certification requirements for electronic goods influence import compliance timelines for international manufacturers. Bengaluru and Mumbai creator economy clusters expand demand for firmware-unlocked resolution upgrade tiers.
China
Live commerce integration through direct-to-consumer retail channels collapses traditional distributor margins and captures full value chain economics. MIIT radio transmission regulations govern wireless connectivity certification for cloud-synced metadata tagging functionality. Shenzhen hardware manufacturing ecosystems concentrate action camera assembly and waterproof housing production.
Pocket Video Camera Market Competitive Environment
Top-tier vendors anchor premium positioning through cinema-grade sensor R&D, while mid-tier specialists compete on ruggedized industrial design and creator-centric software ecosystems. The vendor base stratifies across three strategic archetypes: sensor-integrated conglomerates leveraging semiconductor verticality, action-sport specialists commanding direct-to-consumer channels, and mirrorless innovators cultivating professional videographer loyalty. Dominant competitive moves include firmware-locked resolution upgrade monetization and cloud-based editing subscription attach rates.
Within the sensor-integrated conglomerate tier, Sony Corporation and Canon Inc. exemplify positioning anchored in broadcast-compatible codec ecosystems and logarithmic gamma curve differentiation. Panasonic Corporation occupies a position bridging professional videographer loyalty with action-sport durability requirements. GoPro Inc. anchors the direct-to-consumer specialist archetype through owned channel control and outdoor adventure brand equity.
| Leading Market Players |
|---|
| Sony Corporation |
| Canon Inc. |
| Panasonic Corporation |
| GoPro Inc. |
| DJI Technology Co. Ltd. |
| Nikon Corporation |
| FUJIFILM Holdings Corporation |
| Blackmagic Design Pty. Ltd. |
| Insta360 |
| Others |
Value Chain & Pricing Dynamics
Japan's METI energy efficiency standards gate qualified battery chemistry supply and premium-tier pricing access, forcing manufacturers to absorb redesign costs for solid-state prototypes or surrender margin in export-bound product lines. This environmental mandate compresses price floors for action camera segments while elevating entry barriers for mid-tier competitors lacking thermal management expertise.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for backside-illuminated CMOS sensors, enabling three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on optical stabilization actuator quality and FCC modular certification status. Cost compression in the entry tier intensifies because smartphone computational photography substitutes erode casual documentarian demand. Amateur filmmakers exhibit highest price sensitivity; professional videographers anchored to logarithmic gamma ecosystems tolerate premium positioning.
Supply Chain Analysis
Precision engineering talent scarcity in Nagoya and Shenzhen constrains optical stabilization actuator output and waterproof housing fabrication throughput. Geographic supply concentrates in Japan, Taiwan, and China for CMOS sensors, lithium-polymer cells, and precision actuators. Raw material dependencies draw from rare earth elements for lens coatings, cobalt for battery cathodes, and high-purity silicon for sensor substrates. Single-source vulnerability in advanced CMOS fabrication exposes manufacturers to foundry allocation disruptions. Distribution runs through direct-to-consumer manufacturer storefronts and platform-native live commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's BIS certification timelines lag EU AI Act compliance burdens by eighteen months, creating first-mover windows for firmware-locked resolution tiers among tier-two city influencers.
For Market Incumbents: Anchor premium positioning through cinema-grade sensor R&D verticality and broadcast-compatible codec ecosystem lock-in. Defend against smartphone neural processing substitution by accelerating on-device background replacement capabilities. Prioritize channel control via owned direct-to-consumer storefronts over distributor margin compression. For New Entrants and Emerging Players: Launch via live commerce integration in China's direct-to-consumer retail channels to collapse traditional distributor economics. Target India's regional language content creator segment with firmware-unlocked upgrade tiers priced below Sony and Canon entry points. Exploit EU AI Act compliance tooling as aftermarket software service revenue. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier action camera specialists because accessory ecosystem fragmentation inflates total cost of ownership and locks users into brand-specific hardware. Long-term viability hinges on capturing creator economy subscription attach rates rather than hardware shipment volumes. Watch for inflection when METI energy efficiency standards force solid-state battery redesigns across export-bound product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Locked Resolution Upgrades | Monetizes hardware relationships through cloud-based editing subscription tiers and post-purchase capability unlocks. |
| Direct-to-Consumer Channel Expansion | Collapses traditional retail margins and captures full value chain economics in Germany and United States outdoor adventure segments. |
| Optical Stabilization R&D Investment | Differentiates professional B-roll acquisition from electronic alternatives in Japan's Nagoya precision engineering clusters. |
| EU AI Act Compliance Tooling | Creates aftermarket firmware revenue for facial recognition autofocus opt-in consent architectures. |
| Live Commerce Platform Integration | Combines product demonstration with immediate purchase through China's MIIT-regulated wireless transmission channels. |
Study Parameters
Bottom-up content creator adoption modeling reconciled against top-down CMOS sensor shipment tracking forms the analytical core. Primary interviews with professional videographers, platform engineering leads at YouTube and TikTok, optical stabilization actuator procurement managers, and FCC equipment authorization consultants combined with secondary validation from SEC 10-K filings, METI energy efficiency disclosure databases, and EU AI Act regulatory guidance documents. Triangulation across these sources yields volume and value estimates.
Historical trendline analysis of replacement cycle compression and platform algorithmic preference shifts informs projection mechanics across the analysis window. Segmentation dimensions modeled include product format, user sophistication tier, embedded technology depth, and deployment context severity. CAGRs derive from sensor roadmap acceleration rates and firmware monetization attach rate assumptions. Forecast inputs incorporate creator economy monetization threshold changes and insurance documentation mandate propagation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption in Taiwan Strait shipping lanes or lithium-polymer raw material price spikes. Projections reflect assumptions regarding platform resolution preference stability and regulatory compliance timeline adherence. Material deviation in METI energy efficiency standard enforcement or FCC modular certification backlogs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Industrial Camera Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Chemical Imaging Systems Market
Imaging
Global 3D Camera Market
Imaging
AI Camera Market
Imaging
Light Field Market
Imaging
Chemiluminescence Imaging Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Global Computed Radiography Market
Imaging
Embedded Smart Cameras Market
Imaging
Hybrid Imaging Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Global Acoustic Cameras Market
Imaging
Event Camera Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market