
 High Dynamic Range Market | 2026-2036
High Dynamic Range Market Size, Share, and Industry Trends Forecast 2026-2036
High Dynamic Range Market Outlook
The EU Ecodesign for Energy-related Products Directive is realigning the cost-of-entry calculus for display manufacturers targeting European distribution. Samsung Electronics leverages vertical integration across panel and semiconductor supply chains to sustain pricing flexibility in premium smart TV tiers. Sony Corporation anchors its position through proprietary image processing silicon that differentiates cinema-grade reference monitors from commodity panels.
High Dynamic Range denotes imaging and display systems capable of reproducing luminance ratios exceeding 1,000:1 between darkest shadows and brightest highlights, typically quantified in nits where consumer displays now target 1,000–4,000 nits peak brightness. The technology enables content creators to preserve detail across extreme lighting conditions in broadcast, gaming, and film production workflows. Smart TVs running Dolby Vision command margin concentration at the premium tier, while HDR10 dominates volume shipments due to royalty-free licensing. Gaming applications represent the fastest-expanding segment as console and GPU manufacturers mandate HDR output across new hardware generations.
The FCC enforces broadcast transmission standards that shape HDR signal distribution across US terrestrial and cable networks, while CE marking under EU Ecodesign mandates minimum efficiency thresholds for displays sold in member states. Japan's METI coordinates domestic 4K/8K HDR broadcast trials that influence regional equipment procurement cycles. Stakeholders must monitor divergence between royalty-bearing Dolby Vision ecosystems and open-standard HDR10+ adoption curves as content licensing terms reshape hardware profitability.
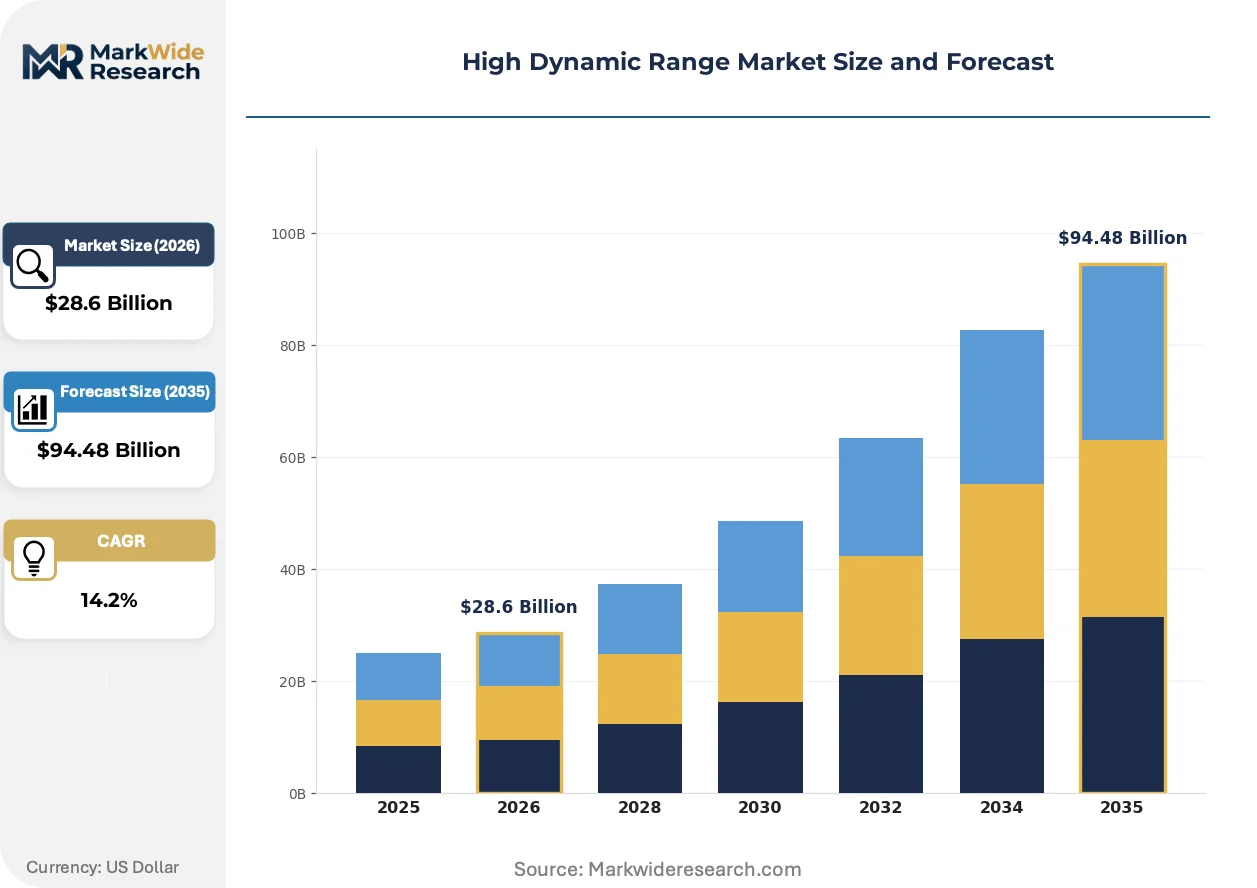
Market Dynamics
The convergence of royalty-bearing Dolby Vision ecosystems with open-standard HDR10+ adoption curves is compressing margin structures across display manufacturing tiers, forcing hardware vendors to recalibrate certification strategies against content licensing terms.
Growth Catalysts
- Console GPU mandates:Sony PlayStation and Microsoft Xbox hardware generations now enforce HDR output requirements, pulling display upgrade cycles forward across gaming households.
- EU Ecodesign thresholds:Minimum efficiency standards for displays sold in member states are accelerating LED backlight technology transitions in European-bound manufacturing lines.
- Streaming pipeline expansion:Netflix, Disney+, and Amazon Prime Video have normalized HDR mastering for original content, creating baseline consumer expectation for compatible hardware.
Market Restraints
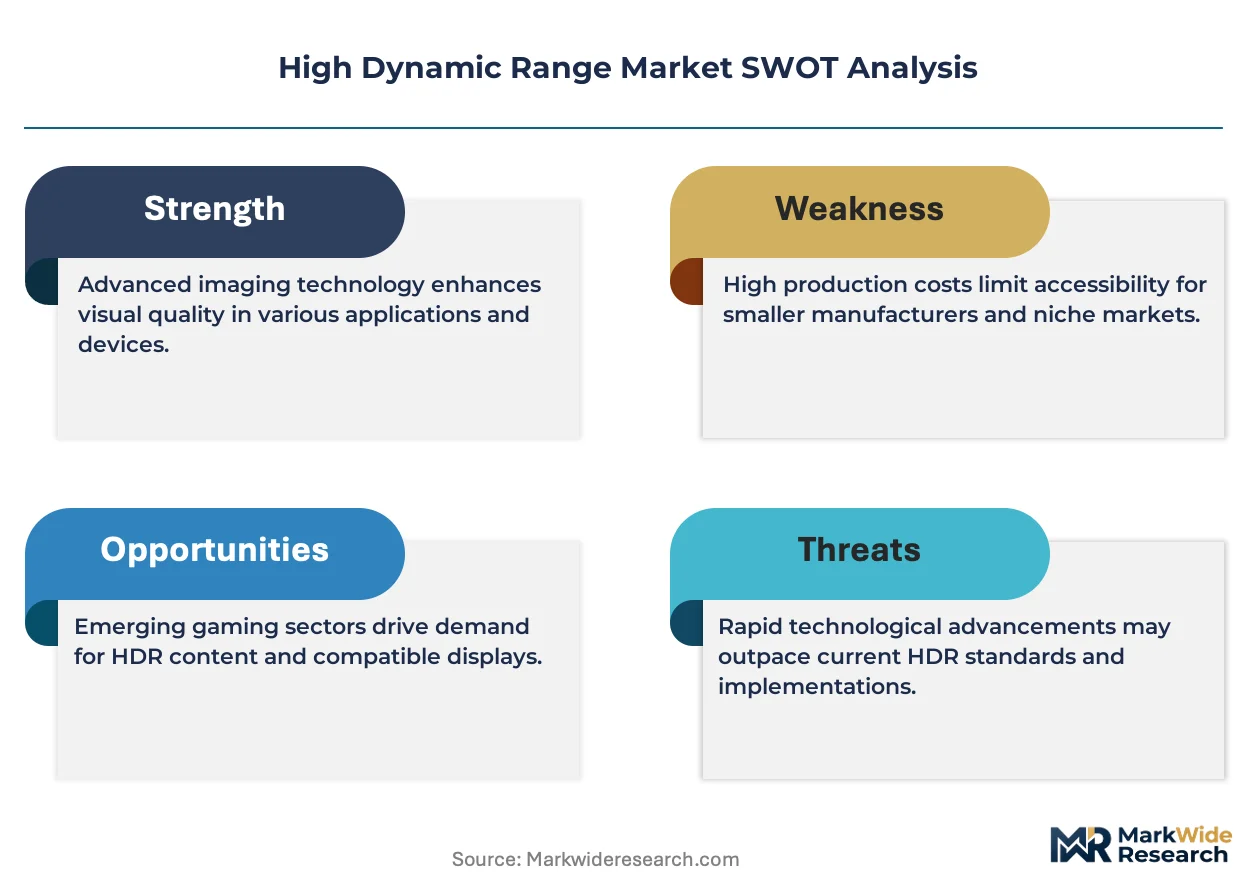
- Rare earth element concentration:Neodymium and europium supply for quantum dot enhancement films clusters within Chinese processing facilities, exposing panel makers to input volatility.
- Dual certification burden:Simultaneous Dolby Vision and HDR10+ licensing creates redundant royalty stacks that disproportionately burden mid-tier display vendors.
- Luminance ceiling physics:Thermal management constraints in edge-lit LED architectures cap consumer display brightness below 2,000 nits without costly mini-LED transitions.
Strategic Opportunities
- India broadcast infrastructure:TRAI-mandated 4K set-top box deployments are creating first-time HDR upgrade demand across 400 million television households.
- Automotive display integration:HDR-capable cockpit screens are penetrating electric vehicle platforms as Mercedes-Benz and BMW differentiate cabin experience through high-contrast instrumentation.
- Cloud gaming edge nodes:Google Stadia and NVIDIA GeForce NOW server farms require HDR encoding pipelines, opening enterprise display procurement channels beyond consumer retail.
Industry Challenges
- Color science talent scarcity:Reference monitor calibration and HDR grading workflow expertise concentrates within Los Angeles and London post-production clusters, constraining regional content hub development.
- Legacy SDR integration:Broadcast infrastructure amortization cycles delay HDR signal chain replacement, forcing hybrid encoding investments that complicate operational workflows.
- Patent thickets around tone mapping:Dolby Laboratories and Technicolor hold overlapping intellectual property in perceptual quantizer algorithms, creating licensing negotiation friction for algorithm developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Dynamic Range Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Cameras, Smart TVs, Projectors Technology: HDR10, Dolby Vision, HLG, Advanced HDR End User: Residential, Commercial, Educational, Entertainment Application: Broadcasting, Gaming, Photography, Film Production |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, Canon Inc., Nikon Corporation, Fujifilm Holdings Corporation, Hisense Group, Dolby Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Dynamic Range Market Strategic Shifts
Mini-LED backlight architectures are cascading from cinema reference monitors into mass-market smart TVs, compressing the performance gap between professional and consumer display tiers while reconfiguring supply chain sourcing patterns for LED die manufacturers.
Dual-layer LCD technology is absorbing the luminance demands previously reserved for OLED panels, enabling 4,000-nit peak brightness in cost-constrained product lines. Chinese panel makers BOE and CSOT are deploying this architecture across 65-inch and larger screen sizes. The technology is absorbing market share from high-end OLED segments where burn-in risk deters commercial signage buyers.
Japan's METI has coordinated domestic 8K HDR broadcast trials through NHK since 2016, establishing transmission protocols that now influence equipment procurement cycles across East Asian markets. The regulator's Super Hi-Vision roadmap mandates HDR metadata carriage in terrestrial signals, forcing receiver manufacturers to embed HLG (Hybrid Log-Gamma) compatibility. Japanese domestic equipment makers are responding with integrated tuner-processor SoCs that reduce bill-of-materials complexity for export-bound television sets.
Enterprise procurement of HDR reference monitors is fragmenting across direct manufacturer relationships and specialized broadcast equipment distributors, displacing traditional consumer electronics retail channels for professional-grade hardware. Post-production houses in Berlin, Mumbai, and São Paulo are establishing dedicated vendor accreditation programs that bypass regional distributors. This pattern is most visible in subscription-based color grading suite operators who prioritize calibration service bundling over upfront hardware acquisition.
High Dynamic Range Market Segmentation
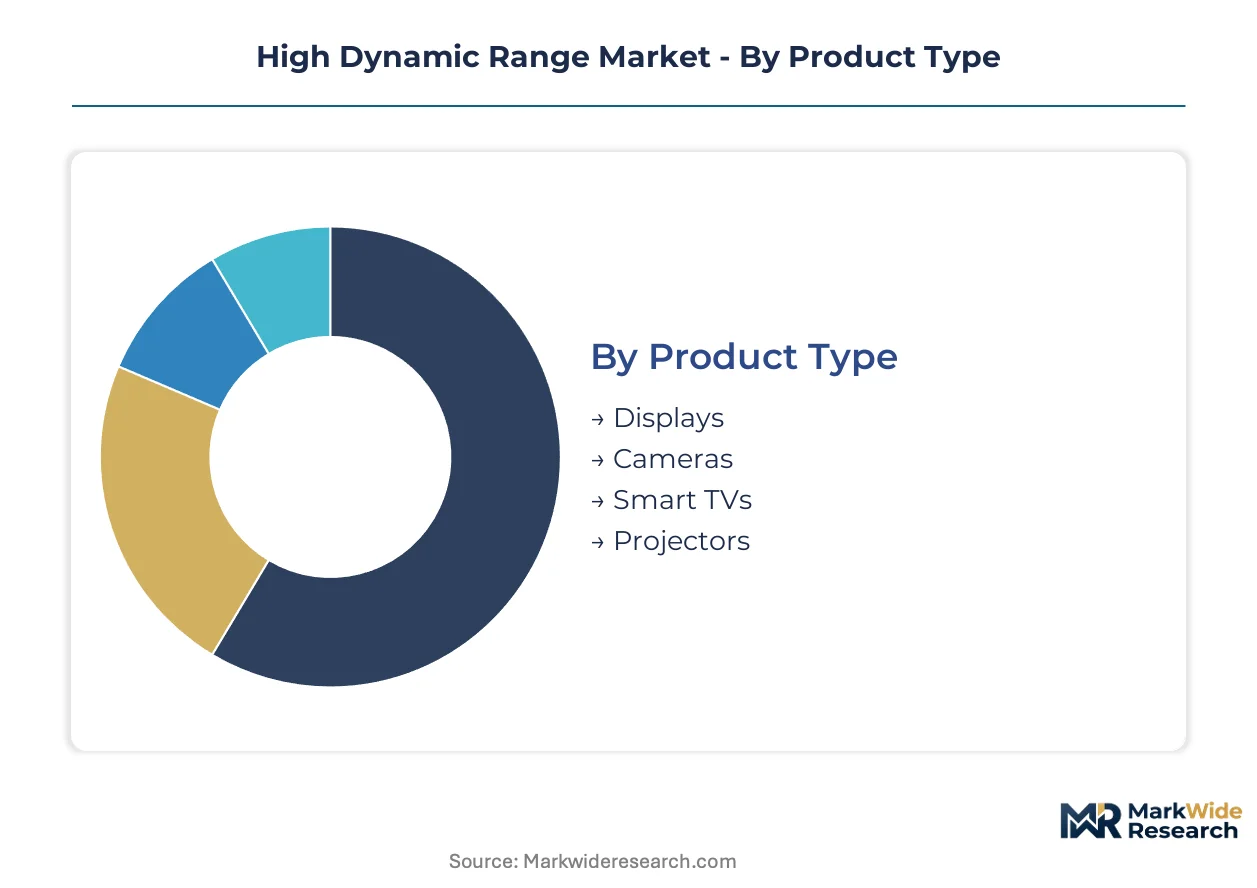
Segmentation in the High Dynamic Range market reveals how certification requirements and content pipelines reshape procurement patterns across hardware tiers. Buyers prioritize ecosystem compatibility over raw specifications, creating distinct value curves within each category.
Product Type:
Purchase decisions hinge on peak luminance targets and certification bundle requirements rather than panel technology alone.
- Smart TVs:Mass-market penetration centers on 1,000-nit edge-lit LED architectures with Dolby Vision or HDR10+ decoding. Netflix and Disney+ streaming mandates pull upgrade cycles forward in gaming households across the United States and South Korea.
- Displays:Professional reference monitors demand 4,000-nit mini-LED backlights with factory calibration protocols. Post-production facilities in Los Angeles and London concentrate procurement for cinema-grade color grading workflows.
- Cameras:Cinema cameras embed dual-native ISO sensors with 15+ stop dynamic range for HDR acquisition.
- Projectors:Laser phosphor light engines achieve 3,000-lumen output with HDR tone mapping for commercial cinema installations.
Volume sits with Smart TVs; growth tilts toward Displays.
Technology:
Licensing cost structures and metadata handling capabilities determine hardware vendor certification strategies.
- Dolby Vision:Dynamic metadata enables frame-by-frame luminance optimization through proprietary perceptual quantizer algorithms. Premium smart TV tiers absorb royalty costs to secure streaming platform compatibility.
- HDR10:Static metadata with royalty-free licensing dominates volume shipments across mid-tier display portfolios. Samsung and LG leverage this standard to avoid per-unit licensing burdens in price-sensitive segments.
- HLG:Broadcast-optimized hybrid log-gamma encoding supports simultaneous SDR and HDR transmission without separate simulcast feeds.
- Advanced HDR:Technicolor and Philips proprietary formats target regional broadcast deployments with customized tone mapping curves.
Deployment concentrates with HDR10; premium positioning favors Dolby Vision.
End User:
Usage intensity and content creation requirements separate procurement specifications across customer types.
- Residential:Living room consumption drives 55-inch and larger screen demand with integrated streaming app ecosystems.
- Commercial:Digital signage and corporate presentation systems require 2,000-nit brightness for ambient light visibility in retail environments.
- Entertainment:Cinema chains and post-production houses specify DCI-P3 color gamut coverage with 1,000-nit minimum sustained brightness.
- Educational:University media labs and broadcast training programs prioritize HLG compatibility for terrestrial signal integration.
Residential absorbs unit volume; Entertainment commands highest per-unit pricing.
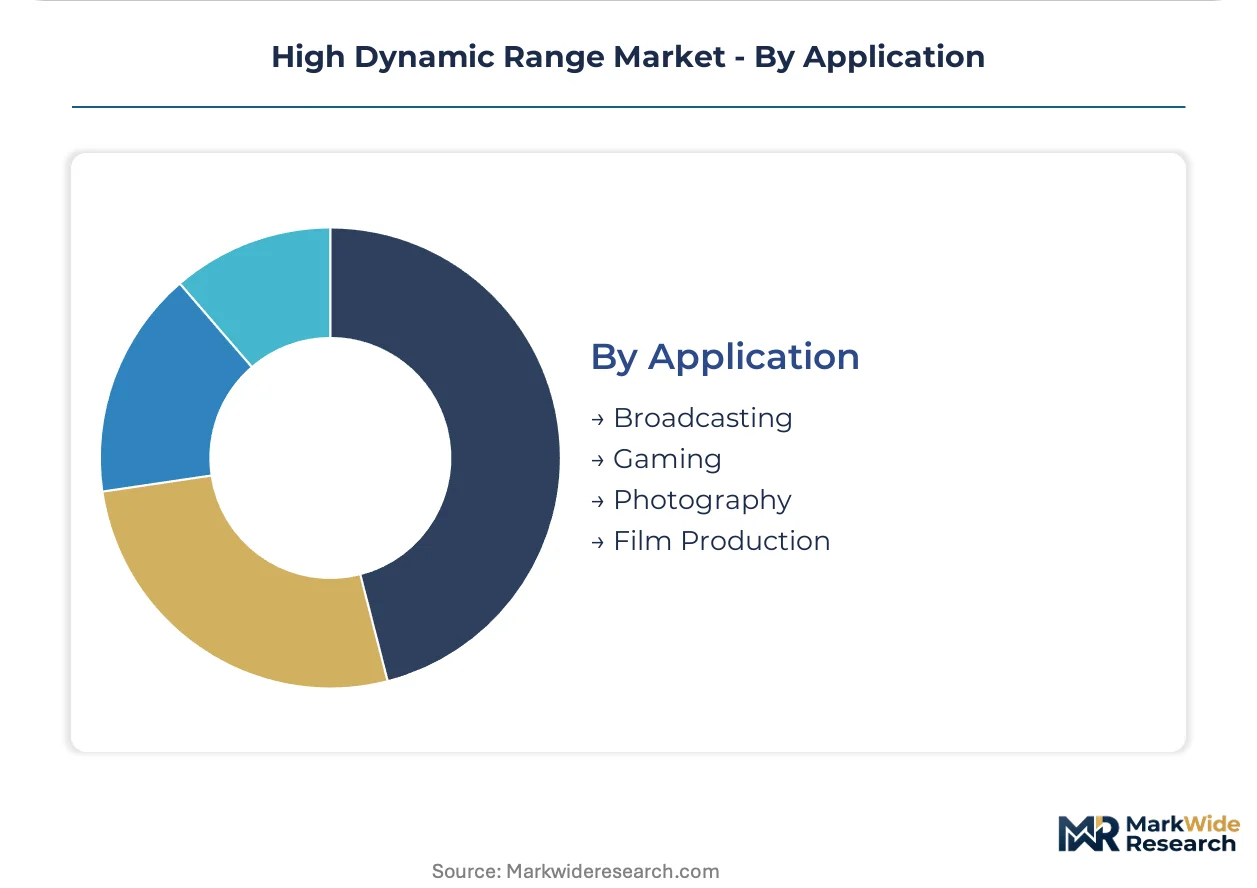
Application:
Content pipeline maturity and hardware refresh cycles create divergent growth trajectories across use cases.
- Gaming:Sony PlayStation and Microsoft Xbox console mandates enforce HDR output across new hardware generations. GPU manufacturers NVIDIA and AMD embed tone mapping hardware in graphics cards for PC gaming.
- Film Production:Virtual production stages with LED volume walls demand real-time HDR rendering for in-camera visual effects.
- Broadcasting:NHK 8K HDR trials in Japan establish transmission protocols influencing equipment procurement across East Asian markets.
- Photography:Mirrorless camera systems capture 14-bit RAW files with extended dynamic range for HDR merging workflows.
Gaming is expanding most quickly; Broadcasting carries longest replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streaming platform infrastructure investments and gaming console penetration concentrate hardware upgrade cycles in South Korea, the United States, and China, while content licensing hubs in Japan and Germany shape certification requirements for export-bound manufacturers.
United States
FCC broadcast transmission standards govern HDR signal distribution across terrestrial and cable networks, mandating compatible receiver architectures. The FCC's regulatory framework shapes equipment procurement for regional broadcast affiliates. Los Angeles post-production clusters concentrate reference monitor demand for cinema-grade color grading workflows.
South Korea
Console gaming penetration and domestic streaming service expansion pull smart TV upgrade cycles forward across metropolitan households. The Korea Communications Commission coordinates 4K/8K broadcast infrastructure deployment timelines. Seoul-based panel makers leverage vertical integration across semiconductor and display supply chains to sustain pricing flexibility in premium tiers.
China
Domestic streaming platform HDR mastering requirements and gaming hardware manufacturing scale drive display panel demand. MIIT standards govern display energy efficiency and broadcast receiver specifications. Shenzhen and Beijing industrial corridors concentrate LED die manufacturing and quantum dot enhancement film processing capabilities.
Japan
METI-coordinated 8K HDR broadcast trials through NHK establish transmission protocols influencing East Asian equipment procurement. The regulator's Super Hi-Vision roadmap mandates HLG metadata carriage in terrestrial signals. Tokyo and Osaka electronics clusters develop integrated tuner-processor SoCs reducing bill-of-materials complexity for export-bound sets.
Germany
EU Ecodesign minimum efficiency thresholds for displays accelerate LED backlight technology transitions in European-bound manufacturing lines. CE marking requirements under the directive realign cost-of-entry calculus for distribution into member states. Berlin and Munich broadcast equipment procurement cycles respond to HLG compatibility mandates in terrestrial signal infrastructure.
High Dynamic Range Market Competitive Environment
South Korean and Japanese producers anchor one tier; Chinese fabricators and audio-technology specialists hold adjacent positions. The vendor base distributes across consolidated panel manufacturing and fragmented content licensing domains. Three archetypes dominate: vertically integrated display conglomerates, proprietary format licensors, and optical component specialists. Capacity expansion in mini-LED backlight architectures and strategic technology licensing partnerships constitute the primary competitive vectors reshaping positioning.
Within the vertically integrated tier, Samsung Electronics and LG Electronics occupy positions exemplifying captive supply chain control from semiconductor through panel assembly. Sony Corporation anchors the proprietary processing silicon segment, representing differentiation through image processing hardware rather than commodity panel specifications. Dolby Laboratories, Inc. sits within the format licensing archetype, its position deriving from royalty-bearing ecosystem control rather than hardware manufacturing scale.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| Canon Inc. |
| Nikon Corporation |
| Fujifilm Holdings Corporation |
| Hisense Group |
| Dolby Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned LED die specialists in Taiwan and South Korea anchor pricing discipline through captive wafer capacity, while their financing structures—heavy on equipment-backed lending—force volume commitments that ripple through downstream panel pricing.
Pricing Analysis
Lead-time-driven pricing separates urgent orders from contracted volumes, with spot inventory clearing at discounts to long-term offtake rates. The dominant structure runs on licensing-royalty hybrids where Dolby Vision certification adds per-unit costs that Samsung and LG absorb in premium tiers but avoid in HDR10-dominant mid-range lines. Price differentiation centers on certification grade and volume scale, with automotive display contracts commanding premiums over consumer retail. Cost compression in edge-lit LED architectures is intensifying as Chinese panel makers BOE and CSOT push dual-layer LCD alternatives. Mid-tier display vendors exhibit highest price sensitivity due to redundant dual-certification burdens.
Supply Chain Analysis
Neodymium and europium supply for quantum dot enhancement films rests on Chinese rare earth processing facilities concentrated in Inner Mongolia and Jiangxi province. LED die manufacturing draws from Taiwanese and South Korean specialty foundries, while phosphor materials feed from Japanese chemical producers. Single-source vulnerability clusters around Chinese rare earth element concentration, exposing panel makers to export restriction risk. Distribution runs through vertically integrated conglomerate channels for premium tiers and specialized broadcast equipment distributors for professional reference monitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign for Energy-related Products Directive erects a compliance moat that favors incumbents with established CE marking pathways and European distribution infrastructure.
For Market Incumbents: Anchor market position through backward integration into mini-LED die manufacturing and exclusive calibration service bundling for post-production houses. Samsung Electronics and LG Electronics should deepen captive supply of quantum dot enhancement films to offset rare earth volatility. Dolby Laboratories must defend its royalty stack against open-standard HDR10+ encroachment by tightening streaming platform exclusivity terms. For New Entrants and Emerging Players: Launch via direct-to-post-house relationships in Berlin, Mumbai, and São Paulo, bypassing regional distributors that incumbents dominate. India's TRAI-mandated 4K set-top box deployment represents the most penetrable geography, with 400 million television households creating first-time HDR upgrade demand. Target automotive cockpit display integration as the go-to-market angle, where Mercedes-Benz and BMW procurement cycles remain less consolidated than consumer retail. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized reference monitor calibration firms in Los Angeles and London clusters, where color science talent scarcity creates durable margin structures. Long-term viability hinges on positioning for cloud gaming edge node procurement as Google Stadia and NVIDIA GeForce NOW infrastructure scales. Watch Dolby Vision-to-HDR10+ adoption ratio shifts as the inflection signal for royalty-dependent versus open-standard hardware profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Mini-LED Capacity Expansion | Chinese panel makers BOE and CSOT are absorbing market share from OLED in commercial signage. |
| Dolby Vision Certification Investment | Streaming platform mandates from Netflix and Disney+ lock in premium tier pricing power. |
| Automotive Display Partnership | Mercedes-Benz and BMW cabin differentiation strategies open HDR cockpit procurement channels. |
| Cloud Gaming Infrastructure Supply | NVIDIA GeForce NOW and Google Stadia edge nodes require enterprise-grade HDR encoding pipelines. |
| India Broadcast Equipment Localization | TRAI-mandated 4K set-top box deployments create first-time upgrade cycles across 400 million households. |
Study Parameters
Independent corroboration across display panel manufacturers, streaming platform technology officers, and post-production facility engineers underwrites the qualitative findings in this study. Primary fieldwork involved structured interviews with LED die procurement leads, color grading suite operators, and broadcast equipment distributors. Secondary validation drew from FCC broadcast standards filings, EU Ecodesign directive documentation, and METI Super Hi-Vision roadmap publications. Bottom-up shipment estimates triangulate against top-down content licensing revenue analysis.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation by product type, technology certification, end-user category, and application intensity. CAGRs derive from installed base replacement cycles, content pipeline maturation curves, and hardware mandate enforcement timelines. Console GPU output requirements and streaming platform HDR mastering normalization constitute key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for dual-layer LCD versus mini-LED transition would alter the outlook for Chinese panel maker competitiveness. Forecasts reflect assumptions around Dolby Vision royalty sustainability and rare earth supply continuity. Regulatory divergence between EU Ecodesign thresholds and FCC broadcast standards, plus patent litigation around perceptual quantizer algorithms, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
SWIR Camera Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Cinematographic Camera Market
Imaging
Photoacoustic Tomography Market
Imaging
Electron Microscopy Market
Imaging
US Near Infrared Imaging Market
Imaging
360-Degree Camera Market
Imaging
North America Digital Camera Market
Imaging
Camera with Flip Screen Market
Imaging
Machine Vision Camera Market
Imaging
Handheld Imager Market
Imaging
Acoustic Microscopy Market
Imaging
Photoconductor Drums Market
Imaging
Facial Recognition Machine Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Brazil Surveillance Analog Camera Market