
 Europe Hyperspectral Imaging Market | 2026-2036
Europe Hyperspectral Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hyperspectral Imaging Market Intelligence
Modular sensor-head configurations is pivoting buyer choice across the European hyperspectral imaging landscape, allowing end users to swap optical components without replacing entire camera systems. Imec leverages its semiconductor foundry partnerships to sustain wafer-level spectral filter production. SPECIM Spectral Imaging Ltd. anchors Nordic defense and forestry contracts through ruggedized pushbroom lines. XIMEA GmbH differentiates via embedded processing architectures that reduce downstream computing loads.
Hyperspectral imaging captures contiguous narrow spectral bands across ultraviolet through shortwave infrared wavelengths, typically spanning 400-2500 nm, to generate pixel-level material signatures for identification and quantification. Pushbroom imaging dominates industrial inline inspection due to its spatial resolution and throughput advantages, while snapshot imaging captures fastest-growing interest in drone-mounted agricultural scouting where platform motion limits dwell time. Software segments concentrate margin pools as analytics layers decouple from hardware commoditization trends.
EMA medical-device frameworks and EU AI Act conformity requirements shape product development timelines for clinical hyperspectral applications, while REACH chemical compliance governs sensor material sourcing. The EU Green Deal's carbon-accounting rules for agriculture redirect subsidy flows toward verified precision-farming technologies. Stakeholders must monitor how CSRD disclosure mandates expand corporate sustainability budgets for environmental monitoring instrumentation.
Market Dynamics
Modular sensor-head architectures are restructuring procurement economics across European hyperspectral imaging, allowing end users to upgrade spectral resolution without full system replacement. This hardware decoupling accelerates refresh cycles while compressing vendor lock-in premiums.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Agricultural subsidy flows now require verified precision-farming technologies, directing public procurement toward drone-mounted spectral scouting systems.
- Industrial automation clusters in Germany:Machine vision integrators in Stuttgart and Munich anchor sensor demand for inline quality inspection across automotive and electronics manufacturing.
- Snapshot imaging technology maturation:Platform motion constraints on agricultural drones favor instantaneous full-frame capture over pushbroom mechanical scanning.
Market Restraints
- Indium gallium arsenide detector costs:Shortwave infrared sensor substrates face price volatility tied to rare earth refining capacity concentrated in East Asian supply chains.
- REACH chemical compliance burdens:ECHA substance restrictions on sensor coatings and adhesives extend qualification timelines for new hardware platforms.
- Computational storage requirements:Raw hyperspectral datacubes demand specialized high-throughput architectures that exclude smallholder agricultural operators.
Strategic Opportunities
- Underpenetrated Nordic forestry monitoring:Sweden and Finland maintain extensive unmanaged woodland where spectral disease detection remains nascent.
- EU AI Act conformity pathways:Clinical diagnostic applications gain accelerated market access through harmonized medical-device and artificial intelligence certification frameworks.
- Edge computing convergence:Embedded spectral processing architectures reduce downstream bandwidth requirements for remote agricultural deployments.
Industry Challenges
- Multispectral algorithm talent scarcity:European universities produce insufficient trained personnel for spectral unmixing and radiometric calibration functions.
- CSRD disclosure timeline compression:Corporate sustainability reporting mandates strain environmental monitoring instrumentation supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hyperspectral Imaging Market |
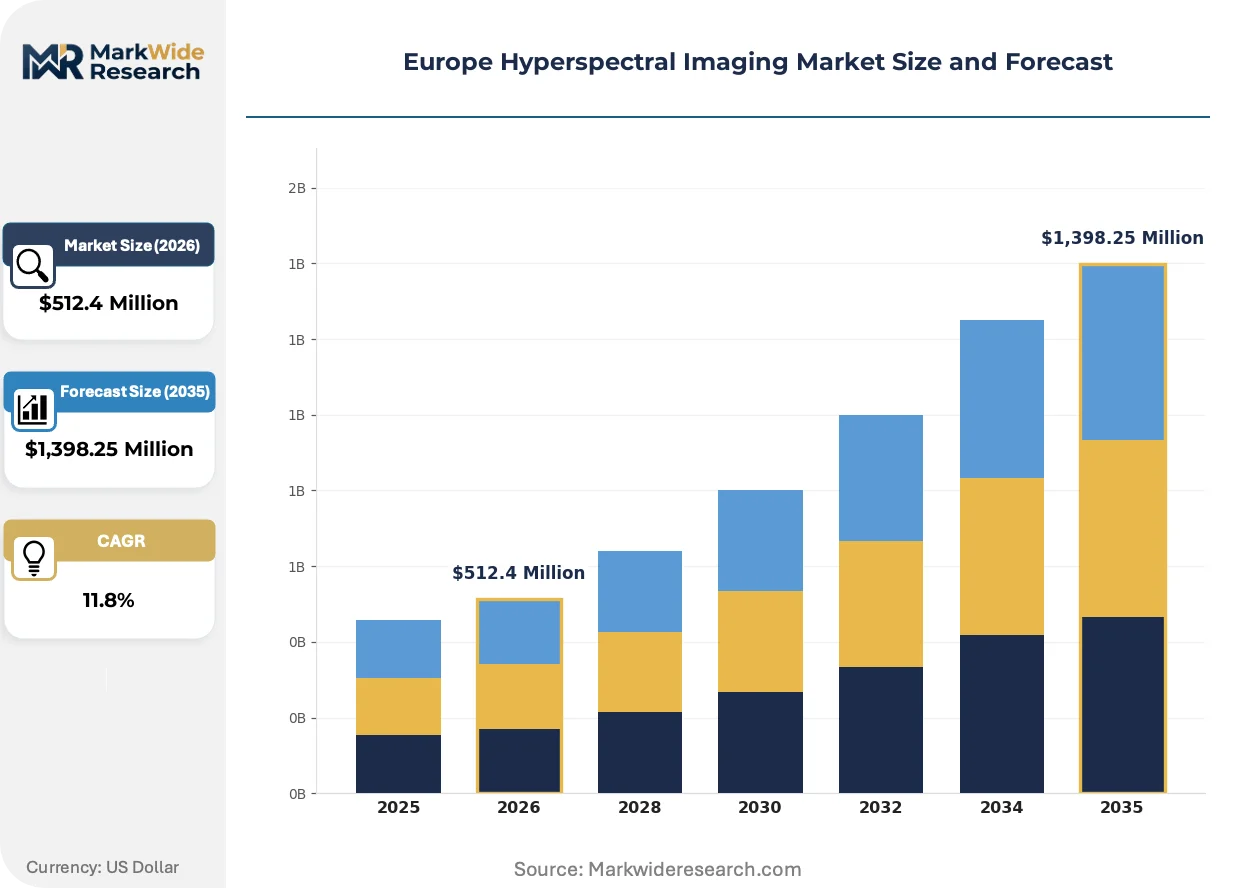
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,398.25 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Software, Accessories End User: Agriculture, Environmental Monitoring, Healthcare, Defense Technology: Snapshot Imaging, Pushbroom Imaging, Tunable Filter, LCD Application: Food Quality Inspection, Mineral Exploration, Disease Detection, Atmospheric Studies |
| Companies Covered | Imec, XIMEA GmbH, Cubert GmbH, SPECIM Spectral Imaging Ltd., Headwall Photonics, Inc., Norsk Elektro Optikk AS, EVK DI Kerschhaggl GmbH, Diaspective Vision GmbH, Corning Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hyperspectral Imaging Market Strategic Shifts & Innovations
Spectral analytics layers are decoupling from hardware commoditization, redirecting value capture toward software-defined material classification. This shift elevates data interpretation capabilities above sensor specification competition.
Snapshot mosaic filter arrays are converging with CMOS readout circuits to enable single-exposure full-spectral capture. Agricultural drone operators in France and the Netherlands adopt these architectures to eliminate motion artifacts during high-speed field surveys. The technology is converging with embedded GPU processing to compress ground-station computing requirements.
EMA medical-device frameworks and EU AI Act conformity requirements are extending product development timelines for clinical hyperspectral applications. Manufacturers must navigate dual certification pathways for diagnostic imaging hardware incorporating machine learning classification. German and Swiss clinical device developers face the steepest compliance cost escalation.
Service unbundling now separates spectral data acquisition from analytics subscriptions. Agricultural cooperatives in Spain and Italy rent drone-mounted sensors while purchasing per-hectare crop health reports from cloud-based interpretation platforms. This model spreads capital burden across growing seasons rather than concentrating upfront hardware expenditure.
Europe Hyperspectral Imaging Market Segmentation
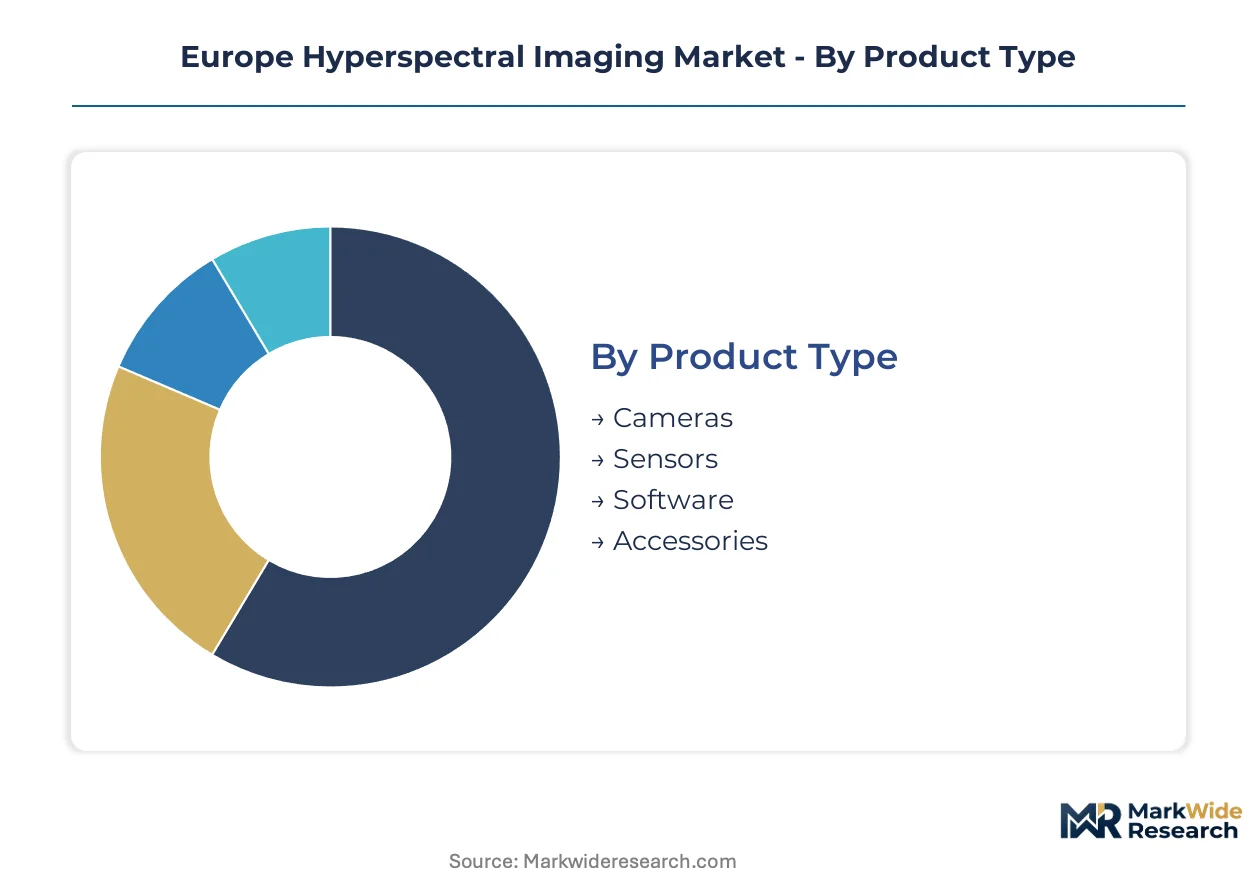
Hyperspectral imaging procurement across Europe fragments across hardware, software, and service layers with distinct upgrade economics. Buyers now prioritize modular architectures that permit spectral resolution improvements without full system replacement, compressing traditional replacement cycles.
Product Type:
Upgrade flexibility varies sharply across product tiers, with sensor-head modularity commanding premium positioning against integrated camera systems.
- Cameras:Integrated camera systems combine optical benches with detector arrays in fixed configurations. German automotive machine vision integrators in Stuttgart and Munich anchor procurement volumes for inline quality inspection lines.
- Sensors:Modular sensor heads permit wavelength range swaps and resolution upgrades without replacing downstream electronics. Precision agriculture operators in France and the Netherlands favor this architecture for seasonal capability expansion.
- Software:Spectral analytics platforms decouple from hardware commoditization, capturing margin pools through subscription-based material classification services.
- Accessories:Calibration targets, mounting hardware, and thermal management components complete system deployments.
Volume placements concentrate in Cameras; the faster expansion belongs to Software.
End User:
Carbon-accounting mandates redirect public subsidy flows toward verified environmental monitoring technologies, reshaping demand concentration across user categories.
- Agriculture:Drone-mounted spectral scouting systems verify crop health, nitrogen stress, and irrigation efficiency for EU Green Deal compliance. Spanish and Italian agricultural cooperatives increasingly adopt rental-plus-analytics service models.
- Environmental Monitoring:Atmospheric composition tracking and water quality assessment drive institutional procurement. Sweden and Finland maintain extensive unmanaged woodland where spectral disease detection remains nascent.
- Healthcare:Clinical diagnostic applications face extended development timelines under EMA medical-device frameworks and EU AI Act conformity requirements. German and Swiss device developers encounter steepest compliance cost escalation.
- Defense:Nordic defense contracts anchor demand for ruggedized pushbroom systems with extended operational temperature ranges.
Revenue concentration sits with Agriculture; Healthcare climbs the fastest as dual certification pathways mature.
Technology:
Platform motion constraints on agricultural drones favor instantaneous capture architectures over mechanical scanning systems.
- Snapshot Imaging:Single-exposure full-spectral capture eliminates motion artifacts during high-speed field surveys. CMOS-integrated mosaic filter arrays converge with embedded GPU processing to compress ground-station computing requirements.
- Pushbroom Imaging:Mechanical scanning delivers spatial resolution and throughput advantages for industrial inline inspection. SPECIM Spectral Imaging Ltd. anchors Nordic defense and forestry contracts through ruggedized product lines.
- Tunable Filter:Acousto-optical and liquid crystal tunable filters enable wavelength-programmable capture without moving parts.
- LCD:Liquid crystal-based spectral selection offers compact form factors for portable and embedded applications.
Installed base dominance rests with Pushbroom Imaging; Snapshot Imaging gains share fastest among new agricultural deployments.
Application:
Material identification requirements vary across end-use contexts, with food safety and mineral discovery commanding distinct spectral range specifications.
- Food Quality Inspection:Contaminant detection and ripeness assessment drive inline deployment across European processing facilities. Shortwave infrared capabilities penetrate packaging materials for non-destructive verification.
- Mineral Exploration:Spectral signatures identify ore bodies and alteration zones for mining sector targeting. Geological survey organizations in Germany and Scandinavia maintain active procurement programs.
- Disease Detection:Early pathogen identification in crops and forests enables targeted intervention before visible symptoms emerge.
- Atmospheric Studies:Trace gas quantification and aerosol characterization support climate research and emissions monitoring networks.
Deployment scale favors Food Quality Inspection; Disease Detection shows steepest expansion trajectory as forestry monitoring penetrates Nordic markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe consumes more hyperspectral imaging systems than it produces, with sensor manufacturing concentrated in Germany, Belgium, and Finland while deployment spreads across agricultural and industrial users from Spain to Sweden. This consumption-production gap shapes cross-border procurement patterns and technology transfer flows.
Germany
Machine vision integrators in Stuttgart and Munich anchor continental demand for inline quality inspection systems across automotive and electronics manufacturing. The EU AI Act and MDR frameworks extend product development timelines for clinical device developers in German and Swiss clusters. Baden-Württemberg's industrial automation corridor concentrates sensor procurement for production line integration.
France
Agricultural cooperatives in the Île-de-France and Nouvelle-Aquitaine regions adopt drone-mounted snapshot imaging for high-speed field surveys. The EU Green Deal's carbon-accounting rules redirect subsidy flows toward verified precision-farming technologies. Bordeaux-based wine producers deploy spectral scouting for vine stress monitoring under sustainability certification programs.
Netherlands
Horticulture operators in the Westland greenhouse cluster integrate hyperspectral sensors for nutrient stress detection in controlled-environment agriculture. REACH compliance burdens from ECHA substance restrictions extend hardware qualification timelines. Wageningen University anchors research procurement for food quality inspection applications.
Sweden
Forestry monitoring remains underpenetrated across extensive unmanaged woodland in Norrland and Svealand regions. The Swedish Forest Agency's climate adaptation programs redirect public procurement toward spectral disease detection systems. SPECIM Spectral Imaging Ltd. anchors Nordic defense contracts through ruggedized pushbroom product lines.
Spain
Olive and citrus cooperatives in Andalusia adopt rental-plus-analytics service models to spread capital burden across growing seasons. CSRD disclosure mandates expand corporate sustainability budgets for environmental monitoring instrumentation. Seville-based agricultural operators pilot edge-computing architectures for remote spectral processing.
Europe Hyperspectral Imaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. The vendor base organizes into three strategic archetypes: semiconductor foundry partners leveraging wafer-level spectral filter production, ruggedized system specialists capturing defense and forestry contracts, and embedded processing architects reducing downstream computing loads. Competitive moves concentrate on modular sensor-head configurations that permit wavelength range swaps without full system replacement, and service unbundling that separates spectral data acquisition from analytics subscriptions.
Within the semiconductor-integrated tier, Imec represents foundry-linked spectral filter production. Among German sensor fabricators, XIMEA GmbH and Cubert GmbH occupy positions in embedded processing and compact spectral imaging architectures. SPECIM Spectral Imaging Ltd. exemplifies the ruggedized system specialist archetype anchoring Nordic defense and forestry procurement.
| Leading Market Players |
|---|
| Imec |
| XIMEA GmbH |
| Cubert GmbH |
| SPECIM Spectral Imaging Ltd. |
| Headwall Photonics, Inc. |
| Norsk Elektro Optikk AS |
| EVK DI Kerschhaggl GmbH |
| Diaspective Vision GmbH |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
Indium gallium arsenide spot price volatility cascades through European hyperspectral imaging supply chains, compressing margins on shortwave infrared sensor tiers while amplifying premium pricing power for vendors with captive semiconductor sourcing. This raw-material cost pressure stratifies procurement economics across modular sensor-head configurations and integrated camera systems.
Pricing Analysis
Margin tightening in mid-tier camera systems reflects indium gallium arsenide substrate cost escalation and REACH compliance qualification burdens. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade calibrated units from agricultural scouting bundles and entry-level laboratory configurations. Pricing pressure stems from East Asian rare earth refining concentration and ECHA substance restriction timelines. Smallholder agricultural operators exhibit highest price sensitivity, while defense procurement channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Sensor refurbishment flows from German automotive machine vision integrators back to XIMEA GmbH and Cubert GmbH service centers extend component lifecycles and compress replacement demand. Manufacturing concentration in Germany, Belgium, and Finland draws from Taiwan semiconductor foundries and Chinese rare earth refineries for detector substrates and optical coatings. Single-source vulnerability in shortwave infrared indium phosphide supply creates exposure to export restriction shocks. Distribution runs through Stuttgart and Munich industrial automation clusters, Wageningen horticulture networks, and Nordic defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snapshot imaging architectures are displacing pushbroom mechanical scanning across European agricultural drone deployments, rewriting competitive positioning for vendors anchored to legacy scanning technologies.
For Market Incumbents: Acquire embedded GPU processing IP to defend against software-defined spectral analytics unbundling. SPECIM Spectral Imaging Ltd.'s ruggedized pushbroom dominance in Nordic defense contracts faces erosion from CMOS-integrated mosaic filter arrays; incumbents must deepen backward integration into wafer-level spectral filter production through foundry partnerships or captive semiconductor capacity in Belgium and Germany.
For New Entrants and Emerging Players: Edge-computing convergence for remote agricultural deployments offers entry leverage against cloud-dependent analytics incumbents. Underpenetrated Swedish and Finnish forestry monitoring presents the most accessible white-space target, with disease detection algorithms for unmanaged woodland commanding premium subscription economics. Agricultural cooperatives in Spain and Italy favor rental-plus-analytics service models, enabling asset-light market penetration without hardware manufacturing scale.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular sensor-head specialists with REACH qualification completion in German industrial automation corridors. Long-term viability hinges on software margin capture decoupled from hardware commoditization trajectories. Watch EU AI Act conformity pathway harmonization with EMA medical-device frameworks as inflection signal for clinical diagnostic application acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Spectral Filter Partnership | Imec's semiconductor foundry relationships anchor cost-competitive CMOS-integrated mosaic production. |
| Edge Computing Architecture Deployment | Embedded GPU processing reduces ground-station bandwidth requirements for French drone operators. |
| REACH Compliance Pre-Certification | ECHA substance restriction adherence accelerates hardware qualification timelines for German automotive integrators. |
| Service Unbundling Launch | Rental-plus-analytics subscriptions spread capital burden across Spanish agricultural cooperative growing seasons. |
| Nordic Defense Contract Capture | Ruggedized pushbroom specifications with extended temperature ranges anchor Swedish Forest Agency procurement. |
Research Approach
Multi-period observation of EU Green Deal subsidy flow redirection and EMA medical-device framework evolution anchored the trend analysis, supplemented by interviews with machine vision integration engineers, precision agriculture operators, biomedical device regulatory leads, spectral algorithm specialists, and defense procurement officers. Secondary validation drew from ECHA substance restriction databases, EU AI Act implementation guidance, CSRD disclosure mandate timelines, and customs records for indium gallium arsenide detector imports. Bottom-up sensor shipment tallies triangulated against top-down agricultural drone deployment estimates.
Input-output matrices mapped snapshot imaging adoption rates, pushbroom installed base depreciation, and software subscription attach rates across the projection horizon. Segmentation dimensions modeled included product type tier, end-use vertical, technology architecture, and regional regulatory cluster. CAGRs derived from technology substitution curves and carbon-accounting mandate compliance deadlines. Forecast inputs incorporated REACH qualification timeline distributions and rare earth refining capacity utilization assumptions.
Several conditions sit outside the modeled scope, including geopolitical export restrictions on shortwave infrared substrates and unannounced EU AI Act conformity pathway revisions. Forecasts reflect documented assumptions about technology maturation schedules and subsidy flow continuity. Practitioners should monitor ECHA substance restriction expansion lists and Nordic defense budget appropriations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Phosphor Screen Scanner Market
Imaging
Hybrid Imaging Market
Imaging
High-Speed Camera Market
Imaging
Mobile Imaging Services Market
Imaging
Handheld Imaging Devices Market
Imaging
Photo Kiosk Market
Imaging
Camera Lens Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
AI Camera Market
Imaging
Pocket Video Camera Market
Imaging
On-Chip Color Filters Market
Imaging
Live Cell Imaging Market
Imaging
Global Whole Slide Imaging Market