
 Live Cell Imaging Market | 2026-2036
Live Cell Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Live Cell Imaging Market Intelligence
Subscription-based image analysis software is expanding the addressable market beyond capital equipment buyers toward recurring-revenue models. Thermo Fisher Scientific leverages its cloud-enabled analytical pipelines to sustain long-term client relationships across distributed research networks. Danaher anchors its position through integrated workflow solutions that span sample preparation through data interpretation. Nikon specializes in high-numerical-aperture objectives that differentiate its systems for demanding super-resolution protocols.
Live cell imaging denotes the continuous observation of biological specimens in physiological conditions using photon-based or electron-based detection systems, typically operating at 37 degrees Celsius with controlled carbon dioxide and humidity to preserve viability. Its primary purpose is capturing dynamic cellular processes—migration, division, signaling—in real time for quantitative biological insight. Fluorescence microscopes occupy the largest installed base owing to decades of established protocol compatibility and fluorophore availability. Super-resolution microscopy represents the fastest-expanding technology segment as researchers pursue sub-diffraction-limit structural detail in living specimens. Pharmaceutical companies constitute the most concentrated margin pool among end users because their procurement cycles prioritize throughput, automation, and regulatory documentation.
The FDA enforces 21 CFR Part 11 compliance for electronic records in GxP environments, compelling vendors to architect audit trails and access controls into imaging platforms. ISO 13485 quality management standards govern instrument design for clinical and diagnostic applications, raising barriers for software-only entrants seeking hardware integration. The EPA maintains oversight of fluorescent dye disposal protocols in institutional settings, shaping reagent selection and waste handling specifications. Stakeholders must monitor how evolving AI-enabled image analysis triggers new regulatory scrutiny around algorithmic validation and clinical decision support claims.
Market Dynamics
Pharmaceutical compound screening workflows are consolidating procurement around integrated platforms that merge imaging hardware with compliant data-integrity modules, compressing vendor selection cycles toward full-stack suppliers.
Growth Catalysts
- 21 CFR Part 11 mandates:FDA electronic records requirements force imaging software vendors to embed audit trails and access controls, creating upgrade cycles across installed fluorescence microscope bases in GxP environments.
- Super-resolution microscopy protocols:Sub-diffraction-limit structural detail demand pulls research institutions toward high-numerical-aperture objective investments, expanding the technology's addressable use cases.
- NIH funding priorities:Sustained federal research budgets in the United States maintain instrument procurement velocity through biotechnology clustering in Boston, San Diego, and Research Triangle Park.
Market Restraints
- Fluorophore input cost volatility:Specialized fluorescent dye synthesis depends on rare earth element supply chains concentrated in China, creating margin pressure for reagent-dependent workflows.
- ISO 13485 certification barriers:Quality management standards for clinical instrument design raise capital requirements for software-only entrants seeking hardware integration partnerships.
- Electron microscopy substitution threat:Cryo-electron techniques capture comparable structural detail in fixed specimens for certain applications, constraining live-cell pricing power in structural biology segments.
Strategic Opportunities
- Cloud-enabled analytical pipelines:Distributed research networks across multinational pharmaceutical operations create demand for subscription-based image analysis software with centralized data repositories.
- EU AI Act compliance services:Algorithmic validation requirements for clinical decision support claims open advisory revenue streams for vendors embedding explainable AI modules in imaging platforms.
- Biomanufacturing process analytical technology:Cell therapy production facilities in Singapore and South Korea adopt real-time viability monitoring, extending live-cell imaging from R&D into GMP environments.
Industry Challenges
- Computational microscopy skill gaps:Super-resolution image reconstruction and deconvolution algorithm operation require specialized bioimage informaticists, constraining deployment velocity at mid-tier research institutions.
- Legacy LIMS integration complexity:Laboratory information management systems from the 2010s lack API architectures for modern imaging metadata streams, forcing costly middleware development.
- Phototoxicity protocol standardization delays:Absence of cross-platform illumination dosage metrics complicates multi-site reproducibility studies, fragmenting best-practice consensus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Cell Imaging Market |
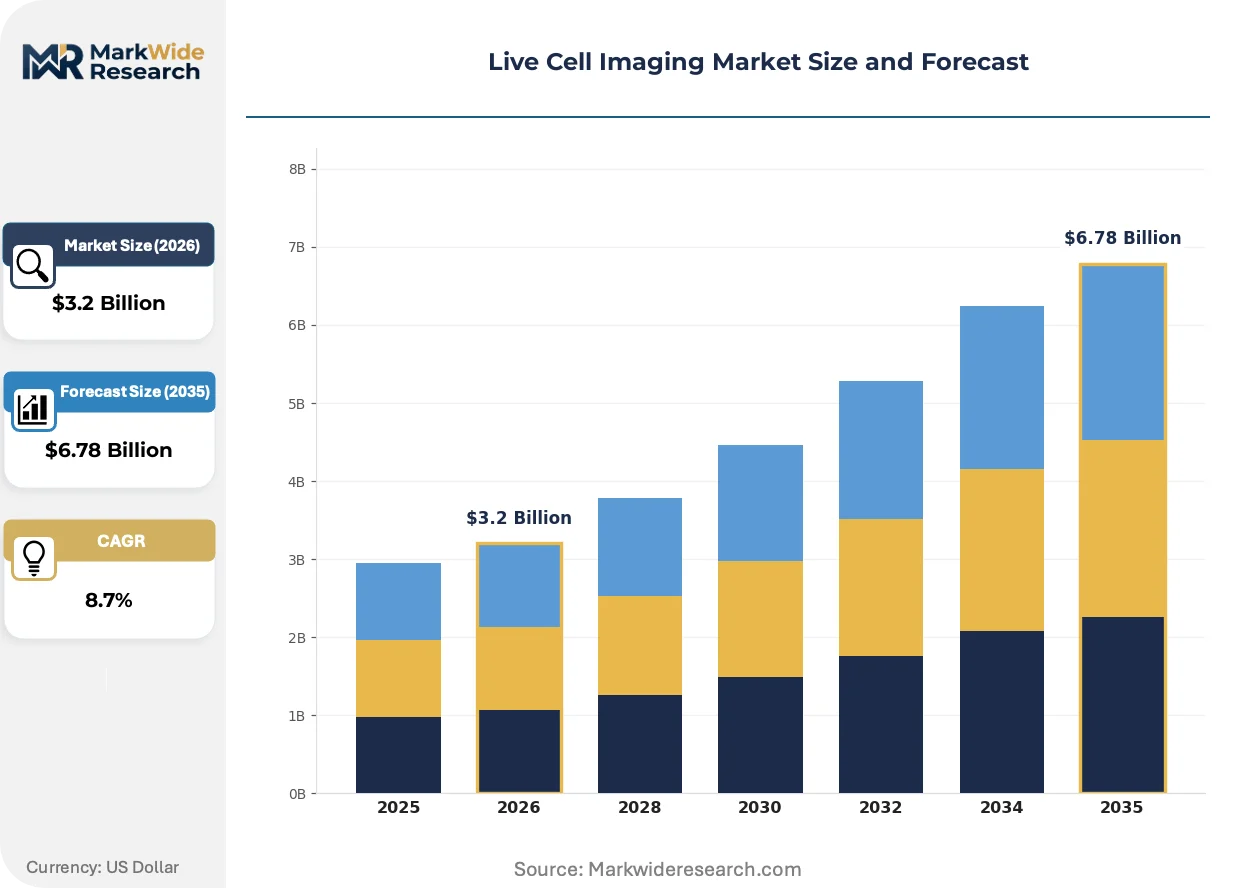
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Microscopes, Electron Microscopes, Image Analysis Software, Optical Systems Application: Cell Biology, Drug Discovery, Cancer Research, Neuroscience End User: Academic Research Institutes, Pharmaceutical Companies, Hospitals, Clinical Laboratories Technology: Confocal Microscopy, Super-Resolution Microscopy, Light Sheet Microscopy, Intracellular Imaging |
| Companies Covered | Sartorius AG, Olympus Corporation, Thermo Fisher Scientific Inc., Revvity, Inc., Nikon Corporation, Danaher, Agilent Technologies, Inc., Merck KGaA, ZEISS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Cell Imaging Market Strategic Shifts & Innovations
Live cell imaging is transitioning from standalone hardware procurement toward integrated workflow ecosystems where software subscription layers capture recurring value and regulatory compliance becomes a product feature rather than an afterthought.
Light-sheet microscopy is expanding into developmental biology and organoid research applications through its capacity for rapid volumetric imaging with reduced photodamage. Pharmaceutical discovery groups at Merck and Roche adopt the technology for high-content phenotypic screening campaigns. The approach is compressing time-to-data for longitudinal cell lineage tracing studies, displacing slower confocal methods in demanding specimens.
REACH regulation amendments on per- and polyfluoroalkyl substances are restricting certain mounting media and immersion oil formulations used in high-resolution objectives. European microscopy core facilities face requalification costs for alternative reagents with equivalent refractive indices. German and Dutch research institutes accelerate supplier audits to secure compliant supply chains before enforcement deadlines.
Academic core facilities increasingly unbundle instrument access from technical service contracts, shifting toward self-service booking platforms with usage-based billing. The model disrupts traditional full-service support relationships that bundled maintenance, training, and data interpretation. This behavioral shift concentrates in United States research universities facing indirect cost rate pressures and demands for higher instrument utilization metrics.
Live Cell Imaging Market Segmentation
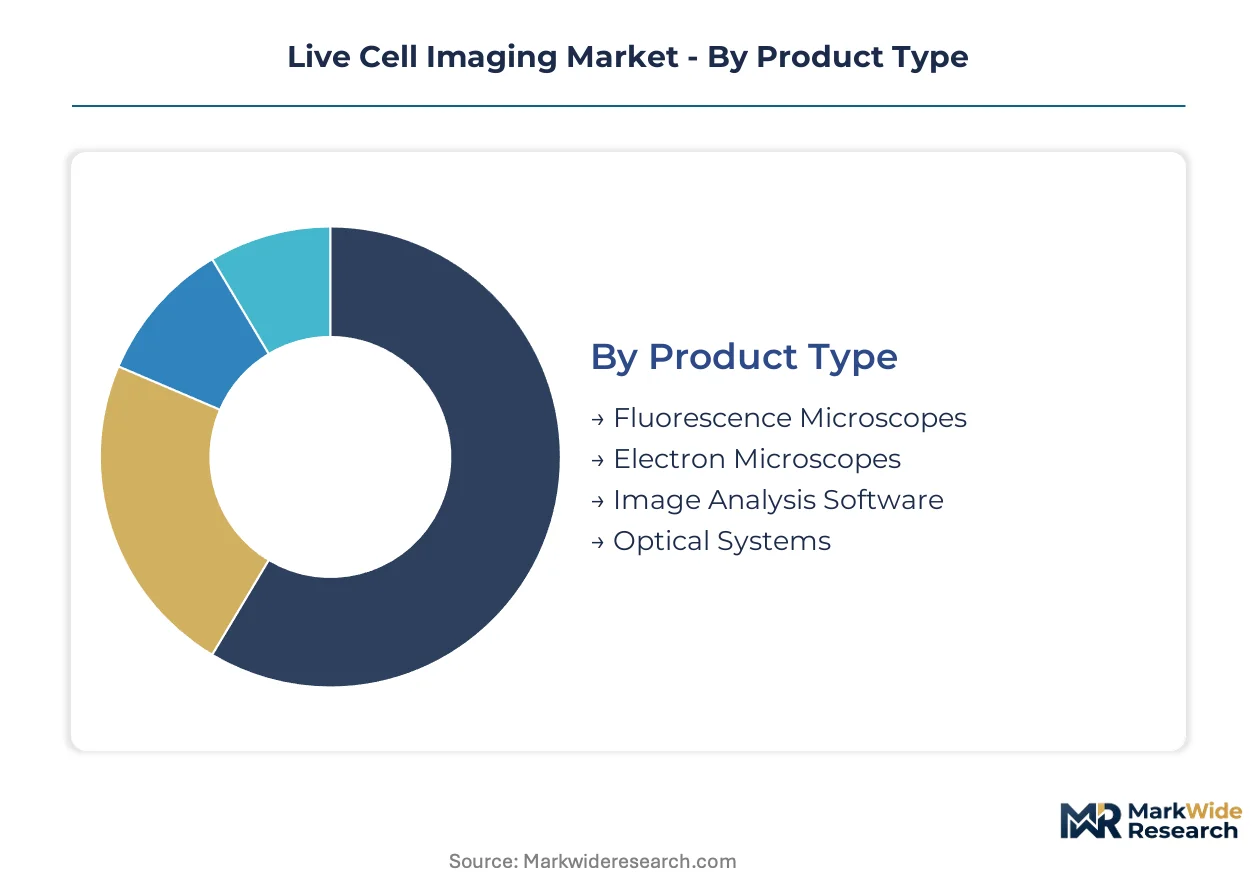
Live cell imaging market segmentation reveals distinct procurement patterns across hardware, software, and service layers. Technology choices cascade through application requirements and end-user compliance obligations, creating non-overlapping vendor ecosystems.
Product Type:
Volume concentration sits in fluorescence microscope installations, while premium capture concentrates in integrated optical systems with embedded analytical modules.
- Fluorescence Microscopes:These systems utilize arc lamp or LED illumination combined with filter-based wavelength selection for multi-channel specimen visualization. Academic core facilities in the United States sustain replacement cycles through NIH instrumentation grants, though phototoxicity concerns constrain longitudinal imaging protocols.
- Electron Microscopes:Transmission and scanning configurations deliver nanometer-scale structural resolution for fixed specimens, with live-cell variants emerging through environmental chamber innovations. Pharmaceutical structural biology groups in Germany and Switzerland balance these investments against cryo-EM substitution risks for certain protein characterization workflows.
- Image Analysis Software:Cloud-native platforms with subscription licensing expand recurring revenue beyond capital equipment sales.
- Optical Systems:Modular components including detectors, stages, and environmental controllers enable custom instrument assembly.
Mature deployment sits with fluorescence microscopes. Newer deployment is concentrated in image analysis software with regulatory-compliant audit architectures.
Application:
Commercial intensity varies sharply: drug discovery commands premium pricing for throughput-automation integration, while cell biology sustains volume through academic procurement.
- Cell Biology:Fundamental research applications span organelle dynamics, cytoskeletal reorganization, and intercellular signaling pathway visualization. European Research Council funding in France, Germany, and the Netherlands maintains baseline instrument demand, though budget fragmentation across national systems complicates multi-site standardization.
- Drug Discovery:High-content screening campaigns require plate-based automation, kinetic readouts, and GxP-compliant data lineage. Merck and Roche operations in Basel and Boston drive specifications for 384-well format compatibility and integrated compound library management.
- Cancer Research:Tumor spheroid and patient-derived organoid imaging demands specialized penetration depth and hypoxia monitoring capabilities.
- Neuroscience:Brain slice and in vivo preparations require motion correction and deep-tissue imaging optimizations.
Revenue concentration clusters in drug discovery. Steepest expansion trajectory appears in cancer research through immuno-oncology cell therapy manufacturing integration.
End User:
Procurement authority separates capital equipment buyers from recurring service subscribers, with pharmaceutical procurement cycles compressing vendor selection toward full-stack compliance.
- Academic Research Institutes:Core facility models with usage-based billing displace traditional full-service contracts. United States universities facing indirect cost pressures in Massachusetts and California accelerate this transition toward self-service platforms.
- Pharmaceutical Companies:Integrated workflow requirements spanning screening through lead optimization prioritize vendors with 21 CFR Part 11 pre-validated software architectures. FDA inspection readiness drives consolidation around established suppliers with quality management documentation.
- Hospitals:Clinical pathology and intraoperative imaging applications demand ISO 13485 certified instruments with diagnostic labeling.
- Clinical Laboratories:Reproductive medicine and infectious disease diagnostics represent emerging adoption vectors.
Established purchasing volume resides with academic institutes. Fastest share gains occur in pharmaceutical companies through GxP environment expansion.
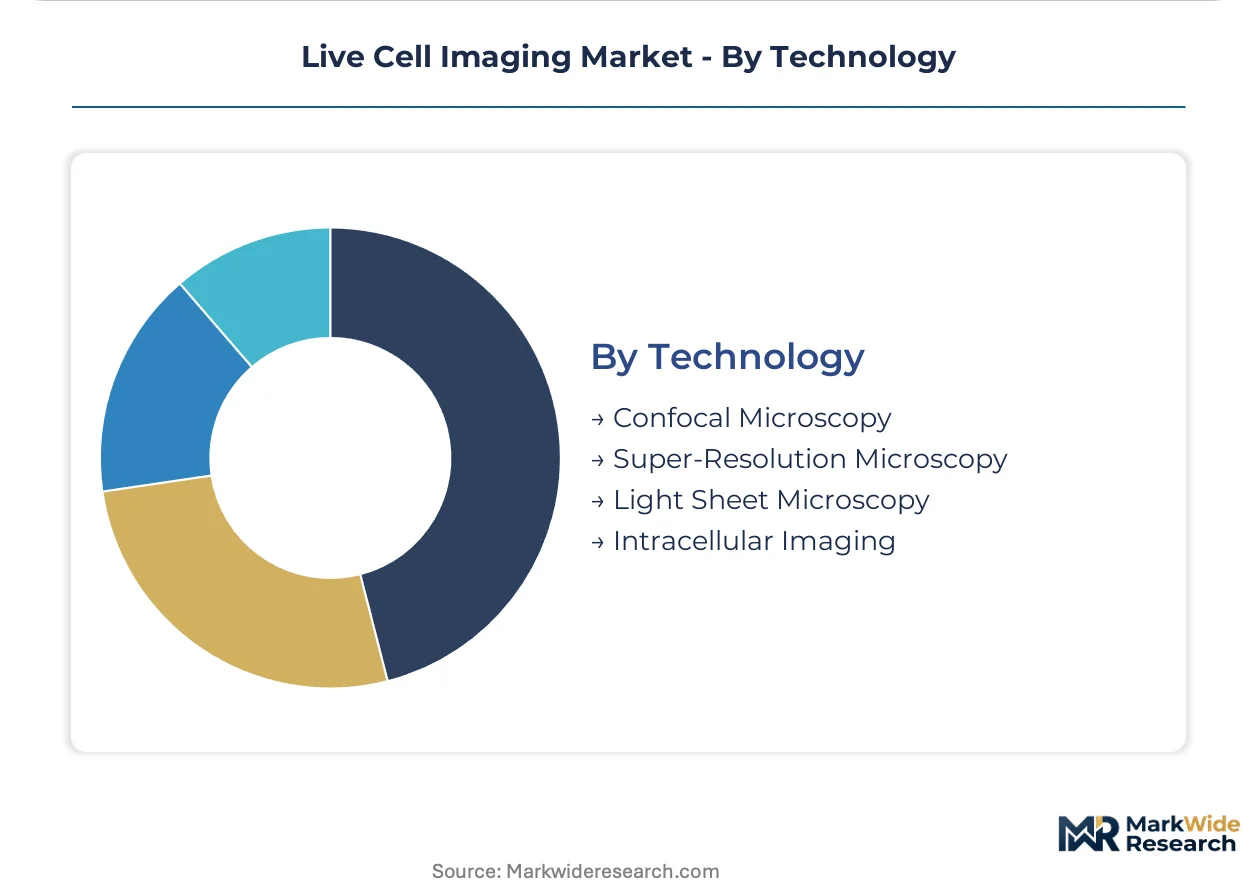
Technology:
Resolution-performance tradeoffs define adoption: confocal methods dominate routine applications while super-resolution protocols capture premium research budgets.
- Confocal Microscopy:Laser scanning and spinning disk variants provide optical sectioning for 3D reconstruction with moderate photodamage profiles. Institutional core facilities in Japan and South Korea maintain extensive installed bases serving routine cell culture quality control.
- Super-Resolution Microscopy:STED, PALM, STORM, and MINFLUX implementations break diffraction limits for single-molecule localization. Howard Hughes Medical Institute Janelia Research Campus and European Molecular Biology Laboratory sites in Heidelberg and Barcelona anchor demand for specialized technical staffing.
- Light Sheet Microscopy:Selective plane illumination enables rapid volumetric imaging with reduced phototoxicity for developmental specimens.
- Intracellular Imaging:Biosensor and genetically encoded indicator approaches track ion concentrations and protein interactions in real time.
Confocal systems represent the largest installed base. Light sheet microscopy exhibits the steepest adoption curve through organoid and developmental biology protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing concentrates in Germany and Japan, while consumption gravity pulls toward the United States and China where pharmaceutical R&D spending and academic research budgets sustain procurement velocity.
United States
NIH instrumentation grants and biotechnology clustering in Boston and San Diego drive fluorescence microscope replacement cycles. FDA 21 CFR Part 11 enforcement compels vendors to embed audit trails into imaging software for GxP environments. Merck and Roche operations in the Northeast anchor demand for high-content screening platforms with integrated compound library management.
Germany
European Research Council funding and precision optics manufacturing heritage sustain super-resolution microscopy development. REACH regulation amendments on per- and polyfluoroalkyl substances restrict mounting media formulations, forcing requalification of alternative reagents. Heidelberg and Munich host dense concentrations of academic core facilities and pharmaceutical research centers specifying ISO 13485 certified instruments.
China
Domestic biopharmaceutical expansion and cell therapy manufacturing investments accelerate live-cell platform procurement. NMPA quality management standards for clinical applications raise certification barriers for imported instruments. Shanghai and Suzhou biotechnology parks anchor demand for automated imaging systems in contract research organizations serving multinational sponsors.
Japan
Spinning disk confocal installed bases in institutional core facilities and environmental chamber innovations for electron microscopy sustain technology development. METI funding for advanced imaging infrastructure supports academic-industry collaboration programs. Osaka and Tokyo metropolitan areas concentrate pharmaceutical discovery groups and precision equipment manufacturers.
Singapore
Cell therapy production facilities and biomanufacturing process analytical technology adoption extend live-cell imaging from R&D into GMP environments. The country's national biomedical regulator maintains alignment with FDA and EMA quality standards for clinical manufacturing. Biopolis research cluster anchors demand for real-time viability monitoring systems in regenerative medicine applications.
Live Cell Imaging Market Key Industry Players
Capital-heavy optical system manufacturers compete with asset-light analytical software developers for recurring revenue streams in live cell imaging workflows. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with full-stack compliance capabilities, specialized microscopy houses with precision optics heritage, and cloud-native software entrants seeking hardware integration partnerships. Consolidation pressure intensifies as pharmaceutical procurement cycles compress vendor selection toward integrated platform suppliers. Dominant competitive moves include strategic partnerships between instrument makers and AI-enabled analysis providers, plus backward integration into reagent portfolios to secure margin capture.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher exemplify the full-stack compliance archetype through cloud-enabled analytical pipelines and integrated workflow solutions. Nikon Corporation and ZEISS Group occupy positions within the precision optics heritage tier, differentiated by high-numerical-aperture objective specialization. Sartorius AG represents the bioprocess integration vector, extending live-cell monitoring from discovery into manufacturing environments.
| Leading Market Players |
|---|
| Sartorius AG |
| Olympus Corporation |
| Thermo Fisher Scientific Inc. |
| Revvity, Inc. |
| Nikon Corporation |
| Danaher |
| Agilent Technologies, Inc. |
| Merck KGaA |
| ZEISS Group |
| Others |
Cost & Logistics Intelligence
Rare earth element price indices for europium and terbium—critical fluorophore precursors—cascade through live cell imaging supply chains into three-tier pricing structures across premium, standard, and economy instrument levels. Pharmaceutical GxP procurement absorbs premium tier inflation through compliance-embedded contracts, while academic buyers face sharper trade-offs between hardware performance and reagent operating costs.
Pricing Analysis
Cost compression in economy-tier fluorescence microscopes intensifies as Chinese OEMs expand objective lens manufacturing capacity. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by ISO 13485 certification status and embedded 21 CFR Part 11 software validation. Academic research institutes exhibit highest price sensitivity, deferring upgrades when NIH instrumentation grant cycles tighten. Pharmaceutical companies accept premium pricing for pre-validated compliance architectures that compress FDA inspection preparation timelines.
Supply Chain Analysis
Precision optics manufacturing workforce availability in Germany and Japan constrains high-numerical-aperture objective production expansion. Supply chains draw from rare earth element concentrates in China, specialized glass substrates in Japan, and precision motion stages in Germany. Single-source vulnerability concentrates in Chinese fluorophore intermediate synthesis, exposing margin stability to export licensing volatility. Distribution runs through authorized dealer networks for capital equipment and direct SaaS provisioning for cloud-native analysis platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA 21 CFR Part 11 electronic records mandates erect barrier-to-entry moats favoring incumbent vendors with pre-architected audit trail capabilities.
For Market Incumbents: Deploy backward integration into fluorescent dye portfolios to secure margin capture against Chinese supply volatility. Integrate AI-enabled image analysis modules with explainable algorithm architectures ahead of EU AI Act enforcement timelines. Cryo-electron microscopy substitution in structural biology segments threatens live-cell pricing power in German and Swiss pharmaceutical accounts. For New Entrants and Emerging Players: Enter via cloud-native image analysis software with subscription licensing, bypassing capital-intensive hardware certification barriers. Target mid-tier academic core facilities in South Korea and Singapore where self-service platform adoption outpaces full-service incumbent relationships. Position around light-sheet microscopy protocol support for organoid research workflows underserved by established confocal vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light analytical software developers with FDA pre-submission documentation in United States biotechnology clusters. Long-term viability hinges on GMP environment expansion into cell therapy manufacturing quality control. Watch NMPA certification timeline acceleration in China as inflection signal for import substitution pressure on Western instrument makers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Pre-Validation | FDA 21 CFR Part 11 embedded audit trails compress pharmaceutical procurement cycles toward compliant vendors. |
| Backward Integration into Reagents | Captive fluorophore supply secures margin stability against rare earth element price volatility from China. |
| Cloud-Native Platform Expansion | Subscription analytics extend recurring revenue beyond capital equipment sales across distributed research networks. |
| AI Algorithm Explainability Investment | EU AI Act compliance services open advisory revenue streams for clinical decision support positioning. |
| GMP Environment Penetration | Cell therapy manufacturing quality control extends live-cell imaging from R&D into bioprocess analytical technology. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this live cell imaging market analysis. Primary interviews with microscopy core facility directors, pharmaceutical discovery group leaders, regulatory affairs specialists, and biomedical imaging software architects combined with FDA 510(k) databases, NIH RePORTER grant records, EMA quality guideline documents, and import-export statistics. Bottom-up instrument shipment tracking and top-down research budget allocation analysis triangulated market sizing across hardware, software, and service revenue layers.
Segmentation granularity modeled technology choices at confocal-super-resolution-light sheet resolution tiers, end-user procurement authority at academic-pharmaceutical-clinical laboratory levels, application intensity at drug discovery-cell biology-cancer research segments, and geographic regulatory clusters at FDA-EMA-NMPA jurisdiction boundaries. CAGRs derived from instrument replacement cycle analysis, funding trajectory projections, and compliance-driven upgrade elasticity estimates. Industry-specific forecast inputs incorporated phototoxicity protocol standardization delays and legacy LIMS integration complexity constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorophore supply disruption scenarios or accelerated cryo-EM substitution in structural biology. Forecasts reflect documented assumptions regarding NIH funding continuity, REACH regulation enforcement timelines, and pharmaceutical R&D budget allocation stability. Material deviation in rare earth element export licensing, AI regulatory framework finalization, or cell therapy manufacturing scale-up trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Thermal Imaging Systems Market
Imaging
Global Automotive Imaging Market
Imaging
Virtual Reality Camera Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Global Whole Slide Imaging Market
Imaging
Mobile Camera Module Market
Imaging
Compact Camera Module Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Video Processing Solutions Market
Imaging
Multimodal Imaging Market
Imaging
Global Mobile Image Sensor Market
Imaging
Gige Camera Market
Imaging
Frame Grabber Market
Imaging
Global Document Scanner Market
Imaging
Pico Projector Market
Imaging
Widefield Imaging Systems Market