
 Agricultural Films and Bonding Market | 2026-2036
Agricultural Films and Bonding Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Films and Bonding Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for agricultural film manufacturers serving European growers. ExxonMobil Corporation leverages its integrated polyethylene supply chain to sustain cost advantages across mulch and silage film lines. BASF SE anchors its position through specialized biodegradable polymer grades that navigate tightening EU single-use plastics rules. Berry Global Inc. competes on blown film manufacturing scale, controlling distribution networks across North American agricultural belts.
Agricultural films and bonding encompasses thermoplastic polymer sheeting and adhesive systems engineered to thickness tolerances between 50 and 200 microns, manufactured through blown or cast extrusion processes with UV stabilizer packages for 12- to 48-month field durability. These materials regulate soil temperature, moisture retention, and crop microclimate to extend growing seasons and improve yield consistency. Mulch films dominate volume consumption across row-crop applications, while greenhouse films command premium positioning due to multi-layer coextrusion requirements for light diffusion and thermal retention. Biodegradable material grades represent the fastest-expanding segment as regulatory deadlines phase out conventional polyethylene in specific EU member states.
The EPA governs agricultural chemical containment standards that influence film specifications in US specialty crop regions, while China's MEE enforces plastic pollution action plans affecting domestic film manufacturing emissions profiles. India's BIS certifies polyethylene film dimensional stability for monsoon-season vegetable production, shaping import requirements for foreign suppliers. Stakeholders must monitor how cascading biodegradability certification requirements across multiple jurisdictions will reshape raw material sourcing decisions and capital allocation for extrusion asset upgrades.
Market Dynamics
The EU Green Deal's plastics sustainability mandates are compressing the viable material set for agricultural film producers. Manufacturers must requalify entire product lines around bio-based feedstocks while maintaining field durability specifications.
Growth Catalysts
- Intensive horticulture clusters:China's Shandong Province concentrates commercial vegetable production under protected cultivation systems. Film consumption per hectare exceeds national averages by significant multiples.
- REACH compliance consolidation:The EU chemical regulatory framework elevates cost-of-entry for film manufacturers. Incumbent suppliers with established registration portfolios capture displaced volume from non-compliant competitors.
- Multi-layer coextrusion advances:Greenhouse film specifications now demand thermal retention layers combined with light diffusion additives. Premium positioning follows technical performance differentiation.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin constitutes the dominant cost input for conventional film grades. Price swings in naphtha and natural gas liquids compress margin predictability for extrusion operators.
- Biodegradability certification timelines:Industrial composting standards vary across EU member states. Fragmented approval pathways delay product launches and freeze capital allocation decisions.
- Mechanical recycling contamination:Soil-buried mulch films accumulate pesticide and heavy metal residues. Technical barriers to closed-loop recovery limit circular economy claims.
Strategic Opportunities
- Carbon farming incentive schemes:The EU Common Agricultural Policy rewards soil carbon sequestration practices. Biodegradable mulch films that eliminate tillage disruption align with payment eligibility criteria.
- Precision agriculture integration:Sensor-enabled films that transmit soil moisture data are converging with variable-rate irrigation systems. Early deployments concentrate in California specialty crop regions.
- Extended field durability packages:UV stabilizer formulations targeting 48-month service life address high-altitude Andean cultivation zones. Reduced replacement frequency improves total cost-of-ownership positioning.
Industry Challenges
- Polymer formulation talent scarcity:Biodegradable resin compounding requires expertise spanning enzymatic degradation kinetics and process rheology. Educational pipelines lag commercial demand acceleration.
- Extrusion asset reconfiguration:Bio-based polymers exhibit distinct melt flow characteristics versus conventional polyethylene. Capital deployment for screw design and cooling line modifications strains mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Films and Bonding Market |
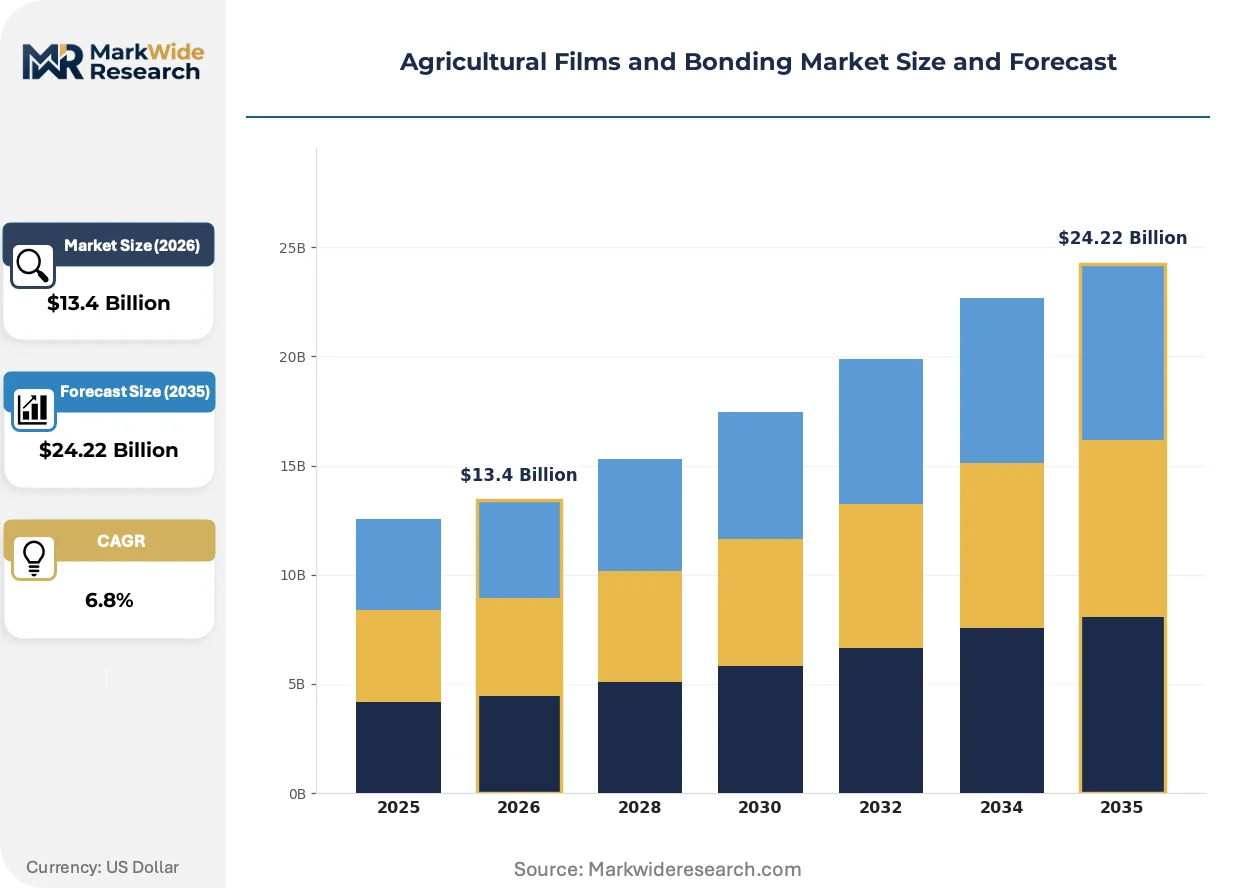
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $24.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulch Films, Greenhouse Films, Silage Films, Shrink Films Material: Polyethylene, Polypropylene, Biodegradable, PVC Application: Crop Protection, Soil Enhancement, Harvesting, Packaging End User: Agricultural Producers, Retailers, Distributors, Contractors |
| Companies Covered | ExxonMobil Corporation, BASF SE, Berry Global Inc., Armando Alvarez Group, AB Rani Plast, Trioplast Industrier AB, Novamont S.p.A., RKW Group, Plastika Kritis S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Films and Bonding Market Emerging Trajectories
Material science advances and regulatory deadline compression are redefining competitive positioning in agricultural film supply. Technical differentiation now determines margin capture across application segments.
Multilayer barrier films incorporating ethylene-vinyl alcohol copolymers are converging with oxygen-sensitive high-value crop protection requirements. Berry vegetable growers in the Netherlands and Belgium adopt these specifications for modified-atmosphere cultivation tunnels. The technology is compressing acceptable permeability thresholds and disqualifying single-layer commodity alternatives from premium greenhouse contracts.
The EU F-Gas Regulation phase-down timeline is accelerating thermal retention layer innovation in greenhouse films. Manufacturers reformulate infrared-blocking additives to maintain performance without fluorinated gas blowing agents. Mediterranean horticulture belts in Spain and Italy face the most acute compliance deadlines, driving accelerated qualification programs for alternative foam-core insulation laminates.
Direct contracting between film converters and large-scale grower cooperatives is displacing distributor-mediated procurement in North American row-crop regions. Volume commitments spanning multiple growing seasons lock in capacity allocation and stabilize input cost pass-through mechanisms. The Corn Belt and California Central Valley exhibit the most pronounced consolidation of purchasing decision authority.
Agricultural Films and Bonding Market Segmentation
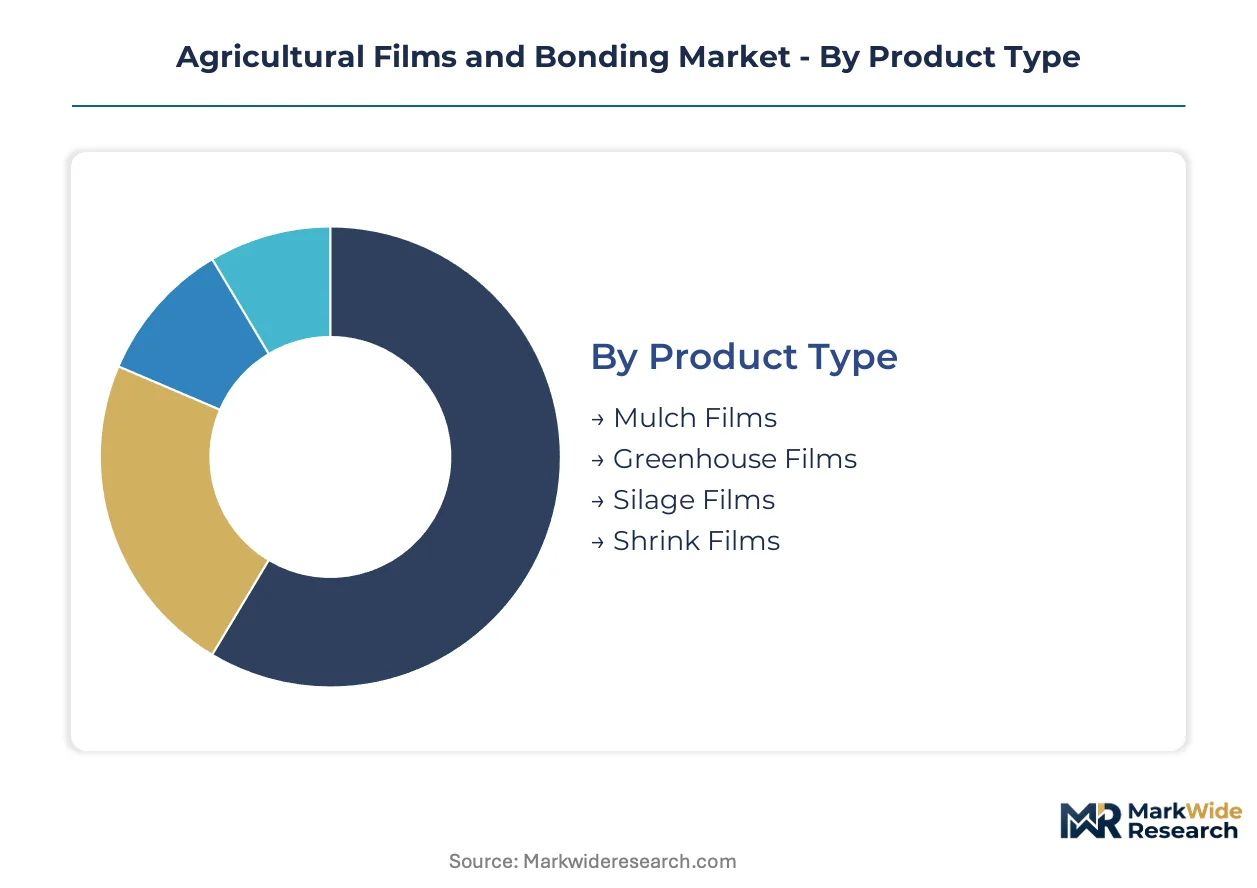
Film thickness tolerances, UV stabilizer packages, and biodegradability certifications fragment procurement decisions across agricultural value chains. Segment boundaries increasingly blur as multi-layer coextrusion converges mulch durability with greenhouse thermal performance in single product platforms.
Product Type:
Volume concentration separates commodity row-crop applications from premium protected cultivation systems requiring multi-year service life.
- Mulch Films:These 15-50 micron polyethylene sheets regulate soil temperature and suppress weed competition across vegetable and fruit row crops. China's Shandong Province consumes disproportionate volumes where intensive horticulture clusters drive replacement cycles every 6-12 months.
- Greenhouse Films:Multi-layer coextruded constructions incorporating ethylene-vinyl alcohol copolymers and light diffusion additives command technical premiums. Mediterranean growers in Spain and Italy face compressed F-Gas Regulation timelines that accelerate thermal retention layer innovation.
- Silage Films:Oxygen barrier specifications protect anaerobic fermentation in forage preservation. Dairy operations in Germany and the Netherlands specify 150-200 micron constructions with 24-month UV resistance.
- Shrink Films:Bundling applications for haylage and palletized produce require balanced shrink force and puncture resistance. Distribution networks across the US Corn Belt standardize around 80-120 gauge specifications.
Today's leader: Mulch Films. Tomorrow's challenger: Greenhouse Films.
Material:
Feedstock chemistry determines compliance pathways across diverging regulatory jurisdictions.
- Polyethylene:Linear low-density and high-density grades dominate conventional film extrusion through established blown film infrastructure. ExxonMobil's integrated supply chain sustains cost positioning across North American agricultural belts despite naphtha feedstock volatility.
- Biodegradable:PLA-PHA copolymer blends and starch-based compounds navigate EU single-use plastics phase-out deadlines. BASF's specialized polymer grades capture premium positioning as industrial composting standards consolidate across member states.
- Polypropylene:Biaxially oriented constructions serve high-strength netting and woven ground cover applications. India's BIS dimensional stability certifications shape import requirements for monsoon-season vegetable production.
- PVC:Rigid formulations persist in select greenhouse structural applications and irrigation tubing. REACH compliance burdens constrain European deployment versus alternative thermoplastics.
Polyethylene retains volume dominance. Biodegradable grades climb the fastest as regulatory deadlines compress.
Application:
Functional requirements separate field-installed systems from post-harvest handling equipment.
- Crop Protection:Insect netting, anti-hail films, and frost protection covers extend growing seasons in high-altitude Andean zones. UV stabilizer packages targeting 48-month durability reduce replacement frequency and improve total cost-of-ownership.
- Soil Enhancement:Moisture retention films and fumigation barriers align with EU Common Agricultural Policy carbon farming incentives. Biodegradable mulch eliminates tillage disruption that would otherwise disqualify payment eligibility.
- Harvesting:Mechanical aid films for fruit collection and field drying of grains serve specialty crop regions in California and Italy.
- Packaging:Modified-atmosphere films for fresh produce distribution converge with oxygen-sensitive berry protection requirements in the Netherlands and Belgium.
Soil Enhancement commands capital allocation. Crop Protection offers the steepest expansion trajectory from precision agriculture integration.
End User:
Purchasing authority concentrates as direct contracting displaces distributor intermediation.
- Agricultural Producers:Large-scale grower cooperatives in the US Corn Belt and California Central Valley lock in multi-season volume commitments. Sensor-enabled films transmitting soil moisture data are converging with variable-rate irrigation systems.
- Distributors:Regional inventory positions face margin compression from manufacturer-direct relationships. Technical support capabilities differentiate surviving intermediaries.
- Retailers:Garden center and farm supply chains serve smallholder segments with standardized SKU portfolios.
- Contractors:Installation services for greenhouse construction and large-scale mulching operations require project-scale procurement relationships.
Agricultural Producers dictate specifications. Contractors gain influence through turnkey system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer formulation specialists cluster around Shandong Province's intensive horticulture belt and Germany's industrial chemical corridors. These talent concentrations anchor regional supply capabilities for conventional and biodegradable film grades.
China
Shandong Province's commercial vegetable growers consume disproportionate mulch film volumes per hectare. The MEE enforces plastic pollution action plans that reshape domestic manufacturing emissions profiles. Qingdao and Weifang host extrusion facilities serving the intensive horticulture clusters driving replacement cycles every 6-12 months.
Germany
Dairy operations in Lower Saxony specify 150-200 micron silage films with 24-month UV resistance. REACH compliance elevates cost-of-entry for manufacturers serving European growers. The Rhine-Ruhr industrial corridor anchors BASF's specialized biodegradable polymer production navigating EU single-use plastics rules.
United States
California Central Valley specialty crop regions deploy sensor-enabled films transmitting soil moisture data. The EPA governs agricultural chemical containment standards influencing film specifications. Direct contracting between converters and grower cooperatives concentrates purchasing authority across the Corn Belt and Pacific Coast production zones.
Spain
Mediterranean greenhouse operators face compressed F-Gas Regulation timelines for thermal retention layer innovation. The EU Green Deal's plastics sustainability mandates redirect procurement toward bio-based alternatives. Almería's concentrated protected cultivation systems drive multi-layer coextrusion demand for light diffusion and thermal performance.
India
Monsoon-season vegetable production in Maharashtra and Gujarat requires polyethylene films certified for dimensional stability. BIS certification shapes import requirements for foreign suppliers. Pune and Ahmedabad host distribution networks standardizing around 80-120 gauge shrink film specifications for palletized produce handling.
Agricultural Films and Bonding Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and application segments. The vendor base separates into three tiers: integrated petrochemical majors controlling resin supply, specialized biodegradable polymer developers, and regional blown film converters. Strategic moves concentrate on extrusion asset reconfiguration for bio-based polymer processing and direct contracting with large-scale grower cooperatives displacing distributor intermediation.
Within the integrated petrochemical tier, ExxonMobil Corporation and BASF SE exemplify divergent positioning strategies. ExxonMobil anchors cost advantages through captive polyethylene supply chains sustaining position across commodity mulch and silage lines. BASF occupies the specialized biodegradable grade segment where enzymatic degradation kinetics expertise commands premium positioning. Berry Global Inc. represents the scale-driven converter archetype, with blown film manufacturing assets controlling distribution access across North American agricultural production belts.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| BASF SE |
| Berry Global Inc. |
| Armando Alvarez Group |
| AB Rani Plast |
| Trioplast Industrier AB |
| Novamont S.p.A. |
| RKW Group |
| Plastika Kritis S.A. |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's plastics sustainability mandates gate qualified supply and premium-tier pricing access. REACH compliance elevates cost-of-entry for manufacturers serving European growers, while bio-based feedstock requalification compresses margins for non-compliant competitors.
Pricing Analysis
Film procurement splits between bundled installation services and unbundled material-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects UV stabilizer package durability and biodegradability certification grade. Price differentiation centers on multi-layer coextrusion complexity versus commodity polyethylene grades. Pricing pressure stems from ethylene feedstock volatility, with large-scale grower cooperatives in the US Corn Belt and California Central Valley exhibiting lowest price sensitivity due to volume commitment structures.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns serving intensive horticulture clusters. Resin supply draws from integrated petrochemical corridors in the Rhine-Ruhr, Shandong Province, and the US Gulf Coast. Extrusion assets depend on naphtha and natural gas liquids, with bio-based polymer melt flow characteristics requiring screw design modifications. Single-source vulnerability concentrates in specialty UV stabilizer additive packages. Distribution runs through direct converter-to-cooperative contracts displacing traditional agricultural supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in agricultural films and bonding rests on biodegradable grade premium capture and ethylene feedstock cost compression through long-term offtake structures.
For Market Incumbents: Hedge resin cost exposure through captive polyethylene supply chains or backward integration into bio-based feedstock cultivation. Lock multi-season volume commitments with Shandong Province and California Central Valley grower cooperatives before distributor displacement accelerates. Prioritize extrusion asset reconfiguration for PLA-PHA copolymer processing to defend positioning against EU single-use plastics phase-out deadlines. For New Entrants and Emerging Players: Launch via direct-to-cooperative contracting models in India's Maharashtra and Gujarat monsoon-season vegetable belts where BIS certification gaps create procurement friction. Target biodegradable mulch film segments in Mediterranean horticulture zones facing compressed F-Gas Regulation timelines. Pursue precision agriculture integration partnerships for sensor-enabled moisture transmission films in Andean high-altitude cultivation zones. For Investors and Strategic Acquirers: Roll-up economics work for regional blown film converters because direct contracting concentration is displacing distributor intermediation and fragmenting local market share. Target mid-tier extrusion operators with installed cooling line capacity suitable for bio-based polymer modification. Watch industrial composting standard consolidation across EU member states as inflection indicator for biodegradable grade margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock | BASF's enzymatic degradation expertise anchors premium positioning under REACH compliance deadlines. |
| Extrusion Asset Reconfiguration | Screw design and cooling line modifications enable PLA-PHA copolymer processing for EU Green Deal alignment. |
| Direct Cooperative Contracting | Volume commitments spanning multiple growing seasons stabilize input cost pass-through for Corn Belt operators. |
| Precision Agriculture Integration | Sensor-enabled films transmitting soil moisture data converge with California Central Valley variable-rate irrigation systems. |
| Extended UV Durability Development | 48-month stabilizer packages address high-altitude Andean replacement frequency and improve total cost-of-ownership positioning. |
Methodological Framework
Multiple input streams — extrusion plant manager interviews, downstream grower cooperative procurement leads, distribution channel partner assessments, and regulatory affairs specialists — were reconciled against secondary validation. Primary fieldwork encompassed polyethylene resin procurement directors, biodegradable polymer R&D heads, and agricultural extension officers across Shandong Province, Lower Saxony, and the California Central Valley. Secondary sources included customs and trade data, EPA agricultural chemical containment filings, ECHA REACH registration databases, and MEE plastic pollution action plan disclosures. Bottom-up volume modeling triangulated against top-down resin consumption estimates.
Data-stream reconciliation across product type, material grade, application function, and end-user purchasing authority dimensions structured the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic agricultural output projections. Industry-specific forecast inputs incorporated ethylene feedstock price scenario modeling and EU biodegradability certification timeline assumptions across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene feedstock volatility spikes and fragmented industrial composting standard delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market