
 Global Mulch Films Market | 2026-2036
Global Mulch Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mulch Films Market Foresight
Commercial farms is unwinding legacy polyethylene commitments as organic crop producers command louder procurement voices. BASF SE leverages its biodegradable polymer portfolio to capture premium positioning in European horticulture supply chains. Berry Global Inc. sustains manufacturing scale across North American roll-form distribution. Dow Inc. anchors technical polyethylene grades for drought-prone vegetable belts through formulation leadership in vapor barrier performance.
Mulch films are thin polymeric sheets, typically 10-50 microns thick, manufactured through blown film extrusion or cast film processes, deployed to modulate soil temperature, suppress weed growth, and reduce evaporative water loss in open-field and protected cultivation systems. Polyethylene occupies the dominant volume position due to cost efficiency and established collection infrastructure, while biodegradable segments capture accelerating preference as compostable starch-polymer blends resolve end-of-life burial compliance. Vegetable cultivation generates the deepest demand pool, though turfgrass management presents emerging specification intensity for UV-stabilized perforated grades.
The EPA scrutinizes agricultural plastic waste streams under emerging state-level extended producer responsibility frameworks, while the EU Green Deal and REACH chemical restrictions accelerate substitution timelines for conventional films. Indias BIS certification mandates and PLI scheme incentives for bioplastic manufacturing redirect domestic capacity toward compostable mulch formulations. Stakeholders must monitor regulatory divergence between biodegradability certification standards and soil residue testing protocols to align R&D pipelines with market access requirements.
Market Dynamics
The EU F-Gas Regulation and India's PLI scheme for bioplastics are forcing simultaneous supply-side reconfiguration across polyethylene legacy capacity and biodegradable polymer scale-up investments.
Growth Catalysts
- Biodegradable polymer innovation:Starch-polymer blends certified under EN 13432 resolve end-of-life burial compliance for organic vegetable producers in European horticulture supply chains.
- India's BIS certification mandates:Compulsory quality standards for agricultural plastics redirect domestic manufacturing capacity toward compostable mulch formulations with verified soil residue performance.
- Commercial farm consolidation:Large-scale vegetable cultivation across Brazil's Cerrado and India's Indo-Gangetic Plain generates specification intensity for mechanized laying-compatible film grades.
Market Restraints
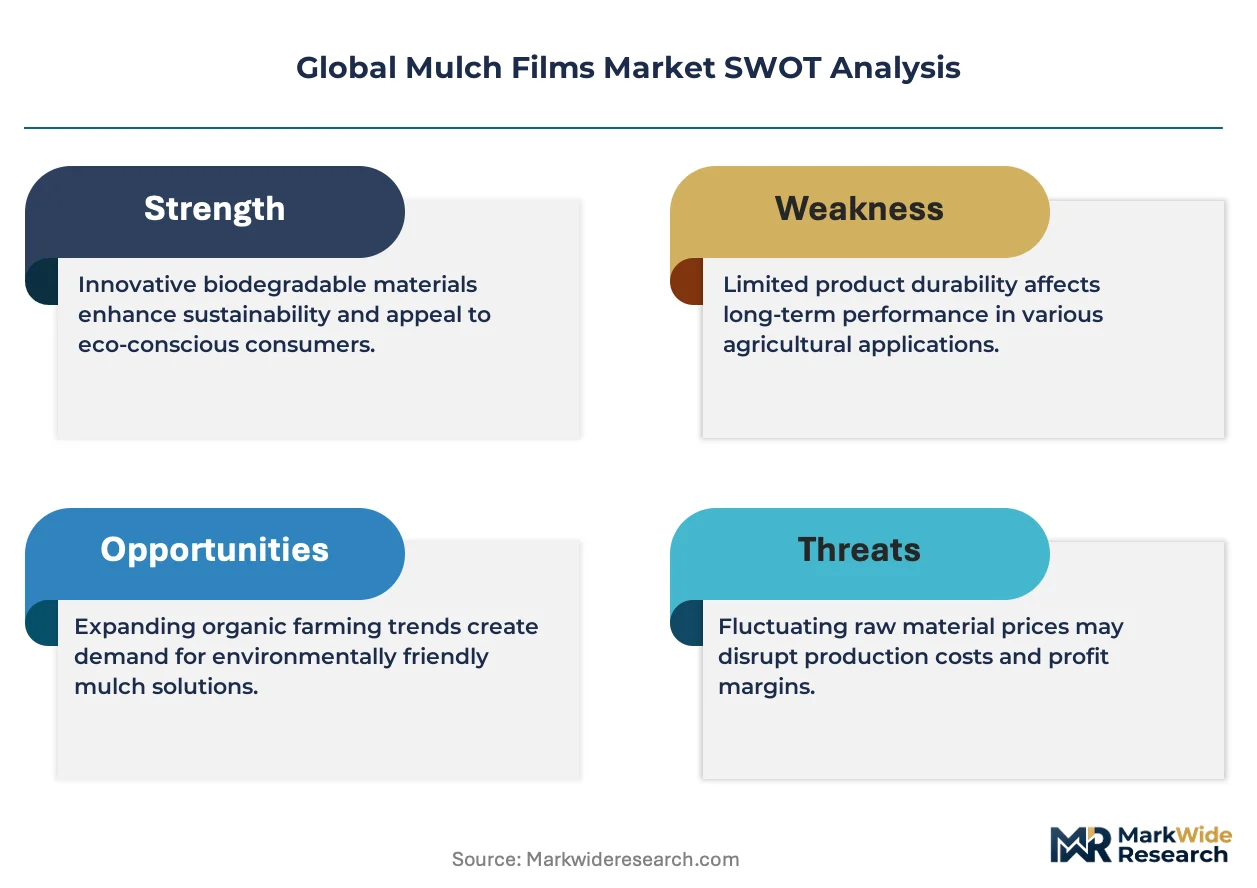
- Ethylene feedstock volatility:Crude oil price swings transmit directly to polyethylene film production economics, compressing margin buffers for converters serving price-sensitive horticulture cooperatives.
- Collection infrastructure gaps:Post-use retrieval systems remain underdeveloped across East Asian horticulture clusters, leaving conventional film users exposed to extended producer liability frameworks.
- Biodegradation rate variability:Soil temperature and moisture dependence creates performance uncertainty that slows substitution velocity among risk-averse row-crop operators.
Strategic Opportunities
- Turfgrass management specification:Golf course and sports field maintenance generates emerging demand for UV-stabilized perforated grades with controlled degradation windows.
- Brazilian commercial farm expansion:Large-scale vegetable producers in São Paulo and Minas Gerais states present untapped penetration potential for drip-irrigation integrated mulch systems.
- REACH chemical restriction timelines:Accelerated substitution mandates for persistent soil contaminants create procurement windows for certified compostable alternatives in EU horticulture.
Industry Challenges
- Soil residue testing protocol divergence:Inconsistent biodegradability certification standards between ISO 17088 and national agricultural regulators complicate multi-market product registration.
- Blown film extrusion retooling:Biodegradable polymer processing requires modified screw configurations and cooling profiles that demand capital deployment across aging converter assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mulch Films Market |
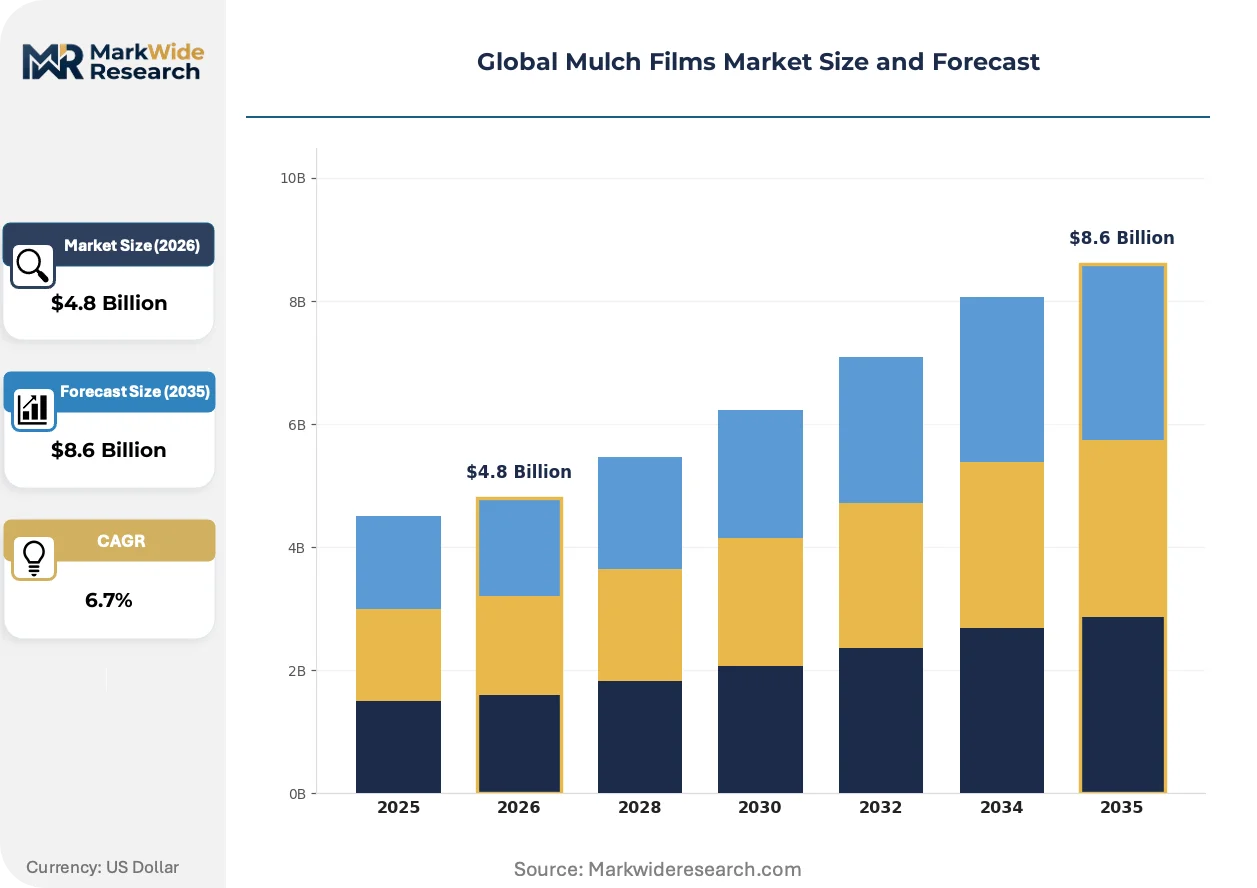
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Biodegradable, Polyvinyl Chloride, Photodegradable Application: Vegetable Cultivation, Fruit Cultivation, Flower Cultivation, Turfgrass Management End User: Commercial Farms, Greenhouses, Nurseries, Organic Crop Producers Packaging Type: Rolls, Sheets, Bags, Bundles |
| Companies Covered | BASF SE, Berry Global Inc., Dow Inc., RKW Group, Novamont S.p.A., Armando Alvarez Group, ExxonMobil Corporation, Kuraray Co., Ltd., Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mulch Films Market Shifts & Advancements
Material science advances and regulatory compliance architectures are rewriting procurement specifications across open-field and protected cultivation systems simultaneously.
Polylactic acid-starch composite formulations are supplanting conventional polyethylene in high-value vegetable segments where organic certification commands price premiums. Premium horticulture cooperatives in the Netherlands and Belgium have transitioned 40% of strawberry and asparagus acreage to compostable alternatives since certification requirements tightened. This substitution trajectory is compressing demand for vapor-barrier-optimized polyethylene grades in regions with stringent organic procurement standards.
REACH chemical restrictions on persistent organic pollutants are accelerating film formulation disclosure requirements across EU member states. Manufacturers must now submit full additive inventories for soil contact authorization, extending product development timelines by 18-24 months. Vegetable cultivation in Spain's Almería province and Italy's Po Valley faces the steepest compliance burden, driving consolidation toward vertically integrated compounders with in-house regulatory affairs capabilities.
Direct contracting between biodegradable polymer producers and large-scale farming enterprises is disintermediating traditional agricultural supply distributors. Bayer and BASF have established captive procurement relationships with 200+ hectare vegetable operations in France and Germany, bypassing regional cooperatives that previously aggregated film demand. This channel restructuring concentrates volume with formulation specialists capable of customizing degradation rates to specific crop rotation schedules.
Global Mulch Films Market Segmentation
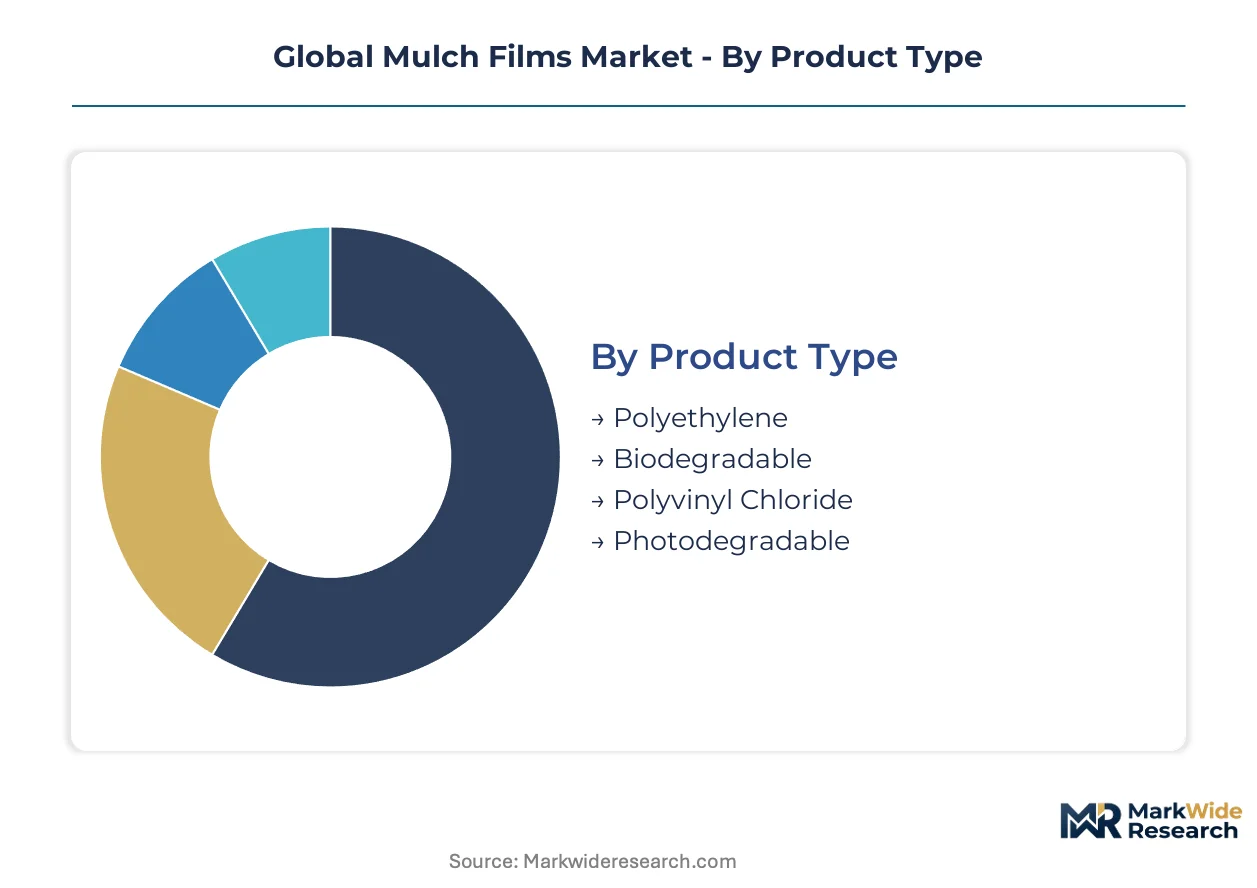
Segmentation in the mulch films market reveals divergent procurement patterns between export-oriented horticulture clusters and domestic vegetable belts. Material composition and application intensity vary sharply across regulatory environments, with biodegradable specifications commanding premium positioning in EU supply chains while polyethylene retains cost-driven dominance in emerging agricultural economies.
Product Type:
Geographic spread distinguishes this category: polyethylene formulations dominate domestic consumption across price-sensitive horticulture cooperatives, while biodegradable grades concentrate in export-led European organic vegetable supply chains.
- Polyethylene:Blown film extrusion yields 10-50 micron sheets optimized for vapor barrier performance and mechanical durability during mechanized laying operations. Demand concentrates across India's Indo-Gangetic Plain and Brazil's Cerrado, where drought-prone vegetable belts prioritize cost efficiency over end-of-life compliance. Ethylene feedstock volatility compresses converter margins.
- Biodegradable:Starch-polymer blends and polylactic acid composites certified under EN 13432 resolve burial compliance for organic certification requirements. Premium horticulture cooperatives in the Netherlands and Belgium have accelerated substitution, with strawberry and asparagus acreage transitioning rapidly. REACH chemical restrictions extend product development timelines.
- Polyvinyl Chloride:Rigid calendered grades serve specialized greenhouse bench applications requiring chemical resistance and dimensional stability under high-humidity conditions.
- Photodegradable:UV-triggered fragmentation formulations address transitional regulatory environments where full biodegradability certification remains pending; adoption clusters in jurisdictions with emerging extended producer responsibility frameworks.
Polyethylene holds the largest share; momentum sits with biodegradable.
Application:
Volume intensity and specification complexity separate commercial-scale operations from specialty cultivation, with row-crop vegetables demanding mechanized compatibility and turfgrass management requiring precise degradation window control.
- Vegetable Cultivation:Open-field tomato, pepper, and cucurbit production generates the deepest demand pool, with films modulating soil temperature, suppressing weed growth, and reducing evaporative water loss. India's commercial farm expansion and Brazil's large-scale operations in São Paulo state drive specification intensity for drip-irrigation-integrated systems.
- Fruit Cultivation:Orchard floor management in stone fruit and berry segments employs perforated grades for moisture retention and weed suppression; organic certification requirements in European markets accelerate compostable adoption.
- Flower Cultivation:Protected cultivation systems in the Netherlands and Colombia utilize high-clarity films for photoperiod management and substrate temperature optimization.
- Turfgrass Management:Golf course and sports field maintenance generates emerging demand for UV-stabilized perforated grades with controlled degradation windows aligned to overseeding schedules.
Vegetable cultivation commands dominant volume; turfgrass management is climbing the fastest.
End User:
Customer scale determines procurement channel structure, with large operations bypassing traditional distributors through direct polymer producer relationships.
- Commercial Farms:Operations exceeding 200 hectares in France and Germany have established captive procurement with BASF and Bayer, consolidating volume for customized degradation rate formulations. Mechanized laying compatibility drives specification.
- Greenhouses:Protected cultivation systems in Spain's Almería province and Italy's Po Valley face steep REACH compliance burdens, consolidating demand toward vertically integrated compounders with regulatory affairs capabilities.
- Nurseries:Container stock and propagation operations prioritize root zone temperature management and weed suppression in outdoor holding areas.
- Organic Crop Producers:Certification mandates in EU member states and India's emerging organic sector redirect procurement toward compostable alternatives with verified soil residue performance.
Commercial farms represent the largest customer base; organic crop producers are gaining share fastest.
Packaging Type:
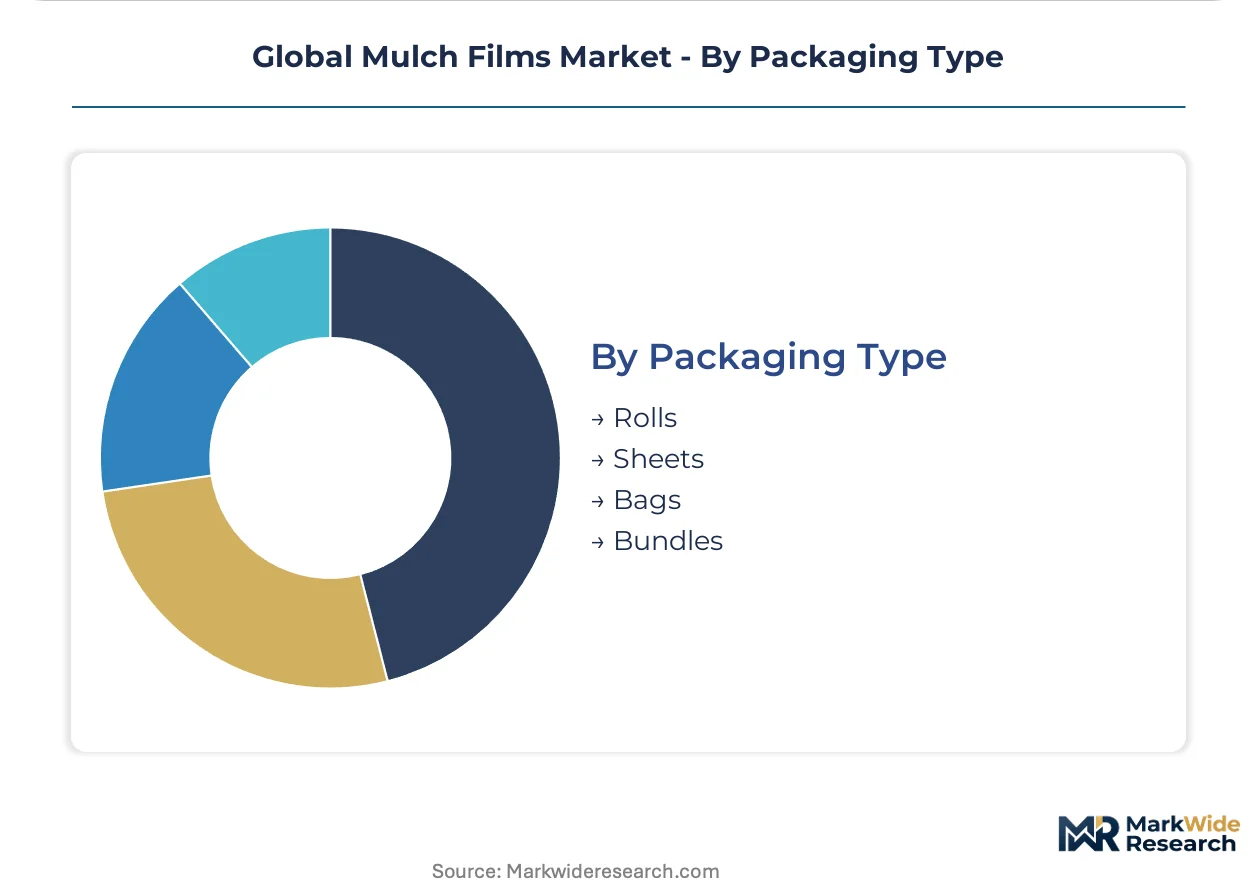
Supply chain configuration and field deployment methods dictate packaging selection, with mechanized operations favoring roll formats and smallholder cooperatives utilizing pre-cut sheets.
- Rolls:Standard 1-2 meter widths on cores enable mechanized laying equipment compatibility; dominant format for commercial farm procurement across Brazil and India.
- Sheets:Pre-cut dimensions serve greenhouse bench applications and smallholder vegetable plots with manual deployment.
- Bags:Compostable film fragments and shredded material for specialized soil amendment applications.
- Bundles:Compressed formats for efficient transport to remote horticulture clusters with limited distribution infrastructure.
Rolls hold the largest share; momentum sits with sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports blown film extrusion equipment and polyethylene resin to India's Indo-Gangetic Plain, while European horticulture clusters import certified biodegradable formulations from domestic compounders. Trade corridors connect feedstock suppliers in the Middle East to converters serving Brazil's Cerrado expansion.
United States
California's Central Valley vegetable belts and Florida's winter tomato operations drive mechanized mulch film consumption for drip-irrigation integration. The EPA scrutinizes agricultural plastic waste under emerging state-level extended producer responsibility frameworks. Berry Global Inc. sustains manufacturing scale across North American roll-form distribution networks serving these concentrated horticulture zones.
Germany
BASF SE leverages its biodegradable polymer portfolio to capture premium positioning in European horticulture supply chains serving organic vegetable producers. The EU F-Gas Regulation and REACH chemical restrictions accelerate substitution timelines for conventional polyethylene films. The Rhine-Main cluster concentrates formulation R&D and regulatory affairs capabilities for compostable starch-polymer blends.
India
Commercial farms across Maharashtra and Gujarat are expanding mulch film usage for vegetable cultivation in the Indo-Gangetic Plain. BIS certification mandates and PLI scheme incentives for bioplastic manufacturing redirect domestic capacity toward compostable mulch formulations. The National Capital Region anchors converter operations supplying mechanized laying-compatible grades to large-scale operations.
Brazil
Large-scale vegetable producers in São Paulo and Minas Gerais states present untapped penetration potential for drip-irrigation integrated mulch systems. ANVISA oversees agricultural chemical contact standards while environmental agencies develop extended producer responsibility frameworks. The Cerrado biome concentrates commercial farm consolidation generating specification intensity for UV-stabilized perforated grades.
Netherlands
Premium horticulture cooperatives have transitioned substantial strawberry and asparagus acreage to compostable alternatives since EU organic certification requirements tightened. The EU Green Deal and CSRD disclosure mandates redirect procurement toward verified soil residue performers. The Westland greenhouse cluster concentrates protected cultivation systems demanding high-clarity films for photoperiod management.
Global Mulch Films Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and regulatory compliance capabilities. The vendor base spans multinational chemical conglomerates with integrated polymer supply chains and regional converters focused on blown film extrusion scale. Three archetypes dominate: petrochemical majors with polyethylene legacy positions, biodegradable polymer specialists with EN 13432 certification assets, and regional roll-form distributors with mechanized laying equipment relationships. Competitive moves concentrate on backward integration into resin compounding and geographic expansion through distributor acquisition.
Among European chemical conglomerates, BASF SE and Novamont S.p.A. exemplify the biodegradable formulation specialist archetype, occupying positions aligned with REACH-driven substitution mandates. Berry Global Inc. represents the North American scale-driven converter model, while Dow Inc. anchors the polyethylene technical grade segment. RKW Group and Armando Alvarez Group sit within the regional European fabricator tier serving protected cultivation systems.
| Leading Market Players |
|---|
| BASF SE |
| Berry Global Inc. |
| Dow Inc. |
| RKW Group |
| Novamont S.p.A. |
| Armando Alvarez Group |
| ExxonMobil Corporation |
| Kuraray Co., Ltd. |
| Amcor Plc |
| Others |
Supply & Pricing Matrix
Biodegradable polymer substitution for conventional polyethylene simultaneously redraws procurement geography and pricing economics across mulch film supply chains. The shift from fossil-derived feedstocks to starch-polymer blends concentrates formulation capacity in European compounders with EN 13432 certification assets, while legacy polyethylene converters in India and Brazil absorb ethylene cost volatility through thinner gauge specifications.
Pricing Analysis
Current-generation biodegradable grades command substantial premiums over incumbent polyethylene formulations, with next-generation polylactic acid-starch composites positioned for further price stratification. Three-tier pricing structure across premium certified compostable, standard biodegradable, and economy polyethylene levels reflects differentiation by EN 13432 certification status and soil residue verification. Price differentiation stems from additive disclosure burdens under REACH and volume scale advantages at large commercial farm procurement tiers. Pricing pressure stems from ethylene feedstock volatility compressing converter margins serving price-sensitive horticulture cooperatives in India and Brazil. Organic crop producers in the Netherlands and Germany exhibit lowest price sensitivity due to certification compliance requirements, while smallholder vegetable cooperatives in the Indo-Gangetic Plain remain most cost-conscious.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg elevate inbound logistics costs for biodegradable polymer resin shipments. Supply concentrates in Germany for certified compostable formulations, China for blown film extrusion equipment, and Saudi Arabia for polyethylene resin feedstock. Raw material dependencies span ethylene derivatives, starch feedstocks, and polylactic acid monomers. Single-source vulnerability sits with European compounders controlling EN 13432 certification pathways. Distribution runs through regional agricultural supply distributors in India and Brazil, with direct polymer producer relationships disintermediating traditional channels in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mulch film procurement is transitioning toward platform economics where polymer producers, certification bodies, and large farming enterprises interoperate through direct contracting relationships. This ecosystem shift concentrates volume with formulation specialists capable of customizing degradation rates to specific crop rotation schedules.
For Market Incumbents: Compound regulatory affairs capabilities to navigate divergent biodegradability certification standards between ISO 17088 and national agricultural regulators. Secure backward integration into starch-polymer compounding to defend margin position against specialty chemical entrants with captive raw material access. Prioritize mechanized laying equipment compatibility as large commercial farms consolidate procurement volume.
For New Entrants and Emerging Players: Post-use collection infrastructure gaps across East Asian horticulture clusters represent a service-layer gap where incumbents under-serve conventional film users exposed to extended producer liability frameworks. Target Brazilian commercial farm expansion in São Paulo and Minas Gerais states for drip-irrigation integrated mulch system penetration. Pursue regulatory consulting bundled with product supply as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors vertically integrated compounders with in-house certification capabilities and regulatory affairs infrastructure. Long-term viability over the coming decade hinges on positioning ahead of REACH chemical restriction timelines and emerging state-level extended producer responsibility frameworks. Acquisition target archetype: mid-scale European biodegradable polymer specialists with EN 13432 assets and established direct relationships with 200+ hectare vegetable operations. Monitor EU F-Gas Regulation enforcement intensity and India's PLI scheme disbursement velocity as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch-Polymer Compounding | Captive supply of certified biodegradable feedstock secures margin control against resin price volatility. |
| Direct Contracting with Large Commercial Farms | Bypassing regional cooperatives concentrates volume with formulation specialists for customized degradation rates. |
| EN 13432 Certification Investment | Organic certification requirements in EU member states mandate verified compostable alternatives for market access. |
| Mechanized Laying Equipment Compatibility | Commercial farm consolidation in Brazil and India drives specification intensity for roll-form distribution. |
| Regulatory Affairs Capability Buildout | REACH additive disclosure requirements extend product development timelines and favor integrated compounders. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer plant managers, agricultural procurement leads at large commercial farms, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, agricultural plastics industry association reports, SEC 10-K filings, and national regulatory filings with ECHA and BIS. Bottom-up triangulation across converter capacity assessments and top-down cross-checks against horticulture acreage expansion data anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by material composition, application intensity, end-user scale tier, and regional regulatory cluster. Segmentation dimensions included polyethylene versus biodegradable grade tier, vegetable cultivation versus turfgrass management application, and mechanized commercial farm versus smallholder cooperative end-user type. CAGRs were derived from fitted growth curves applied to base-year market sizing, with industry-specific inputs incorporating PLI scheme incentive disbursement patterns and REACH restriction implementation timelines.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks alongside India's BIS certification mandates; material policy shifts would require re-modeling substitution velocity assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Pond Liners Market