
 Aquafeed Additives Market | 2026-2036
Aquafeed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Aquafeed Additives Market Intelligence
The rise of integrated aquaculture systems financed through long-term offtake agreements is reconfiguring the competitive landscape for additive suppliers. Large-scale producers like Cargill leverage their vast supply chain to offer bundled feed and additive solutions. Evonik Industries specializes in essential amino acids, critical for formulating high-performance feeds. Kemin Industries differentiates through its portfolio of specialty ingredients focused on animal health and preservation.
Aquafeed additives are non-nutritive substances incorporated in small quantities into aquatic animal diets to enhance specific physiological functions. These compounds, often dosed at the parts-per-million level, improve feed conversion ratios and bolster disease resistance. Within product types, amino acids and vitamins constitute the largest value segments due to their foundational role in animal nutrition. Demand from shrimp farming represents the fastest-growing end-user category, driven by production intensification in Asia and Latin America.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) define permissible ingredients and maximum inclusion levels. In parallel, approvals from China's agricultural authorities are critical for market access, shaping global product portfolios. Navigating this complex compliance environment while demonstrating clear return on investment to farmers remains the central challenge for additive manufacturers.
Market Dynamics
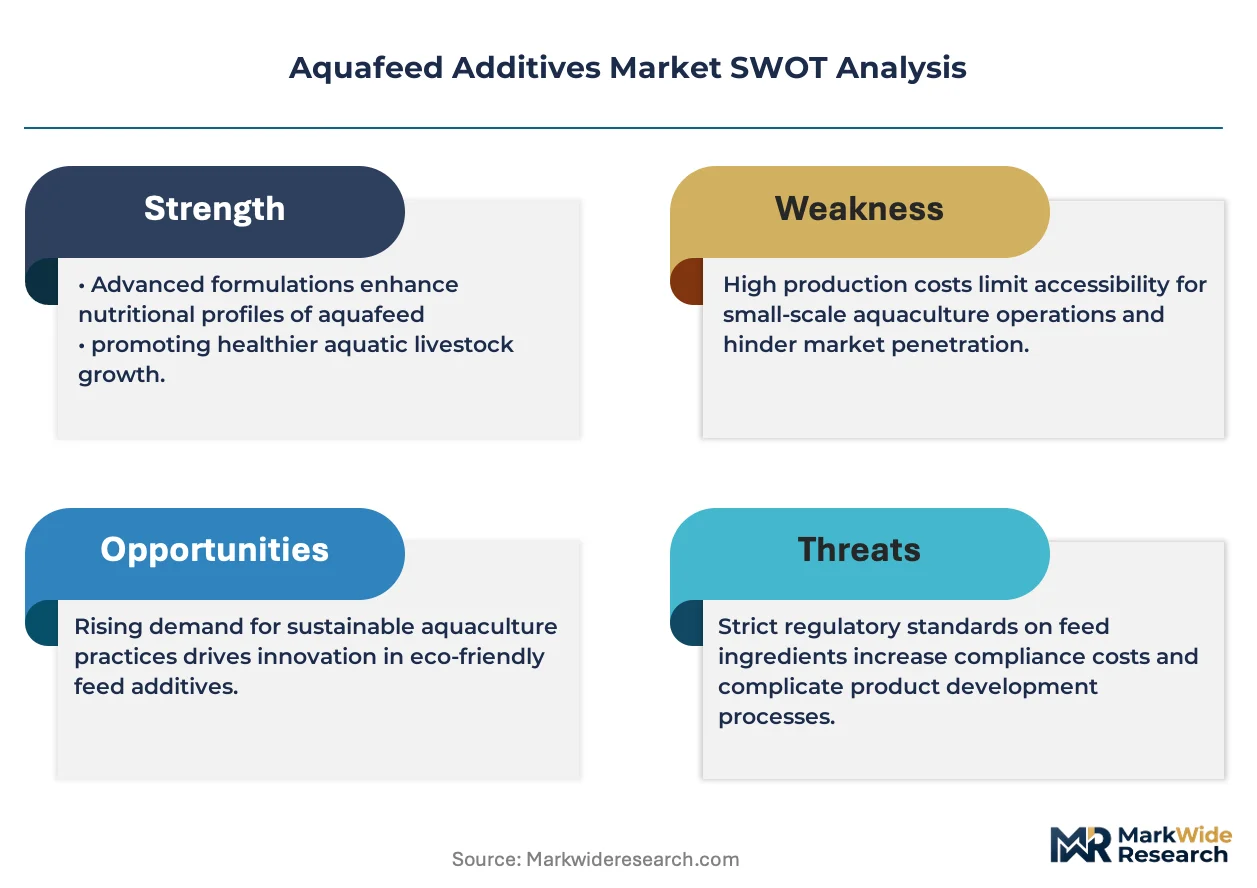
The central dynamic shaping the aquafeed additives market is the pressure for production intensification clashing with stricter global regulations on animal health management. This tension is forcing a pivot from traditional antibiotic use towards sophisticated, health-promoting additives to maintain productivity and disease resistance.
Growth Catalysts
- Regulatory Mandates:European Food Safety Authority (EFSA) antibiotic restrictions create demand for alternative health additives like probiotics for disease control.
- Shrimp Farming Intensification:High-density shrimp farming in Asia requires specialized additives to improve survival rates and feed conversion, driving consumption.
- Production Scale in China:China’s status as the top aquaculture producer establishes a massive baseline demand for foundational additives like amino acids.
Market Restraints
- Input Cost Volatility:Prices for amino acids are tied to volatile agricultural commodity markets, creating unpredictable costs for feed manufacturers.
- Farmer ROI Justification:Proving a clear return on investment for premium additives to price-sensitive small-scale farmers remains a significant adoption barrier.
- Complex Compliance Pathways:Inconsistent approval processes between the FDA, EFSA, and Chinese regulators delay product launches and increase development costs.
Strategic Opportunities
- Functional Ingredients for New Species:Developing specialized additive packages for emerging aquaculture species, such as seaweed or alternative finfish, opens new product differentiation pathways.
- African Aquaculture Expansion:Underpenetrated markets in Nigeria and Egypt present growth potential as their aquaculture sectors modernize and intensify production methods.
- Digital Integration:Combining additives with digital farm management platforms enables data-driven dosing, creating value-added services and strengthening customer loyalty.
Industry Challenges
- Supply Chain Traceability:Ensuring the quality, purity, and traceability of micro-ingredients sourced from a fragmented global supplier base presents a constant operational hurdle for manufacturers.
- Farmer Education and Training:Effectively training a diverse and geographically dispersed end-user base on the correct application of sophisticated additives requires significant investment in technical support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquafeed Additives Market |
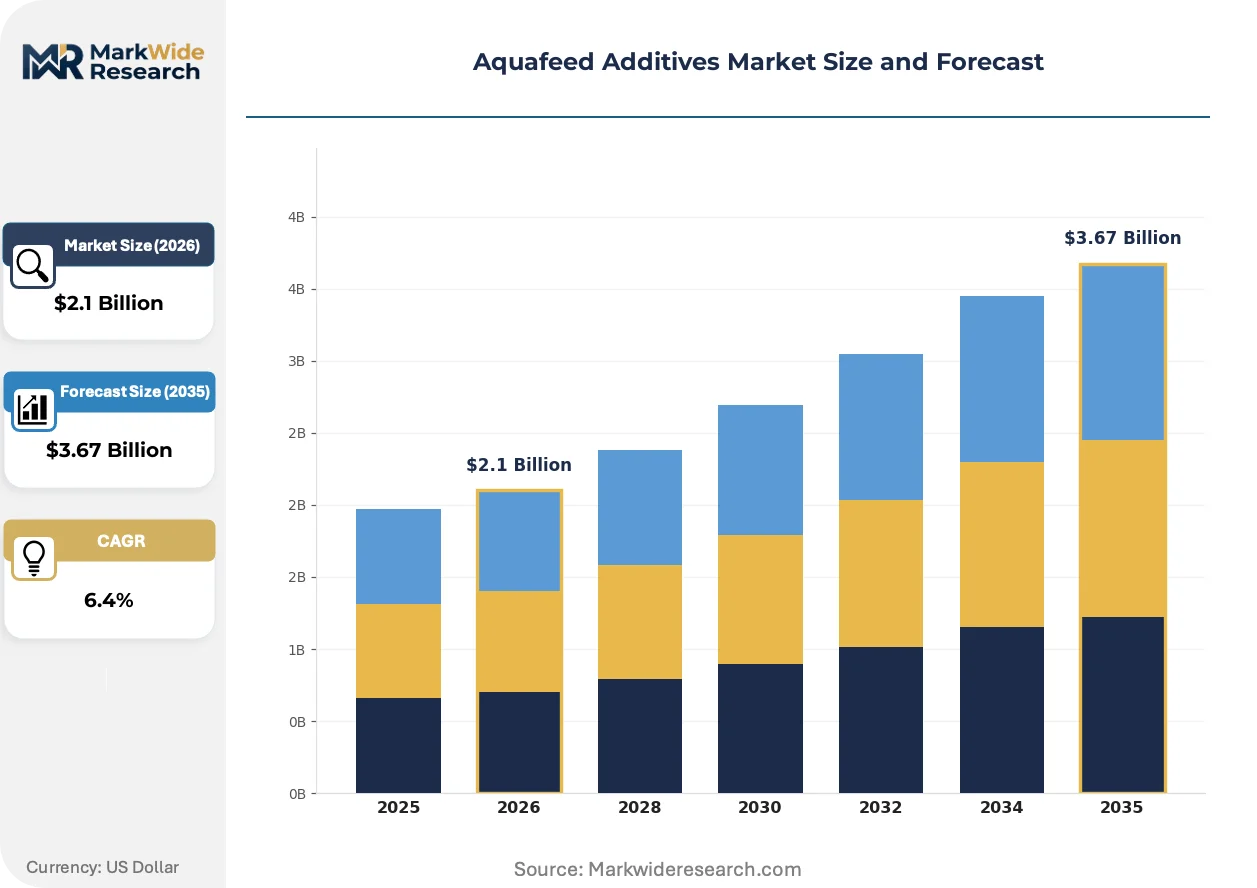
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes End User: Fish Farming, Shrimp Farming, Mollusk Farming, Aquaculture Operations Formulation Type: Dry Form, Liquid Form, Granules, Powders Distribution Channel: Direct Sales, Distributors, Online Retail, Sales Agents |
| Companies Covered | Evonik Industries, Kemin Industries, Nutreco, Archer Daniels Midland, DSM, BioMar Group, Cargill, Adisseo, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquafeed Additives Market Strategic Shifts & Innovations
Biological specificity and data-driven precision are the new frontiers in aquafeed formulation. The market is shifting from broad-spectrum additives to targeted solutions, driven by advances in nutritional science that optimize health and performance at the farm level.
Precision feeding systems utilize aquatic sensors and data analytics to optimize the timing and composition of feed. Large, integrated salmon and shrimp producers are the primary adopters, seeking to minimize waste and improve feed conversion. This technology is digitizing nutritional management, enabling real-time adjustments to additive inclusion based on live farm conditions.
The European Food Safety Authority’s (EFSA) stringent limits on antibiotic use in animal husbandry are a primary regulatory driver. This forces a systemic shift toward non-antibiotic health solutions, such as probiotics, prebiotics, and phytogenics. The salmon and shrimp farming sectors, heavily reliant on exports to the EU, are most affected and are actively reformulating feeds.
Buying patterns are evolving as large aquaculture producers consolidate their supply chains. These integrators increasingly favor long-term agreements for bundled feed and additive solutions over transactional purchases of individual ingredients. This model is most prominent in the highly organized salmon farming industry in Norway and Chile, altering the competitive landscape for suppliers.
Aquafeed Additives Market Segmentation
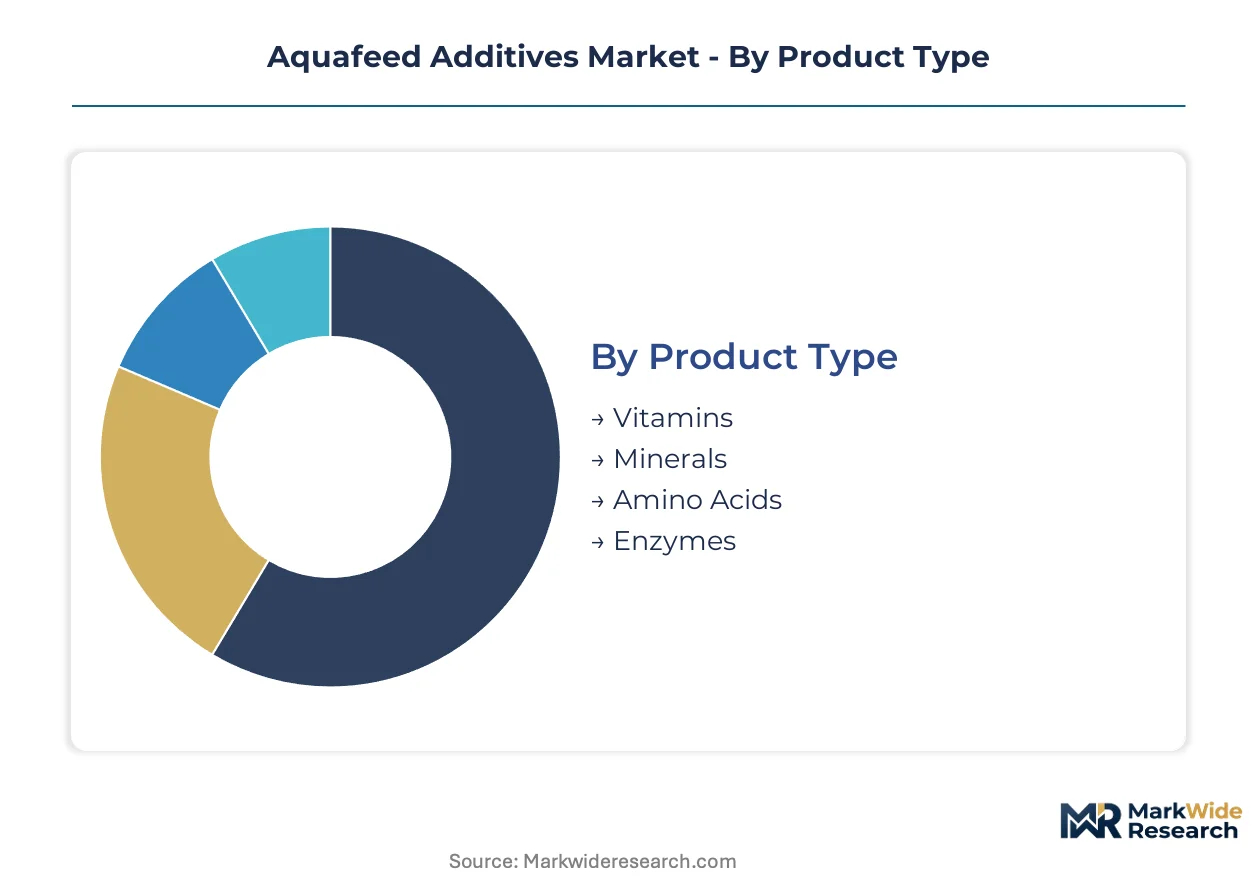
The aquafeed additives market categorizes diverse products and applications, reflecting the specialized needs of aquatic species and varied aquaculture practices. Understanding these segments is crucial for manufacturers to tailor solutions that address specific physiological requirements and production challenges across different farming environments.
Product Type:
The functional composition of aquafeed additives directly influences their efficacy in enhancing aquatic animal health and growth performance.
- Amino Acids:These organic compounds are fundamental protein building blocks, essential for muscle development and metabolic functions in aquatic species. Demand concentrates in intensive shrimp and salmon farming, driven by the need for optimal feed conversion ratios.
- Vitamins:These micronutrients regulate numerous physiological processes, including immune response and stress resistance in farmed aquatic animals. Asian aquaculture, particularly in China and Vietnam, drives significant vitamin consumption for disease prevention.
- Minerals:Inorganic elements like calcium and phosphorus support skeletal development and osmoregulation in fish and shrimp.
- Enzymes:These proteins improve nutrient digestibility and absorption, reducing feed waste and improving gut health in finfish.
Amino Acids commands the established base. The steepest expansion runs through Enzymes.
End User:
The application of aquafeed additives varies significantly across different aquaculture species, each presenting unique nutritional requirements and production challenges.
- Shrimp Farming:This segment utilizes specialized additives to improve survival rates, growth, and disease resistance in high-density production systems. Intensification in Latin America and Southeast Asia drives consistent demand for these solutions.
- Fish Farming:This category represents a large-volume consumer of additives, focusing on species like salmon, tilapia, and pangasius to optimize growth and feed efficiency. European salmon farms prioritize additives for health and welfare.
- Mollusk Farming:Additives for mollusk production typically focus on improving water quality and enhancing natural food sources for species like oysters and clams.
- Aquaculture Operations:This broad category includes diverse smaller-scale or emerging species, requiring tailored additive solutions for specific environmental conditions.
Fish Farming consistently drives the largest volumes. Shrimp Farming exhibits the most rapid expansion.
Formulation Type:
The physical form of aquafeed additives dictates handling, storage, and mixing characteristics, impacting their integration into various feed production processes.
- Powders:These fine particle forms allow for precise dosing and easy integration into dry feed mixes during manufacturing. They are widely used across all aquaculture sectors due to their versatility.
- Dry Form:This encompasses a broad range of solid additives, offering stability and extended shelf life, crucial for bulk handling and storage. Large-scale feed mills in China heavily utilize dry form additives.
- Liquid Form:Concentrated liquid additives offer ease of application in certain feed production methods and can be sprayed onto pellets.
- Granules:These small, solid particles provide better flowability and reduced dust compared to powders, improving handling safety.
Dry Form additives constitute the foundational supply. Liquid Form solutions are gaining traction for specialized applications.
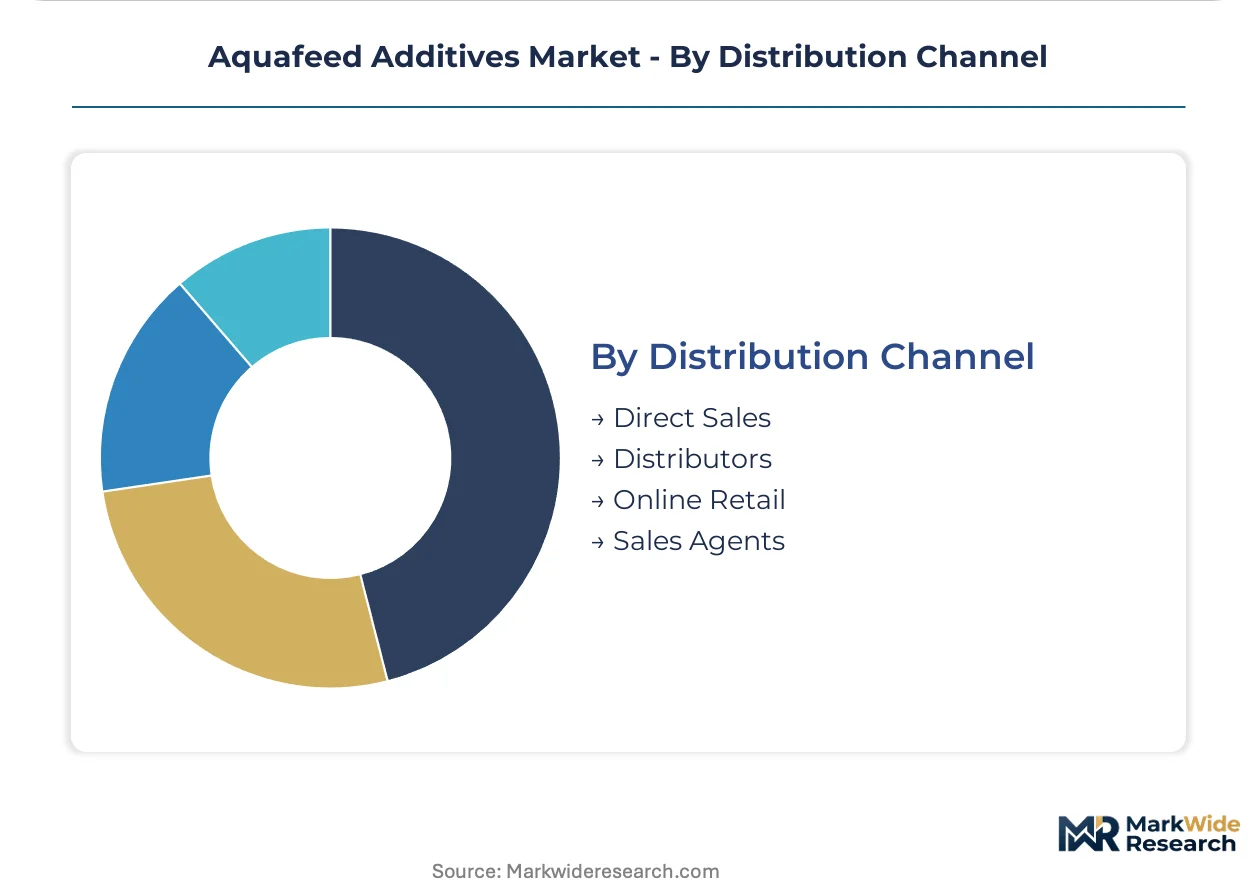
Distribution Channel:
The pathways for delivering aquafeed additives reflect the industry's structure, ranging from direct engagement with large producers to broader market reach through intermediaries.
- Direct Sales:This channel involves manufacturers selling directly to large-scale aquaculture operations and integrated feed producers. Major salmon farms in Norway often procure additives through direct agreements.
- Distributors:These intermediaries provide extensive market coverage, reaching a wide array of small to medium-sized farms across diverse geographies. Distributors are crucial for market penetration in fragmented Asian markets.
- Online Retail:E-commerce platforms offer accessibility for smaller buyers and niche products, providing convenience and price transparency.
- Sales Agents:Independent agents represent manufacturers, facilitating sales and providing technical support in specific regional markets.
Distributors ensure widespread market access. Direct Sales capture the highest volume transactions with integrated producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory mandates from authorities like the European Food Safety Authority (EFSA) are reshaping aquafeed additive consumption patterns globally. These policies drive demand for health-promoting alternatives to traditional inputs. Countries with significant aquaculture production are adapting to these new compliance landscapes.
China
Demand for foundational additives like amino acids is substantial in China, driven by its status as the leading aquaculture producer. China's agricultural authorities' approvals are critical for market access and product portfolios. Coastal provinces, such as Guangdong and Fujian, are hubs for intensive aquaculture operations, requiring consistent additive supply.
Norway
Norway's advanced salmon farming industry drives demand for high-performance feed and additive solutions, often through long-term agreements. The European Food Safety Authority (EFSA) restrictions on antibiotic use influence Norwegian producers, who prioritize non-antibiotic health solutions. Major salmon farming regions like Trøndelag and Western Norway concentrate integrated producers seeking bundled solutions.
United States
Diverse aquaculture species in the United States create demand for specialized additive packages to optimize growth and health. The US Food and Drug Administration (FDA) defines permissible ingredients and maximum inclusion levels for aquafeed additives. Aquaculture operations in states like Washington and Florida focus on species-specific nutritional requirements, driving demand for tailored solutions.
Vietnam
Shrimp farming intensification in Vietnam requires specialized additives to improve survival rates and feed conversion ratios. The Vietnamese government actively promotes sustainable aquaculture practices, impacting additive formulation. The Mekong Delta region, a major shrimp production area, sees significant consumption of health-promoting additives for disease prevention.
Aquafeed Additives Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with large-scale integrators and specialized ingredient manufacturers. Major players leverage extensive supply chains to offer comprehensive feed and additive solutions. Three strategic archetypes emerge: global feed integrators, essential amino acid specialists, and health-promoting ingredient innovators. Competitive moves focus on vertical integration, product differentiation through R&D, and forging long-term customer agreements.
Within the global feed integrator archetype, Cargill, a multinational agribusiness corporation, represents a player offering bundled feed and additive solutions through its vast supply chain. Evonik Industries, a German-based specialty chemicals company, exemplifies a specialized ingredient manufacturer, focusing on essential amino acids crucial for high-performance feeds. Kemin Industries, an Iowa-based ingredient manufacturer, occupies a position as a specialty additive provider, differentiating through its portfolio of health-focused ingredients and preservation solutions.
| Leading Market Players |
|---|
| Evonik Industries |
| Kemin Industries |
| Nutreco |
| Archer Daniels Midland |
| DSM |
| BioMar Group |
| Cargill |
| Adisseo |
| Alltech |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for essential amino acids and vitamins determines pricing tier spreads and shapes the aquafeed additive supply chain. Regulatory chokepoints from authorities like the EFSA also influence market access and cost structures.
Pricing Analysis
Regulatory approval status, such as EFSA or FDA certification, creates the primary pricing spread for aquafeed additives. Large integrated producers often engage in contract-based long-term offtake agreements, while smaller farms rely on transactional purchases. Pricing softness impacts foundational additives due to underlying agricultural commodity market fluctuations. Small-scale farmers exhibit the highest price sensitivity, whereas large salmon farming operations prioritize performance over cost.
Supply Chain Analysis
Contract manufacturing for many foundational additives concentrates in China, particularly for amino acids and vitamins. Specialized ingredient production also occurs in Europe and the United States. The supply chain relies on agricultural commodity inputs like soybean meal and corn for fermentation processes. Traceability challenges for micro-ingredients sourced from a fragmented global base represent a structural risk. Distribution runs through a network of intermediaries for smaller farms, with direct sales to large integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aquafeed additives market presents a significant service-attach opportunity for suppliers. Digital farm management platforms, offering data-driven dosing and real-time nutritional adjustments, are expanding faster than standalone ingredient sales.
For Market Incumbents:Harden existing long-term offtake agreements with large integrated producers to defend against new entrant competition. Invest in advanced R&D for next-generation non-antibiotic health solutions, addressing EFSA antibiotic restrictions. Expand capacity for specialty ingredients in Europe to mitigate supply chain risks. Prioritize certification investment for novel probiotics and phytogenics.
For New Entrants and Emerging Players:Establish a beachhead in specialized additive packages for emerging aquaculture species like seaweed or alternative finfish. Target underpenetrated markets in African countries such as Nigeria and Egypt, where aquaculture is modernizing. The small-to-medium scale shrimp farming segment in Southeast Asia offers a penetrable entry point. Go-to-market strategies should bundle additives with technical support and farmer training programs.
For Investors and Strategic Acquirers:EFSA's stringent antibiotic restrictions reshape the acquisition landscape, favoring companies with proven alternative health solutions. The market's long-term viability centers on precision-dosed, health-promoting additives over the next decade. Acquisition targets should include specialty ingredient manufacturers holding strong intellectual property in probiotics, prebiotics, and phytogenics. Increased regulatory enforcement of non-antibiotic mandates serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand digital integration platforms. | Enhances customer loyalty through data-driven dosing for large salmon producers. |
| Acquire specialized phytogenic and probiotic producers. | Diversifies product portfolio to meet demand for non-antibiotic solutions in the EU. |
| Invest in supply chain traceability technologies. | Ensures quality and purity of micro-ingredients, meeting Chinese agricultural authority requirements. |
| Develop tailored solutions for emerging aquaculture species. | Opens new product differentiation pathways for alternative finfish and seaweed. |
| Strengthen technical support and farmer training. | Increases adoption rates for sophisticated additives among Vietnamese shrimp farmers. |
Research Approach
Initial hypotheses were tested against primary input from aquaculture farm managers, feed formulators, regulatory affairs specialists, and additive manufacturers. This primary research was validated through extensive secondary data, including EFSA reports, FDA guidelines, and Chinese agricultural authority publications. The approach integrated both bottom-up market sizing and top-down validation to ensure data integrity.
Demand-supply-balance modeling formed the core of the forecast framework across the projection horizon. Segmentation dimensions included product type, end-user, formulation type, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from historical trends and anticipated regulatory impacts. Aquaculture production volumes in Asia and antibiotic restriction timelines in Europe served as critical forecast inputs.
Stress conditions across commodity price volatility and disease outbreak severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding stable regulatory environments. Quarterly review of global aquaculture production statistics and EFSA policy updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
North America Herbicide Market