
 Irrigation Syringe Market | 2026-2036
Irrigation Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Irrigation Syringe Market Foresight
Hospital procurement channels is reshaping how irrigation syringe manufacturers reach end users, with group purchasing organizations consolidating contract awards and squeezing distributor margins. BD leverages its vertically integrated manufacturing footprint to sustain cost advantages across North American hospital networks. Terumo Corporation anchors its competitive position through specialized catheter-tip syringe designs that dominate Japanese surgical suites. Cardinal Health competes on logistics density, using its distribution control to occupy preferred supplier status with integrated delivery networks.
An irrigation syringe is a manually operated medical device consisting of a barrel, plunger, and tip designed to deliver controlled volumes of sterile fluid to body cavities, wounds, or medical apparatus, typically manufactured through injection molding of medical-grade polypropylene with tolerances of ±5% on stated volume. Its primary commercial purpose centers on preventing cross-contamination during wound debridement, ear lavage, and enteral hydration procedures across acute and ambulatory settings. Standard syringes and bulb syringes together command the majority of unit volume, though piston syringes carry higher margin pools due to precision dosing requirements in enteral feeding applications. The home care end user segment is expanding fastest as post-acute protocols shift irrigation maintenance from institutional settings to patient-controlled environments.
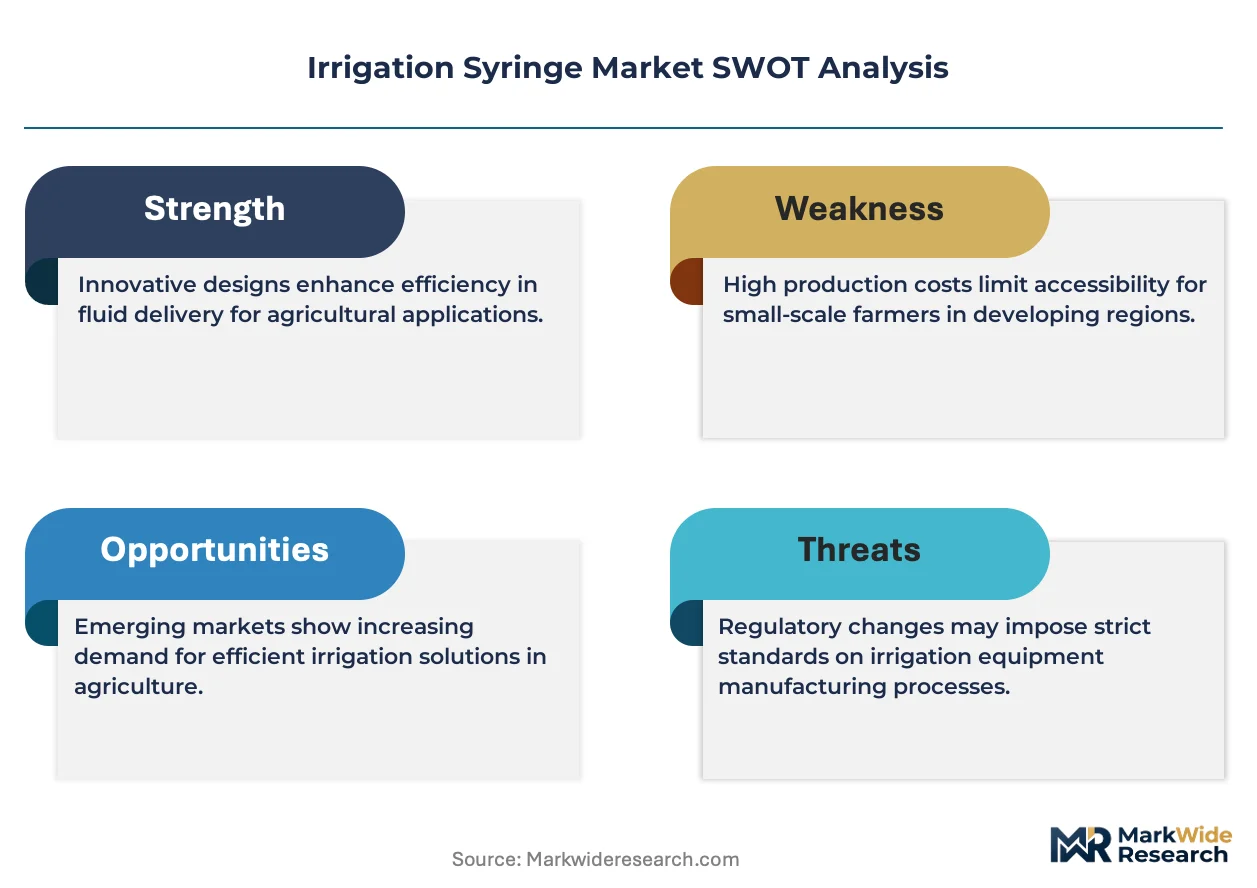
FDA 510(k) clearance pathways and EU MDR technical documentation requirements are elevating barrier costs for new irrigation syringe entrants, while ISO 7886 standards govern dimensional and performance consistency across international trade. The country's national pharmaceutical regulator in India and CDSCO are tightening import inspections on disposable syringe lots, redirecting some procurement toward domestic BIS-certified manufacturers. Stakeholders must monitor how FDA sterility guidance revisions and EU F-Gas Regulation impacts on medical device packaging materials will reshape compliance investments and sourcing geography decisions.
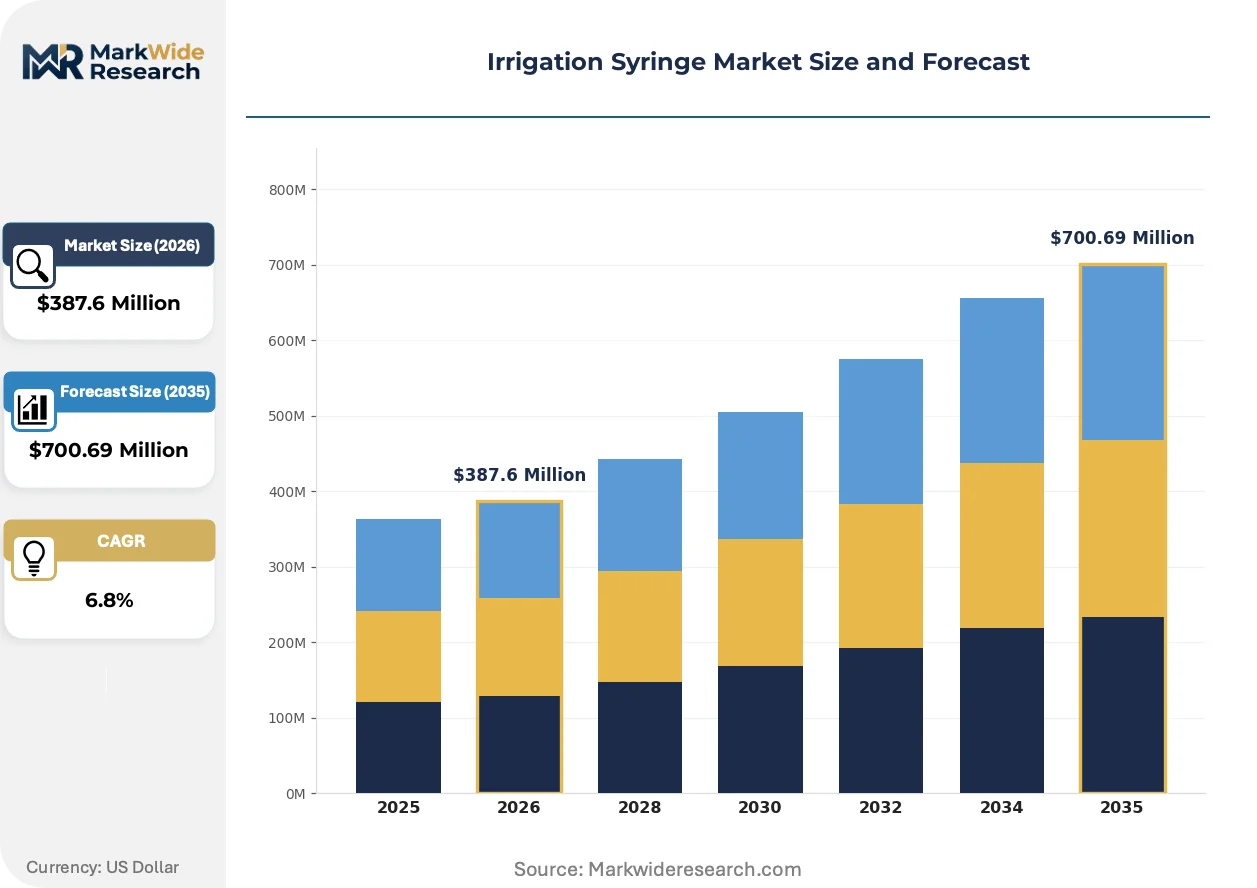
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing distributor margins and forcing manufacturers to absorb sterility assurance costs mandated by converging FDA and EU MDR requirements.
Growth Catalysts
- Outpatient wound care expansion:Post-acute protocols in the United States and Germany are shifting irrigation maintenance from inpatient wards to ambulatory surgical centers, expanding addressable procedure volume.
- FDA sterility guidance convergence:Unified sterility assurance requirements across 510(k) clearance pathways are elevating compliance barriers that favor established manufacturers with validated aseptic processing lines.
- Enteral feeding precision dosing:Piston syringe designs with catheter-tip configurations are capturing preference in Japanese surgical suites where enteral hydration protocols demand ±5% volume tolerance.
Market Restraints
- Medical-grade polypropylene feedstock volatility:Injection molding resin costs fluctuate with petrochemical pricing, squeezing gross margins on standard syringe categories where price elasticity limits pass-through.
- Single-source sterilization capacity concentration:Gamma irradiation and ethylene oxide sterilization services cluster in the United States and Germany, creating geographic chokepoints for manufacturers serving Asian markets.
- EU F-Gas Regulation packaging constraints:Restrictions on fluorinated gas use in medical device barrier films are forcing material substitutions that extend qualification timelines and raise unit costs.
Strategic Opportunities
- Home care patient-controlled irrigation:Post-discharge wound management protocols in Japan and the United States are creating demand for simplified bulb syringe designs with intuitive plunger resistance.
- ISO 7886 harmonization with EU MDR:Converging dimensional standards are reducing SKU complexity for manufacturers with multi-regional footprints, enabling scale economies in polypropylene barrel production.
- Digital supply chain integration:RFID-enabled syringe tracking is penetrating integrated delivery networks in Germany, creating preference for manufacturers with serialization capabilities.
Industry Challenges
- Aseptic processing technician scarcity:Validated cleanroom operations require specialized personnel whose certification timelines extend 18-24 months, constraining capacity expansion.
- Legacy ERP integration with track-and-trace mandates:EU MDR unique device identifier requirements are forcing mid-tier manufacturers to replace decades-old inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irrigation Syringe Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Bulb Syringes, Piston Syringes, Specialty Syringes End User: Hospitals, Clinics, Dental Practices, Home Care Material: Plastic, Glass, Silicone, Rubber Application: Wound Care, Ear Irrigation, Hydration, Cleaning |
| Companies Covered | BD (Becton, Dickinson and Company), Medtronic, Cardinal Health, Terumo Corporation, Smiths Medical, B. Braun Melsungen AG, Nipro Corporation, Baxter International Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irrigation Syringe Market Shifts & Advancements
Digital serialization and connected health interfaces are penetrating irrigation syringe categories that have remained mechanically unchanged for decades, reshaping how manufacturers demonstrate value to procurement committees.
Smart syringe technologies with embedded pressure sensors and Bluetooth connectivity are virtualizing the documentation of irrigation procedures, enabling automated logging of lavage volume and pressure parameters. Ambulatory surgical centers in Germany and the United States are piloting these devices for liability documentation. The technology is virtualizing the role of manual charting, compressing documentation labor while creating data assets for outcome analytics.
EU MDR technical documentation requirements are extending pre-market submission timelines by 40-60% for irrigation syringe manufacturers seeking CE marking renewal. The regulation demands exhaustive clinical evidence for devices previously cleared under simpler equivalence pathways. Class I reusable irrigation syringes face the steepest compliance burden, driving portfolio rationalization toward single-use alternatives with clearer sterility claims.
Group purchasing organization contract consolidation is compressing the viable supplier base for standard irrigation syringes to three-to-five preferred vendors per metropolitan hospital network. Integrated delivery networks in the United States are unbundling distributor services, awarding logistics contracts separately from product supply. This bifurcation is most visible in the Midwest and Southeast regions where health system mergers have created procurement entities covering 15-20 hospital facilities.
Irrigation Syringe Market Segmentation
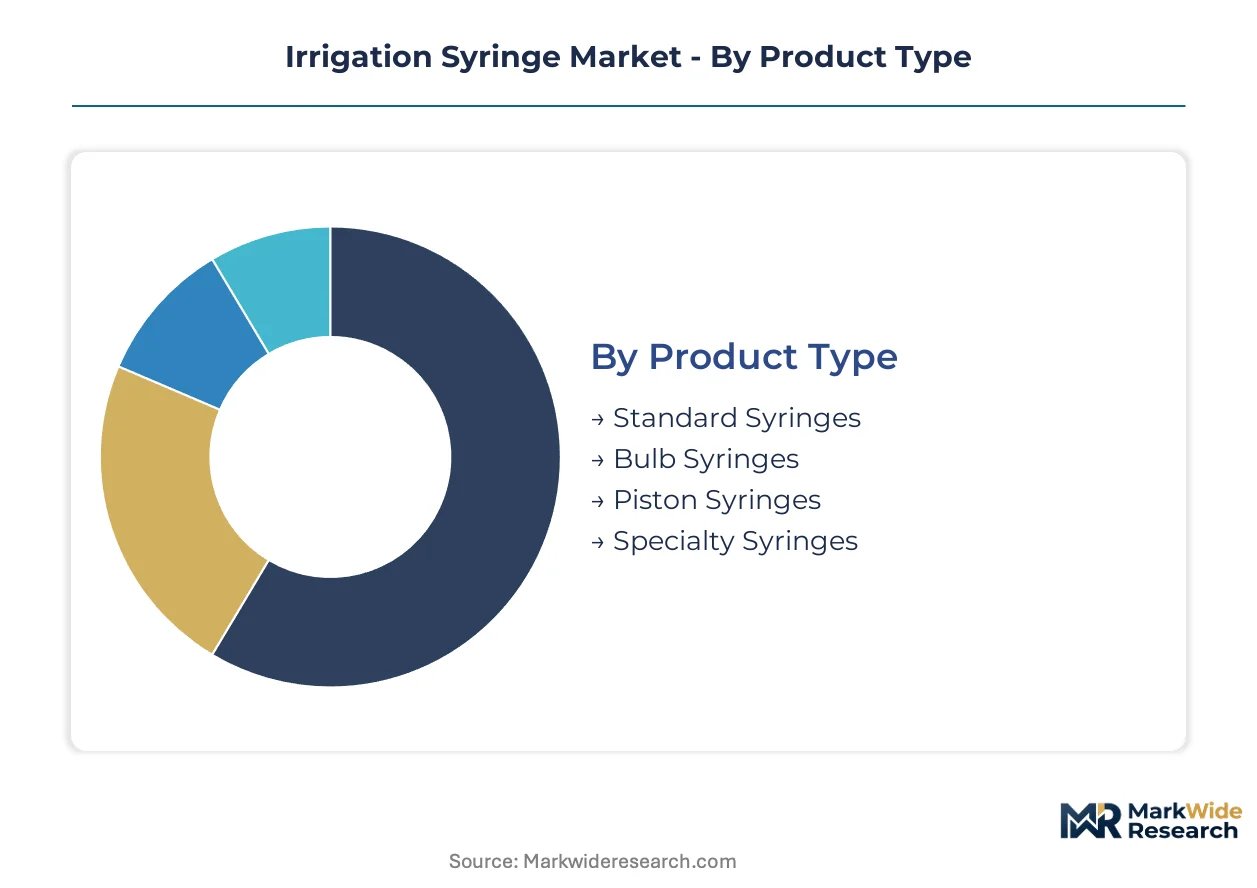
Irrigation syringe procurement diverges sharply across clinical settings, with sterility requirements and precision tolerances dictating product selection. Manufacturers must align barrel materials, tip configurations, and volume capacities to distinct procedure protocols spanning acute care through patient-controlled home environments.
Product Type:
Use-case spectrum spans from high-volume disposable standard units to precision-calibrated piston systems for enteral feeding.
- Standard Syringes:Medical-grade polypropylene barrels with Luer-lock or slip-tip configurations dominate high-throughput hospital wards. Demand concentrates in United States metropolitan hospital networks where group purchasing organization contracts favor validated aseptic processing lines from established suppliers.
- Piston Syringes:Catheter-tip designs with graduated barrels deliver ±5% volume tolerance required for enteral hydration protocols. Japanese surgical suites anchor preference here, driven by METI-influenced precision standards and post-operative feeding tube maintenance volumes.
- Bulb Syringes:Elastomer bulb mechanisms with tapered soft tips serve ear lavage and nasal irrigation in outpatient settings.
- Specialty Syringes:Angled-tip and curved-barrel variants address wound debridement in podiatric and plastic surgery applications.
The dominant share belongs to Standard Syringes, while Piston Syringes is closing the gap fastest.
End User:
Customer-type stratification reveals divergent purchasing authority, from centralized hospital procurement committees to individual patient retail selection.
- Hospitals:Integrated delivery networks consolidate orders across 15-20 facilities, demanding lot-level traceability and gamma irradiation certificates. FDA sterility guidance convergence elevates compliance costs that squeeze mid-tier distributors.
- Home Care:Post-discharge wound management protocols in Germany and Japan are shifting irrigation maintenance to patient-controlled environments. Simplified bulb syringe designs with intuitive plunger resistance are gaining preference as reimbursement codes expand for home-based debridement.
- Clinics:Ambulatory surgical centers in United States Midwest and Southeast regions unbundle logistics from product supply.
- Dental Practices:Smaller volume procurement with preference for single-unit sterile packaging.
Hospitals command the installed base, though Home Care is expanding most quickly as post-acute protocols migrate outside institutional walls.
Material:
Cost-tier and performance-grade differentiation separates commodity polypropylene from specialized elastomer and glass alternatives.
- Plastic:Injection-molded polypropylene dominates unit economics with medical-grade resin specifications. Petrochemical feedstock volatility compresses gross margins where price elasticity constrains pass-through to group purchasing organization contracts.
- Silicone:Platinum-cured elastomer bulbs and seals deliver compression durability for repeated actuation cycles. Japanese home care segment preference for soft-tip comfort drives specialty silicone formulation demand.
- Glass:Borosilicate barrels persist in research and compounding pharmacy settings requiring chemical inertness.
- Rubber:Natural and synthetic elastomer components for plunger seals and bulb mechanisms.
Plastic holds volume leadership, while Silicone is climbing the fastest on home care comfort requirements.
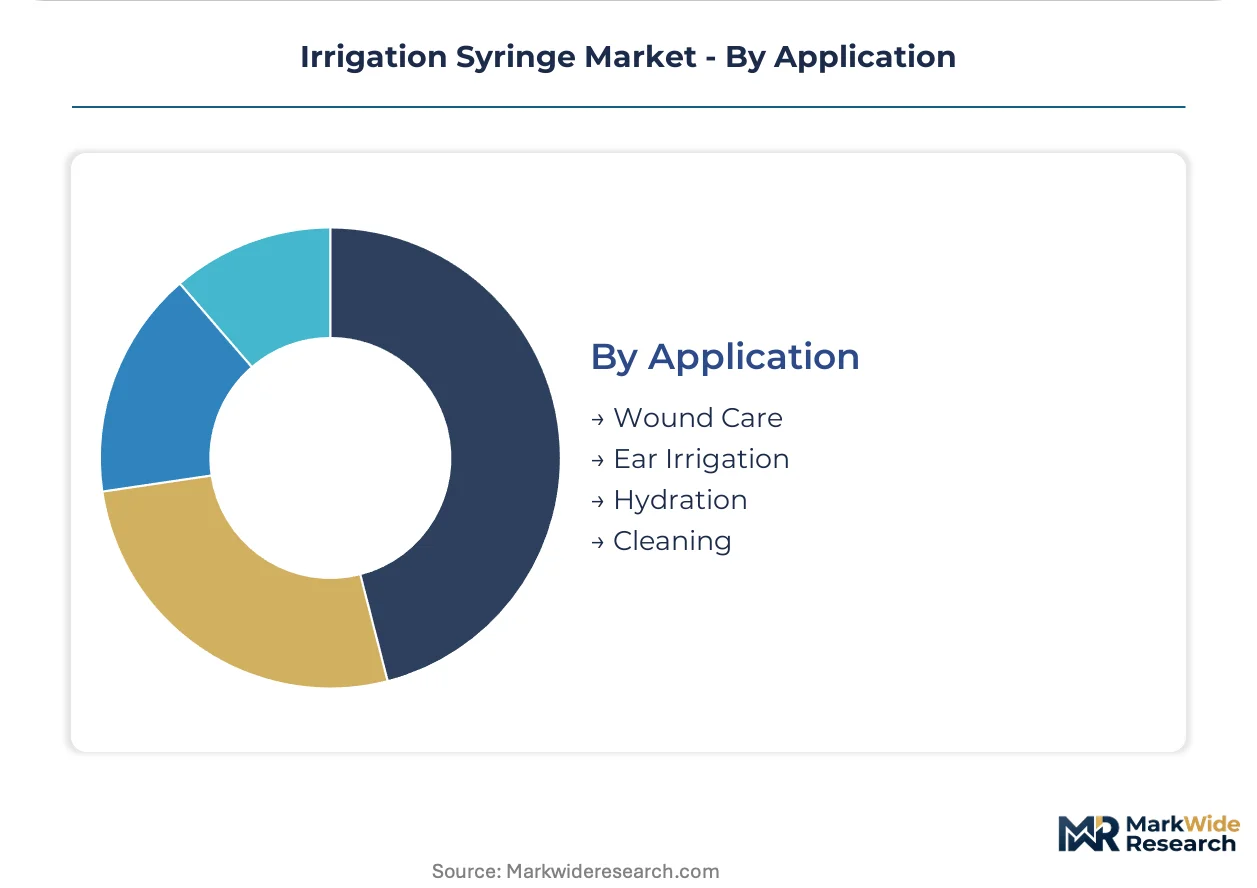
Application:
Procedure-specific performance requirements dictate tip geometry, volume range, and pressure tolerance specifications.
- Wound Care:High-volume saline lavage for debridement and infection control drives standard syringe consumption. United States outpatient surgical centers are expanding procedure volume as post-acute protocols shift irrigation maintenance from inpatient wards.
- Hydration:Enteral and parenteral fluid delivery demands piston syringe precision with catheter-tip compatibility. Japanese surgical suites anchor this segment through specialized enteral feeding protocols.
- Ear Irrigation:Bulb syringe mechanics with soft tapered tips address cerumen removal in primary care.
- Cleaning:Instrument and apparatus flushing applications in sterile processing departments.
Wound Care captures the largest procedure volume, while Hydration is gaining share fastest on enteral feeding protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese surgical suites and German integrated delivery networks, while procurement leverage fragments across United States metropolitan hospital systems. Manufacturers absorb divergent compliance costs across FDA 510(k) pathways and EU MDR technical documentation regimes. Sterility assurance investments reshape sourcing geography as gamma irradiation capacity clusters in specific industrial zones.
United States
Group purchasing organizations consolidate contracts across 15-20 hospital facilities in Midwest and Southeast health systems. FDA sterility guidance revisions elevate barrier costs for new entrants. Minneapolis-St. Paul logistics corridors anchor Cardinal Health distribution density for integrated delivery network procurement.
Germany
Ambulatory surgical centers expand outpatient wound care volumes as post-acute protocols shift irrigation maintenance outside inpatient wards. EU MDR documentation requirements extend CE marking timelines by 40-60%. Baden-Württemberg industrial clusters concentrate gamma irradiation sterilization services for manufacturers serving European markets.
Japan
Specialized enteral feeding protocols in surgical suites demand piston syringe precision with ±5% volume tolerance. METI-influenced standards shape catheter-tip design preferences. Osaka-Kobe manufacturing zones anchor Terumo Corporation production for domestic surgical supply chains.
India
CDSCO tightens import inspections on disposable syringe lots, redirecting procurement toward domestic BIS-certified manufacturers. Price elasticity constrains pass-through of medical-grade polypropylene resin volatility. Gujarat pharmaceutical manufacturing corridors expand injection molding capacity for regional hospital supply.
United Kingdom
NHS procurement frameworks favor suppliers with validated aseptic processing lines and lot-level traceability systems. REACH compliance on medical-grade polymers extends material qualification timelines. Thames Valley logistics hubs concentrate distributor warehousing for London metropolitan hospital networks.
Irrigation Syringe Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and precision molding. The vendor base compresses around three-to-five preferred suppliers per metropolitan network as group purchasing organization contracts consolidate. Two strategic archetypes dominate: vertically integrated manufacturers with captive sterilization capacity, and specialized fabricators with catheter-tip design expertise. Competitive moves center on logistics density expansion and ISO 7886 harmonization investments that reduce SKU complexity across multi-regional footprints.
Among diversified medical technology conglomerates, BD and Medtronic occupy positions as platform integrators with system-tier procurement access. Cardinal Health exemplifies logistics-driven competitive positioning through distribution control over integrated delivery networks. Terumo Corporation anchors the specialized fabricator archetype, with its geographic name indicating Japanese industrial concentration. These three company structures represent the dominant competitive configurations: diversified conglomerate, supply chain integrator, and regional precision specialist.
| Leading Market Players |
|---|
| BD (Becton, Dickinson and Company) |
| Medtronic |
| Cardinal Health |
| Terumo Corporation |
| Smiths Medical |
| B. Braun Melsungen AG |
| Nipro Corporation |
| Baxter International Inc. |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Gamma irradiation undercapacity across Baden-Württemberg and Minneapolis-St. Paul corridors is compressing sterilization slot availability, forcing manufacturers to absorb capacity premiums or extend lead times while group purchasing organizations resist pass-through pricing.
Pricing Analysis
Configured-to-order catheter-tip piston syringes command 40-60% premiums over standard Luer-lock configurations in Japanese surgical suites. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 7886 certification grade and FDA 510(k) clearance pathway. Cost compression in standard polypropylene categories is intensifying because petrochemical feedstock volatility outpaces contract renegotiation cycles. Ambulatory surgical centers exhibit highest price sensitivity, while integrated delivery networks with captive logistics tolerate modest premiums for lot-level traceability.
Supply Chain Analysis
Contract manufacturing for medical-grade polypropylene barrel molding concentrates in Gujarat pharmaceutical corridors, Osaka-Kobe industrial zones, and Minneapolis-St. Paul logistics hubs. Injection molding draws from medical-grade polypropylene resin, platinum-cured silicone elastomers, and gamma irradiation sterilization services. Single-source vulnerability runs through ethylene oxide sterilization capacity clustering in Germany and the United States. Distribution runs through Cardinal Health and group purchasing organization consignment models dominating United States metropolitan hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through group purchasing organization contract awards covering 15-20 hospital facilities, fragmenting viable supplier bases to three-to-five preferred vendors per network.
For Market Incumbents: Insulate sterilization capacity through captive gamma irradiation investments or long-term offtake agreements with Baden-Württemberg service providers. Deepen backward integration into medical-grade polypropylene compounding to offset resin volatility squeezing standard syringe margins. Prioritize ISO 7886 harmonization investments that reduce SKU complexity across multi-regional footprints against emerging regional specialists. For New Entrants and Emerging Players: Build out simplified bulb syringe designs for patient-controlled home care environments in Germany and Japan where reimbursement codes are expanding. Target ambulatory surgical center procurement in United States Midwest and Southeast regions where logistics unbundling creates supplier entry points. Pursue direct-to-clinic distribution models bypassing consolidated distributor tiers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EU MDR convergence elevates compliance barriers that favor scaled incumbents with validated aseptic processing lines. Acquisition candidates should demonstrate captive sterilization capacity or specialized catheter-tip design expertise. Monitor CDSCO import inspection stringency and domestic BIS certification expansion as inflection signals for Indian manufacturing repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation demands extend pre-market timelines by 40-60% for renewal candidates. |
| Hospital System Partnership | Integrated delivery network procurement consolidation favors suppliers with RFID-enabled lot traceability systems. |
| Backward Integration | Captive medical-grade polypropylene compounding insulates margin compression from petrochemical volatility. |
| Software Companion Development | Bluetooth-enabled pressure sensors virtualize irrigation documentation for liability protection in ambulatory settings. |
| Reimbursement Strategy | Home care billing code expansion in Japan and Germany shifts procedure volume toward patient-controlled environments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and gamma irradiation capacity directories. Primary interviews engaged hospital purchasing committee directors, GPO contracts managers, biomedical engineers, aseptic processing technicians, and enteral feeding protocol specialists. Bottom-up triangulation across product-type unit economics and top-down validation against sterilization service capacity utilization anchored volume estimates.
Forecast inputs span product type segmentation by precision tolerance, end user procurement authority concentration, material grade certification tier, and application protocol standardization. Modeled dimensions include standard versus piston versus bulb syringe configurations, hospital versus home care versus clinic settings, and wound care versus hydration versus ear irrigation applications. CAGRs were derived from procedure volume elasticity to surgical discharge protocols and enteral feeding protocol expansion trajectories across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by domestic Indian manufacturers or accelerated FDA sterility guidance revisions would shift outcomes beyond modeled ranges. Quarterly review of GPO contract award announcements, CDSCO import inspection bulletins, and EU F-Gas Regulation packaging material qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Soil Mixer Market