
 Mulching Materials Market | 2026-2036
Mulching Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Mulching Materials Market Insights
Aftermarket soil amendment services is reshaping margin distribution in the mulching value chain. BASF SE leverages its polymer science portfolio to dominate engineered geotextile mulch derivatives. The Scotts Miracle-Gro Company anchors North American consumer channels through garden center partnerships. Novamont S.p.A. differentiates with compostable biopolymer formulations that meet industrial composting standards.
Mulching materials are surface-applied protective layers, typically 2-6 inches thick, composed of organic matter, mineral aggregates, or polymer films that moderate soil temperature, suppress weed germination, and reduce evaporative water loss. Organic mulches derived from bark, wood chips, and composted yard waste dominate volume sales due to low raw material cost and soil conditioning benefits. Biodegradable films represent the fastest-expanding material category as agricultural producers face disposal bans on conventional polyethylene sheeting. Synthetic mulches retain importance in high-value vegetable production where precision weed control justifies premium pricing.
The EPA regulates pesticide-contaminated mulch under FIFRA, while state-level departments of agriculture enforce pathogen suppression standards for compost-based products. The USDA's Natural Resources Conservation Service incentivizes conservation mulch practices through Environmental Quality Incentives Program contracts. Stakeholders must monitor evolving compostability certification requirements and water utility rebate programs that increasingly specify mulch depth and material origin for eligibility.
Market Dynamics
The Mulching Materials Market is being fundamentally restructured by municipal water conservation mandates that are converting discretionary landscaping spend into compliance-driven procurement, with drought emergency declarations in California, Arizona, and Nevada now specifying mulch depth requirements for irrigation reduction credits.
Growth Catalysts
- EPA Stormwater Runoff Controls:Tightened post-construction stormwater management rules under the National Pollutant Discharge Elimination System are mandating erosion control mulching for commercial and residential developments exceeding one acre.
- USDA Conservation Incentives:Environmental Quality Incentives Program contracts are covering up to 75% of material and installation costs for agricultural producers adopting conservation mulch practices on erosion-prone acreage.
- Biodegradable Film Technology:Thermoplastic starch formulations that meet ASTM D6400 compostability standards are eliminating polyethylene disposal costs for vegetable growers facing landfill bans on conventional plastic mulch.
Market Restraints
- Bark Supply Concentration:Pacific Northwest timber harvest reductions have concentrated raw bark supply among three regional processors, creating price volatility for hardwood mulch derivatives.
- Compost Pathogen Standards:State departments of agriculture in California, Florida, and Texas enforce divergent temperature-time protocols for compost-based mulches, fragmenting production certification costs.
- Synthetic Turf Substitution:Artificial grass installations for commercial landscaping are capturing municipal maintenance budgets that previously allocated to organic mulch replenishment cycles.
Strategic Opportunities
- Colorado River Basin States:Arizona, Nevada, and Utah water utility rebate programs are expanding eligible mulch specifications to include recycled rubber and mineral aggregate categories previously excluded from incentive calculations.
- Controlled Environment Agriculture:Vertical farming operations in urban corridors are adopting engineered geotextile mulches for precision moisture management in soilless growing systems.
- Industrial Composting Infrastructure:California's SB 1383 organic waste mandates are creating certified compost output streams that qualify for agricultural mulch applications under state carbon sequestration protocols.
Industry Challenges
- Compostability Certification Timeline:Biodegradable mulch film producers face 18-24 month validation periods for ASTM D6400 and EN 13432 dual certification required by municipal procurement specifications.
- Application Equipment Retrofit Costs:Agricultural contractors must upgrade pneumatic mulch laying equipment to handle fragile bio-based films without tearing, requiring capital outlays that compress contractor margins on fixed-price municipal contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mulching Materials Market |
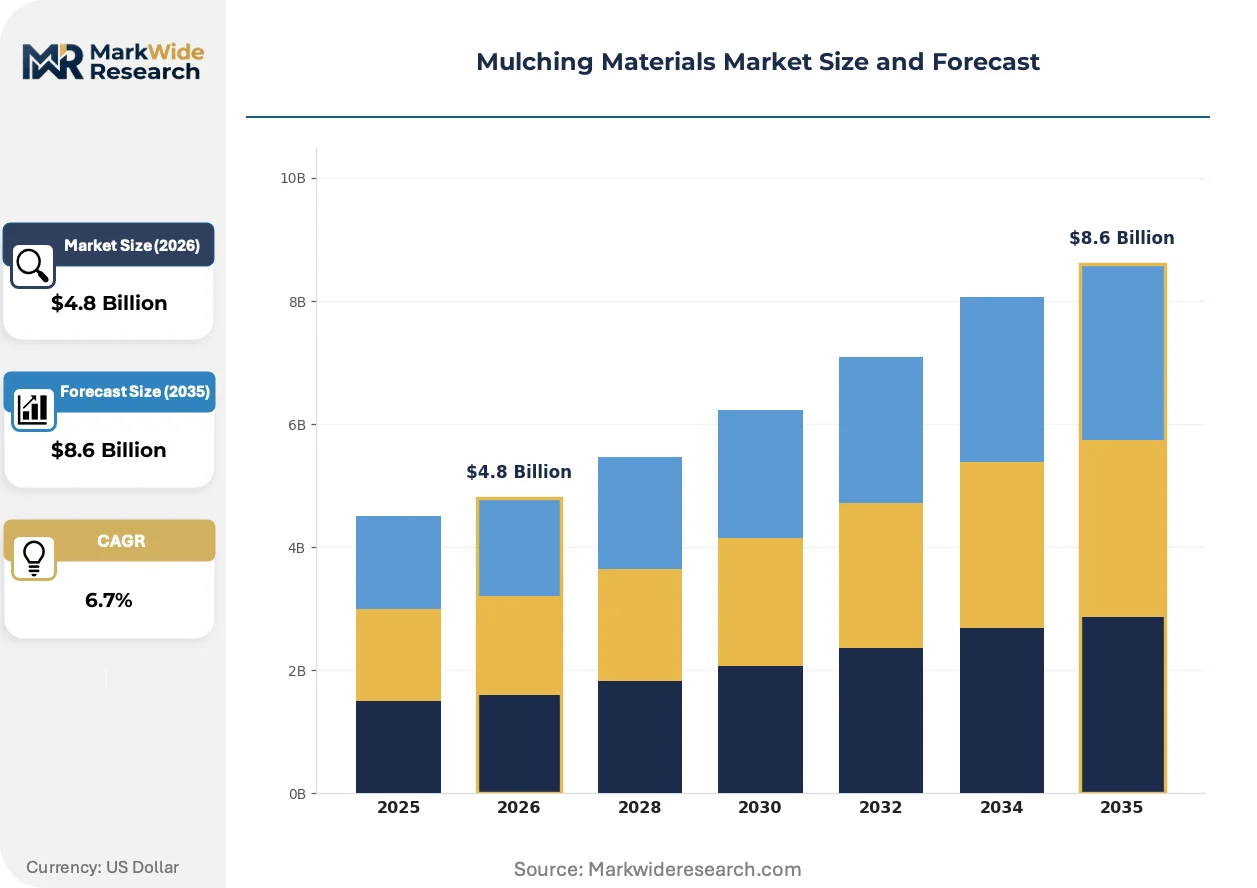
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Organic, Inorganic, Biodegradable, Synthetic Application: Home Gardening, Commercial Landscaping, Agriculture, Erosion Control End User: Professional Landscapers, Homeowners, Agricultural Producers, Government Agencies Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Wholesale Distributors |
| Companies Covered | The Scotts Miracle-Gro Company, BASF SE, Novamont S.p.A., Ohio Mulch, Jolly Gardener, Cowart Mulch Products Inc., Bailey Bark Materials Inc., FKuR Kunststoff GmbH, RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mulching Materials Market Trends and Innovations
Material science advances and regulatory pressure on petroleum-based products are converging to accelerate formulation turnover, with performance benchmarks for water retention and weed suppression being rewritten by bio-based alternatives.
Photodegradable starch-polymer blend films are rendering obsolete conventional polyethylene sheeting in specialty crop production. Strawberry and tomato growers in California's Central Valley are converting acreage at rates exceeding 15% annually. The technology is rendering obsolete the established economics of plastic mulch disposal, previously a $200-400 per acre cost center now eliminated through soil-incorporation.
California's SB 1383 organic waste recycling mandates are diverting municipal yard trimmings from landfills into certified compost production streams. Landscape maintenance contractors must now source mulch products from state-approved composting facilities to maintain eligibility for water utility rebate programs. The regulation is compressing supply chains for conventional bark products while expanding compost-based mulch market share in municipal and commercial segments.
Landscape maintenance procurement is consolidating around performance-based specifications rather than material-type preferences. Municipal grounds departments and homeowner associations are awarding multi-year service contracts specifying weed suppression percentages and irrigation reduction targets rather than mandating specific mulch compositions. The shift is most visible in Arizona and Nevada where water authority rebate eligibility hinges on documented evapotranspiration reduction rather than material origin.
Mulching Materials Market Segmentation
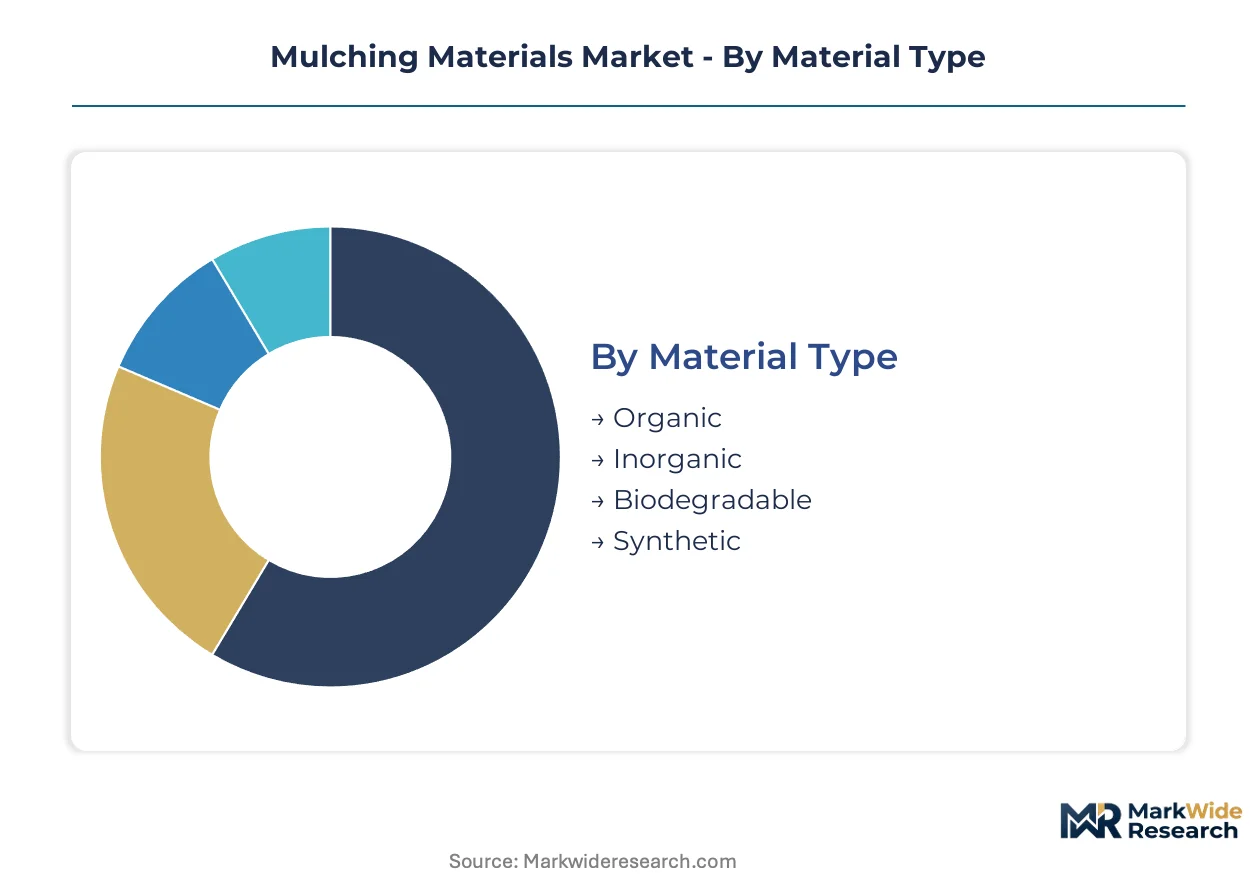
Material composition determines performance specifications across water retention, weed suppression, and soil temperature moderation. Application context dictates thickness requirements, installation methods, and replacement cycles. Procurement channels fragment by customer sophistication, with professional landscapers prioritizing bulk logistics and homeowners favoring bagged retail formats.
Material Type:
The use-case spectrum spans soil conditioning benefits in organic matter through precision moisture control in engineered polymers.
- Organic:Bark, wood chips, and composted yard waste deliver soil conditioning through gradual decomposition. Demand concentrates in California's drought-prone agricultural valleys where growers face severe irrigation restrictions and seek carbon sequestration credits.
- Biodegradable:Thermoplastic starch formulations meeting ASTM D6400 compostability standards eliminate polyethylene disposal costs. Vegetable growers in California's Central Valley are converting acreage at rates exceeding 15% annually as landfill bans on conventional plastic mulch tighten.
- Inorganic:Mineral aggregates and recycled rubber provide permanent weed suppression for commercial hardscapes.
- Synthetic:Polyethylene sheeting retains importance in high-value vegetable production where precision weed control justifies premium pricing.
Established volume favors Organic; emerging adoption favors Biodegradable.
Application:
Cost tier stratification separates commodity agricultural consumption from premium commercial landscaping specifications.
- Agriculture:Field-scale deployment requires mechanized installation and removal systems. Strawberry and tomato operations in California's Central Valley drive biodegradable film conversion as disposal economics shift.
- Commercial Landscaping:Municipal grounds departments specify performance-based contracts with documented evapotranspiration reduction targets. Arizona and Nevada water authority rebate eligibility hinges on measured irrigation savings rather than material composition.
- Erosion Control:EPA stormwater management guidelines mandate post-construction mulching for developments exceeding one acre.
- Home Gardening:Bagged retail products target aesthetic preferences with color-enhanced bark and pre-measured coverage calculations.
Volume concentration sits with Agriculture; margin expansion favors Commercial Landscaping.
End User:
Customer sophistication determines specification authority and procurement method.
- Agricultural Producers:USDA Environmental Quality Incentives Program contracts cover up to 75% of material and installation costs on erosion-prone acreage.
- Professional Landscapers:Bulk purchasing power and equipment fleets enable pneumatic application of engineered geotextiles.
- Government Agencies:Municipal procurement departments enforce compostability certification requirements and water utility rebate program specifications.
- Homeowners:Seasonal replenishment cycles favor garden center convenience over cost optimization.
Specification authority concentrates with Government Agencies; replenishment frequency favors Homeowners.
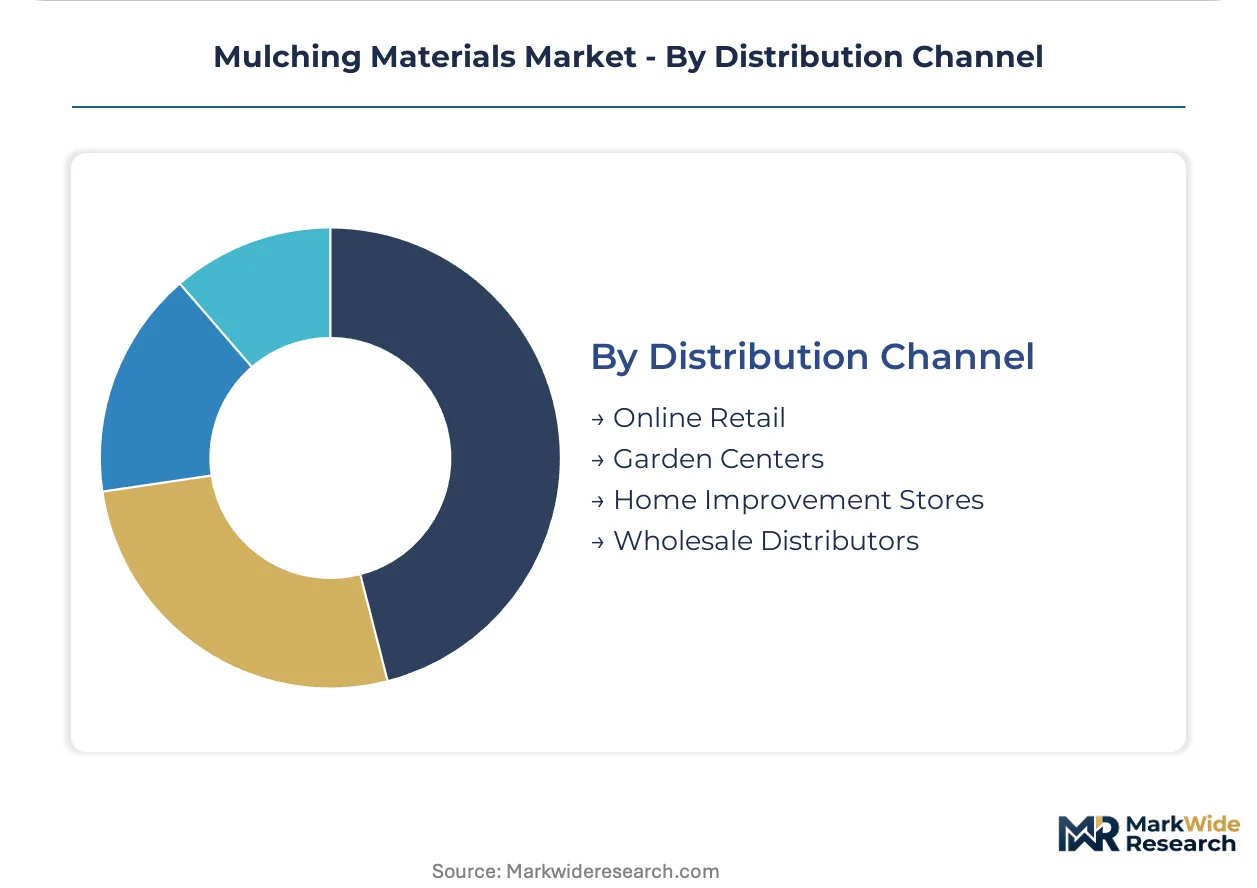
Distribution Channel:
Supply chain configuration separates bulk logistics for professional contractors from last-mile convenience for residential consumers.
- Wholesale Distributors:Regional processors in the Pacific Northwest concentrate raw bark supply, creating price volatility that flows through to contractor pricing.
- Garden Centers:The Scotts Miracle-Gro Company anchors North American consumer channels through exclusive partnerships and private label placement.
- Home Improvement Stores:Big-box retailers specify bagged product formats with standardized coverage claims and seasonal promotional calendars.
- Online Retail:Direct-to-consumer shipping constraints limit bulk organic products to specialty mineral mulches and lightweight synthetic alternatives.
Professional volume flows through Wholesale Distributors; consumer convenience favors Garden Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mulching consumption patterns diverge sharply by geography. The United States emphasizes stormwater compliance and agricultural conservation incentives. Germany prioritizes compostability certification and circular economy alignment. China scales biodegradable film manufacturing for domestic vegetable production.
United States
California's Central Valley strawberry and tomato growers convert acreage to biodegradable films at rates exceeding 15% annually. The EPA's National Pollutant Discharge Elimination System mandates erosion control mulching for commercial developments exceeding one acre. Phoenix and Las Vegas municipal procurement departments specify performance-based contracts with documented evapotranspiration reduction targets.
Germany
Industrial composting infrastructure expansion drives demand for EN 13432-certified biodegradable mulch films. The country's national packaging regulator enforces extended producer responsibility for agricultural plastic waste. Bavarian vegetable cooperatives pioneer thermoplastic starch formulations that eliminate polyethylene disposal costs.
China
Shandong Province plastic mulch replacement programs address soil contamination from legacy polyethylene sheeting. The Ministry of Ecology and Environment tightens agricultural film recycling mandates under dual carbon goals. Xinjiang cotton and tomato operations pilot soil-incorporating biodegradable alternatives to reduce labor-intensive retrieval.
India
Maharashtra and Gujarat horticulture belts adopt mulching for water-stressed pomegranate and grape cultivation. The country's central agricultural regulator promotes conservation mulch practices through subsidized equipment distribution. Karnataka's precision farming clusters integrate drip irrigation with polymer mulch films for export-oriented vegetable production.
Australia
Murray-Darling Basin irrigation restrictions concentrate mulching adoption in drought-prone stone fruit and almond orchards. The country's national water regulator ties allocation reductions to documented soil moisture conservation practices. Queensland sugar cane operations expand trash blanketing—residue mulching—as an alternative to pre-harvest burning.
Mulching Materials Market Competitive Landscape
Capability concentration sits with polymer science specialists; scale advantage sits with consumer distribution networks. The vendor base separates into three tiers: multinational chemical conglomerates with materials R&D infrastructure, regional bark processors controlling raw fiber supply, and specialty biopolymer developers securing compostability certifications. Dominant competitive moves include backward integration into raw bark supply and technology licensing partnerships for biodegradable film formulations.
Among polymer science specialists, BASF SE and Novamont S.p.A. exemplify the capability-driven tier through their respective positions in engineered geotextiles and compostable biopolymers. The Scotts Miracle-Gro Company anchors the consumer-facing segment through garden center channel dominance. Regional processors including Ohio Mulch and Cowart Mulch Products Inc. occupy positions tied to Pacific Northwest and Southeast timber supply basins respectively.
| Leading Market Players |
|---|
| The Scotts Miracle-Gro Company |
| BASF SE |
| Novamont S.p.A. |
| Ohio Mulch |
| Jolly Gardener |
| Cowart Mulch Products Inc. |
| Bailey Bark Materials Inc. |
| FKuR Kunststoff GmbH |
| RKW Group |
| Others |
Pricing and Supply Chain Analysis
Pacific Northwest timber harvest reductions concentrate raw bark supply among three regional processors, creating price volatility that compresses contractor margins and fragments procurement strategies across organic and synthetic product tiers. This single-source dependency forces buyers into long-term offtake agreements or premium spot purchases while reshaping distribution networks toward recycled rubber and mineral aggregate alternatives.
Pricing Analysis
Long-term municipal service contracts dominate commercial landscaping procurement, with performance-based specifications replacing material-type mandates and compressing price differentiation between organic and engineered alternatives. Certification grade for ASTM D6400 compostability and volume scale drive tier spreads, while cost compression in biodegradable films intensifies as landfill bans on polyethylene sheeting tighten. Agricultural producers exhibit highest price sensitivity due to USDA EQIP reimbursement caps, whereas controlled environment agriculture operations show lowest sensitivity given precision moisture control requirements.
Supply Chain Analysis
Upstream feedstock from Pacific Northwest timber operations, German industrial composting facilities, and Shandong Province biopolymer plants anchors global material flows. Raw bark, thermoplastic starch resins, and recycled rubber granules constitute critical inputs, with single-source vulnerability concentrated in Pacific Northwest hardwood fiber supply. Distribution runs through regional wholesale processors for professional contractors and garden center partnerships for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable film technology represents a high-growth disruption as ASTM D6400 certification becomes mandatory for municipal procurement, eliminating polyethylene disposal economics and rewiring competitive positioning across agricultural and commercial segments.
For Market Incumbents: Build certification moats by securing dual ASTM D6400 and EN 13432 validation ahead of 18-24 month approval timelines, while deepening backward integration into Pacific Northwest bark supply to defend against raw material concentration. Synthetic mulch producers face substitution threat from soil-incorporating starch-polymer blends; counter by anchoring high-value vegetable production through precision weed control performance guarantees. For New Entrants and Emerging Players: Pursue Colorado River Basin water utility rebate programs as the most penetrable geography, where expanded mulch specifications now include recycled rubber and mineral aggregates previously excluded from incentive calculations. Target controlled environment agriculture operations in urban corridors with engineered geotextile formulations for soilless growing systems, leveraging direct technical sales to bypass established wholesale distributor relationships. For Investors and Strategic Acquirers: California's SB 1383 organic waste mandates reshape the acquisition landscape by certifying compost output streams for agricultural carbon sequestration protocols, creating asset value in state-approved composting infrastructure. Long-term viability centers on exposure to municipal water conservation compliance spend rather than discretionary landscaping cycles. Watch biodegradable film conversion rates in California's Central Valley as the inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Bark Supply | Captive fiber sourcing from Pacific Northwest timber operations mitigates price volatility exposure. |
| Dual Certification Investment | ASTM D6400 and EN 13432 validation unlocks municipal procurement eligibility across California and Germany. |
| Performance-Based Service Contracts | Evapotranspiration reduction guarantees align with Arizona and Nevada water authority rebate specifications. |
| Biopolymer Formulation Partnerships | Thermoplastic starch technology licensing accelerates product development timelines for vegetable growers. |
| Industrial Composting Facility Acquisition | SB 1383-certified output streams qualify for agricultural carbon sequestration credit programs. |
Research Methodology
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings, combining primary interviews with municipal procurement officers, agricultural extension specialists, landscape maintenance contractors, and biopolymer R&D directors with secondary validation from EPA stormwater guidance documents, USDA EQIP program records, state composting facility certifications, and customs bark import statistics. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates.
Calibration against historical adoption curves for polyethylene mulch displacement and municipal water rebate program enrollment shapes the analytical framework across the projection horizon. Segmentation dimensions include material composition, application context, end-user sophistication, and distribution channel configuration, with CAGRs derived from regression analysis of conservation incentive funding trajectories and biodegradable film manufacturing capacity announcements.
Sensitivities concentrate around Pacific Northwest timber harvest policy revisions, compostability certification timeline delays, and synthetic turf substitution rates in commercial landscaping. Forecasts reflect documented assumptions regarding municipal water conservation mandate expansion; material shifts in Colorado River Basin drought emergency declarations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Nonwoven Crop Cover Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Global Agriculture Nets Market