
 Nonwoven Crop Cover Market | 2026-2036
Nonwoven Crop Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Crop Cover Market Intelligence
Asset-light leasing and project finance models for agricultural inputs are reshaping competitive dynamics in nonwoven crop covers, lowering capital barriers for smaller commercial growers. Berry Global Group leverages its North American manufacturing scale to sustain cost leadership in bulk polypropylene supply. DuPont de Nemours anchors premium positioning through advanced UV stabilization chemistry. Mitsui Chemicals differentiates via specialized spunbond lines serving Asian horticulture markets.
Nonwoven crop covers are engineered sheet structures of thermally or mechanically bonded fibers, typically polypropylene spunbond nonwovens with basis weights between 15 and 50 grams per square meter, designed to modulate temperature, moisture, and pest exposure for protected cultivation. UV stabilized covers dominate volume due to their multi-season durability and predictable replacement cycles, while biodegradable covers represent the fastest-growing material trajectory as waste regulations tighten across agricultural regions. Thermal covers command premium pricing in early-season frost protection, where performance thresholds determine crop survival rather than yield optimization alone.
EPA agricultural plastic waste guidelines and the EU Green Deal's Farm to Fork framework are elevating compliance costs for conventional polyethylene mulch alternatives, redirecting procurement toward certified biodegradable nonwovens. China's MEE standards on soil contamination and agricultural film recycling impose technical barriers that favor suppliers with verified compostability credentials. Stakeholders must monitor evolving biodegradability certification protocols and regional subsidy structures to align product portfolios with shifting compliance thresholds.
Market Dynamics
Climate volatility and the EU Green Deal's Farm to Fork strategy are converging to restructure agricultural cover procurement, redirecting commercial growers from conventional polyethylene mulch toward certified biodegradable nonwovens with verified compostability credentials.
Growth Catalysts
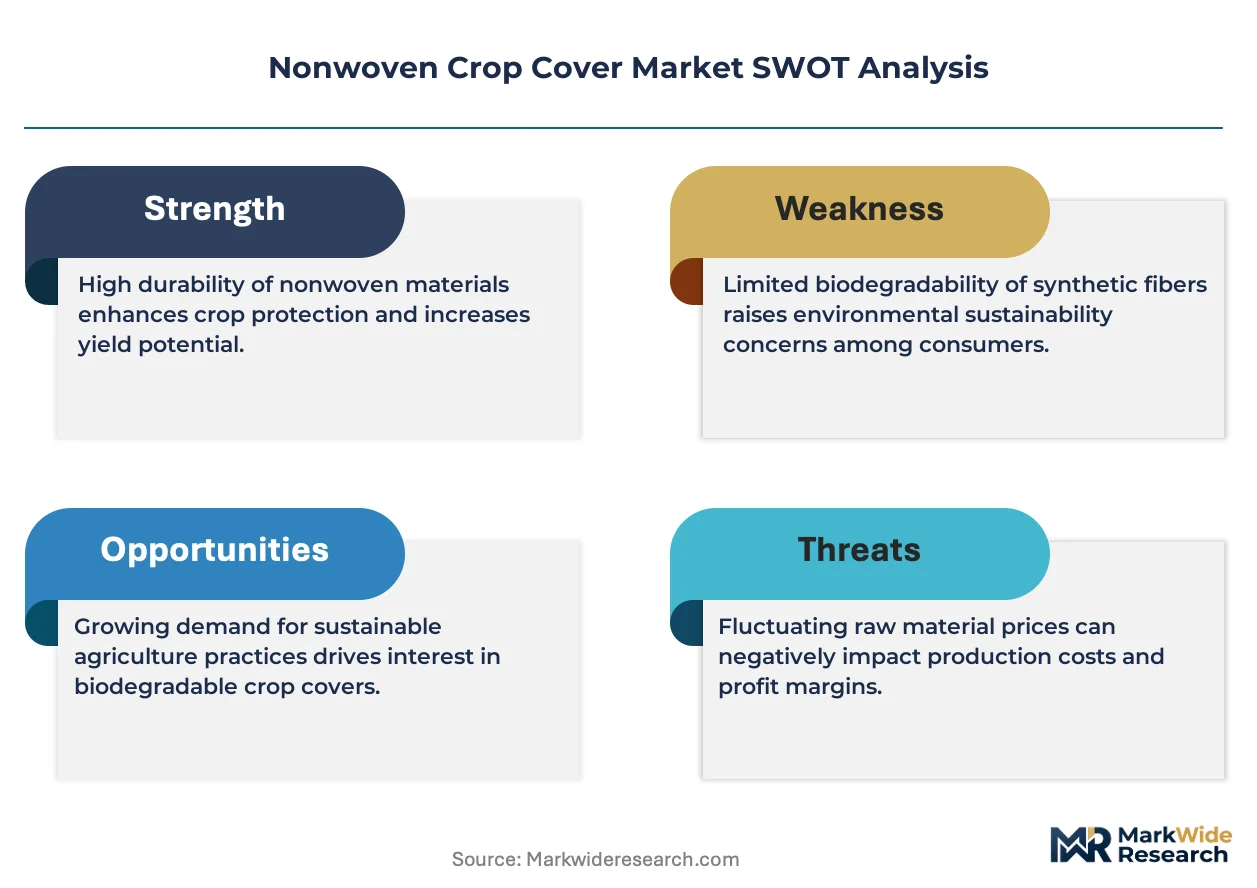
- EU Green Deal Farm to Fork framework:Mandatory reduction targets for agricultural plastic waste are accelerating procurement of biodegradable nonwoven alternatives across open-field vegetable operations in France, Spain, and Italy.
- Spunbond polypropylene UV stabilization:Multi-season durability and predictable replacement cycles are driving volume concentration among commercial growers managing frost protection across China's Shandong province.
- Provincial modernization subsidies:China's Jiangsu province is scaling protected-area horticulture infrastructure, directly stimulating demand for thermal covers in early-season cultivation.
Market Restraints
- Propylene feedstock volatility:Polypropylene resin prices fluctuate with naphtha-cracker economics, compressing margin stability for spunbond manufacturers without backward integration into monomer supply.
- Biodegradability certification bottlenecks:China's MEE standards on soil contamination and agricultural film recycling impose technical barriers that delay market entry for uncertified biodegradable alternatives.
- Polyethylene mulch legacy infrastructure:Existing mechanical laying equipment and collection systems for conventional mulch create switching friction that slows nonwoven penetration in mechanized row-crop operations.
Strategic Opportunities
- Asset-light leasing models:Project finance structures for agricultural inputs are lowering capital barriers for smaller commercial growers in Brazil's Minas Gerais state, expanding addressable demand beyond large-scale operations.
- Dual carbon goals alignment:China's national carbon neutrality targets are channeling subsidy flows toward soil-carbon-sequestration practices that favor biodegradable cover adoption in protected cultivation.
- Precision agriculture convergence:Integration of sensor-enabled microclimate monitoring with adjustable nonwoven covers is creating premium service bundles for high-value horticulture in the Netherlands' Westland cluster.
Industry Challenges
- Compostability testing capacity constraints:Limited accredited laboratory infrastructure for EN 13432 and ASTM D6400 certification is extending product validation timelines and delaying commercial launches.
- Spunbond line reconfiguration costs:Retrofitting existing thermal bonding equipment for biodegradable polymer grades requires substantial capital expenditure that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Crop Cover Market |
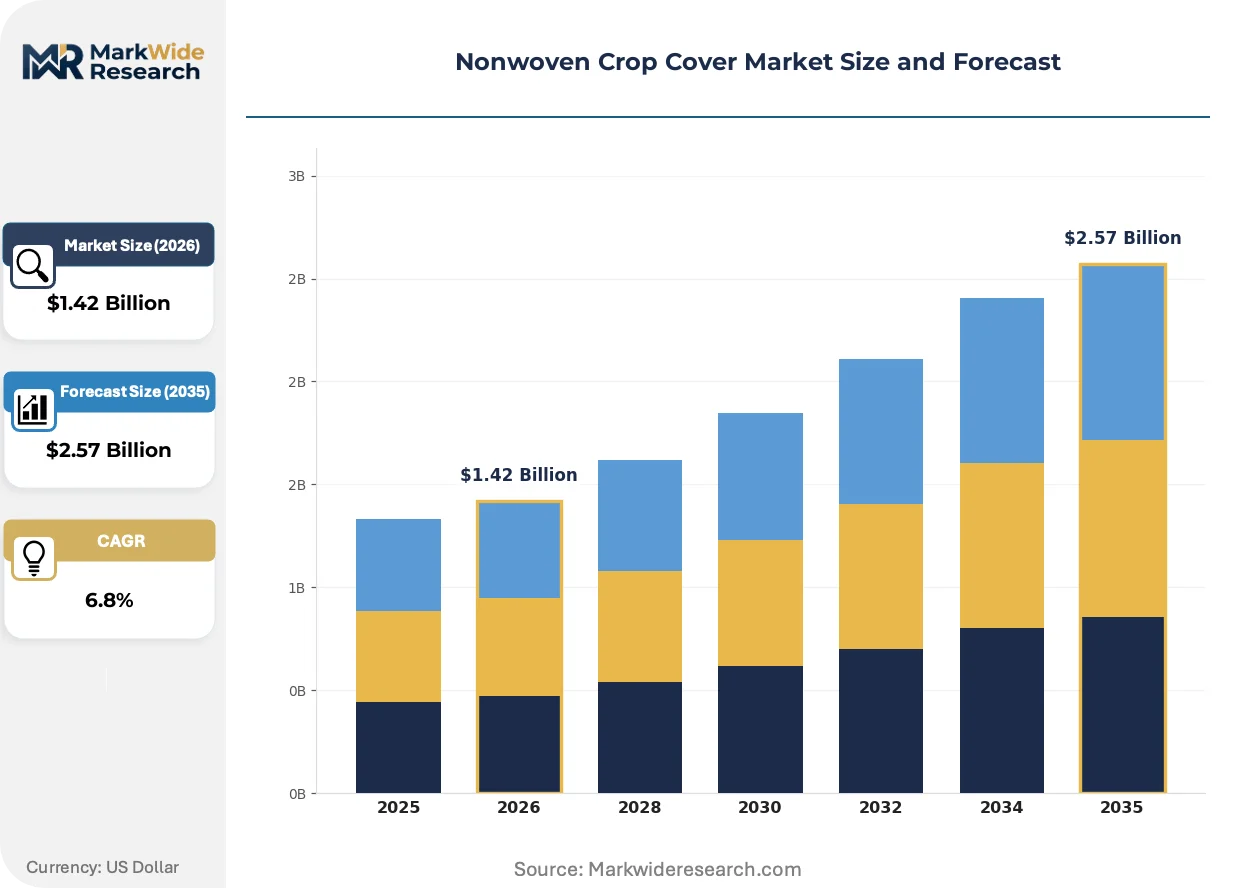
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Covers, UV Stabilized Covers, Thermal Covers, Spin-dyed Covers Material: Polypropylene, Polyester, Cotton, Recycled Fibers Application: Vegetable Protection, Fruit Cultivation, Seed Germination, Soil Moisture Retention End User: Farmers, Agricultural Cooperatives, Horticulturists, Commercial Growers |
| Companies Covered | Kimberly-Clark Corporation, Mitsui Chemicals, Berry Global Group, Glatfelter Corporation, Kolon Industries, DuPont de Nemours, Toray Industries, Ahlstrom, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Crop Cover Market Strategic Shifts & Innovations
Material science advances and regulatory compliance architectures are actively restructuring competitive positioning in agricultural nonwovens, with chemistry differentiation and service-model innovation emerging as primary vectors of value capture.
Multi-layer spunbond-meltblown-spunbond (SMS) composite structures are migrating from medical and hygiene applications into premium crop cover segments requiring combined thermal insulation and moisture vapor transmission control. Large-scale greenhouse operators in Almeria, Spain are piloting these structures for frost protection in high-value berry cultivation. The technology is migrating from industrial hygiene markets into agricultural premium tiers, compressing the performance gap between commodity nonwovens and woven alternatives.
REACH restrictions on persistent organic pollutants and microplastic shedding are tightening specifications for UV stabilizer chemistries used in agricultural nonwovens. ECHA's evolving substance evaluation criteria are forcing reformulation of conventional hindered amine light stabilizers toward bio-based alternatives with lower environmental persistence. European cover suppliers are accelerating partnerships with specialty chemical firms to secure next-generation stabilizer supply ahead of anticipated authorization sunsets.
Direct contracting between nonwoven manufacturers and grower cooperatives is displacing traditional agricultural distributor networks in high-volume vegetable production regions. Berry packing associations in California's Salinas Valley are negotiating collective procurement agreements that bundle cover supply with technical advisory services. This channel restructuring is most visible in concentrated production clusters where buyer scale supports dedicated account management and just-in-time logistics.
Nonwoven Crop Cover Market Segmentation
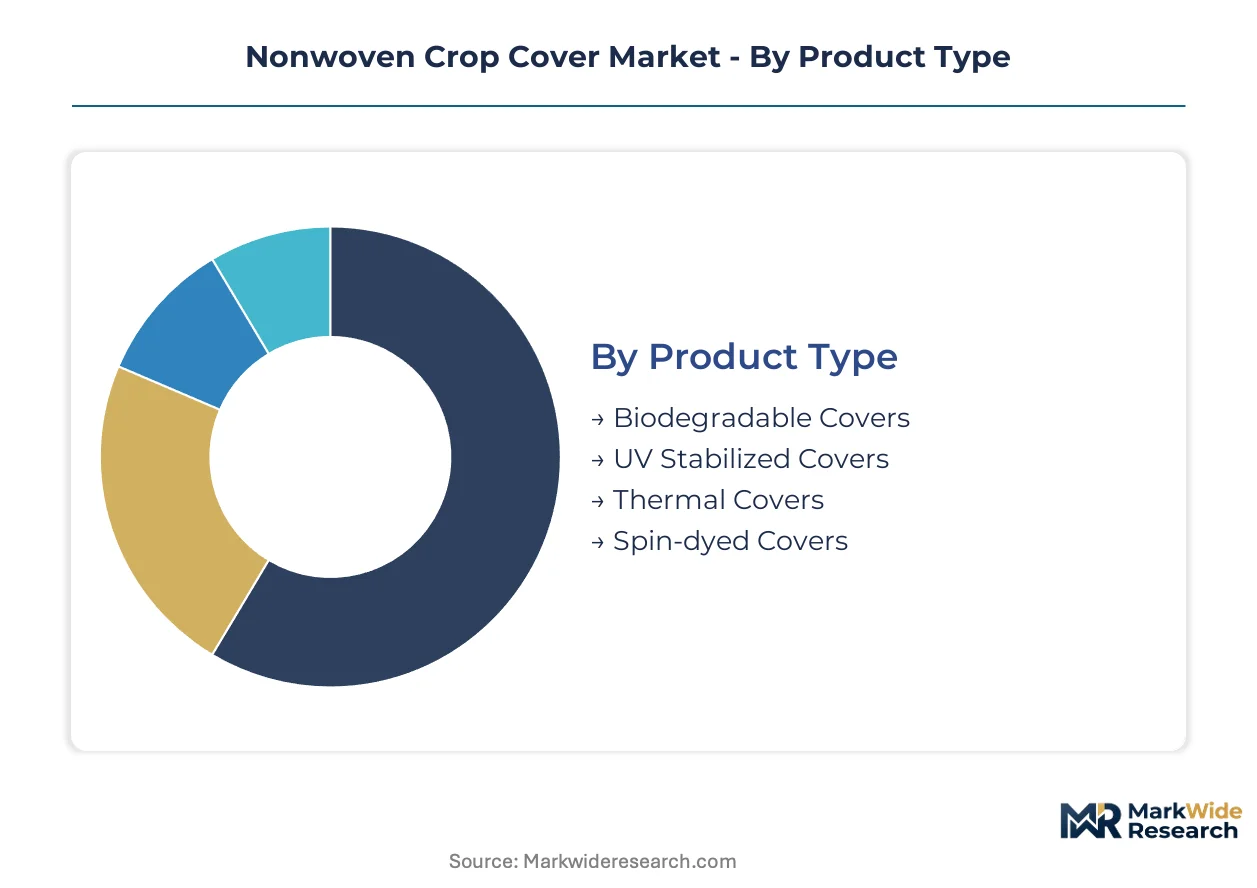
Nonwoven crop cover procurement varies sharply across grower scale and cultivation intensity, with after-sales technical support requirements driving supplier selection in premium segments. Material specifications and regional regulatory compliance further fragment sourcing patterns across commercial vegetable operations and protected horticulture clusters.
Product Type:
After-sales service intensity peaks with biodegradable covers, where compostability verification and soil-health monitoring require ongoing supplier engagement.
- UV Stabilized Covers:Multi-season polypropylene spunbond constructions with hindered amine light stabilizers deliver predictable replacement cycles. Demand concentrates in China's Shandong province, where commercial pepper and tomato growers prioritize frost protection durability over single-season economics.
- Biodegradable Covers:Certified compostable grades using polylactic acid or starch-blend polymers meet EN 13432 and ASTM D6400 protocols. Procurement is accelerating in France's Provence-Alpes-Côte d'Azur region as the EU Green Deal's Farm to Fork waste reduction mandates tighten enforcement.
- Thermal Covers:Heavier basis-weight nonwovens engineered for early-season temperature modulation in berry cultivation.
- Spin-dyed Covers:Solution-pigmented fibers eliminating post-production dyeing for color-coded crop management systems.
UV stabilized covers hold the largest share; momentum sits with biodegradable alternatives.
Material:
Cost tier positioning separates commodity resin supply from specialty polymer grades commanding technical service premiums.
- Polypropylene:Spunbond grades dominate volume through naphtha-cracker economics and established thermal bonding infrastructure. Berry Global Group and Mitsui Chemicals anchor supply security for North American and Asian horticulture markets respectively.
- Recycled Fibers:Post-industrial and post-consumer polyester feedstocks are gaining procurement traction in the Netherlands' Westland greenhouse cluster, where circularity certifications unlock premium retailer contracts.
- Polyester:Higher tenacity fibers for mechanical laying equipment compatibility in large-scale row-crop operations.
- Cotton:Natural fiber alternatives for organic certification compliance in specialty vegetable segments.
Polypropylene retains volume leadership; recycled fibers are expanding most quickly.
Application:
Application-driven specification requirements determine margin structure, with vegetable protection commanding the most intensive technical advisory relationships.
- Vegetable Protection:Open-field brassica and leafy green operations in Spain's Almería province deploy UV stabilized covers for pest exclusion and moisture retention. ECHA's evolving REACH restrictions on microplastic shedding are forcing reformulation timelines for conventional stabilizer chemistries.
- Fruit Cultivation:High-value berry operations in California's Salinas Valley integrate SMS composite structures for combined thermal insulation and vapor transmission control.
- Seed Germination:Lightweight spunbond grades for nursery propagation requiring precise moisture management.
- Soil Moisture Retention:Intermediate basis-weight covers for water-stressed cultivation zones.
Vegetable protection generates the highest service intensity; fruit cultivation delivers the steepest expansion trajectory.
End User:
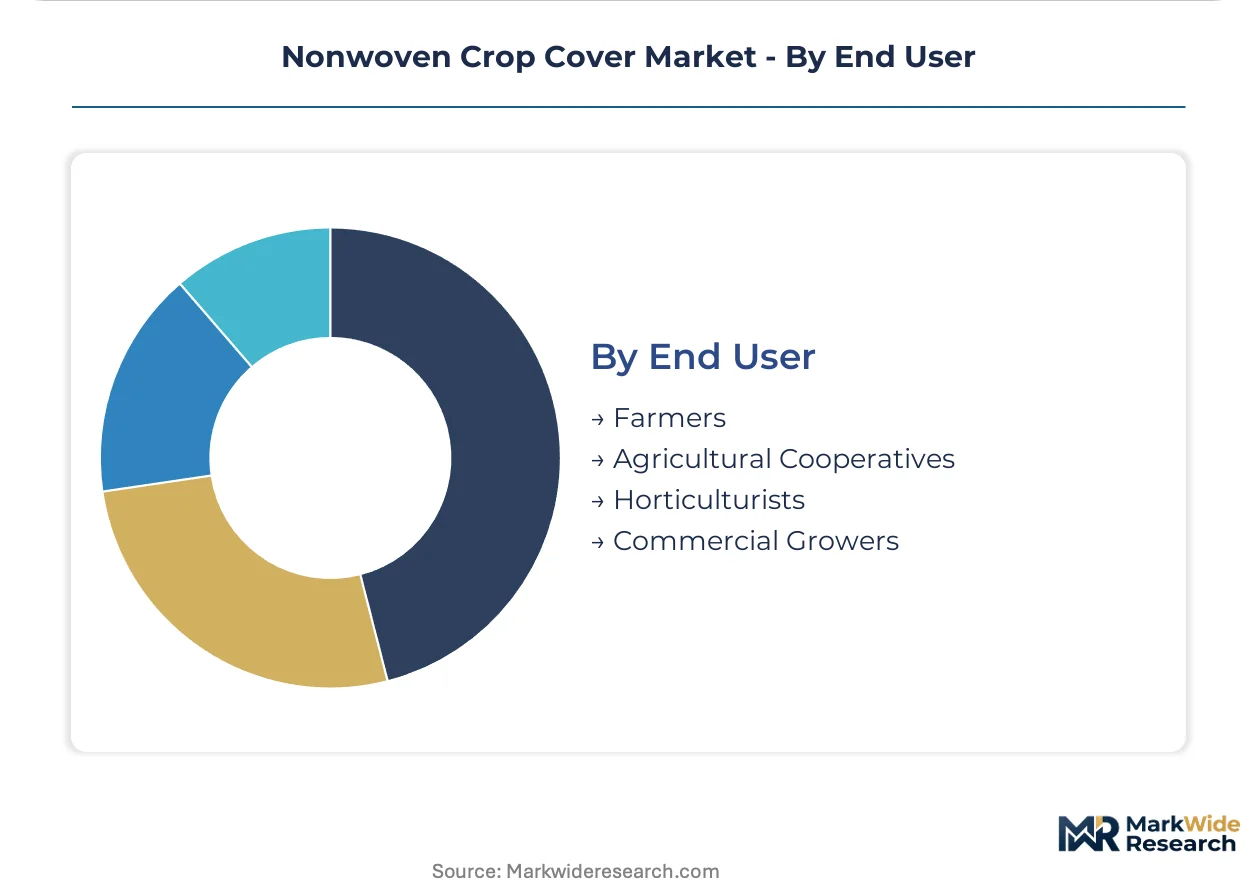
Customer type determines contract structure, with agricultural cooperatives enabling collective procurement leverage unavailable to fragmented farmer bases.
- Commercial Growers:Large-scale operations in Brazil's Minas Gerais state are adopting asset-light leasing models for cover procurement, lowering capital barriers through project finance structures. Direct manufacturer contracting is displacing traditional distributor networks in concentrated production clusters.
- Agricultural Cooperatives:Berry packing associations in California negotiate bundled supply agreements combining cover provision with microclimate monitoring advisory services.
- Farmers:Individual operators dependent on provincial subsidy programs for protected-area horticulture infrastructure.
- Horticulturists:Specialized greenhouse operators requiring precision-grade SMS composites for climate control.
Commercial growers represent the largest addressable base; cooperatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in nonwoven crop covers tilt toward net-import positions in protected horticulture clusters lacking indigenous spunbond capacity. Export competitiveness concentrates where polypropylene feedstock integration meets established technical textile infrastructure.
China
Provincial modernization subsidies in Shandong and Jiangsu provinces are accelerating protected-area horticulture expansion. MEE standards on soil contamination and agricultural film recycling impose technical barriers favoring certified compostable alternatives. The Yangtze River Delta cluster hosts concentrated spunbond manufacturing serving domestic vegetable protection demand.
United States
California's Salinas Valley berry packing associations are negotiating collective procurement agreements bundling cover supply with advisory services. EPA agricultural plastic waste guidelines elevate compliance costs for conventional polyethylene mulch alternatives. Direct manufacturer contracting is displacing traditional distributor networks in concentrated vegetable production clusters.
Spain
Almería province greenhouse operators are piloting SMS composite structures for high-value berry cultivation frost protection. The EU Green Deal's Farm to Fork waste reduction mandates are tightening enforcement across open-field vegetable operations. REACH restrictions on microplastic shedding force reformulation timelines for conventional UV stabilizer chemistries.
France
Provence-Alpes-Côte d'Azur region procurement is accelerating toward EN 13432-certified biodegradable covers as Farm to Fork enforcement intensifies. ECHA's evolving substance evaluation criteria are forcing bio-based stabilizer partnerships ahead of authorization sunsets. Field vegetable cooperatives in the region are consolidating cover purchasing through direct manufacturer relationships.
Brazil
Minas Gerais commercial growers are adopting asset-light leasing models for agricultural input procurement. Project finance structures lower capital barriers for smaller operations expanding protected cultivation. ANVISA regulatory frameworks for agricultural inputs influence import certification timelines for foreign cover suppliers.
Nonwoven Crop Cover Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in resin supply and stabilizer chemistry. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into monomer supply, mid-scale spunbond specialists with regional manufacturing footprints, and niche biodegradable polymer developers. Dominant competitive moves include capacity expansion in Asian horticulture corridors and strategic partnerships securing next-generation UV stabilizer supply ahead of regulatory sunsets.
Among North American chemical conglomerates, DuPont de Nemours and Berry Global Group exemplify contrasting archetypes—premium chemistry positioning versus bulk supply scale. Mitsui Chemicals represents the Asian specialist tier with dedicated spunbond lines. These three anchors illustrate how geographic manufacturing footprint and feedstock integration separate competitive positions in agricultural nonwovens procurement.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Mitsui Chemicals |
| Berry Global Group |
| Glatfelter Corporation |
| Kolon Industries |
| DuPont de Nemours |
| Toray Industries |
| Ahlstrom |
| Freudenberg Group |
| Others |
Cost & Logistics Intelligence
Polypropylene resin concentration in Gulf Coast petrochemical complexes and Yangtze River Delta naphtha-cracker corridors directly determines where margin pools accumulate across spunbond nonwoven tiers. Buyers downstream face divergent cost structures depending on feedstock integration geography.
Pricing Analysis
Commercial growers anchor contract structures across the nonwoven crop cover market. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in commodity spunbond grades is intensifying because naphtha-cracker economics transmit volatility directly to non-integrated converters. Smallholder cooperatives in Brazil's Minas Gerais state exhibit the highest price sensitivity, while Dutch greenhouse operators in the Westland cluster prioritize performance thresholds over unit economics.
Supply Chain Analysis
Propylene feedstock draws from integrated petrochemical complexes concentrated in the United States, China, and Saudi Arabia. Spunbond manufacturing rests on polypropylene resin, hindered amine light stabilizers, and thermal bonding equipment. Single-source vulnerability in certified compostable polymer grades creates bottlenecks for biodegradable cover suppliers. Distribution runs through agricultural cooperatives and direct manufacturer contracting in concentrated production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across biodegradable certification tiers as EU Green Deal enforcement creates compliance-driven niche demand. Regional regulatory divergence rewards specialized positioning over scale dominance.
For Market Incumbents: Entrench feedstock security through backward integration into polypropylene monomer supply or long-term offtake agreements with Gulf Coast crackers. Accelerate EN 13432 certification timelines ahead of ECHA authorization sunsets for conventional UV stabilizers. Channel control through direct grower cooperative relationships defends against distributor displacement. For New Entrants and Emerging Players: Establish a beachhead in biodegradable cover segments where compostability testing capacity constraints delay incumbent product launches. Target France's Provence-Alpes-Côte d'Azur region and China's Jiangsu province where Farm to Fork and MEE enforcement create procurement urgency. Lead with certified compostability credentials bundled with soil-health advisory services. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale spunbond specialists with regional manufacturing footprints and verified biodegradable polymer partnerships. Long-term viability centers on dual carbon goals alignment and circularity certification access. Watch for MEE standard revisions on agricultural film recycling as inflection indicators for Chinese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polypropylene supply insulates Berry Global Group from naphtha-cracker volatility. |
| Certification Investment | EN 13432 accreditation unlocks EU Green Deal procurement channels for biodegradable grades. |
| Regional Capacity Expansion | Dedicated spunbond lines in Shandong province position Mitsui Chemicals for Chinese horticulture demand. |
| Strategic Partnership | Bio-based stabilizer alliances with specialty chemical firms secure next-generation UV chemistry ahead of REACH restrictions. |
| Service Model Innovation | Asset-light leasing structures in Brazil expand addressable demand beyond large-scale commercial growers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial growers, agricultural cooperative procurement managers, spunbond plant engineers, and specialty chemical R&D directors. Secondary validation drew from customs trade databases, EPA agricultural plastic waste guidelines, EU Green Deal Farm to Fork framework documentation, and SEC filings of listed nonwoven manufacturers. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across the projection horizon.
Calibration against historical replacement cycle data and regional subsidy program disbursements anchored the analytical framework. Segmentation dimensions spanned product type, material grade, application intensity, and end-user scale across the modeling period. CAGRs were derived from fitted growth curves incorporating climate volatility indices and regulatory enforcement timelines. Industry-specific inputs included provincial modernization subsidy trajectories and compostability certification pipeline velocities.
Stress conditions across propylene feedstock volatility, biodegradability standard revision timelines, and agricultural plastic waste enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsidy continuity and certification capacity expansion. Cross-checking against Yangtze River Delta spunbond capacity utilization rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
US Agro Textile Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Silage Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Europe Agricultural Films Market