
 Silage Bags Market | 2026-2036
Silage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Silage Bags Market Outlook
The silage bags market is rebalancing as premium multi-layered barrier films with oxygen transmission rates below 5 cm³/m²/day separate from commodity-grade polyethylene options serving cost-sensitive feed lots. Berry Global leverages its blown film extrusion capabilities to sustain dominance in North American dairy supply chains. RKW Group anchors European demand through specialized 7-layer coextrusion technology that meets stringent barrier specifications. Grupo Armando Alvarez competes across Latin America with regionally optimized resin formulations designed for tropical humidity exposure.
Silage bags are cylindrical polyethylene or multi-polymer storage enclosures, typically 2.7–3.6 meters in diameter and 60–120 meters in length, manufactured through blown film extrusion with UV stabilizers to prevent photodegradation during outdoor exposure. Their primary purpose is anaerobic preservation of chopped forage crops by excluding oxygen to enable lactic acid fermentation. Multi-layered bags capture the fastest expansion as dairy farms prioritize reduced dry matter losses below 10% compared to 15–20% in traditional bunker storage. Vacuum sealed bags concentrate margin pools among specialty contractors serving high-value beef finishing operations where feed quality directly impacts carcass grading outcomes. Plastic bags remain the volume base across commodity cattle ranches in price-sensitive procurement environments.
The EPA regulates agricultural plastic waste disposal under Resource Conservation and Recovery Act provisions, while FDA oversight applies to silage bags contacting animal feed intended for dairy cattle producing human-consumption milk. USDA conservation programs increasingly incentivize improved feed storage infrastructure through Environmental Quality Incentives Program cost-sharing. Stakeholders must monitor evolving state-level extended producer responsibility legislation for agricultural plastics, as California and Wisconsin draft frameworks that would shift end-of-life collection costs upstream to manufacturers and distributors.
Market Dynamics
Multi-layered barrier film technology is compressing oxygen transmission thresholds below 5 cm³/m²/day, forcing commodity polyethylene producers into price-only competition while specialty coextrusion operators capture margin premiums from dairy operations prioritizing dry matter retention.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Cost-sharing incentives for improved feed storage infrastructure accelerate silage bag adoption across Upper Midwest dairy operations seeking reduced spoilage losses.
- Brazilian Mato Grosso cattle ranching:Large-scale beef operations replace bunker silos with vacuum-sealed systems to preserve forage quality through extended tropical rainy seasons.
- EU F-Gas Regulation compliance:REACH-mandated barrier specifications push European manufacturers toward 7-layer coextrusion films with enhanced permeability resistance.
Market Restraints
- Ethylene feedstock volatility:Crude oil price fluctuations directly compress polyethylene resin margins for blown film extrusion operations serving price-sensitive commodity feed lots.
- Extended producer responsibility legislation:California and Wisconsin draft frameworks shifting agricultural plastic end-of-life collection costs upstream to manufacturers and distributors.
- Mechanical bunker silo substitution:Concrete and steel storage systems with 20-plus year lifespans compete on total cost of ownership for capital-rich integrated dairy cooperatives.
Strategic Opportunities
- Indian dairy cooperative expansion:Amul and state-level milk federations present untapped demand for small-diameter silage bags suited to fragmented landholding patterns and monsoon-driven harvest compression.
- Biodegradable polymer convergence:Starch-based barrier layers combined with conventional polyethylene create compostable alternatives for organic-certified livestock operations facing plastic waste restrictions.
- Direct-to-farm digital channels:E-procurement platforms bypass traditional agricultural supply distributors, enabling specialty film manufacturers to capture margin from precision livestock farming adopters.
Industry Challenges
- Coextrusion technician scarcity:7-layer blown film operations require specialized polymer rheology expertise concentrated among aging European and North American engineering workforces.
- FDA-EPA dual compliance timelines:Animal feed contact safety validation and agricultural plastic waste disposal permitting create 18-to-24-month product launch cycles for modified resin formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silage Bags Market |
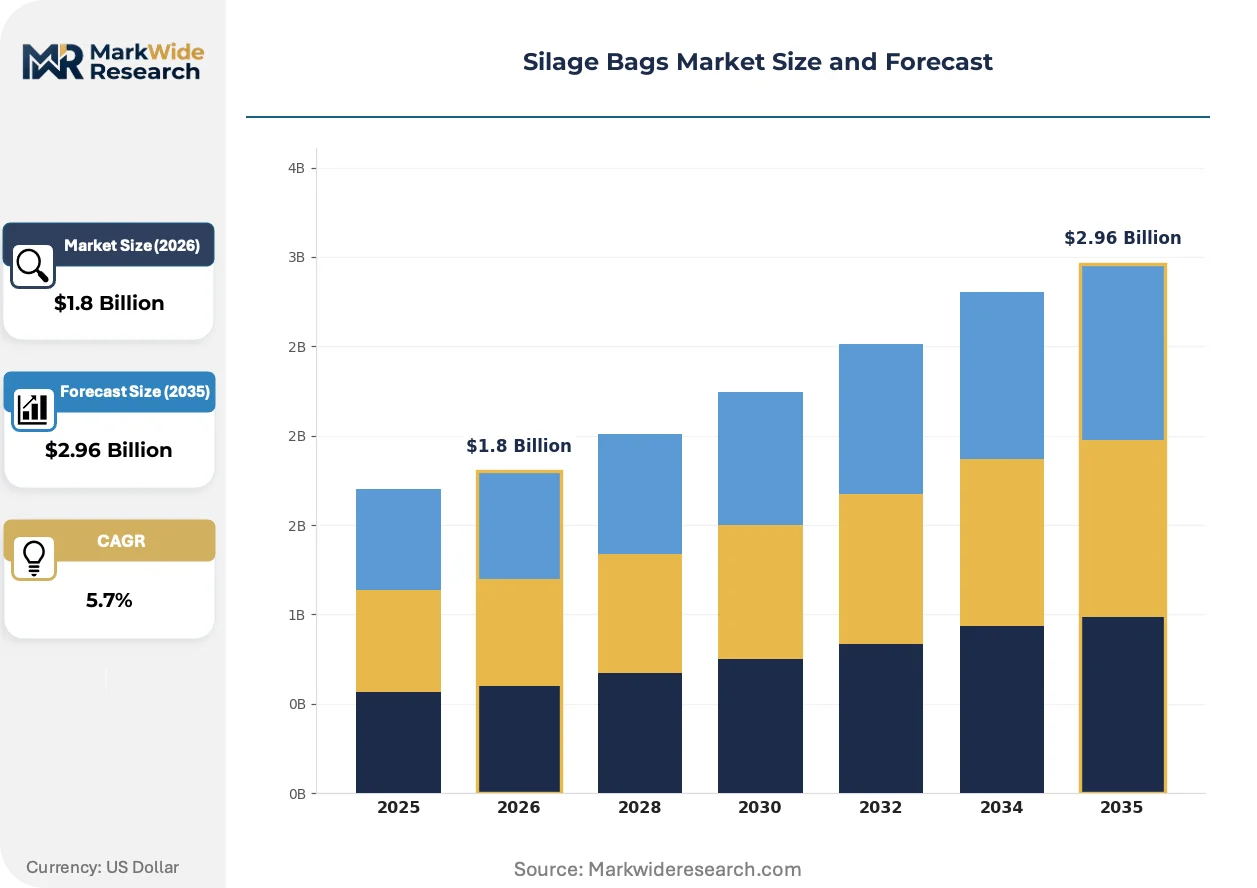
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Biodegradable Bags, Multi-layered Bags, Vacuum Sealed Bags End Use: Dairy Farms, Poultry Farms, Feed Lots, Cattle Ranches Thickness: 100 Microns, 125 Microns, 150 Microns, 200 Microns Application: Animal Feed, Crop Preservation, Fertilizer Storage, Forage Storage |
| Companies Covered | RKW Group, Berry Global, Dow Chemical, KSI Supply, RPC BPI Agriculture, Grupo Armando Alvarez, Trioplast, Silo Bags International Limited, Flex Pack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silage Bags Market Strategic Shifts
Barrier film engineering is compressing oxygen exclusion thresholds while regulatory pressure on agricultural plastic waste forces material science innovation toward recoverable and biodegradable alternatives.
Ethylene vinyl alcohol copolymer is integrating with linear low-density polyethylene substrates to create 9-layer barrier structures achieving oxygen transmission below 3 cm³/m²/day. Premium dairy operations in Wisconsin and the Netherlands adopt these configurations within 24-month replacement cycles. The technology is integrating vacuum-sealed bag systems into high-value beef finishing operations where carcass grading premiums justify 40% material cost premiums over commodity alternatives.
REACH authorization requirements for persistent organic pollutants are restricting certain UV stabilizer chemistries previously standard in agricultural film formulations. European compounders reformulate hindered amine light stabilizer packages to maintain 18-month field durability under revised ECHA substance restrictions. Multi-layer bag producers serving EU dairy exports face accelerated R&D cycles to maintain barrier performance while eliminating restricted additive packages.
Consolidated feedlot operators now specify outcome-based dry matter loss guarantees rather than material specifications in procurement contracts. Specialty contractors in Brazil's Pantanal region assume full spoilage risk, deploying vacuum-sealed systems with embedded oxygen sensors. This model concentrates margin among integrated service providers while compressing commodity film distributors to logistics-only roles.
Silage Bags Market Segmentation
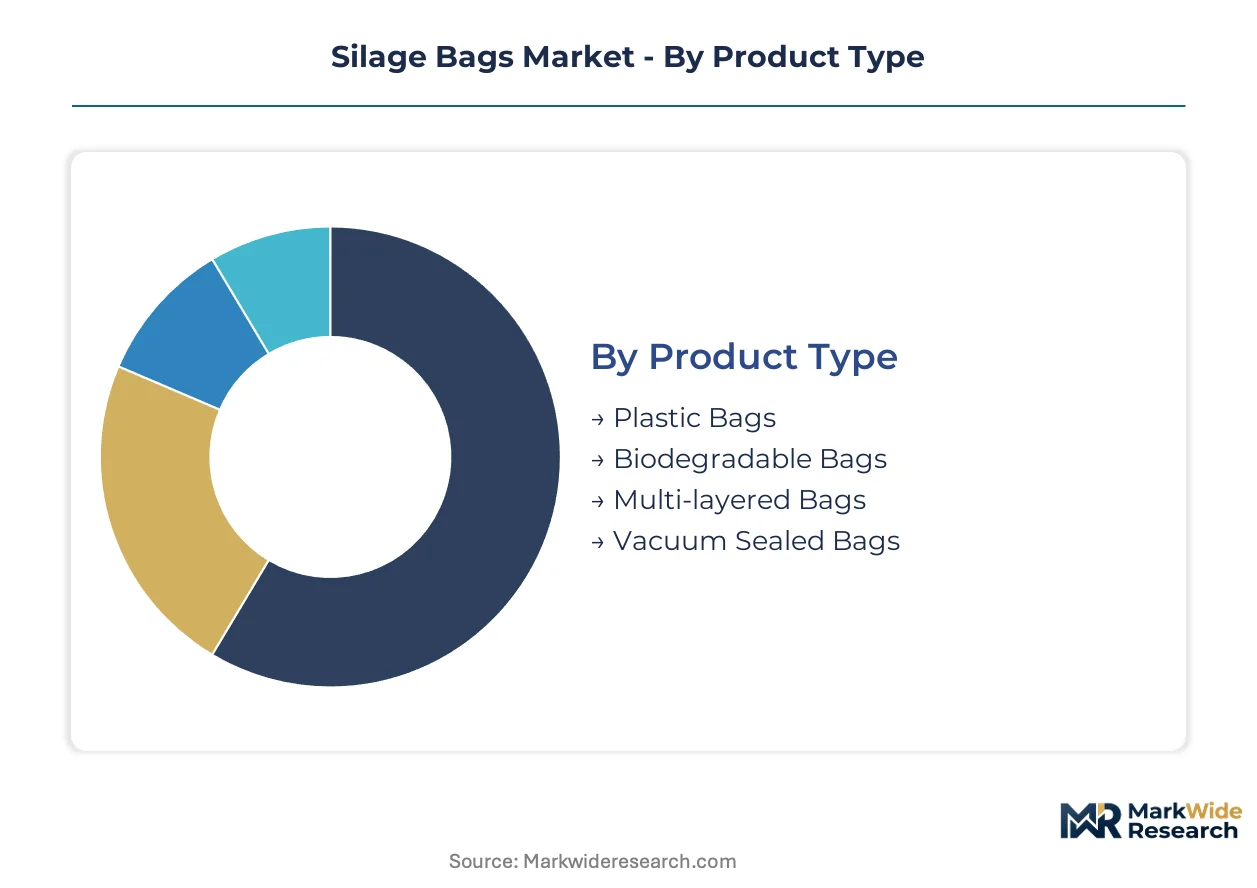
Silage bag segmentation reflects divergent technical requirements across storage duration, forage value, and environmental exposure. Product architecture choices directly determine oxygen exclusion performance and dry matter retention economics for end-users.
Product Type:
Integration depth separates standalone commodity formats from embedded multi-layer systems requiring specialized filling equipment.
- Multi-layered Bags:Seven to nine coextruded layers incorporating ethylene vinyl alcohol copolymer achieve oxygen transmission below 5 cm³/m²/day. Dairy operations in Wisconsin and the Netherlands specify these configurations where dry matter losses must stay under 10% to protect milk production economics.
- Plastic Bags:Standard polyethylene constructions with UV stabilizers serve commodity cattle ranches across price-sensitive procurement environments. These single-layer formats dominate volume placements in Brazil's Mato Grosso feedlots where capital constraints prioritize upfront cost over spoilage reduction.
- Vacuum Sealed Bags:Integrated pump systems extract residual air prior to heat-sealing, embedding mechanical components within the storage architecture. Brazilian Pantanal contractors deploy sensor-embedded variants assuming full spoilage risk under outcome-based service contracts.
- Biodegradable Bags:Starch-based barrier layers laminated to conventional polyethylene address organic-certified operations facing plastic waste restrictions. European compounders reformulate these constructions to maintain 18-month field durability under revised ECHA additive restrictions.
Volume placements concentrate in Plastic Bags; the faster expansion belongs to Multi-layered Bags.
End Use:
Customer scale and forage value determine specification intensity across livestock production systems.
- Dairy Farms:Upper Midwest operations expanding bag adoption seek reduced spoilage during variable weather patterns. USDA Environmental Quality Incentives Program cost-sharing accelerates infrastructure upgrades across Wisconsin and Minnesota cooperatives.
- Cattle Ranches:Large-scale beef finishing operations in Brazil's Mato Grosso state replace bunker silos with vacuum-sealed systems to preserve forage quality through extended tropical rainy seasons.
- Feed Lots:Consolidated operators now specify outcome-based dry matter loss guarantees rather than material specifications in procurement contracts.
- Poultry Farms:Smaller-diameter bag requirements suit fragmented landholding patterns in emerging dairy cooperative regions.
Revenue pools concentrate in Dairy Farms; Cattle Ranches are climbing the fastest as Brazilian ranching consolidates.
Thickness:
Material gauge selection balances puncture resistance against handling flexibility and resin cost exposure.
- 150 Microns:Mid-range specification balancing mechanical durability with extrusion efficiency serves standard dairy and beef operations across temperate climates.
- 200 Microns:Heavy-duty construction resists puncture from coarse forage and wildlife intrusion in extended outdoor storage applications.
- 125 Microns:Lighter gauge suits short-duration storage and mechanized filling systems where handling stress remains controlled.
- 100 Microns:Minimum viable thickness for protected indoor storage or rapid-turnover operations with minimal environmental exposure.
Procurement concentrates in 150 Microns; the steepest specification climb belongs to 200 Microns as climate volatility intensifies.
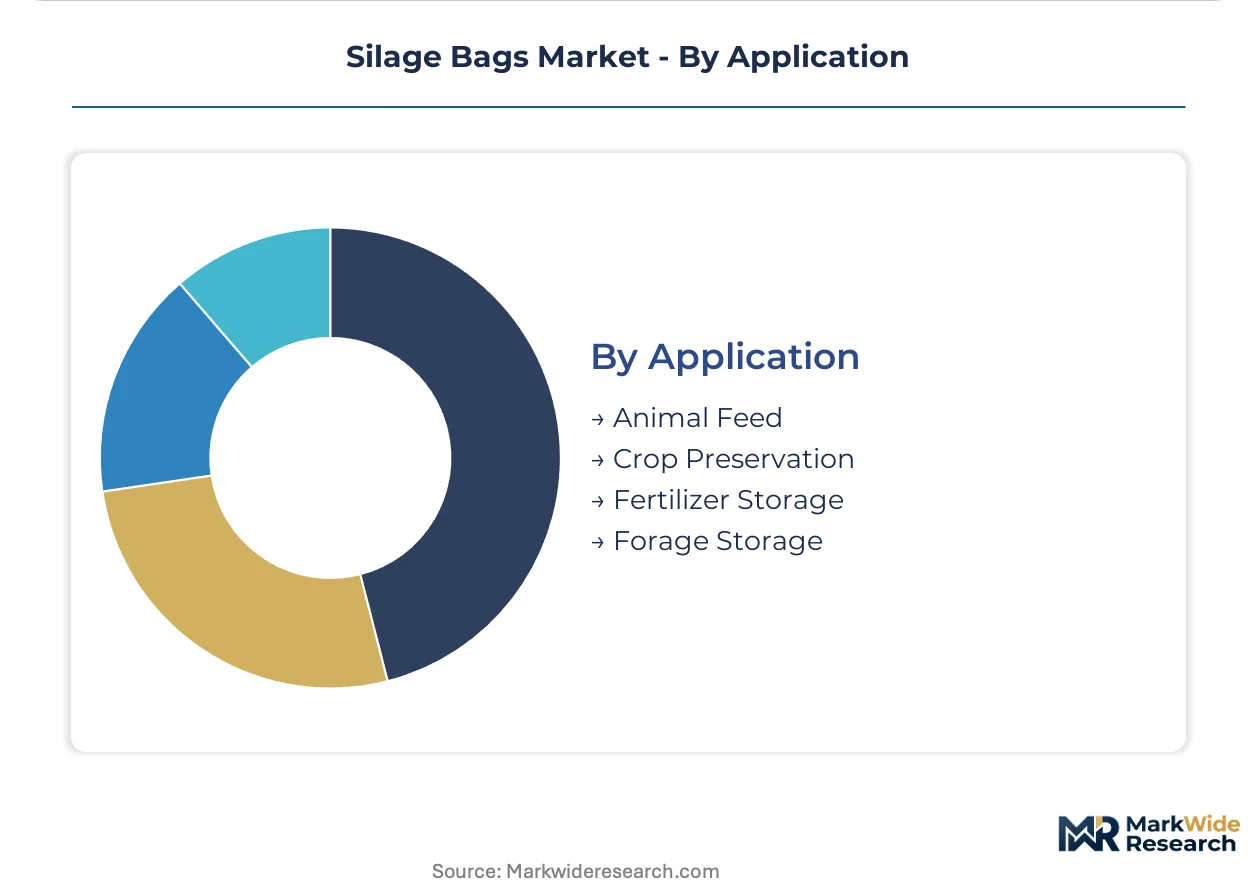
Application:
Use case diversification extends silage bag utility beyond traditional forage preservation into input protection and crop conditioning.
- Animal Feed:Primary application preserving chopped forage through anaerobic lactic acid fermentation excludes oxygen to maintain nutritional value for ruminant diets.
- Forage Storage:Dedicated haylage and silage preservation commands the majority of installed capacity across dairy supply chains.
- Crop Preservation:Moisture-sensitive grain and seed storage applications demand enhanced barrier performance against humidity ingress.
- Fertilizer Storage:Secondary application protecting hygroscopic inputs from caking and nutrient degradation in agricultural supply chains.
Volume concentrates in Animal Feed; Crop Preservation is gaining share fastest as regenerative agriculture expands cover crop retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's Fox River Valley anchors silage bag deployment, where dairy cooperatives expand vacuum-sealed storage infrastructure to combat erratic precipitation patterns disrupting traditional bunker operations.
United States
USDA Environmental Quality Incentives Program cost-sharing accelerates adoption across Minnesota and Wisconsin dairy belts. The EPA regulates agricultural plastic waste disposal under Resource Conservation and Recovery Act provisions. Wisconsin's Fox River Valley hosts concentrated infrastructure upgrades as cooperatives replace aging bunker systems.
Brazil
Mato Grosso cattle ranchers drive vacuum-sealed bag conversion to preserve forage through extended rainy seasons. ANVISA oversight applies to feed contact materials in beef supply chains destined for export markets. The Pantanal region concentrates specialty contractor activity where outcome-based spoilage guarantees dominate procurement.
Germany
Dairy operations in Lower Saxony specify 7-layer coextrusion films meeting EU F-Gas Regulation barrier standards. REACH compliance mandates reformulation of UV stabilizer packages under revised ECHA substance restrictions. The Münsterland dairy corridor anchors European demand for premium oxygen-exclusion systems.
Netherlands
Friesland dairy cooperatives prioritize dry matter retention below 10% through advanced barrier specifications. EFSA guidelines on animal feed safety influence resin formulation choices across supply chains. The northern dairy belt concentrates R&D activity for next-generation biodegradable alternatives.
India
Amul and state-level milk federations present emerging demand for small-diameter formats suited to fragmented landholdings. FSSAI regulations govern feed safety in dairy operations supplying human-consumption markets. Gujarat's Anand district anchors cooperative expansion into improved forage preservation infrastructure.
Silage Bags Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier technology tiers, with coextrusion specialists commanding 40% material cost premiums over standard polyethylene fabricators. The vendor base stratifies between blown film extrusion generalists and 7-layer barrier technology specialists. Three archetypes dominate: diversified packaging conglomerates with agricultural divisions, regional film specialists with tropical climate expertise, and integrated service contractors assuming spoilage risk. Capacity expansion and backward integration into resin formulation represent the dominant competitive vectors.
Within the diversified packaging tier, Berry Global and RKW Group exemplify scale-driven positions across North American and European dairy supply chains respectively. Grupo Armando Alvarez occupies a specialist position anchored in Latin American tropical humidity applications. These three entities represent distinct geographic-technological positioning without overlapping core territories.
| Leading Market Players |
|---|
| RKW Group |
| Berry Global |
| Dow Chemical |
| KSI Supply |
| RPC BPI Agriculture |
| Grupo Armando Alvarez |
| Trioplast |
| Silo Bags International Limited |
| Flex Pack |
| Others |
Value Chain & Pricing Dynamics
EU REACH authorization requirements for persistent organic pollutants gate both qualified supply and premium-tier pricing access, as manufacturers reformulating UV stabilizer packages face 18-to-24-month validation cycles that commodity producers cannot absorb. This regulatory moat concentrates margin capture among 7-layer coextrusion specialists while compressing single-layer polyethylene fabricators into spot-price competition.
Pricing Analysis
Outcome-based dry matter loss guarantees anchor value-based pricing in Brazilian Pantanal contracts where specialty contractors assume full spoilage risk. Three-tier pricing structure across premium barrier films, standard multi-layer constructions, and commodity polyethylene separates dairy operations prioritizing sub-10% dry matter losses from Mato Grosso feedlots optimizing upfront capital. Cost compression in commodity-grade resin runs through ethylene feedstock volatility linked to crude oil fluctuations. Consolidated feedlot operators exhibit lowest price sensitivity; fragmented Indian dairy cooperatives face acute capital constraints.
Supply Chain Analysis
Ethylene vinyl alcohol copolymer supply rests on Japanese and European specialty chemical producers with limited alternative sourcing. Blown film extrusion capacity concentrates in Germany, the United States, and Brazil, with regional compounders formulating UV stabilizer packages to local regulatory specifications. Single-source vulnerability in hindered amine light stabilizer chemistries intensifies under ECHA substance restrictions. Distribution runs through agricultural supply distributors and emerging direct-to-farm digital platforms serving precision livestock farming adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU F-Gas Regulation and REACH mandates erect barrier-to-entry moats favoring manufacturers with validated 7-layer coextrusion capabilities and reformulated additive portfolios.
For Market Incumbents: Hedge resin cost exposure through backward integration into compounder relationships or captive formulation capabilities. Defend margin position by accelerating R&D cycles for biodegradable barrier alternatives ahead of California and Wisconsin extended producer responsibility frameworks. Prioritize certification investment for FDA-EPA dual compliance to compress rival product launch timelines. For New Entrants and Emerging Players: USDA Environmental Quality Incentives Program cost-sharing in the Upper Midwest opens a window for regional film specialists with blown film extrusion capabilities tailored to dairy cooperative specifications. Target small-diameter format gaps in India's fragmented landholding patterns where Amul and state-level milk federations lack established supplier relationships. Pursue direct-to-farm digital channels bypassing traditional agricultural supply distributors. For Investors and Strategic Acquirers: ANVISA feed contact material enforcement in Brazilian beef export supply chains is the leading indicator that barrier specification intensity will intensify across Latin American operations. Long-term viability favors integrated service contractors assuming spoilage risk under outcome-based contracts over commodity film distributors. Watch for consolidation signals among European compounders facing REACH-driven reformulation cost absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of UV stabilizer packages insulates margins from ECHA restriction cycles. |
| Biodegradable Barrier Layer Development | Starch-based alternatives address organic-certified livestock operations facing plastic waste restrictions. |
| Direct-to-Farm Digital Channel Buildout | E-procurement platforms capture margin from precision livestock farming adopters in Wisconsin dairy belts. |
| Vacuum-Sealed System Service Integration | Outcome-based spoilage guarantees concentrate margin pools among Pantanal specialty contractors. |
| Small-Diameter Format Capacity Addition | Fragmented Indian landholdings require tailored solutions beyond standard 3.6-meter diameter specifications. |
Study Parameters
Independent corroboration across dairy cooperative procurement managers, blown film extrusion plant engineers, and agricultural supply distributors underwrites the qualitative findings. Primary interviews with FDA regulatory affairs specialists, ECHA compliance officers, and Brazilian ANVISA feed safety inspectors combined with secondary validation from USDA Environmental Quality Incentives Program documentation, EPA Resource Conservation and Recovery Act filings, and REACH authorization databases. Bottom-up triangulation across resin formulation specifications and top-down validation through end-use demand modeling anchored the segmentation analysis.
Comparable-period anchoring to historical feed storage infrastructure investment cycles established the forecast window baseline. The projection horizon incorporates product type segmentation across multi-layered, plastic, vacuum-sealed, and biodegradable bag architectures; end-use differentiation across dairy farms, cattle ranches, feed lots, and poultry farms; and thickness specifications from 100 to 200 microns. CAGRs derived from installed capacity expansion rates and replacement cycle compression across premium barrier film adopters. Forage dry matter loss economics and regulatory compliance cost absorption served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for biodegradable polymer convergence would alter the outlook. Forecasts reflect assumptions regarding REACH authorization timelines, ethylene feedstock stability, and extended producer responsibility legislative progression. Regulatory enforcement intensity in Brazilian beef export supply chains and Indian dairy cooperative consolidation patterns warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Global Agricultural Films Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Shade Net Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Mulching Materials Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
North America Agricultural Films Market