
 Global Agricultural Films Market | 2026-2036
Global Agricultural Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Films Market Foresight
The capital-intensity divergence between integrated resin producers and specialized converters is bifurcating competitive dynamics across agricultural films. BASF SE leverages its upstream polymer science capabilities to supply high-performance ethylene vinyl acetate grades for greenhouse cladding. Berry Global Group, Inc. anchors its position through blown-film manufacturing scale and direct distribution to North American greenhouse operators. RKW Group differentiates via precision extrusion of silage films with oxygen-barrier coextrusion for European dairy cooperatives.
Agricultural films are multilayer polymeric membranes, typically 15–200 microns thick, manufactured through blown or cast extrusion of polyethylene, polypropylene, or biodegradable aliphatic-aromatic copolyesters, engineered to modify microclimate conditions around crops. Their primary commercial purpose is to extend growing seasons, reduce water consumption, and suppress weed propagation in intensive horticulture. Mulch films command the largest volume share among product types due to universal deployment in row-crop vegetable production, while biodegradable polymers represent the fastest-expanding material category as regulatory restrictions on soil plastic accumulation tighten across the European Union. Greenhouse films concentrate margin pools in anti-drip and IR-blocking formulations where optical additive packages justify premium pricing from Dutch and Israeli greenhouse technology integrators.
The EU REACH regulation and F-Gas framework constrain fluorinated additive use in agricultural film formulations, redirecting R&D toward mineral-based IR modifiers and bio-based plasticizers. The US EPA and state-level California Department of Pesticide Regulation scrutinize microplastic release from conventional mulch degradation, creating compliance thresholds that favor certified soil-biodegradable alternatives. China's MEE and GB standards mandate thickness minimums for agricultural films to reduce tearing and wind dispersal into waterways. Stakeholders must monitor evolving biodegradability certification protocols across jurisdictions to align product portfolios with divergent compliance timelines and subsidy eligibility criteria.
Market Dynamics
Biodegradable polymer formulations are bifurcating competitive positioning between integrated resin producers and specialized converters, as regulatory mandates on soil plastic accumulation tighten procurement specifications across European greenhouse operations.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Sustainability mandates accelerate covered cultivation acreage expansion across Mediterranean horticulture clusters, driving demand for UV-resistant cladding materials.
- Soil solarization protocols:Controlled degradation profiles in mulch applications reduce plastic residue accumulation, aligning with circular agriculture targets in intensive vegetable production systems.
- Almeria greenhouse cluster expansion:Spanish protected horticulture operators scale polyethylene and ethylene vinyl acetate consumption for season-extension infrastructure.
Market Restraints
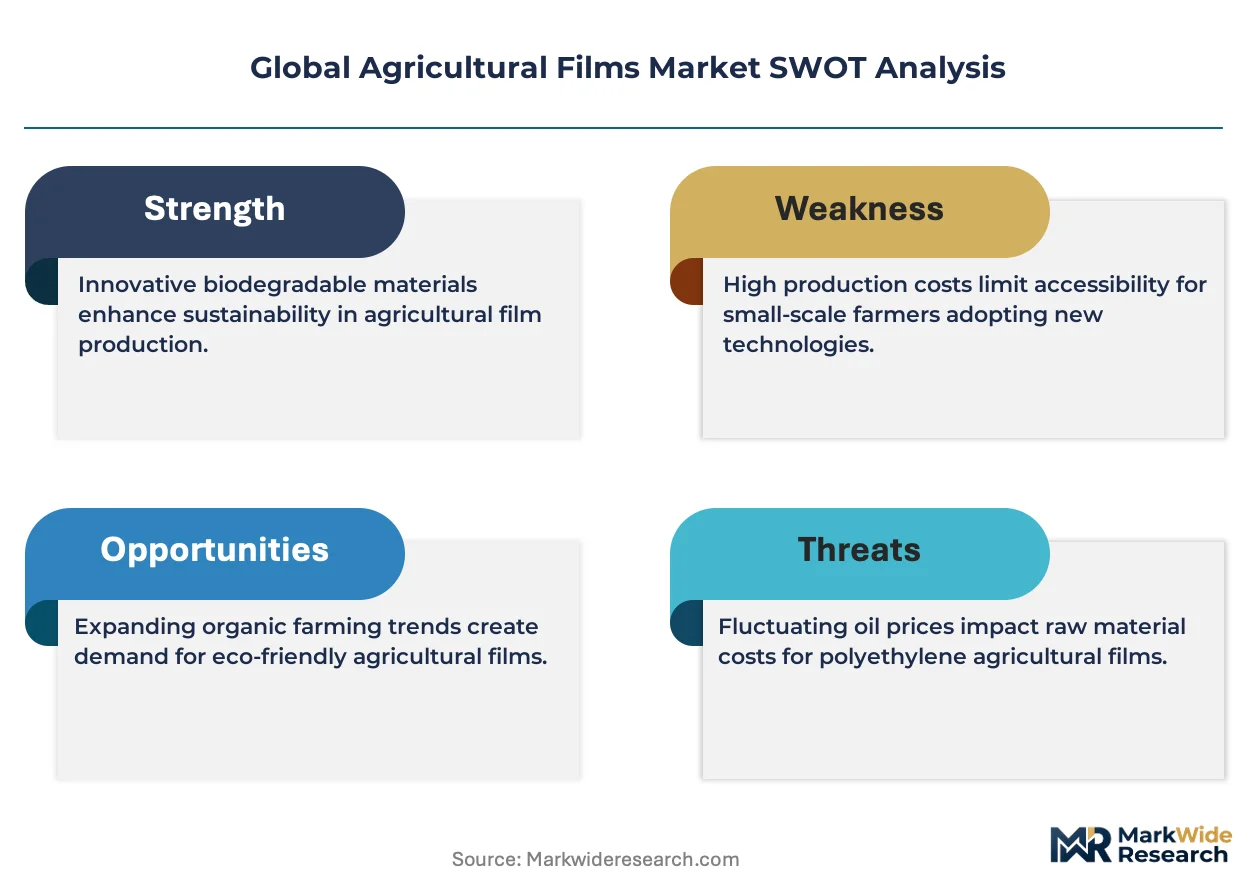
- Ethylene feedstock volatility:Crude oil price swings compress margin pools for polyethylene-based film manufacturers without captive naphtha cracking capacity.
- Fluorinated additive restrictions:EU F-Gas framework and REACH constraints eliminate IR-blocking formulations, forcing mineral-based modifier R&D with inferior optical performance.
- Mechanical recycling contamination:Soil-borne debris and UV stabilizer residues degrade recovered polyethylene quality, limiting circular economy participation.
Strategic Opportunities
- Certified soil-biodegradable alternatives:California Department of Pesticide Regulation microplastic thresholds create first-mover advantage for compliant mulch film suppliers in North American specialty crop sectors.
- Anti-drip optical additive packages:Dutch greenhouse technology integrators command premium pricing for condensation-control formulations in high-value tomato and cucumber production.
- Silage film oxygen-barrier coextrusion:European dairy cooperatives adopt multi-layer structures to reduce aerobic spoilage, opening precision extrusion contracts for specialized converters.
Industry Challenges
- Biodegradability certification fragmentation:Divergent soil-biodegradation testing protocols across EU member states, US ASTM standards, and Chinese GB specifications delay product registration timelines.
- Blown-film equipment retooling costs:Conventional extrusion lines require capital-intensive die and cooling system modifications to process aliphatic-aromatic copolyesters with distinct rheological properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Films Market |
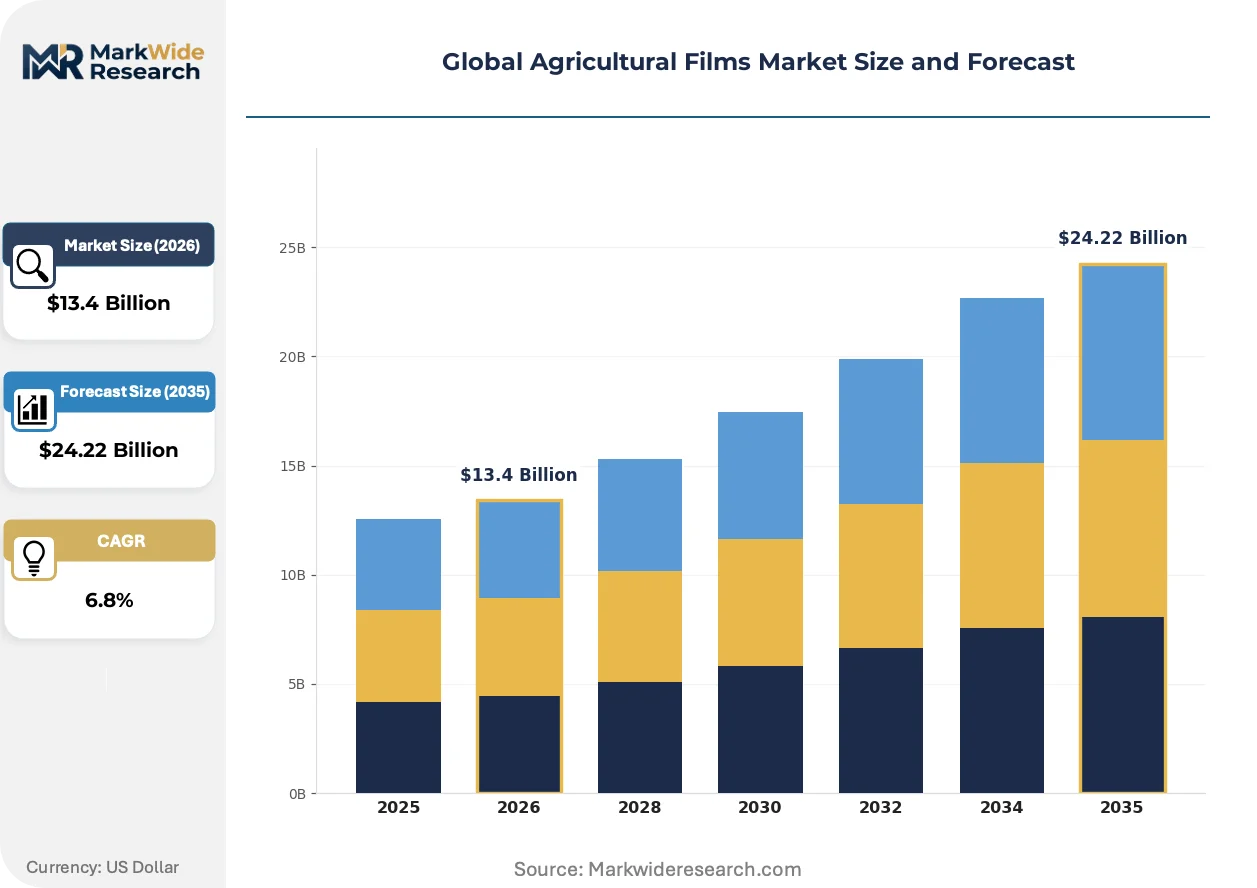
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $24.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulch Films, Greenhouse Films, Silage Films, Tunnels, Anti-Drip Films, Vapor Control Films Material Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Biodegradable Polymers, Ethylene Vinyl Acetate, Polyamide Application: Soil Solarization, Crop Protection, Moisture Conservation, Weed Control, Temperature Regulation, Pest Prevention End User: Farmers, Agricultural Cooperatives, Nurseries, Greenhouse Operators, Landscaping Services, Horticulturists |
| Companies Covered | BASF SE, Berry Global Group, Inc., RKW Group, Armando Alvarez Group, Dow Inc., Coveris, Kuraray Co., Ltd., Rani Group, Plastika Kritis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Films Market Shifts & Advancements
Polymer science advances and regulatory chemistry restrictions are reshaping formulation strategies, while buyer procurement consolidation alters channel economics for specialized agricultural film converters.
Aliphatic-aromatic copolyester biodegradable films are supplanting conventional polyethylene in soil solarization and mulch applications where controlled degradation profiles align with residue accumulation mandates. Greenhouse operators across Italy and Spain accelerate adoption under EU Green Deal procurement guidelines. This substitution is compressing demand for fossil-based mulch grades while expanding margin pools for polymer science specialists with fermentation-derived feedstock capabilities.
REACH and F-Gas framework constraints redirect R&D investment toward mineral-based IR modifiers and bio-based plasticizers, eliminating fluorinated greenhouse gas additives from anti-drip and thermal barrier formulations. Dutch and Israeli greenhouse technology integrators reformulate optical additive packages to maintain condensation control and spectral management performance. European manufacturers face compressed product development cycles to maintain certification eligibility under evolving substance restriction timelines.
Buyer concentration among North American greenhouse operators and European dairy cooperatives consolidates procurement leverage, pressuring distributor margins and accelerating direct manufacturer contracting. Specialized converters bypass traditional agricultural supply channels to capture specification influence in large-scale covered cultivation projects. This channel compression is most visible in California specialty vegetable production and Almeria export-oriented horticulture clusters where volume scale justifies dedicated technical service relationships.
Global Agricultural Films Market Segmentation
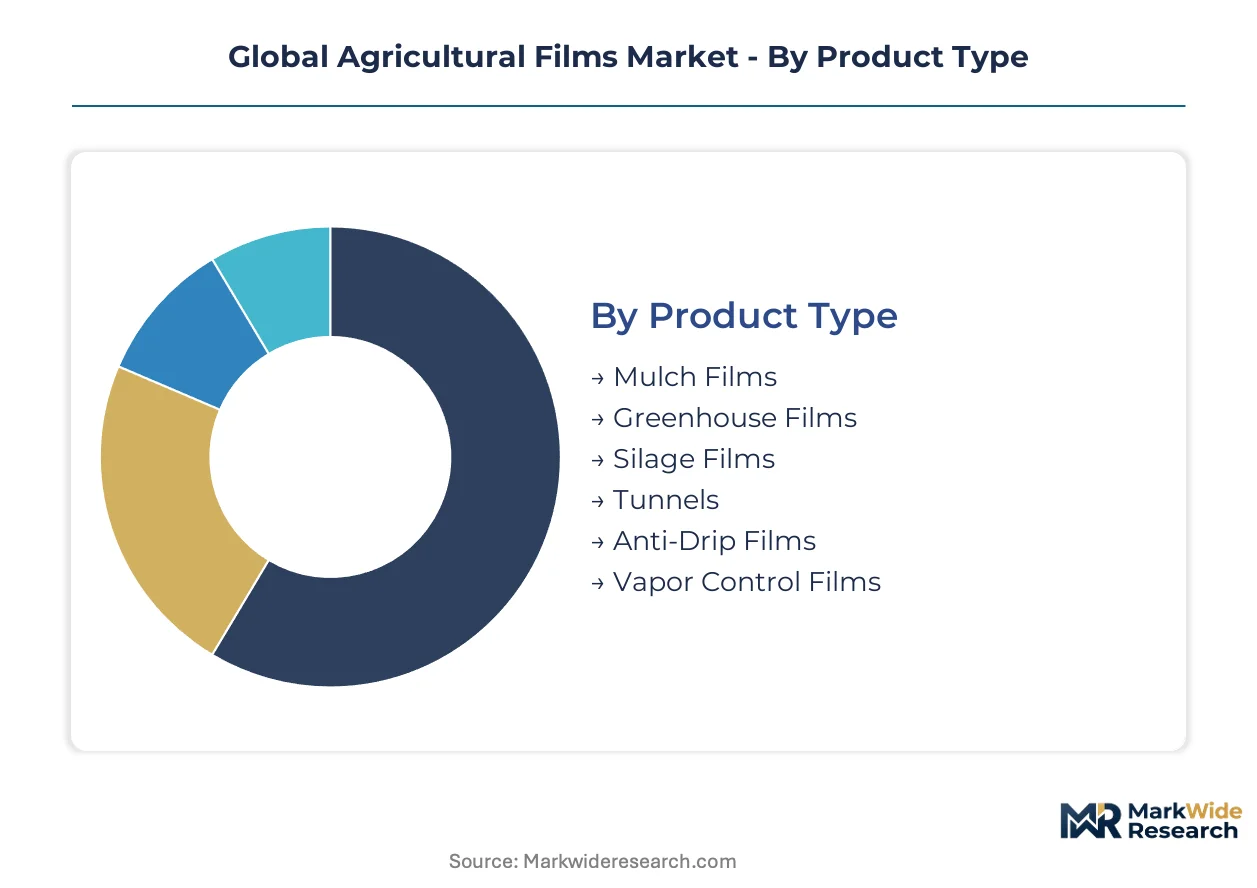
Agricultural films serve heterogeneous cultivation systems from Almeria's export greenhouses to Iowa's corn belt. Segmentation reveals how polymer specifications, application intensity, and buyer procurement scale fragment commercial requirements across distinct value pools.
Product Type:
Domestic consumption dominates mulch and silage categories where regional farming practices dictate specifications, while greenhouse and anti-drip films concentrate in export-oriented horticulture clusters.
- Mulch Films:Polyethylene membranes 15-50 microns thick suppress weed propagation and retain soil moisture in row-crop vegetable production. Demand clusters in California's Central Valley specialty vegetable operations and Spain's Almeria protected cultivation belt, driven by water scarcity mitigation mandates.
- Greenhouse Films:Ethylene vinyl acetate and polyethylene formulations 100-200 microns thick with IR-blocking additives modify microclimate for season extension. Dutch and Israeli technology integrators specify optical packages for high-value tomato and cucumber production, commanding premium pricing against commodity cladding grades.
- Silage Films:Oxygen-barrier coextrusions preserve anaerobic conditions for fermented livestock feed. European dairy cooperatives in Germany and France specify multi-layer precision extrusion to reduce aerobic spoilage losses.
- Tunnels:Semi-permanent hoop structures with ventilated polyethylene cladding extend growing seasons in temperate climates. Italian horticulture clusters deploy these for early strawberry and melon harvests.
- Anti-Drip Films:Surface-modified formulations prevent condensation droplet formation that blocks PAR transmission. Premium greenhouse operators in the Netherlands prioritize these for light-hungry crops.
- Vapor Control Films:High-barrier membranes regulate moisture transmission in controlled-atmosphere storage. Post-harvest applications concentrate in grain handling and seed preservation facilities.
Mulch films hold the largest share; momentum sits with anti-drip formulations where optical performance justifies pricing premiums.
Material Type:
Cost tiers stratify sharply between commodity polyolefins and certified biodegradable alternatives, with fermentation-derived feedstocks commanding 3-5x price multiples over fossil-based grades.
- Polyethylene:Linear low-density and low-density grades dominate volume through blown-film extrusion scalability. Naphtha-derived feedstock volatility compresses margins for converters without captive cracking capacity.
- Biodegradable Polymers:Aliphatic-aromatic copolyesters and polylactic acid formulations degrade under soil burial conditions. EU Green Deal procurement guidelines and California microplastic thresholds accelerate substitution in mulch applications where residue accumulation faces regulatory restriction.
- Polypropylene:Higher melting point and stiffness suit applications requiring dimensional stability under thermal stress. Woven ground covers and reinforced films favor this material.
- Polyvinyl Chloride:Limited deployment in vapor barrier and select greenhouse applications due to plasticizer migration concerns and REACH substance restrictions.
- Ethylene Vinyl Acetate:Copolymer grades with 9-18% vinyl acetate content enhance flexibility and optical clarity for greenhouse cladding. BASF SE supplies high-performance grades to Mediterranean horticulture infrastructure.
- Polyamide:Nylon-based films deliver exceptional oxygen and aroma barrier for specialty silage and modified atmosphere packaging. Premium dairy and meat production systems specify these for high-value feed preservation.
Polyethylene dominates installed volume; biodegradable polymers are climbing the fastest as soil plastic mandates tighten procurement specifications.
Application:
Application intensity correlates with water stress geography and labor cost structures, driving divergent specification requirements between mechanized broadacre and intensive hand-harvested systems.
- Soil Solarization:Transparent or black polyethylene sheets trap solar radiation to sterilize soil prior to planting. Israeli and Spanish vegetable producers deploy this for nematode and pathogen suppression in replant-sensitive crops.
- Crop Protection:Physical barriers exclude insect vectors and reduce pesticide application frequency. Southeast Asian fruit orchards and Italian vineyard operations specify mesh-embedded films for spotted wing drosophila exclusion.
- Moisture Conservation:Mulch films reduce evaporative water loss in arid and semi-arid cultivation. California's drought-driven agricultural water regulations intensify deployment in almond and tomato production.
- Weed Control:Opaque films block photosynthetically active radiation to suppress competing vegetation. Labor-scarce Japanese horticulture operations rely on these for reduced manual cultivation.
- Temperature Regulation:IR-absorbing and -reflective formulations modify soil and air thermal regimes. Northern European greenhouse operators specify these for energy cost reduction in winter production.
- Pest Prevention:UV-blocking and reflective films disorient insect pests and reduce virus transmission. Florida and Mediterranean vegetable producers deploy silver-reflective mulches for whitefly management.
Moisture conservation commands the greatest polymer volume; soil solarization exhibits the steepest expansion trajectory as chemical fumigants face phase-out.
End User:
Customer scale fragments procurement patterns from individual farmer retail purchases to cooperative tender processes and integrated greenhouse operator direct contracting.
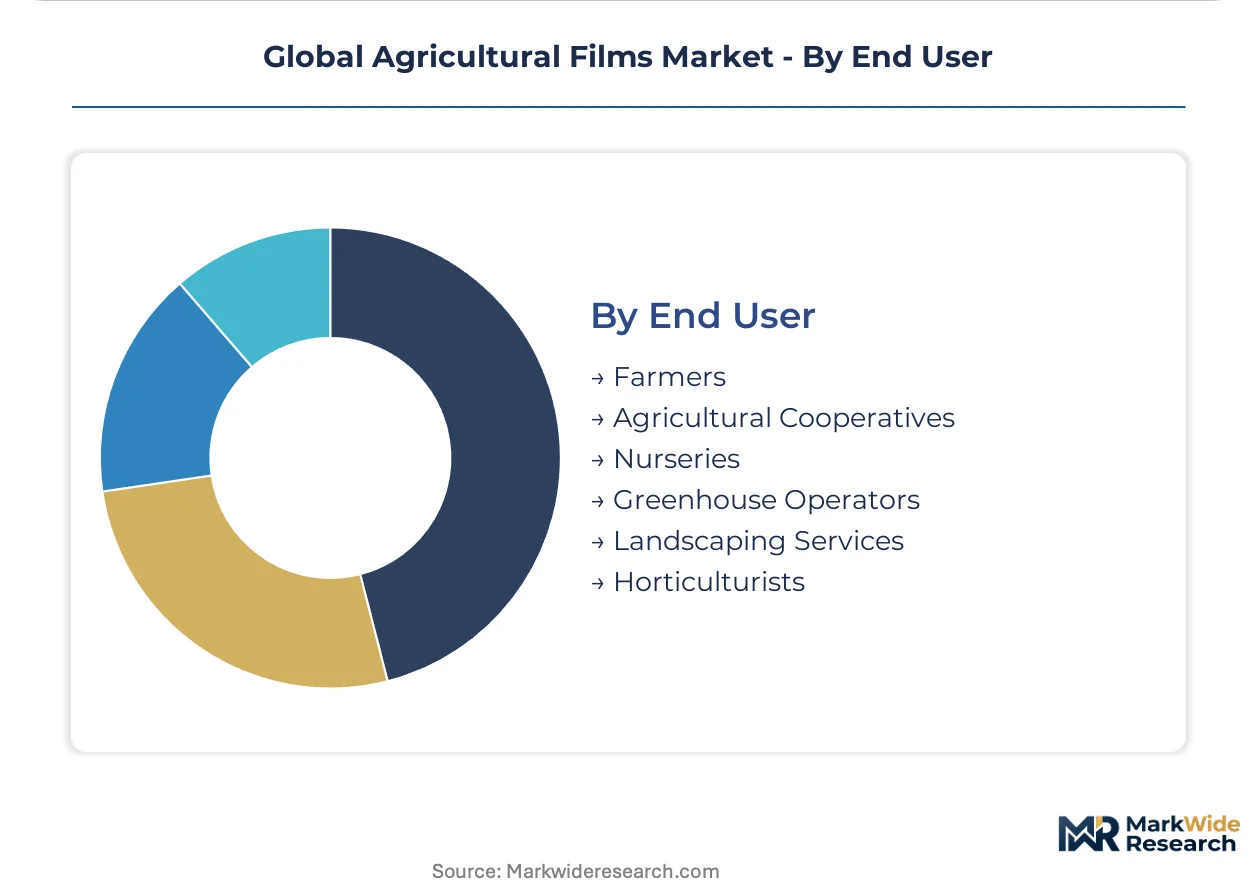
- Farmers:Individual operators purchase standard mulch and silage films through agricultural supply distributors. Price sensitivity dominates specification decisions in commodity grain and livestock systems.
- Agricultural Cooperatives:Consolidated procurement entities negotiate volume contracts for member farms. European dairy cooperatives in Denmark and the Netherlands specify oxygen-barrier silage films through centralized technical purchasing.
- Nurseries:Propagation specialists require UV-stabilized films for seedling hardening structures. Container nursery operations in Oregon and British Columbia prioritize durability for multi-season reuse.
- Greenhouse Operators:Large-scale protected cultivation enterprises source direct from manufacturers with embedded technical service. Almeria's export-oriented tomato and pepper producers specify anti-drip and IR-blocking formulations through dedicated supply agreements.
- Landscaping Services:Commercial turf and ornamental installers utilize erosion control and weed suppression films. Municipal and golf course contracts drive seasonal demand patterns.
- Horticulturists:Research institutions and high-value crop specialists demand performance-optimized formulations. Israeli agricultural research stations trial spectral modification films for photomorphogenic studies.
Greenhouse operators concentrate margin capture; agricultural cooperatives are gaining procurement leverage fastest through volume consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across cultivation geographies. Mediterranean greenhouse operators prioritize optical-grade cladding with anti-drip properties, while North American broadacre farmers emphasize mulch durability for mechanized row-crop systems.
Spain
Almeria's protected horticulture belt drives concentrated demand for ethylene vinyl acetate greenhouse films with IR-blocking formulations. EU Green Deal Farm to Fork procurement guidelines mandate UV-resistant materials for season-extension infrastructure. The Andalusian export cluster scales polyethylene consumption for tomato and pepper cultivation under technology integrator specifications.
United States
California's Central Valley specialty vegetable operations deploy mulch films for water conservation under drought-driven agricultural regulations. The EPA and California Department of Pesticide Regulation scrutinize microplastic release thresholds, redirecting procurement toward certified soil-biodegradable alternatives. Central Coast strawberry producers pilot controlled-degradation formulations to align with residue accumulation mandates.
China
Shandong Peninsula greenhouse clusters consume multi-layer polyethylene for protected vegetable cultivation under MEE thickness minimums designed to reduce wind dispersal. GB standards mandate tear-resistant specifications to limit waterway contamination. The Yangtze River Delta horticulture belt expands covered acreage for high-value leafy green production.
Netherlands
High-technology greenhouse operators specify premium anti-drip and spectral modification films for tomato and cucumber production. REACH and F-Gas framework constraints eliminate fluorinated additives, forcing mineral-based IR modifier adoption. Westland municipality clusters concentrate precision horticulture infrastructure with embedded technical service relationships.
Italy
Po Valley and Sicily horticulture operations expand soil solarization film deployment for nematode suppression as chemical fumigants face phase-out. EU biodegradability certification protocols accelerate substitution of conventional polyethylene in mulch applications. Pachino and Ragusa protected cultivation zones drive consumption of controlled-degradation formulations under circular agriculture procurement guidelines.
Global Agricultural Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in agricultural films. Resin producers with captive polymer science capabilities supply high-performance ethylene vinyl acetate and biodegradable formulations, while blown-film converters compete on manufacturing scale and distribution proximity to greenhouse clusters. Three archetypes dominate: upstream-integrated chemical conglomerates, precision extrusion specialists, and regional blown-film fabricators. Competitive moves center on fermentation-derived feedstock partnerships and direct contracting with large-scale protected cultivation operators.
Among integrated chemical producers, BASF SE and Dow Inc. anchor the premium materials tier with upstream control over polymer science and additive packages. Berry Global Group, Inc. exemplifies the scale-driven converter archetype, occupying a position in North American blown-film manufacturing and distribution. RKW Group represents precision extrusion specialists serving European dairy cooperatives and greenhouse operators with multi-layer silage and cladding formulations.
| Leading Market Players |
|---|
| BASF SE |
| Berry Global Group, Inc. |
| RKW Group |
| Armando Alvarez Group |
| Dow Inc. |
| Coveris |
| Kuraray Co., Ltd. |
| Rani Group |
| Plastika Kritis SA |
| Others |
Supply & Pricing Matrix
EU biodegradability certification protocols gate both supplier qualification and price differentiation simultaneously, compressing procurement options for greenhouse operators while expanding margin pools for compliant resin producers. Buyers face tiered cost structures where certified soil-biodegradable films command substantial premiums over conventional polyethylene grades.
Pricing Analysis
Long-term offtake contracts dominate procurement between large-scale greenhouse operators and integrated resin producers, insulating volume buyers from ethylene feedstock volatility while spot markets serve fragmented farmer segments. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade anti-drip formulations from commodity mulch grades and unadditived base films. Cost compression in standard polyethylene tiers is intensifying because naphtha-derived feedstock volatility squeezes converters lacking captive cracking capacity. Individual farmers exhibit the highest price sensitivity, while Dutch and Israeli greenhouse technology integrators prioritize performance specifications over unit economics.
Supply Chain Analysis
Saudi Arabia and South Korea anchor naphtha cracking and ethylene production for polyethylene feedstock, while Germany and the Netherlands concentrate specialty additive compounding and precision extrusion capabilities. Agricultural film manufacturing draws from ethylene, vinyl acetate monomer, and mineral-based IR modifiers as primary inputs. Single-source vulnerability sits with fermentation-derived biodegradable polymer feedstocks, where limited suppliers of aliphatic-aromatic copolyesters create qualification bottlenecks. Distribution runs through agricultural supply distributors for fragmented farmer segments, while direct manufacturer contracting serves consolidated greenhouse operators and dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where biodegradability certification timelines and substance restriction compliance create sticky supplier relationships that resist displacement.
For Market Incumbents: Fortify positions by deepening captive supply of fermentation-derived biodegradable feedstocks and accelerating mineral-based IR modifier R&D to offset F-Gas framework constraints. Threats from specialized converters with direct greenhouse operator relationships demand channel control investments in embedded technical service capabilities across Almeria and Westland clusters. For New Entrants and Emerging Players: Anchor in California specialty vegetable production, where the Department of Pesticide Regulation microplastic thresholds create first-mover openings for certified soil-biodegradable mulch suppliers. The least penetrated segment sits in oxygen-barrier silage films for North American dairy cooperatives, where precision extrusion capabilities remain scarce and technical purchasing specifications favor specification influence over price competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable polymer fermentation capacity, favoring integrated resin producers with backward feedstock control over pure-play converters. Long-term viability centers on acquisition targets with established EU certification protocols and direct contracting relationships with Mediterranean greenhouse clusters. The signal to watch is California regulatory enforcement intensity, where compliance threshold acceleration would revalue certified alternative suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | BASF SE and Dow Inc. secure captive supply of biodegradable polymer precursors against qualification bottlenecks. |
| Mineral-Based IR Modifier R&D Program | European manufacturers reformulate optical packages to maintain REACH and F-Gas framework compliance eligibility. |
| Direct Technical Service Expansion | Specialized converters bypass distributors to capture specification influence in Almeria and California greenhouse clusters. |
| California Regulatory Compliance Certification | First-mover suppliers align mulch film portfolios with Department of Pesticide Regulation microplastic thresholds. |
| Oxygen-Barrier Silage Film Capacity Addition | Precision extrusion specialists target European dairy cooperative procurement consolidation with multi-layer formulations. |
Research Methodology
The analysis maps mulch, greenhouse, silage, and biodegradable film sub-sectors, each validated through greenhouse operators, resin procurement directors, blown-film plant managers, and agricultural supply distributors. Primary interviews with these stakeholders combined with secondary validation from EU REACH substance restriction databases, ECHA additive authorization filings, US EPA microplastic research publications, and Chinese GB standards documentation. Bottom-up polymer consumption modeling and top-down macroeconomic triangulation anchored volume estimates.
Consistency checks against customs trade data and industry association capacity disclosures validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, material formulation, application intensity, end-user procurement scale, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating cultivation acreage expansion rates, substitution dynamics between conventional and biodegradable polymers, and compliance-driven procurement specification shifts.
Material uncertainties — feedstock price volatility, biodegradability certification protocol divergence, and enforcement intensity variation across EU member states and US state regulators — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and substitution elasticity that material shifts in EU Green Deal implementation or California pesticide regulation enforcement could revise. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
South America Agricultural Films Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Pond Liners Market
Agricultural Fabrics
Europe Agricultural Films Market
Agricultural Fabrics
Farming Sacks and Totes Market
Agricultural Fabrics
Anti Wind Net Market
Agricultural Fabrics
North America Agricultural Films Market
Agricultural Fabrics
Agricultural Gloves Market
Agricultural Fabrics
Agriculture Bags Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Nonwoven Crop Cover Market