
 Garden Cress Market | 2026-2036
Garden Cress Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Cress Market Foresight
The capital-intensity divergence between integrated seed producers and commodity resellers is rotating competitive advantage toward firms with captive germination infrastructure. Pristine Organics leverages proprietary organic seed lines across South Asian export corridors. Kitazawa Seed Company anchors its position through century-old heirloom cultivars and direct-to-chef distribution in North America. West Coast Seeds differentiates via region-adapted varietals and climate-specific growing guides.
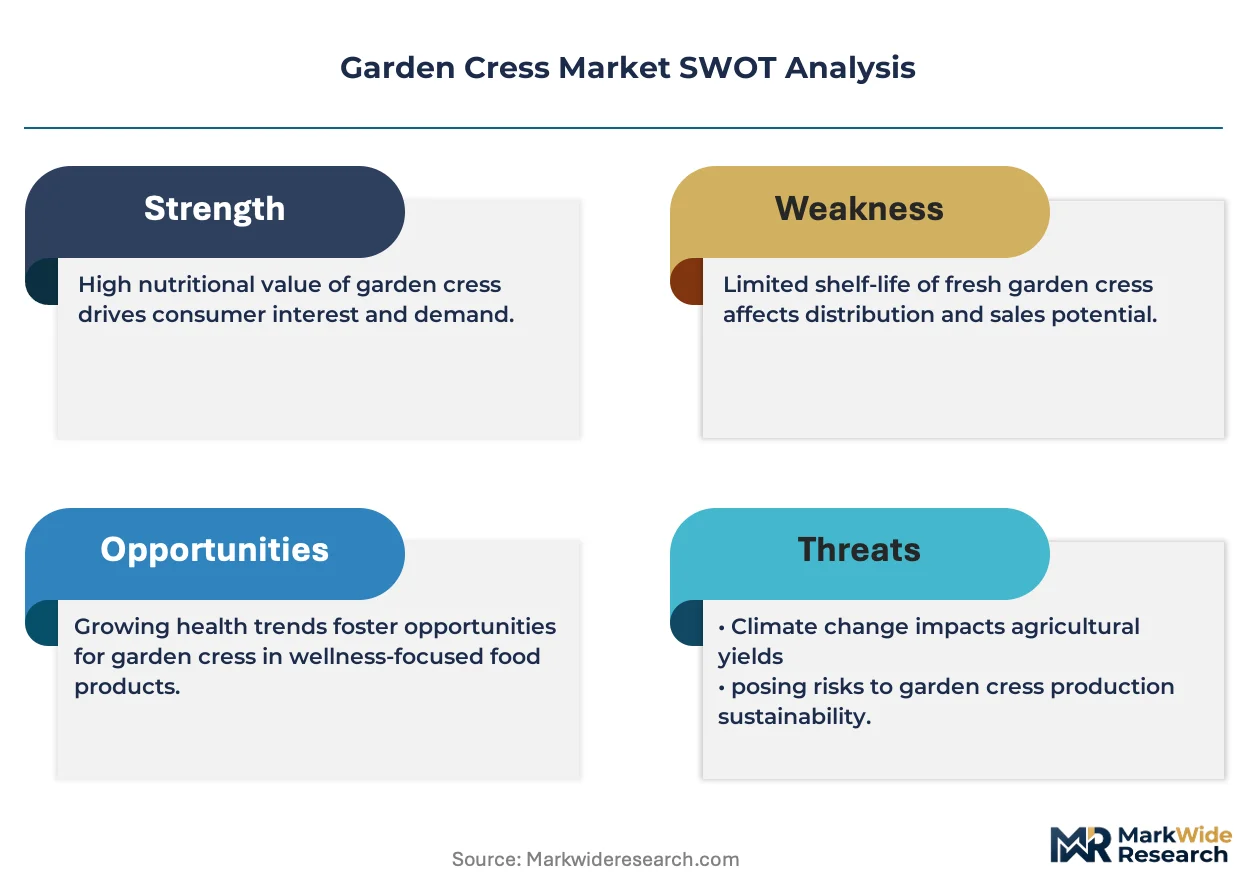
Garden cress (Lepidium sativum) is an annual brassica cultivated for its pungent, nutrient-dense foliage and mucilaginous seed coat, germinating within 48–72 hours under controlled humidity and delivering glucosinolate concentrations valued in functional food formulations. Seeds command premium positioning among commercial microgreen operations due to standardized germination rates and year-round cultivation viability, while fresh leaves retain dominant volume through supermarket produce aisles and restaurant supply chains. Herbal remedies applications attract margin concentration from specialized extractors serving European botanical pharmaceutical channels.
EU organic certification under EFSA and USDA National Organic Program standards shape cross-border seed commerce and phytosanitary documentation burdens for exporters. India's FSSAI and APEDA frameworks govern processed cress product eligibility for overseas shipment, creating compliance layering for integrated processors. Stakeholders must monitor evolving maximum residue limits for brassica-specific chemistries as import jurisdictions tighten contaminant thresholds.
Market Dynamics
EU organic certification frameworks are compressing seed commerce timelines while concentrating procurement authority among integrated germination operators with captive supply chains.
Growth Catalysts
- EFSA maximum residue limit tightening:Brassica-specific contaminant thresholds are filtering out commodity resellers and rewarding seed processors with in-house phytosanitary documentation capabilities.
- Functional food formulation demand:Glucosinolate extraction from garden cress mucilage is penetrating European botanical pharmaceutical channels at accelerating velocity.
- Urban farm-to-table sourcing protocols:Western European metropolitan restaurant supply chains are mandating 48-hour harvest-to-delivery windows that favor localized microgreen operations.
Market Restraints
- Input cost volatility:Humidity-controlled germination infrastructure requires precision HVAC and LED arrays vulnerable to energy price spikes in Germany and the Netherlands.
- Supply concentration risk:Certified organic seed stock concentrates among South Asian exporters subject to India's APEDA documentation delays and monsoon logistics disruption.
- Substitution threat:Broccoli microgreens and radish shoots deliver comparable glucosinolate profiles at lower cultivation complexity, pressuring cress premium positioning.
Strategic Opportunities
- Underpenetrated North American direct-to-chef distribution:Century-old heirloom cultivar networks in California and Oregon remain fragmented versus European procurement consolidation.
- Climate-adapted varietal development:Region-specific growing guides paired with drought-tolerant seed lines are opening arid-zone cultivation in Spain and Portugal.
- EU Green Deal agricultural incentives:Carbon-sequestering indoor farming subsidies are offsetting capex burdens for certified organic germination facilities.
Industry Challenges
- Phytosanitary compliance timeline compression:Cross-border seed shipments now require dual USDA National Organic Program and EFSA documentation with non-aligned inspection cycles.
- Skill scarcity in controlled-environment agriculture:Germination rate optimization and glucosinolate preservation protocols demand technicians trained in brassica-specific physiology.
- Integration friction with legacy foodservice procurement:Supermarket produce buyers resist shifting from volume-based contracts to harvest-window-guaranteed microgreen sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Cress Market |
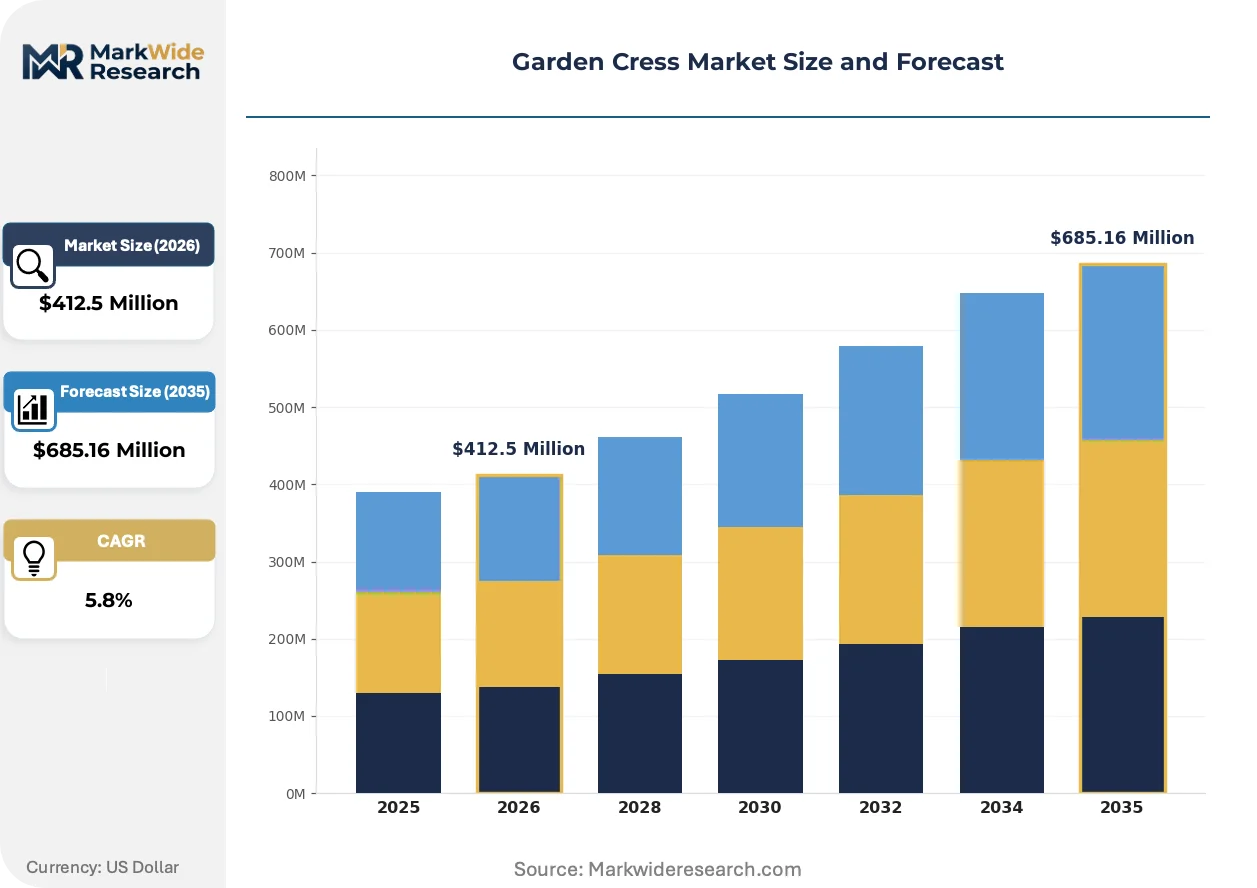
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Microgreens, Fresh Leaves, Sprouts Application: Salads, Sandwiches, Garnishes, Herbal Remedies, Culinary Herbs End User: Food Processors, Restaurants, Herbalists, Home Gardeners Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Farmers Markets |
| Companies Covered | Pristine Organics, Rr Agro Foods, Udeep Organic, Kitazawa Seed Company, West Coast Seeds, Himalayan Natives, Sorichorganics, Cress Company Inc., Moksha Lifestyle Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Cress Market Shifts & Advancements
Controlled-environment agriculture is fragmenting competitive advantage between capital-intensive vertical farms and distributed greenhouse networks, each pursuing divergent certification and channel strategies.
Automated seed coating technology is bifurcating the market between precision-applied mucilage preservation for extractors and bare-seed bulk supply for commodity microgreen operators. European botanical pharmaceutical channels are adopting coated seed lines at three times the rate of North American restaurant suppliers. This technology is compressing germination rate variance from 15% to under 3%, enabling outcome-based pricing contracts that displace traditional tonnage-based procurement.
REACH substance restriction updates are reclassifying brassica-specific chemistries used in conventional seed treatment, forcing processors to eliminate neonicotinoid-based coatings from EU-bound shipments. German functional food manufacturers are now requiring third-party residue testing beyond baseline EFSA certification. This regulatory pressure is accelerating migration toward biological seed treatment alternatives among exporters serving Rotterdam and Hamburg distribution hubs.
Chef-driven varietal selection is displacing standardized supermarket produce specifications as the dominant demand signal. Farm-to-table restaurants in Copenhagen and Amsterdam are contracting directly with germination facilities for specific harvest-window cress morphology. This channel disintermediation is most visible in Netherlands urban clusters where procurement managers bypass traditional wholesale produce distributors entirely.
Garden Cress Market Segmentation
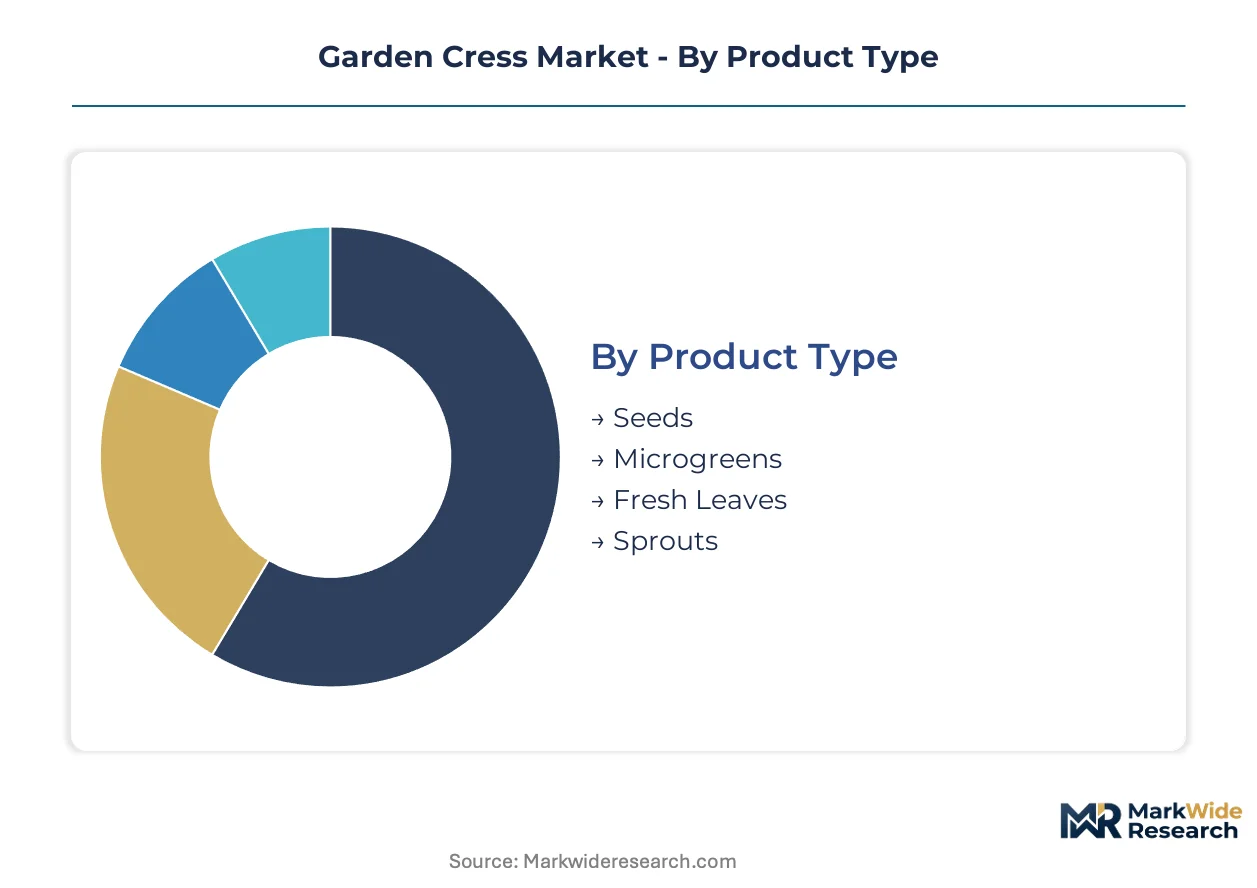
Garden cress segmentation reveals divergent margin profiles across cultivation formats and procurement channels. Substitution pressure from broccoli microgreens and radish shoots varies sharply by product form and end-use application.
Product Type:
Microgreens and sprouts face the most acute substitution threat from radish shoots delivering comparable glucosinolate density at lower operational complexity.
- Seeds:Certified organic seed stock commands premium positioning through standardized germination rates and year-round cultivation viability. Demand concentrates among commercial microgreen operations in Germany and the Netherlands under EU organic certification frameworks, though APEDA documentation delays from Indian exporters create supply friction.
- Microgreens:Controlled-environment cultivation delivers 48–72 hour harvest cycles with precise glucosinolate preservation. Copenhagen and Amsterdam restaurants contract directly for specific harvest-window morphology, bypassing traditional wholesale distributors entirely.
- Fresh Leaves:Supermarket produce aisles retain dominant volume through conventional supply chains.
- Sprouts:Commodity positioning limits margin expansion despite high turnover velocity.
Fresh leaves anchors the volume base while microgreens gains share at the steepest rate.
Application:
Cost tier stratification separates premium botanical pharmaceutical extraction from mass-market culinary deployment.
- Salads:Farm-to-table restaurant sourcing in Western European urban centers mandates compressed harvest-to-delivery windows. German and Dutch procurement managers favor localized germination facilities over import-dependent supply.
- Herbal Remedies:Glucosinolate extraction from mucilaginous seed coat penetrates European botanical pharmaceutical channels at accelerating velocity. EFSA maximum residue limit tightening filters out processors lacking in-house phytosanitary documentation.
- Sandwiches:Volume-driven foodservice contracts prioritize consistency over premium positioning.
- Garnishes:Chef-driven varietal selection displaces standardized specifications.
- Culinary Herbs:Home cooking applications show stable but undifferentiated demand patterns.
Salads captures the broadest customer base while herbal remedies delivers the highest margin concentration.
End User:
Customer type determines certification burden intensity and contract structure flexibility.
- Restaurants:Direct-to-chef distribution networks in North America remain fragmented versus European consolidation. California and Oregon heirloom cultivar suppliers compete on climate-adapted varietals and growing guide specificity.
- Food Processors:Functional food manufacturers require third-party residue testing beyond baseline EFSA certification. German processors now mandate biological seed treatment alternatives eliminating neonicotinoid-based coatings.
- Herbalists:Small-batch extraction demands create niche procurement relationships.
- Home Gardeners:Price-sensitive segment with minimal certification requirements.
Food processors anchor procurement volume while restaurants drive premium pricing expansion.
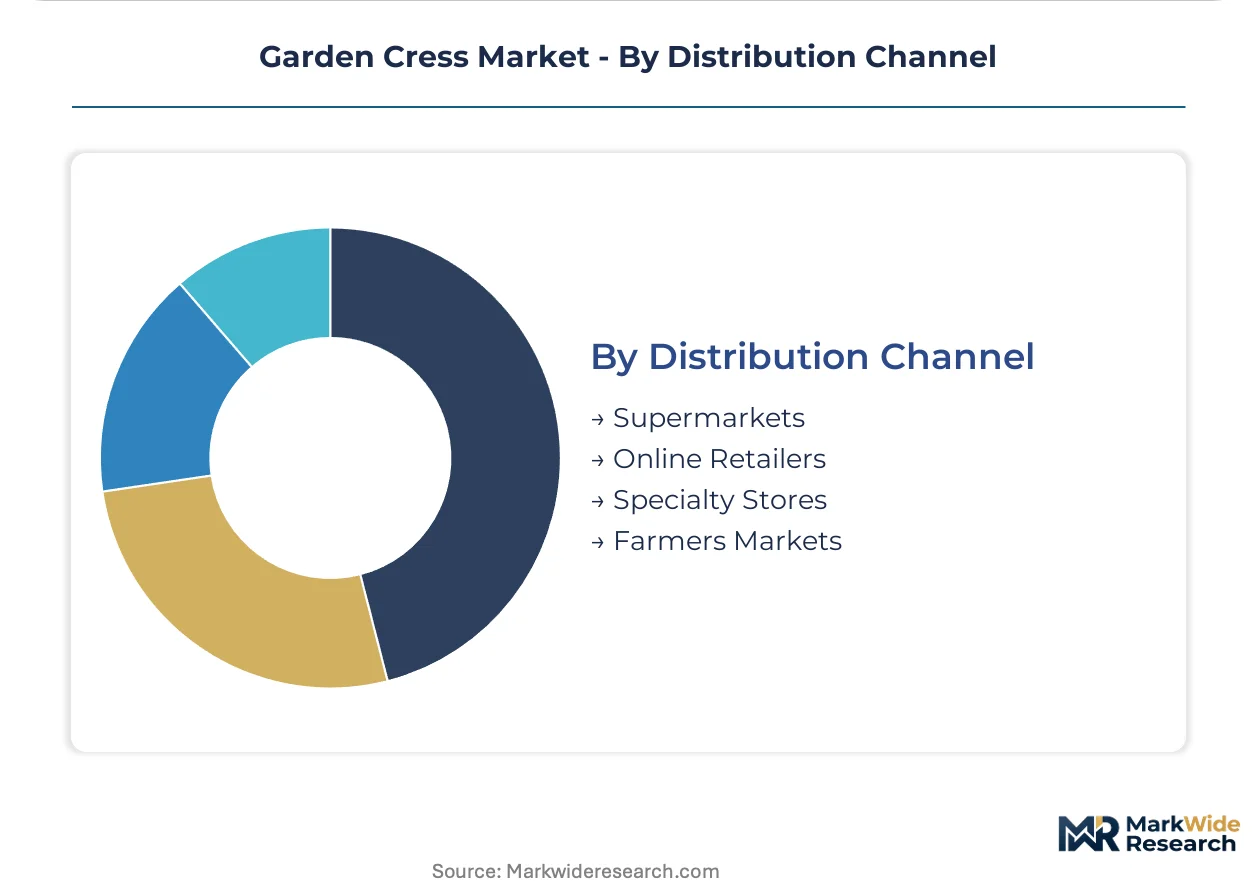
Distribution Channel:
Supply concentration risk shifts across channel types based on documentation and perishability requirements.
- Specialty Stores:Curated organic seed lines and region-adapted varietals attract discerning home gardeners and small-scale chefs. Climate-specific growing guides differentiate offerings in Spain and Portugal arid-zone markets.
- Online Retailers:Bare-seed bulk supply competes with precision-applied mucilage preservation for extractors. Automated seed coating technology adoption runs three times higher in European botanical channels than North American restaurant supply.
- Supermarkets:Volume-based contracts resist shift to harvest-window-guaranteed sourcing.
- Farmers Markets:Localized cultivation bypasses cross-border phytosanitary complexity.
Supermarkets maintains volume dominance while specialty stores expands most quickly in premium tier capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home gardeners in India exhibit the sharpest price sensitivity, while German functional food manufacturers absorb substantial premiums for certified organic seed stock with documented phytosanitary compliance.
Germany
Functional food processors in Hamburg and Berlin drive procurement consolidation under EFSA maximum residue limit tightening. The EU Green Deal agricultural incentives offset capex burdens for certified organic germination facilities. The Ruhr Valley urban corridor anchors demand for 48-hour harvest-to-delivery microgreen contracts.
Netherlands
Amsterdam and Copenhagen restaurants mandate specific harvest-window cress morphology, bypassing traditional wholesale distributors entirely. REACH substance restriction updates reclassify brassica-specific chemistries, forcing elimination of neonicotinoid-based coatings from Rotterdam-bound shipments. The Randstad cluster concentrates controlled-environment agriculture expertise.
India
APEDA documentation delays and monsoon logistics disruption create supply friction for South Asian organic seed exporters. FSSAI frameworks govern processed cress product eligibility for overseas shipment, layering compliance complexity. Maharashtra and Gujarat host integrated processors serving European botanical pharmaceutical channels.
United States
California and Oregon heirloom cultivar suppliers compete on climate-adapted varietals and growing guide specificity. USDA National Organic Program standards shape cross-border seed commerce with non-aligned inspection cycles versus EFSA protocols. The Pacific Northwest anchors fragmented direct-to-chef distribution networks.
Spain
Region-specific growing guides paired with drought-tolerant seed lines open arid-zone cultivation in Andalusia and Valencia. Climate-adapted varietal development attracts EU Green Deal carbon-sequestering indoor farming subsidies. Madrid metropolitan restaurants tighten farm-to-table sourcing protocols.
Garden Cress Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated germination operators commanding premium positioning while commodity resellers compete on bare-seed bulk supply. The vendor base fragments across century-old heirloom cultivar networks, proprietary organic seed lines, and region-adapted varietal specialists. Three archetypes dominate: captive germination infrastructure owners, biological seed treatment innovators, and climate-specific growing guide providers. Competitive moves concentrate on backward integration into certified organic seed stock and geographic expansion through direct-to-chef distribution channels.
Within the integrated germination tier, Pristine Organics and Kitazawa Seed Company exemplify divergent geographic anchoring strategies. West Coast Seeds occupies a position among region-adapted varietal specialists. These three entities represent the competitive spectrum from South Asian export corridor dominance to North American direct-to-chef fragmentation.
| Leading Market Players |
|---|
| Pristine Organics |
| Rr Agro Foods |
| Udeep Organic |
| Kitazawa Seed Company |
| West Coast Seeds |
| Himalayan Natives |
| Sorichorganics |
| Cress Company Inc. |
| Moksha Lifestyle Products |
| Others |
Supply & Pricing Matrix
Capacity utilization rates at certified organic germination facilities in Germany and the Netherlands compress price floors for microgreen-grade seed stock while elevating premiums for phytosanitary-compliant export inventory. Scale economies in controlled-environment agriculture tether pricing power to captive infrastructure ownership, fragmenting margin capture between integrated operators and commodity resellers.
Pricing Analysis
After-sales service contracts for climate-specific growing guides and harvest-window guarantees drive lifetime value for region-adapted varietal specialists. Three-tier pricing structure across premium certified organic, standard conventional, and economy bare-seed bulk levels segments buyer archetypes. Cost compression in the economy tier intensifies because Indian APEDA documentation delays extend working capital cycles for South Asian exporters. Home gardeners in domestic Indian markets exhibit the sharpest price sensitivity, while German functional food manufacturers absorb substantial premiums for EFSA-compliant seed stock with third-party residue testing.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg distribution hubs elevates inbound logistics costs for Indian exporters serving European botanical pharmaceutical channels. Certified organic seed stock concentrates in India, the Netherlands, and the United States, drawing from brassica-specific germplasm banks and heirloom cultivar networks. Supply chain risk hinges on single-source vulnerability for mucilage-preservation coating technology. Distribution runs through direct-to-chef networks in Amsterdam and Copenhagen, bypassing traditional wholesale produce distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as chef-driven varietal selection displaces standardized supermarket specifications, creating niche procurement relationships for morphology-specific harvest contracts.
For Market Incumbents: Shield germination rate optimization capabilities through backward integration into certified organic seed stock in South Asian export corridors. Defend margin position by investing in biological seed treatment alternatives ahead of REACH substance restriction enforcement. Capacity addition in Portugal and Spain captures EU Green Deal subsidies for arid-zone cultivation expansion.
For New Entrants and Emerging Players: Lead with climate-adapted varietal development targeting drought-tolerant seed lines for Mediterranean markets. Underpenetrated North American direct-to-chef distribution remains the most accessible white space, fragmented versus European consolidation. Go-to-market execution should anchor on growing guide specificity paired with region-specific cultivation protocols.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated germination operators with captive supply chains and multi-year restaurant contracts. Long-term viability over the next decade favors biological seed treatment innovators and phytosanitary documentation specialists. Acquisition targets should demonstrate in-house glucosinolate preservation protocols. The signal to monitor is EFSA maximum residue limit tightening velocity, which filters out commodity resellers and concentrates procurement authority.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Seed Stock | Captive germination infrastructure in India and the Netherlands secures supply chain control against APEDA documentation delays. |
| Biological Seed Treatment Transition | Elimination of neonicotinoid-based coatings ensures REACH compliance for Rotterdam and Hamburg distribution hubs. |
| Climate-Adapted Varietal Development | Drought-tolerant seed lines open arid-zone cultivation in Spain and Portugal under EU Green Deal incentives. |
| Direct-to-Chef Distribution Expansion | Bypassing wholesale distributors captures premium positioning in Amsterdam and Copenhagen restaurant supply chains. |
| Automated Seed Coating Technology Deployment | Precision-applied mucilage preservation compresses germination rate variance for European botanical pharmaceutical channels. |
Research Methodology
Initial hypotheses were tested against primary input from germination facility operators, restaurant procurement managers, functional food R&D directors, and organic certification auditors and refined through secondary validation. Sources included EFSA regulatory filings, APEDA export documentation databases, EU Green Deal agricultural incentive records, and controlled-environment agriculture trade publications. Bottom-up seed stock volume estimates and top-down functional food formulation demand projections were triangulated for convergence.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs incorporated brassica-specific glucosinolate extraction demand curves and urban farm-to-table sourcing protocol adoption rates.
Forecasts assume regulatory continuity in EFSA maximum residue limit enforcement and USDA National Organic Program standards; material policy shifts would require re-modeling. Substitution velocity from broccoli microgreens and radish shoots, energy price spikes affecting humidity-controlled infrastructure, and monsoon logistics disruption in South Asian export corridors constitute primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Air Dried Vegetables Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Asparagus Market
Vegetables
Fresh Vegetables Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Tomato Market
Vegetables
Sprouts Market
Vegetables
Roselle Market
Vegetables
Vegetable Grader Market
Vegetables
Potato Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Yams Market
Vegetables
Dried Vegetable Market