
 Africa Packaging Market | 2026-2036
Africa Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Packaging Market Analysis
Direct-to-retail distribution across Africa is narrowing as modern trade formats expand and informal wholesale layers consolidate. Nampak Limited leverages its integrated beverage can and glass operations to sustain supply advantages in Southern African markets. Constantia Flexibles Group anchors its position through specialized pharmaceutical blister and sachet capabilities that meet stringent export standards. Mondi Group competes via kraft paper and corrugated solutions tailored to fresh-produce export logistics from Kenya and South Africa.
Africa packaging encompasses material enclosures, protective structures, and information-bearing surfaces engineered from polymers, cellulose fibers, glass, or metal alloys to preserve, contain, transport, and merchandise goods through supply chains. Flexible packaging dominates volume in snack foods and powdered beverages due to lightweight films that reduce freight cost per unit, while rigid plastic containers lead in edible oils and household chemicals where dimensional stability prevents leakage. Paperboard packaging captures premium positioning in personal care and pharmaceutical outer cartons where print fidelity supports brand differentiation, though glass packaging retains structural share in spirits and pharmaceutical ampoules demanding inert barrier properties.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that shift recycling accountability to brand owners and converters. The African Organisation for Standardisation coordinates harmonized packaging specifications for cross-border trade, while national food safety agencies in Nigeria and Kenya mandate migration-tested materials for edible product contact. Stakeholders must track how diverging national implementation timelines for plastic waste regulations will reshape material substitution decisions and converter capital allocation across the continent.
Market Dynamics
Extended producer responsibility frameworks across Africa are forcing converters to restructure material sourcing and recycling partnerships ahead of enforcement deadlines. South Africa's Department of Forestry, Fisheries and the Environment leads this shift, with Nigeria and Kenya drafting parallel legislation that will reshape capital allocation continent-wide.
Growth Catalysts
- Flexible Film Adoption:Food and beverage producers in Nigeria's Lagos industrial corridor are expanding use of laminated pouches for powdered beverages and edible oils. Lightweight structures reduce freight cost per unit on deteriorating road networks.
- South Africa's EPR Mandate:The country's extended producer responsibility regulations accelerate demand for recyclable polyethylene and paperboard substrates. Brand owners now contract directly with recycling cooperatives to meet post-consumer recovery targets.
- Aseptic Carton Migration:Dairy and juice processors across Kenya and Ethiopia are retrofitting filling lines for ambient distribution. This technology extends shelf life without cold chain dependency in markets with unreliable refrigeration infrastructure.
Market Restraints
- Resin Import Dependency:Polypropylene and polyethylene granule supply concentrates on Middle Eastern and Asian petrochemical exporters. Currency volatility in Nigeria and Egypt amplifies working capital requirements for converters holding dollar-denominated inventory.
- Recycling Infrastructure Gaps:Formal collection systems cover under 15 percent of post-consumer plastic in sub-Saharan markets outside South Africa. Informal waste picker networks lack standardized sorting protocols, contaminating recovered polymer streams.
- Energy Cost Volatility:Grid instability and diesel generator dependence inflate conversion costs for extrusion and thermoforming operations. Ghana and South Africa experience the most severe electricity supply disruptions, forcing production stoppages.
Strategic Opportunities
- Pharmaceutical Blister Expansion:Export-oriented drug manufacturers in Tunisia and Morocco require migration-tested PVC and aluminum foil laminates. This segment commands price premiums over commodity food packaging.
- Biopolymer Feedstock Localization:Cassava and sugarcane bagasse processing in East Africa offers pathway to domestic biodegradable film production. Kenya's agricultural waste volumes could support pilot-scale PLA and starch-compound extrusion.
- Cross-Border Harmonization:The African Organisation for Standardisation coordinates unified packaging specifications for regional trade. Early alignment with these protocols positions converters for preferential procurement under the African Continental Free Trade Area.
Industry Challenges
- Technical Skills Scarcity:Gravure printing and multi-layer coextrusion expertise concentrates in South Africa and Egypt. Converters in francophone West Africa struggle to recruit operators capable of maintaining European-imported production lines.
- Migration Testing Bottlenecks:Food safety agencies in Nigeria and Kenya mandate laboratory certification for all food-contact materials. Accredited testing facilities number fewer than ten across the continent, extending product launch timelines by four to eight months.
- Legacy Equipment Integration:Retrofitting older extrusion lines for recycled content feedstock requires screw and die modifications. Many mid-scale converters lack engineering capacity to execute these conversions without external technical assistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Packaging Market |
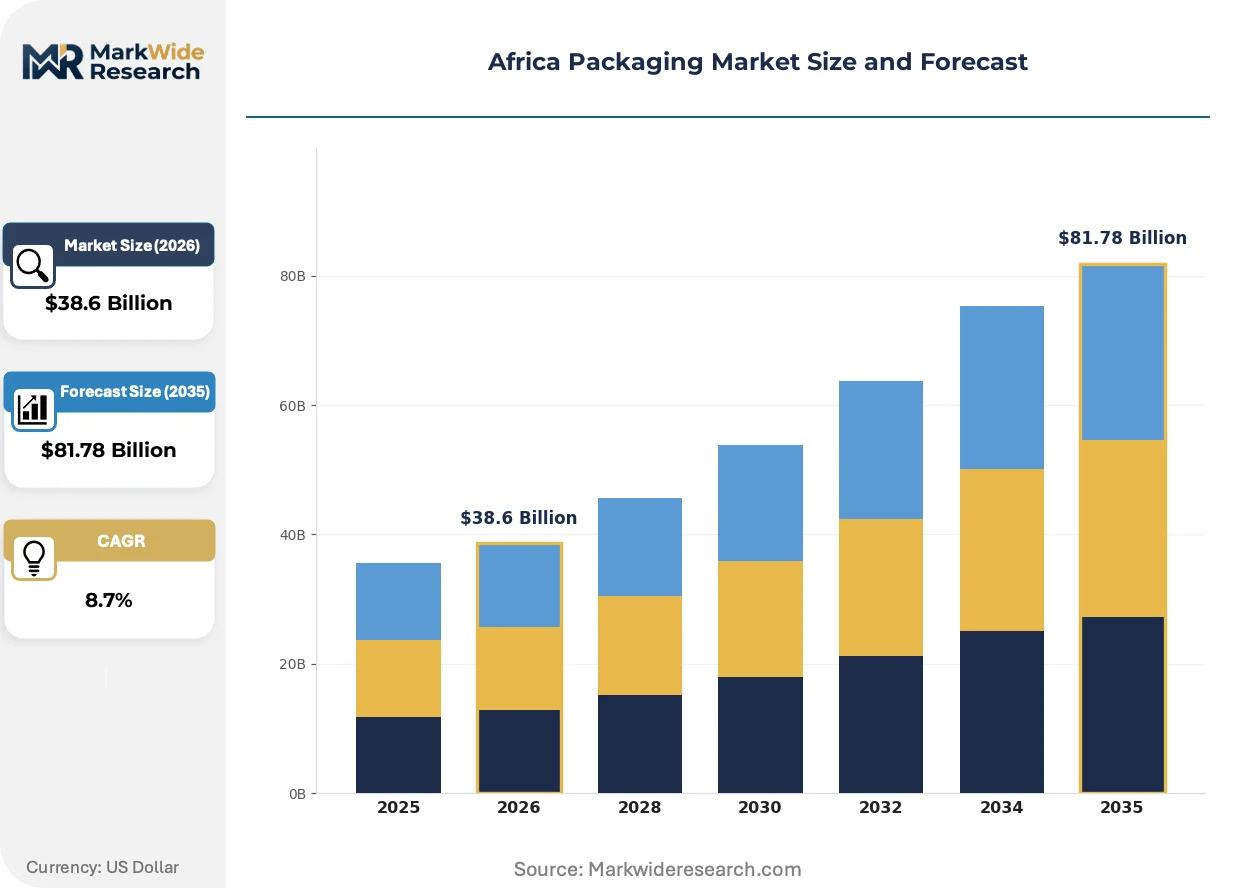
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard Packaging, Glass Packaging Material: Polyethylene, Polypropylene, Paper, Metal End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Packaging Type: Bags, Containers, Bottles, Boxes |
| Companies Covered | Astrapak Ltd, Constantia Flexibles Group, Nampak Limited, Amcor plc, Tetra Pak SA, Mondi Group, Foster Packaging International, Consol Glass, Mpact Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Packaging Market Emerging Trajectories
Material science advances and regulatory pressure are converging to accelerate substrate substitution across Africa's packaging value chain. Converters are repositioning around circularity credentials and lightweighting performance to defend margin structures against imported finished goods.
Mono-material polyethylene films are migrating from niche pharmaceutical applications toward mainstream food packaging in South Africa and Nigeria. Nestlé and Unilever procurement teams have mandated recyclable structures for snack and detergent portfolios by 2027. This technology compression is collapsing the historical distinction between high-performance barrier films and commodity polyethylene, forcing specialty resin suppliers to reformulate for sortability.
South Africa's extended producer responsibility regulations are creating compliance infrastructure that did not exist three years prior. The framework assigns recycling accountability to brand owners based on tonnage placed on market. Food and personal care multinationals are responding by pre-paying recycler fees and specifying post-consumer recycled content minimums in supplier contracts.
Modern trade format expansion in Lagos, Nairobi, and Johannesburg is consolidating procurement authority into fewer retail headquarters. Shoprite and Spar Group buyers now negotiate direct with converters for private-label packaging, bypassing traditional wholesale layers. This concentration is visible most acutely in rigid containers for cooking oils and household chemicals, where volume commitments justify dedicated production lines.
Africa Packaging Market Segmentation
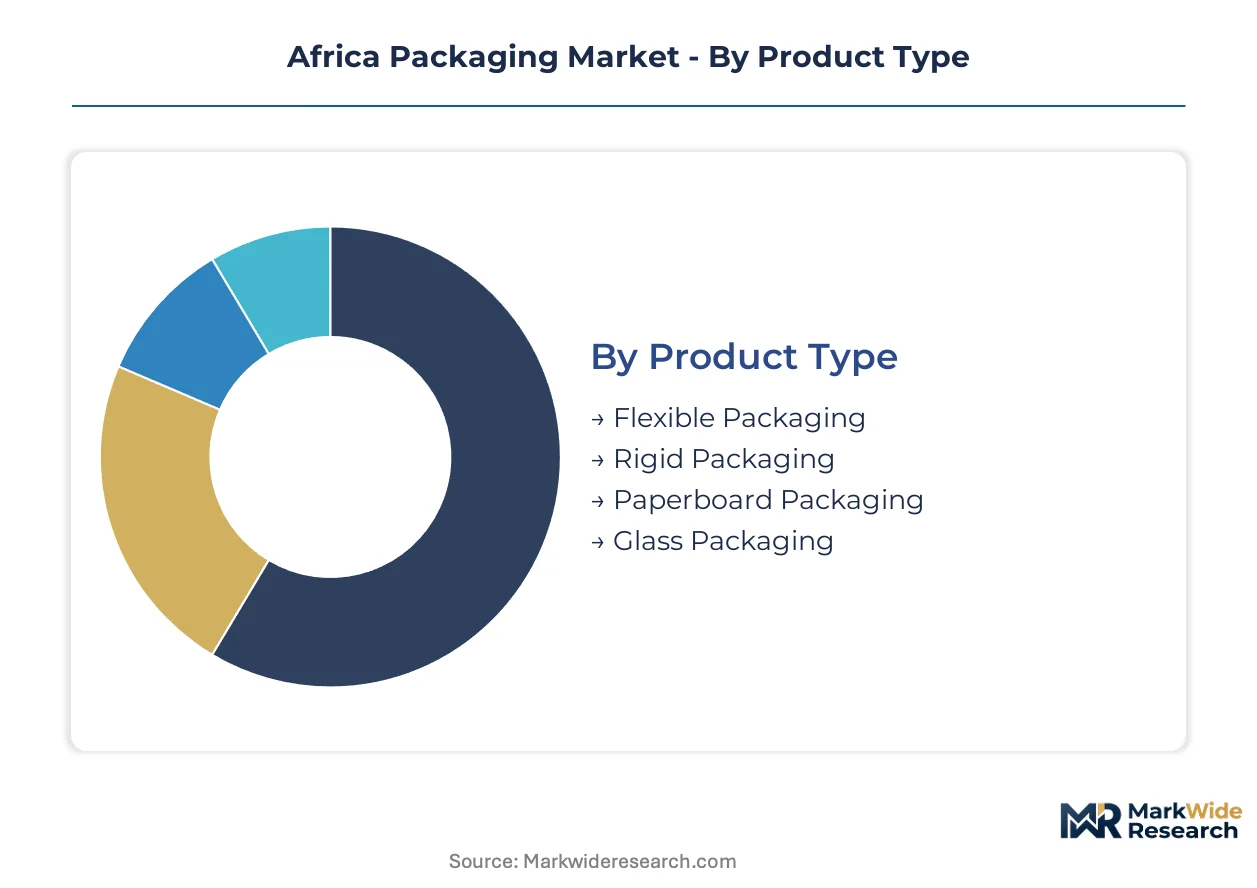
Packaging converters across Africa configure production assets around four distinct segmentation axes. Material selection and end-use specifications dictate equipment investment, resin procurement contracts, and recycling partnerships in ways that vary sharply by country regulatory maturity.
Product Type:
After-sales service intensity runs highest for flexible packaging lines requiring frequent die and cylinder replacements, while rigid and glass systems demand less intensive maintenance contracts.
- Flexible Packaging:Multi-layer films and laminated pouches dominate powdered beverage and snack distribution in Nigeria's Lagos corridor. Lightweight structures cut freight costs on deteriorating road networks, though converters struggle with gravure cylinder sourcing delays.
- Rigid Packaging:Injection-molded containers and thermoformed trays provide dimensional stability for edible oils and household chemicals. South African brand owners now specify minimum post-consumer recycled content thresholds under extended producer responsibility frameworks.
- Paperboard Packaging:Corrugated cases and folding cartons capture premium positioning in pharmaceutical outer packaging and fresh-produce export logistics from Kenya.
- Glass Packaging:Inert barrier properties sustain structural share in spirits and pharmaceutical ampoules, with furnace operations concentrated in Egypt and South Africa.
Flexible packaging holds the largest share; momentum sits with rigid formats as recycled feedstock integration accelerates.
Material:
Cost tier stratification separates commodity resins from specialty substrates, with polyethylene commanding volume leadership and metal laminates anchoring pharmaceutical price premiums.
- Polyethylene:Mono-material films are migrating from niche pharmaceutical applications toward mainstream food packaging. Nestlé and Unilever procurement teams have mandated recyclable polyethylene structures for snack and detergent portfolios.
- Polypropylene:Biaxially oriented films and injection-molded closures serve edible oil and dairy segments, though import dependency on Middle Eastern petrochemical exporters amplifies currency volatility exposure.
- Paper:Kraft linerboard and corrugated medium support fresh-produce export logistics, with Mondi Group tailoring specifications for Kenyan and South African agricultural shippers.
- Metal:Aluminum foil laminates and tinplate containers command price premiums in pharmaceutical blister packs and infant formula cans, with migration-tested specifications required for Tunisian and Moroccan export markets.
Polyethylene dominates volume; metal substrates are climbing the fastest on pharmaceutical export demand.
End User:
Application-specific barrier requirements and regulatory compliance burdens fragment converter capabilities across food safety, pharmaceutical migration testing, and cosmetic stability protocols.
- Food & Beverage:Aseptic carton retrofitting accelerates across Kenya and Ethiopia as dairy and juice processors seek ambient distribution without cold chain dependency. Flexible pouches displace rigid formats in powdered beverages.
- Pharmaceuticals:Export-oriented drug manufacturers in Tunisia and Morocco require PVC and aluminum foil laminates meeting stringent migration standards. Accredited testing facility scarcity extends product launch timelines.
- Personal Care:Paperboard outer cartons and flexible sachets compete for shelf presence, with print fidelity supporting brand differentiation in South African modern trade formats.
- Household Products:Rigid polyethylene containers lead in bleach and detergent categories where chemical resistance prevents leakage, with Lagos industrial corridor manufacturing clusters driving bulk procurement.
Food and beverage holds the largest share; pharmaceuticals are expanding most quickly on export certification premiums.
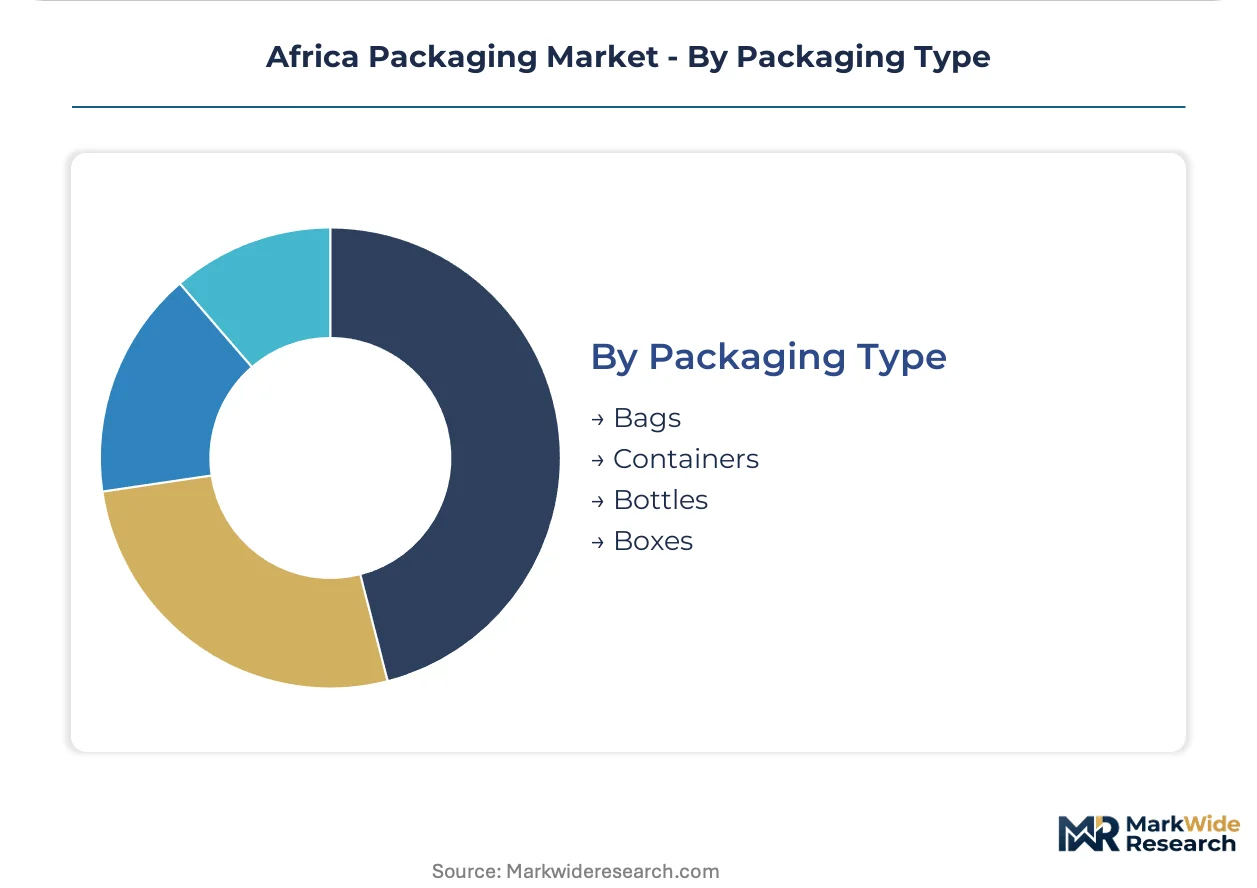
Packaging Type:
Customer procurement concentration in modern retail chains is reshaping format preferences, with direct converter relationships displacing traditional wholesale layers.
- Bags:Laminated flexible pouches and woven polypropylene sacks serve grain and powdered beverage distribution, with lightweighting reducing unit freight costs.
- Containers:Rigid plastic pails and drums capture cooking oil and chemical volumes, with Shoprite and Spar Group buyers negotiating direct supply agreements bypassing intermediaries.
- Bottles:PET and HDPE formats compete in edible oils and personal care, though glass retains spirits and pharmaceutical ampoule segments demanding inert barriers.
- Boxes:Corrugated cases and folding cartons align with fresh-produce export logistics and pharmaceutical secondary packaging, with print quality supporting brand differentiation.
Containers hold the largest share; bags are gaining share fastest on flexible film substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Durban's container handling capacity underwrites South Africa's role as the primary gateway for packaging machinery imports and polymer resin distribution across Southern Africa. This logistics backbone connects Gauteng's manufacturing belt to export corridors serving landlocked neighbors.
South Africa
Extended producer responsibility frameworks from the Department of Forestry, Fisheries and the Environment are restructuring converter obligations around post-consumer recovery targets. Johannesburg's industrial corridor hosts Nampak Limited and Mpact Ltd operations where beverage can and paperboard recycling partnerships are now contractually mandated. Cape Town's pharmaceutical cluster demands migration-tested blister laminates for export compliance.
Nigeria
Lagos industrial corridor manufacturing clusters are driving bulk procurement of rigid containers and laminated films for edible oils and powdered beverages. The Standards Organisation of Nigeria mandates laboratory certification for all food-contact materials, extending product launch timelines. Kano's agricultural processing belt is expanding woven polypropylene sack demand for grain distribution.
Kenya
Dairy and juice processors across Nairobi and Thika are retrofitting filling lines for aseptic carton technology to enable ambient distribution without cold chain dependency. The Kenya Bureau of Standards coordinates harmonized specifications with the African Organisation for Standardisation for cross-border trade. Mombasa's port infrastructure supports fresh-produce export logistics requiring Mondi Group's corrugated specifications.
Egypt
Glass furnace operations concentrated in Alexandria and Cairo supply pharmaceutical ampoules and spirits bottles demanding inert barrier properties. The Egyptian Organization for Standardization and Quality enforces food safety protocols aligned with export market requirements. Suez Canal Zone industrial parks are attracting flexible film converters serving North African and Middle Eastern markets.
Ethiopia
Addis Ababa's beverage processors are adopting aseptic carton formats to bypass refrigeration infrastructure gaps in rural distribution networks. The Ethiopian Food and Drug Authority is building migration testing capacity to reduce dependency on South African laboratories. Hawassa Industrial Park's manufacturing tenants are sourcing rigid containers from domestic injection molding operations.
Africa Packaging Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated multinational converters and regional specialists serving national regulatory environments. South African and Egyptian operations anchor capacity for polymer extrusion and glass furnace production, while Nigerian and Kenyan markets attract trading-house intermediaries supplying imported finished goods. Three archetypes dominate: integrated substrate producers controlling resin-to-converter value chains, flexible packaging specialists targeting pharmaceutical export compliance, and rigid container fabricators serving fast-moving consumer goods clusters. Competitive positioning hinges on backward integration into recycling cooperatives and technology licensing for aseptic filling compatibility.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify substrate-to-converter control spanning multiple African markets. Nampak Limited represents the regional champion archetype, leveraging Southern African operational density to defend supply advantages. Constantia Flexibles Group occupies a specialized position where pharmaceutical blister and sachet capabilities command compliance premiums over commodity food packaging. Tetra Pak SA anchors the aseptic technology vector, with filling line retrofitting partnerships determining converter selection across East African dairy markets.
| Leading Market Players |
|---|
| Astrapak Ltd |
| Constantia Flexibles Group |
| Nampak Limited |
| Amcor plc |
| Tetra Pak SA |
| Mondi Group |
| Foster Packaging International |
| Consol Glass |
| Mpact Ltd |
| Others |
Supply Flow & Price Mechanics
Underutilized extrusion capacity in Egypt's Alexandria industrial zone is compressing contract-manufacturing rates for polyethylene film converters, forcing suppliers to absorb resin volatility while buyers consolidate procurement volumes. This utilization gap simultaneously weakens supplier pricing power and accelerates direct-contracting trends among Lagos and Nairobi-based brand owners.
Pricing Analysis
Volume-discount tiering separates multinational fast-moving consumer goods buyers from mid-scale regional converters and informal trading-house intermediaries. Premium-mid-economy pricing differentiation rests on migration-testing certification and aseptic filling-line compatibility, with pharmaceutical-grade laminates commanding substantial premiums over commodity food-contact films. Price erosion runs through standard-tier polyethylene pouch segments as Shoprite and Spar Group procurement teams consolidate supplier panels. Informal wholesale layers exhibit highest price sensitivity, while export-oriented pharmaceutical manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration sits with Nampak Limited and Mpact Ltd in South Africa's Gauteng corridor, alongside Tetra Pak SA's aseptic filling partnerships across East Africa. Raw material procurement draws from Middle Eastern polypropylene and polyethylene exporters, Egyptian glass furnace operations, and Kenyan kraft linerboard producers. Single-source vulnerability concentrates in gravure cylinder supply and accredited migration-testing laboratory access. Distribution runs through Durban's container port for polymer resin imports, with Mombasa and Lagos handling regional converter-to-manufacturer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a capital-expenditure trough as extended producer responsibility deadlines trigger converter retrofitting cycles across Southern and West Africa.
For Market Incumbents: Pre-empt recycling cooperative acquisition before South Africa's post-consumer recovery targets tighten supplier eligibility criteria. Secure backward integration into cassava-derived biopolymer feedstocks in East Africa to defend margin position against Middle Eastern resin volatility. Prioritize aseptic filling-line certification investments to lock in dairy processor loyalty across Kenya and Ethiopia.
For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical blister-pack laminates for Tunisian and Moroccan export markets, where migration-testing scarcity creates procurement bottlenecks for incumbent converters. Target woven polypropylene sack production in Nigeria's Kano agricultural belt, bypassing Lagos corridor overcapacity. Lead with rapid laboratory certification turnaround as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among flexible packaging specialists with pharmaceutical export compliance capabilities, where multi-year supply agreements predominate over spot procurement. Five-to-ten-year viability favors converters with integrated recycling cooperative relationships and EPR-framework alignment. Monitor South Africa's Department of Forestry, Fisheries and Environment enforcement timelines as the critical inflection signal for capital redeployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Cooperative Integration | Direct contractual relationships with waste picker networks secure EPR compliance credits under South African regulations. |
| Aseptic Filling Line Retrofitting | Technology licensing from Tetra Pak SA determines converter selection across Kenyan and Ethiopian dairy markets. |
| Migration Testing Laboratory Investment | Accredited in-house capacity collapses four-to-eight-month product launch delays plaguing Nigerian pharmaceutical exporters. |
| Biopolymer Feedstock Localization | Cassava and sugarcane bagasse processing in Kenya reduces dependency on dollar-denominated resin imports. |
| Cross-Border Harmonization Alignment | Early adoption of African Organisation for Standardisation protocols positions converters for AfCFTA preferential procurement. |
Methodological Framework
Cross-validation between converter production data and brand owner procurement disclosures anchors the qualitative findings in operational reality. Primary interviews with extrusion plant managers, pharmaceutical regulatory affairs leads, retail category buyers, and recycling cooperative coordinators were synthesized with secondary validation from customs trade records, SEC filings of multinational packaging suppliers, African Organisation for Standardisation harmonization protocols, and national food safety agency migration-testing registries. Bottom-up capacity assessments and top-down demand modeling were reconciled through iterative triangulation.
Calibration against historical resin price volatility and enforcement timeline slippage shaped the projection framework. Segmentation dimensions modeled include material substrate, product format flexibility, end-use regulatory tier, and regional logistics infrastructure maturity. CAGRs were derived from supply-side capacity expansion schedules and demand-side procurement consolidation patterns, with specific weighting applied to EPR-framework implementation phasing and aseptic technology adoption curves.
Sensitivities concentrate around currency volatility in Nigerian and Egyptian resin import markets, grid instability disrupting South African and Ghanaian extrusion operations, and divergence in national plastic waste regulation timelines. Quarterly review of Department of Forestry, Fisheries and Environment enforcement actions, naira and pound exchange rate movements against dollar-denominated resin contracts, and accredited laboratory capacity additions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
VCI Packaging Market