
 Tertiary Packaging Market | 2026-2036
Tertiary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tertiary Packaging Market Outlook
Reusable pallet tracking through IoT-enabled asset management is fragmenting traditional one-way shipping models across supply chains. Brambles sustains the largest pooled equipment network through its CHEP brand, operating across grocery and retail verticals in multiple continents. Mondi Group anchors European corrugated tertiary packaging capacity with integrated kraft paper and containerboard production. Sonoco Products Company differentiates through engineered wood and composite pallet systems serving pharmaceutical cold chain requirements.
Tertiary packaging denotes the outermost shipping layer—pallets, slip sheets, stretch wrap, and strapping—that unitizes primary and secondary packages for mechanical handling, typically specified to withstand forklift penetration, stacking loads, and moisture exposure during intermodal transit. Its commercial purpose centers on protecting goods through distribution while enabling warehouse automation compatibility. Plastic pallets represent the fastest-expanding material category as hygiene-sensitive food and pharmaceutical end users phase out wood alternatives prone to contamination and splintering. E-commerce and food and beverage applications command the dominant share of unit volume, though pharmaceutical-grade tertiary packaging carries substantially higher margin pools due to temperature validation and serialization requirements.
The EU Packaging and Packaging Waste Regulation and the US EPA sustainable materials management framework are tightening recycled content mandates and extended producer responsibility obligations, directly elevating compliance costs for cardboard and plastic tertiary formats. ISO 8611 pallet testing standards and FDA food contact material regulations further shape product specifications and market access thresholds for suppliers serving regulated industries. Stakeholders must monitor evolving state-level packaging EPR legislation in the United States and pending EU harmonization rules that will determine which material platforms retain cost advantages in cross-border fulfillment networks.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material choice windows while e-commerce fulfillment automation is forcing dimensional standardization across pallet and corrugated formats.
Growth Catalysts
- Recycled content mandates:The EU Packaging and Packaging Waste Regulation mandates minimum recycled thresholds for corrugated containers, compelling converters to retool furnish mixes and secure long-term recovered fiber supply contracts.
- IoT-enabled asset tracking:Food and pharmaceutical logistics operators are deploying pallet-level sensors to monitor location, temperature, and shock events, reducing shrinkage and enabling dynamic routing.
- Pharmaceutical cold chain expansion:Temperature-validated tertiary packaging demand is accelerating in Germany, China, and the United States as biologics distribution networks multiply.
Market Restraints
- Recovered fiber cost volatility:Old corrugated container feedstock prices swing with municipal collection rates and Chinese import policy shifts, compressing margins for integrated producers.
- Plastic resin supply concentration:Polypropylene pallet production depends on Gulf Coast petrochemical complexes vulnerable to hurricane disruptions and export quota fluctuations.
- Wooden pallet sanitation limits:ISPM-15 heat treatment requirements and moisture absorption constraints block wood from pharmaceutical cleanrooms and fresh produce washdown environments.
Strategic Opportunities
- India fulfillment infrastructure:E-commerce penetration in tier-two and tier-three cities lacks standardized pallet pooling networks, creating first-mover terrain for equipment-leasing platforms.
- Reusable packaging as a service:Pooling models combined with blockchain-based custody tracking are emerging as alternatives to single-use corrugated for high-velocity retail loops.
- Carbon border adjustment alignment:EU importers are sourcing tertiary packaging from low-carbon containerboard mills to preempt CBAM-equivalent scope three penalties on embedded emissions.
Industry Challenges
- Automation integration timelines:Warehouse robotics vendors require pallet dimensional tolerances within two millimeters, forcing tertiary packaging suppliers to recalibrate extrusion and forming equipment.
- Serialization compliance complexity:Pharmaceutical tertiary packaging must integrate with EU MDR and FDA track-and-trace systems, extending qualification cycles and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tertiary Packaging Market |
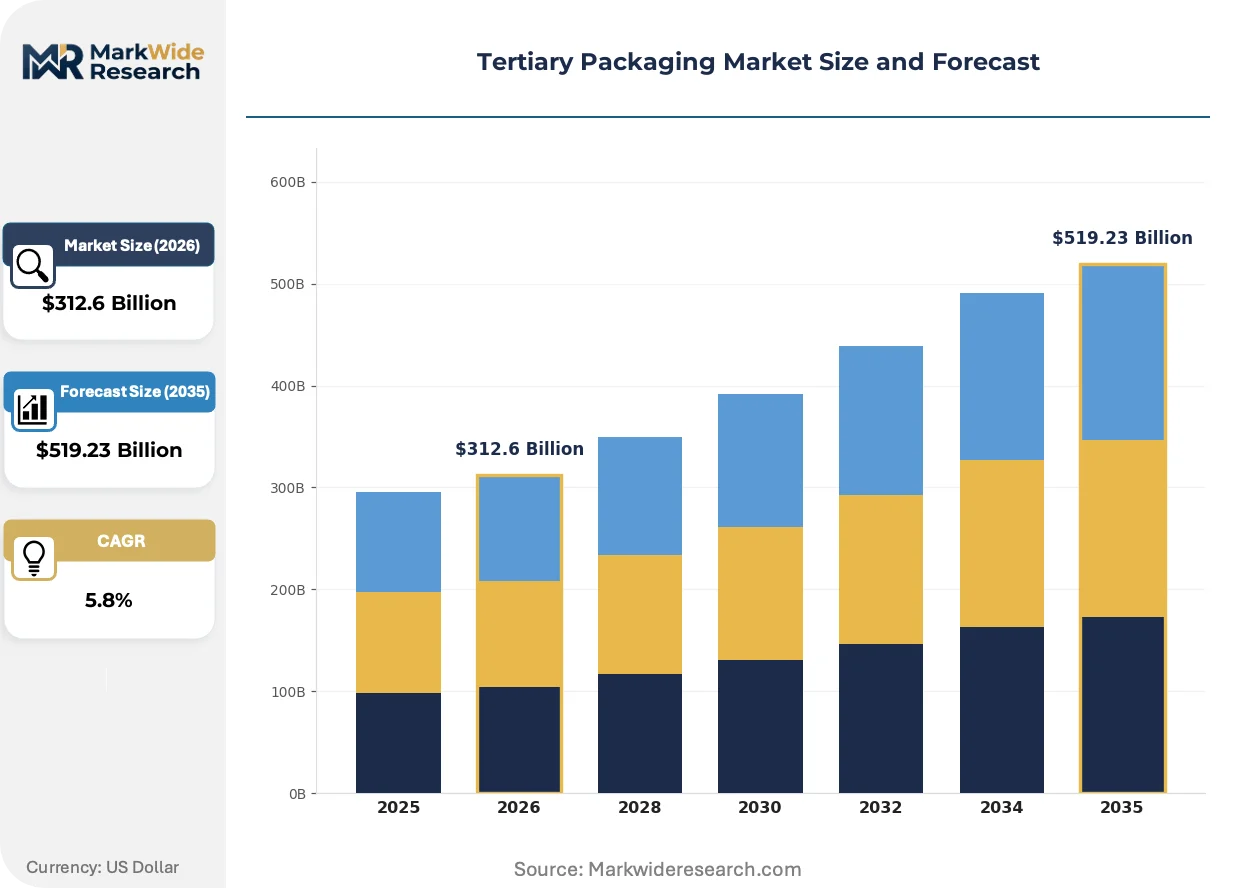
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Containers, Crates, Shrink Wrap Material: Wood, Plastic, Metal, Cardboard End User: E-Commerce, Food & Beverage, Pharmaceuticals, Electronics Application: Storage, Transportation, Distribution, Retail Display |
| Companies Covered | Mondi Group, Brambles, Amcor, Rengo, Sonoco Products Company, International Paper, Berry Global, Novolex, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tertiary Packaging Market Strategic Shifts
Material science advances and regulatory compression are converging to redefine performance specifications across pallet, slip sheet, and protective wrap categories.
Polypropylene structural foam is migrating from niche pharmaceutical applications toward mainstream grocery and retail pooling programs. Hygiene-sensitive operators in fresh produce and prepared foods are adopting plastic pallets at accelerated replacement cycles. This shift is compressing the addressable market for hardwood and composite alternatives in moisture-prone distribution environments.
REACH substance restrictions and EU Green Deal carbon intensity benchmarks are forcing reformulation of stretch film additives and adhesive coatings. Manufacturers are substituting bio-based cling layers and eliminating phthalate plasticizers to maintain market access. Corrugated converters serving cross-border fulfillment networks are prioritizing mills with certified renewable energy and closed-loop water systems.
Omnichannel retailers are consolidating tertiary packaging specifications across store replenishment and direct-to-consumer channels. Unified pallet and carton standards reduce sortation complexity in automated fulfillment hubs. This consolidation is most visible in Germany and the United States, where grocery chains are merging e-commerce and brick-and-mortar distribution into single network architectures.
Tertiary Packaging Market Segmentation
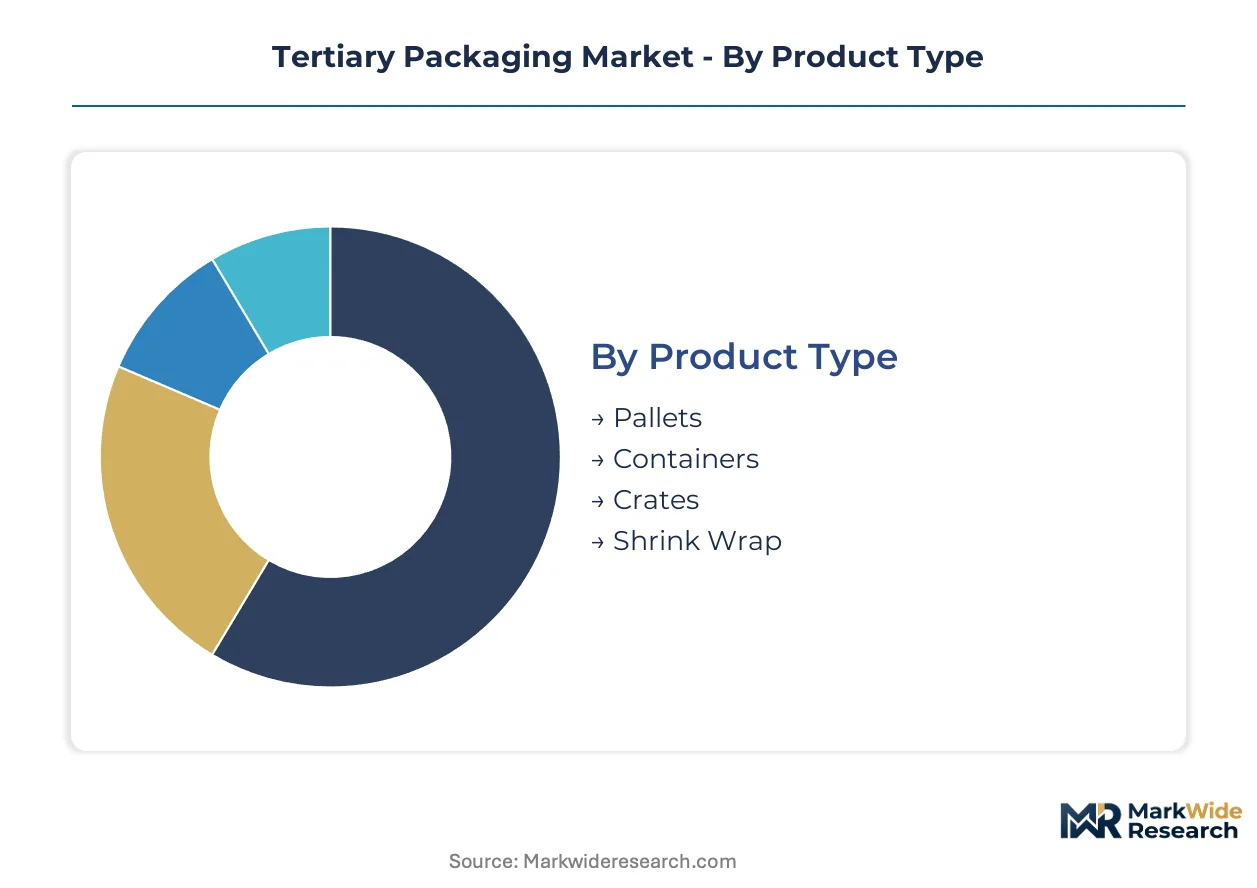
Tertiary packaging segmentation reveals divergent service intensity requirements across material platforms and end-use verticals. Pooling operators must calibrate asset tracking density, sanitation protocols, and return logistics complexity differently for each segment cluster.
Product Type:
After-sales service intensity varies dramatically across product categories, with pooled equipment demanding continuous field maintenance and single-use formats requiring minimal post-delivery support.
- Pallets:Flat transport structures built from wood, plastic, or composite materials designed for forklift entry and rack stacking. Demand concentrates in automated grocery distribution centers across Germany and the United States as retailers consolidate omnichannel fulfillment networks. CHEP and PECO pooling programs dominate, embedding RFID tags for cycle counting and damage detection.
- Containers:Rigid receptacles including bulk bins, intermediate bulk containers, and foldable large containers for dense liquid or granular cargo. Pharmaceutical manufacturers in Switzerland and Ireland specify single-use liners with validated cleaning certificates, driving premium attachment revenue streams.
- Crates:Stackable handheld containers for loose-item picking and store replenishment. Dairy and bakery distributors in France deploy standard footprint crates through closed-loop retail return systems.
- Shrink Wrap:Polyethylene film applied through automated turntable or orbital stretch systems to unitize palletized loads. Fresh produce exporters in Spain and Italy prioritize puncture-resistant formulations for refrigerated maritime transit.
Pallets hold the largest share; momentum sits with containers as pharmaceutical serialization requirements expand.
Material:
Cost tier stratification separates premium hygiene-validated materials from commodity substitutes, with compliance burdens determining viable substitution thresholds.
- Wood:Hardwood and softwood lumber constructed through nailed or block assembly, subject to ISPM-15 heat treatment for cross-border phytosanitary compliance. Grocery distributors in Poland and Romania retain wood for dry goods where moisture exposure remains minimal.
- Plastic:High-density polyethylene and polypropylene formulations molded through structural foam or twin-sheet thermoforming. Food processors in the Netherlands and Belgium are displacing wood in washdown environments requiring daily sanitization cycles.
- Metal:Steel or aluminum fabrication for extreme load ratings and fire-resistant specifications. Automotive component logistics in Germany and Mexico specify metal stillages for engine block transport.
- Cardboard:Corrugated fiberboard pallets and slip sheets for lightweight, single-trip export applications. E-commerce fulfillment operators in the United Kingdom trial cardboard alternatives to reduce return freight costs in reverse logistics.
Wood retains volume leadership; plastic is gaining share fastest in hygiene-regulated end uses.
End User:
Application-specific performance requirements create distinct margin pools, with temperature-validated segments commanding pricing premiums over ambient logistics.
- E-Commerce:Omnichannel retail fulfillment demanding dimensional standardization for automated sortation and last-mile compatibility. Amazon and Zalando specification convergence in Germany is forcing pallet footprint harmonization across supplier bases.
- Food & Beverage:The dominant volume segment spanning fresh produce, dairy, meat, and beverage distribution. Cold chain operators in California and Florida specify plastic pallets with drainage channels for ice-packed seafood transport.
- Pharmaceuticals:Temperature-validated tertiary packaging with EU MDR and FDA track-and-trace integration. Biologics distributors in Massachusetts and North Carolina require thermal qualification documentation across the entire packaging hierarchy.
- Electronics:Electrostatic discharge protection and shock attenuation for semiconductor and consumer device distribution. Cleanroom-compatible materials are mandatory for wafer transport in South Korea and Taiwan fabrication facilities.
Food & Beverage holds the largest share; Pharmaceuticals shows the steepest expansion trajectory as biologics networks multiply.
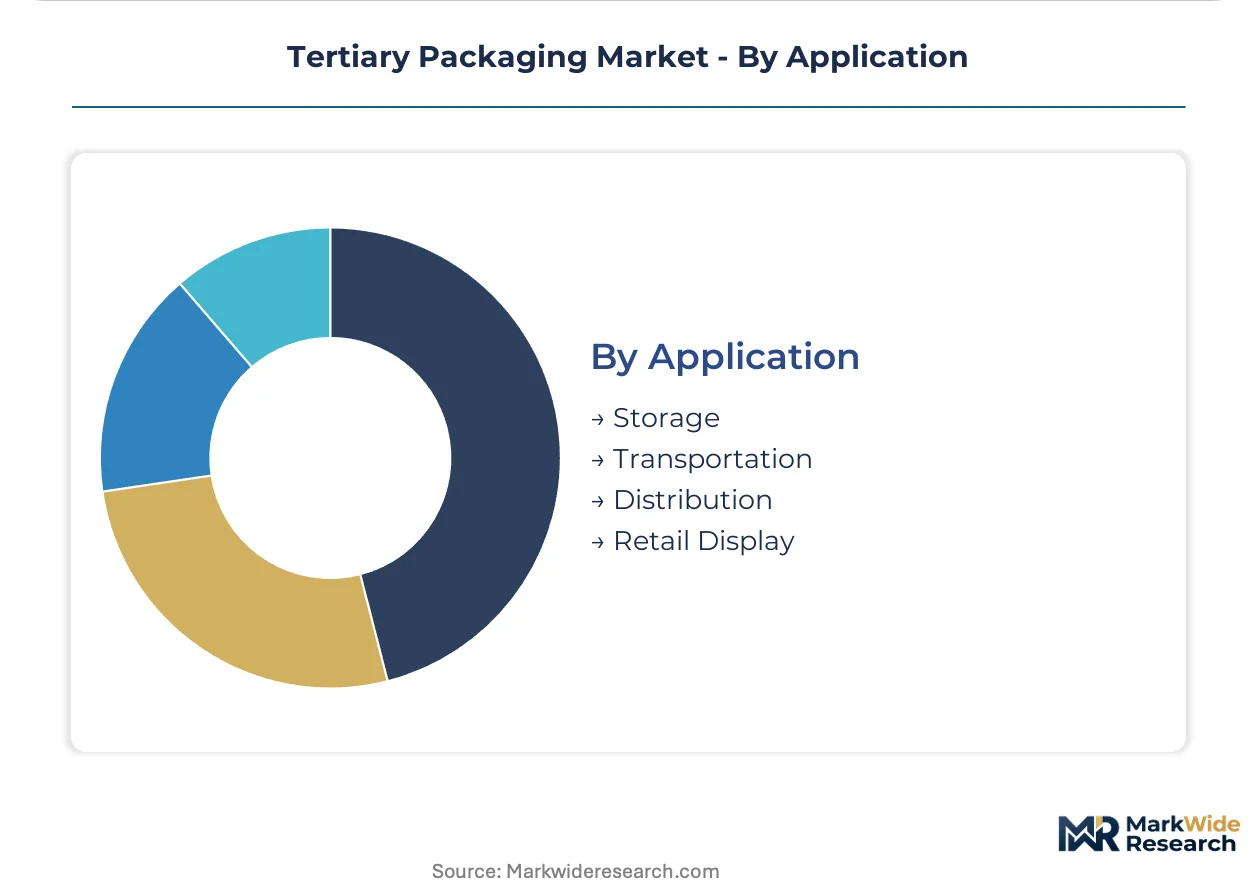
Application:
Volume concentration varies by operational phase, with transportation-facing formats subject to higher damage rates and replacement frequency than static storage assets.
- Storage:Rack-compatible pallets and containers designed for warehouse density optimization. Automated storage and retrieval system vendors in Germany specify dimensional tolerances within millimeter ranges.
- Transportation:Intermodal-rated packaging for truck, rail, and maritime handoff. Container shipping lines impose strict weight and fumigation documentation for wooden platforms.
- Distribution:Cross-dock and transload environments requiring rapid transfer between conveyance modes. Retail consolidation centers in Illinois and Pennsylvania prioritize four-way entry for multidirectional forklift access.
- Retail Display:Shelf-ready tertiary formats reducing backroom labor through direct-to-floor presentation. Mass merchants in Texas and Florida are piloting display-ready pallets for promotional velocity items.
Transportation holds the largest share; Retail Display is climbing the fastest as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in containerized freight are reshaping tertiary packaging demand patterns across major logistics corridors. Countries with persistent goods trade surpluses require higher asset velocity in pooling networks, while deficit markets accumulate packaging waste or face return-logistics cost penalties.
United States
E-commerce fulfillment automation is driving dimensional standardization across pallet formats in distribution hubs serving omnichannel retail networks. The EPA sustainable materials management framework is tightening recycled content expectations for corrugated tertiary packaging. Chicago and Philadelphia retail consolidation centers prioritize four-way entry pallets for multidirectional forklift access in high-velocity cross-dock environments.
Germany
Automotive component logistics and grocery distribution are converging on pooled plastic pallet specifications for automated storage and retrieval compatibility. The EU Packaging and Packaging Waste Regulation mandates minimum recycled thresholds for corrugated containers, compelling converters to secure long-term recovered fiber supply contracts. The Rhine-Ruhr logistics corridor hosts dense networks of equipment pooling depots serving pan-European fulfillment loops.
China
Biologics distribution expansion is accelerating demand for temperature-validated tertiary packaging in pharmaceutical cold chain networks. SAMR enforcement of GB standards for food contact materials is elevating hygiene specifications for plastic pallets in fresh produce logistics. The Yangtze River Delta manufacturing belt generates concentrated demand for export-rated wooden pallets subject to ISPM-15 heat treatment protocols.
India
E-commerce penetration in tier-two and tier-three cities is outpacing standardized pallet pooling infrastructure, creating equipment-leasing gaps for fulfillment operators. The FSSAI is tightening food-grade packaging material specifications for domestic distribution networks. Maharashtra and Karnataka industrial corridors are piloting reusable container programs for automotive component suppliers serving export assembly plants.
Brazil
Agricultural export logistics are sustaining demand for hardwood pallets in soybean and coffee supply chains subject to phytosanitary compliance. ANVISA pharmaceutical packaging regulations are elevating traceability requirements for tertiary formats serving domestic drug distribution. The São Paulo state logistics cluster is consolidating cold chain infrastructure for protein exports to Asian markets.
Tertiary Packaging Market Competitive Environment
On the supply side, the industry is bifurcating between capital-intensive pooling operators with embedded asset networks and specialized converters serving single-trip export applications. Consolidation pressures concentrate in corrugated containerboard, where integrated producers command recovered fiber supply advantages. Three strategic archetypes dominate: multinational pooling platforms with IoT-enabled tracking infrastructure, regional corrugated converters with mill-direct cost positions, and niche specialists in pharmaceutical-grade temperature-validated systems. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure long-term supply contracts with e-commerce and food logistics operators.
Among integrated packaging conglomerates with mill and converting assets, Mondi Group, International Paper, and WestRock exemplify the scale-driven archetype serving omnichannel retail and industrial distribution networks. These entities occupy positions spanning containerboard production through finished corrugated tertiary formats, enabling furnish optimization in response to recycled content mandates. Brambles, operating through its CHEP brand, represents the pooling-platform model with embedded RFID tracking infrastructure and grocery-retail vertical specialization. Sonoco Products Company sits within the engineered-materials tier, anchoring composite and wood-based systems for pharmaceutical cold chain requirements where temperature validation and serialization integration command premium positioning.
| Leading Market Players |
|---|
| Mondi Group |
| Brambles |
| Amcor |
| Rengo |
| Sonoco Products Company |
| International Paper |
| Berry Global |
| Novolex |
| WestRock |
| Others |
Value Chain & Pricing Dynamics
Chinese containerboard mill concentration in the Yangtze River Delta feeds directly into margin capture by European corrugated converters serving omnichannel fulfillment networks. Recovered fiber cost volatility and resin supply bottlenecks create asymmetric pricing power across material tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for pooled plastic pallets, while pharmaceutical distributors absorb premium-mid-economy pricing differentiation driven by EU MDR certification tiers and temperature validation documentation. Price differentiation hinges on ISO 8611 testing compliance and RFID tracking integration. Cost compression in commodity corrugated runs through Chinese import policy shifts and OCC feedstock auction dynamics. Food and beverage logistics operators exhibit highest price sensitivity due to thin operating margins, whereas biologics distributors prioritize performance validation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for polypropylene resin and hardwood lumber inputs. Manufacturing concentrates in China, Germany, and the United States for structural foam pallets; recovered fiber pulping clusters in Sweden, Finland, and Brazil supply kraft linerboard. Raw material dependencies rest on Gulf Coast petrochemical complexes for PP resin, Baltic Sea timber concessions for hardwood, and municipal collection systems for OCC feedstock. Single-source vulnerability in semiconductor-enabled RFID tag production threatens tracking infrastructure deployment. Distribution runs through CHEP and PECO depot networks in grocery retail, with direct mill relationships serving e-commerce corrugated demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from reusable packaging-as-a-service models that displace single-trip corrugated in high-velocity retail loops. Blockchain-tracked pooling platforms threaten traditional ownership-based pallet economics.
For Market Incumbents: Entrench position through backward integration into recovered fiber supply contracts and captive RFID manufacturing capacity. CHEP-style pooling operators should deepen sensor infrastructure density to defend against emerging platform competitors. Certification investment in EU MDR and FDA track-and-trace integration preserves pharmaceutical margin pools against composite pallet specialists. For New Entrants and Emerging Players: Pursue white-space expansion in India's tier-two and tier-three e-commerce fulfillment corridors where standardized pooling infrastructure remains absent. Target pharmaceutical cold chain validation services in China and Germany where biologics distribution networks multiply fastest. Go-to-market leverage rests on blockchain-based custody tracking differentiated from incumbent RFID architectures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corrugated converters lacking mill-direct furnish positions. Long-term viability favors integrated producers with renewable energy-certified containerboard capacity and closed-loop water systems. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as inflection signal for recycled content mandate compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Supply | Secures OCC feedstock contracts ahead of EU recycled content mandates tightening converter economics. |
| RFID Manufacturing Capacity Expansion | Reduces single-source vulnerability in pallet-level sensor procurement for IoT-enabled asset tracking. |
| Pharmaceutical Cold Chain Certification Investment | Captures biologics distribution premium through EU MDR and FDA track-and-trace system integration. |
| Reusable Packaging-as-a-Service Platform Launch | Displaces single-use corrugated in high-velocity retail loops through blockchain-tracked pooling models. |
| Renewable Energy Mill Certification Program | Aligns containerboard production with EU Green Deal carbon intensity benchmarks for CBAM-equivalent scope three positioning. |
Study Parameters
Initial hypotheses were tested against primary input from logistics operations directors, corrugated procurement managers, pharmaceutical supply chain executives, and pooling platform asset managers and refined through secondary validation against SEC 10-K filings, EU Packaging and Packaging Waste Regulation implementation documents, customs trade data, and containerboard mill production disclosures. Bottom-up demand modeling across end-use verticals triangulated with top-down macroeconomic indicators.
Demand-supply balance dynamics shaped the analytical framework across the analysis window, with segmentation dimensions spanning material platform, product type, end-use vertical, and regional regulatory cluster. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated e-commerce fulfillment automation penetration rates and pharmaceutical cold chain infrastructure buildout timelines.
Sensitivities concentrate around Chinese OCC import policy shifts, Gulf Coast hurricane disruption frequency, and EU harmonization rule finalization timelines. Forecasts reflect documented assumptions on substitution elasticity between wood and plastic pallet platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Flow Wraps Market
Packaging Materials
France Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Twist Tie Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Reel in Box Market