
 VCI Films Market | 2026-2036
VCI Films Market Size, Share, and Industry Trends Forecast 2026-2036
VCI Films Market Analytics
The capital-intensity divergence between integrated resin producers and specialty compounders is collapsing as blown-film extrusion lines below 1500mm width become commoditized. Cortec Corporation leverages captive VCI masterbatch synthesis to sustain margin capture across polyethylene and polypropylene substrates. Aicello Corporation anchors its position through precision thickness control in sub-50 micron films for Japanese electronics exporters. Daubert Cromwell competes on regional stocking density, operating conversion facilities near Detroit automotive clusters and Hamburg port logistics hubs.
VCI films are multi-layer polyolefin or PVC substrates impregnated with volatile corrosion inhibitors that sublime from the polymer matrix to form a molecular barrier on ferrous and non-ferrous metal surfaces, typically achieving 24-month protection at thicknesses between 25 and 150 microns. Polyethylene formulations dominate volume due to cost-efficient extrusion compatibility and moisture resistance, while polypropylene grades command premium positioning in high-temperature automotive underhood applications. The 50-100 micron thickness band occupies the largest share of machinery and electronics packaging, whereas above-150 micron constructions are displacing rigid VCI paperboard in heavy equipment export crating where puncture resistance governs specification.
EPA restrictions on hexavalent chromium and secondary amine nitrites under TSCA Section 6 are compelling U.S. formulators to certify amine-free chemistries through NACE TM0208 test protocols. REACH Annex XVII limitations on CMR-classified substances in the European Union are blocking legacy nitrite-based VCI films from CE-marked industrial packaging, redirecting procurement toward ECHA-registered alternatives. Stakeholders must monitor evolving GB standards from China's SAMR for dual-use corrosion inhibitors that intersect with food-contact packaging regulations, as multi-purpose film specifications blur traditional market boundaries.
Market Dynamics
REACH Annex XVII restrictions on CMR-classified substances are forcing European VCI film formulators to abandon legacy nitrite-based chemistries entirely, redirecting R&D investment toward amine-free vapor-phase inhibitors and biobased alternatives. This regulatory compression is reshaping competitive positioning across the value chain.
Growth Catalysts
- EPA TSCA Section 6 enforcement:U.S. restrictions on hexavalent chromium and secondary amine nitrites are compelling domestic manufacturers to certify amine-free formulations through NACE TM0208 protocols, creating certified-supplier premiums.
- Automotive OEM procurement expansion:German and U.S. engine component manufacturers are specifying multi-layer VCI films for extended supply chain transits, particularly for precision-machined ferrous castings.
- Yangtze River Delta export concentration:China's precision machinery corridor is driving specification for humidity-activated release profiles in barrier films protecting high-value electronics exports.
Market Restraints
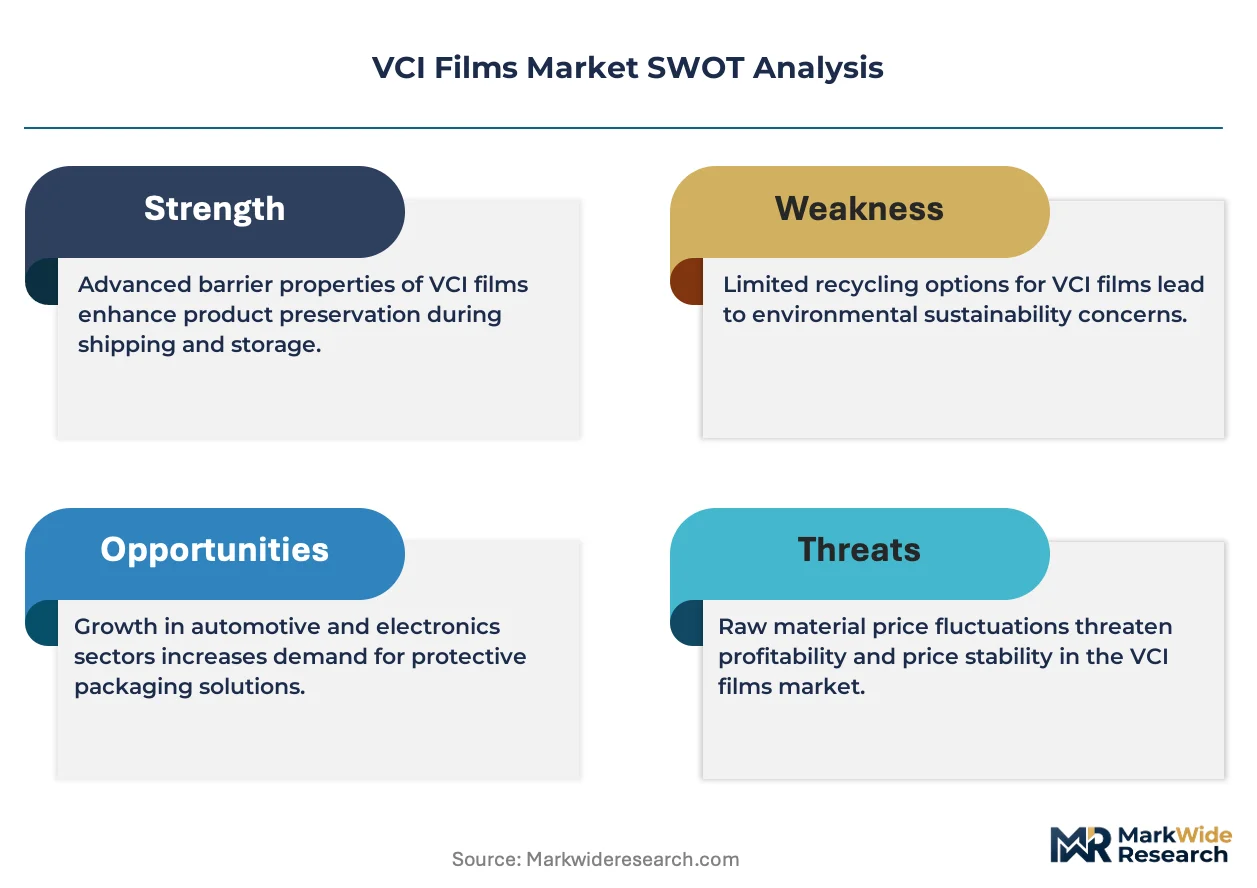
- Ethylene feedstock volatility:Polyethylene substrate costs fluctuate with naphtha-cracker economics, compressing margins for non-integrated compounders lacking captive resin supply.
- Blown-film line commoditization:Extrusion equipment below 1500mm width is collapsing price premiums for regional converters without proprietary masterbatch synthesis.
- Rigid VCI paperboard substitution:Heavy equipment exporters in port-adjacent clusters continue specifying fiber-based crating for puncture-critical applications above 200-micron equivalent protection.
Strategic Opportunities
- India BIS standardization gap:Formal corrosion inhibitor packaging standards remain underdeveloped, creating first-mover advantage for ECHA-registered suppliers establishing local compounding partnerships.
- Polypropylene high-temperature automotive:Underhood thermal requirements above 120°C are opening specification windows for PP-based films in electric vehicle powertrain component packaging.
- Food-contact dual-use convergence:China's SAMR is drafting GB standards intersecting corrosion inhibitor films with food-contact regulations, enabling multi-purpose film specifications for processed machinery exports.
Industry Challenges
- NACE TM0208 certification timelines:Third-party validation of amine-free chemistries extends new product introduction cycles by 8-14 months, delaying revenue recognition for reformulated lines.
- Multi-layer coextrusion technician scarcity:Precision thickness control in sub-50 micron films requires specialized blown-film operators concentrated in Japanese and German industrial clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCI Films Market |
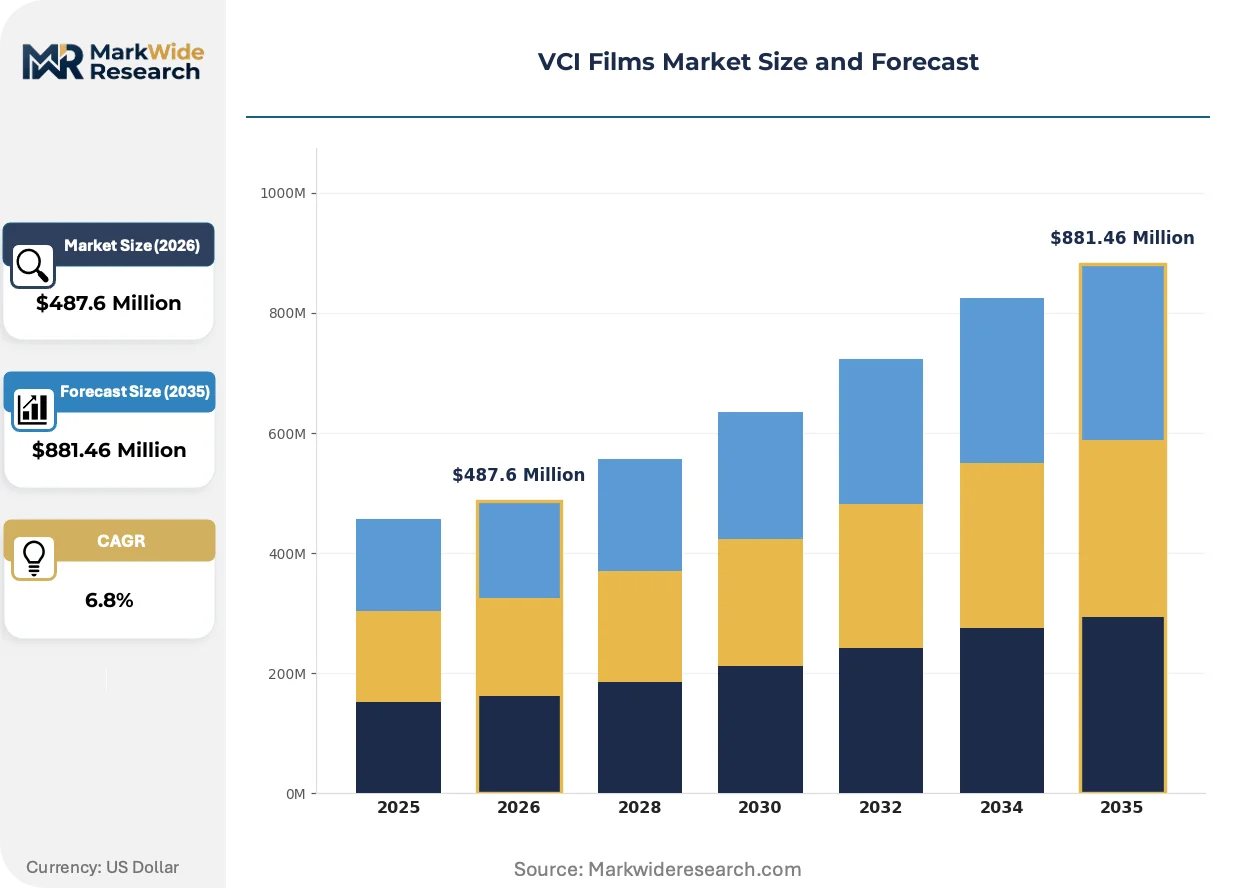
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Automotive, Electronics, Machinery, Aerospace End User: Manufacturing, Distribution, Retail, Export Thickness: Below 50 Microns, 50-100 Microns, 100-150 Microns, Above 150 Microns |
| Companies Covered | Cortec Corporation, Aicello Corporation, Armor Protective Packaging, Daubert Cromwell, Transcendia Inc., Protective Packaging Corporation, BRANOpac, Packaging Aids, Tiberchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCI Films Market Evolving Landscape
Formulation chemistry and substrate engineering are converging to address regulatory compression while extending protection duration. Three developments are restructuring how corrosion inhibition is delivered and specified across industrial packaging.
Humidity-activated VCI release systems are supplanting constant-sublimation chemistries in precision electronics packaging. Japanese automotive electronics exporters are specifying these films for ocean freight to Southeast Asian assembly plants. The technology is compressing inhibitor consumption rates by 40% in dry-storage periods while maintaining protection during transit humidity spikes.
REACH Annex XVII amendments restricting CMR substances are blocking nitrite-based films from CE-marked industrial packaging throughout the European Union. Formulators are redirecting procurement toward ECHA-registered amine-free alternatives certified for 24-month ferrous protection. German automotive OEMs are now requiring full substance disclosure through SCIP database registration for all incoming VCI packaging materials.
Specification consolidation around performance-based protection contracts is displacing traditional thickness-based procurement in machinery export channels. Tier-one automotive suppliers in Detroit and Stuttgart are unbundling film supply from crating services, selecting inhibitors based on NACE test results rather than micron ratings. This shift is most visible in North American heavy equipment exports where puncture resistance and vapor-phase efficacy are now specified independently.
VCI Films Market Segmentation
VCI film specification varies sharply by protection duration, substrate compatibility, and transit mode. Procurement patterns diverge between domestic manufacturing consumption and export-oriented multi-layer barrier requirements.
Product Type:
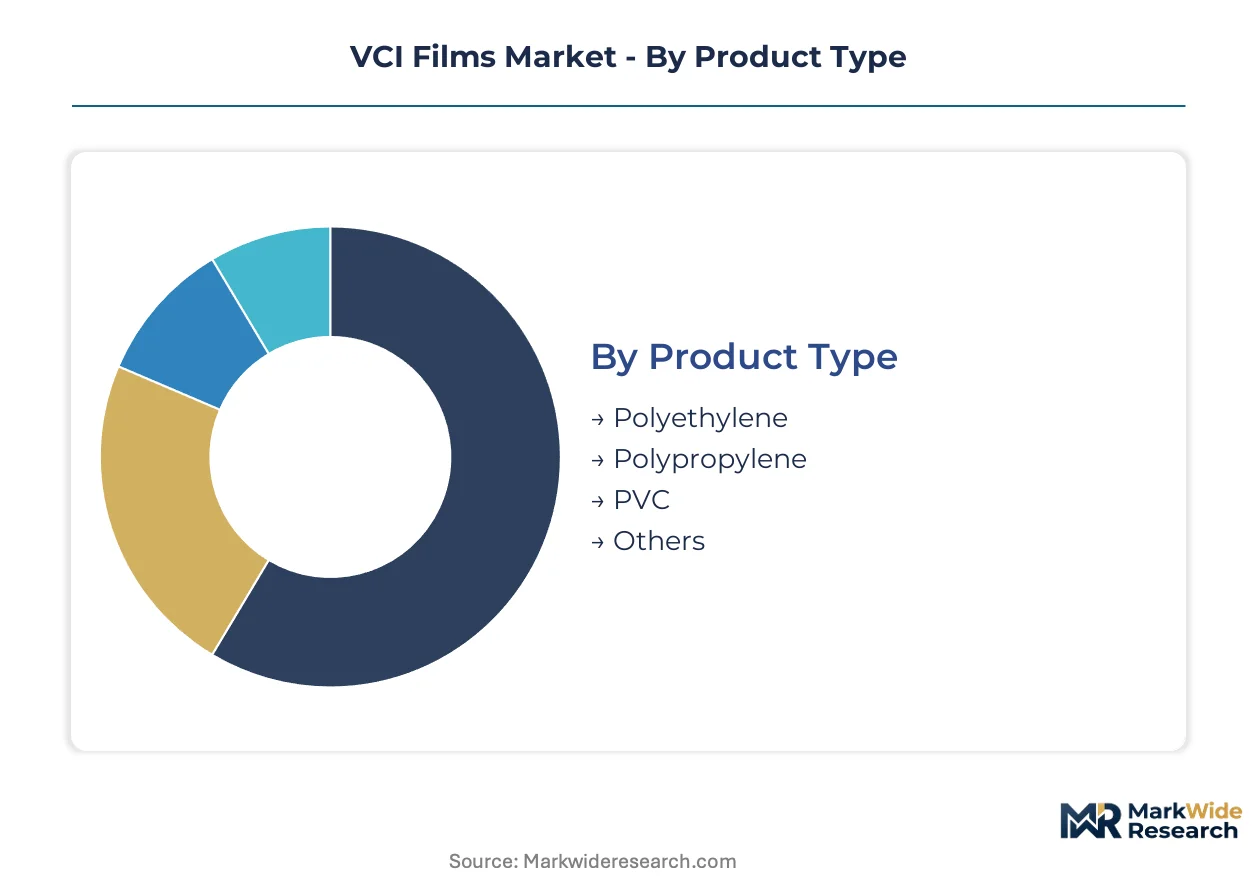
Polyethylene formulations anchor domestic manufacturing consumption across North America and Europe, while polypropylene grades concentrate in high-temperature automotive export corridors.
- Polyethylene:Cost-efficient extrusion compatibility and moisture resistance make this the default substrate for machinery and electronics packaging. Demand concentrates in China's Yangtze River Delta for precision equipment exports to Southeast Asian assembly plants, driven by humidity-activated release profile requirements.
- Polypropylene:Thermal stability above 120°C positions this substrate for electric vehicle powertrain component packaging. German and U.S. automotive OEMs specify PP-based films for underhood applications during extended supply chain transits, constrained by higher resin costs versus PE alternatives.
- PVC:Legacy specification in heavy equipment crating persists in port-adjacent North American clusters.
- Others:Biobased and multi-layer coextrusion substrates emerge in ECHA-registered formulations for REACH-compliant European markets.
Polyethylene holds the largest share; momentum sits with polypropylene as automotive thermal requirements intensify.
Application:
Cost tiering separates precision electronics protection from heavy machinery crating, with aerospace commanding certification premiums.
- Automotive:Engine component manufacturers in Germany and the United States specify multi-layer VCI films for ferrous castings. NACE TM0208 certification requirements for amine-free chemistries extend procurement cycles, compressing margin capture for non-integrated formulators.
- Electronics:Japanese automotive electronics exporters drive humidity-activated release specifications for ocean freight to Southeast Asia. Sub-50 micron precision thickness control concentrates demand among compounders with specialized blown-film operators.
- Machinery:Heavy equipment exporters in Detroit and Hamburg clusters specify puncture-resistant constructions above 150 microns.
- Aerospace:Component traceability requirements through SCIP database registration govern European procurement, favoring ECHA-registered suppliers.
Automotive applications dominate volume; electronics protection climbs fastest on precision export growth.
End User:
Volume scale separates integrated manufacturing consumption from fragmented retail distribution, with export channels commanding specification premiums.
- Manufacturing:Tier-one automotive suppliers unbundle film supply from crating services, selecting inhibitors based on NACE test results. EPA TSCA Section 6 enforcement compels U.S. manufacturers to certify amine-free formulations.
- Distribution:Regional stocking density near Detroit and Hamburg logistics hubs determines competitive positioning for mid-volume procurement.
- Retail:Small-lot machinery parts packaging in underdeveloped standardization markets like India creates first-mover opportunities for ECHA-registered suppliers.
- Export:Multi-layer barrier specifications with 24-month protection duration concentrate in China's precision machinery corridor.
Manufacturing captures the largest volume; export channels expand most quickly on specification consolidation.
Thickness:
Performance-based protection contracts are displacing micron-based procurement, though thickness bands still govern puncture resistance specifications.
- Below 50 Microns:Precision thickness control for Japanese electronics exports requires specialized blown-film operators concentrated in German and Japanese industrial clusters. Technician scarcity constrains capacity expansion.
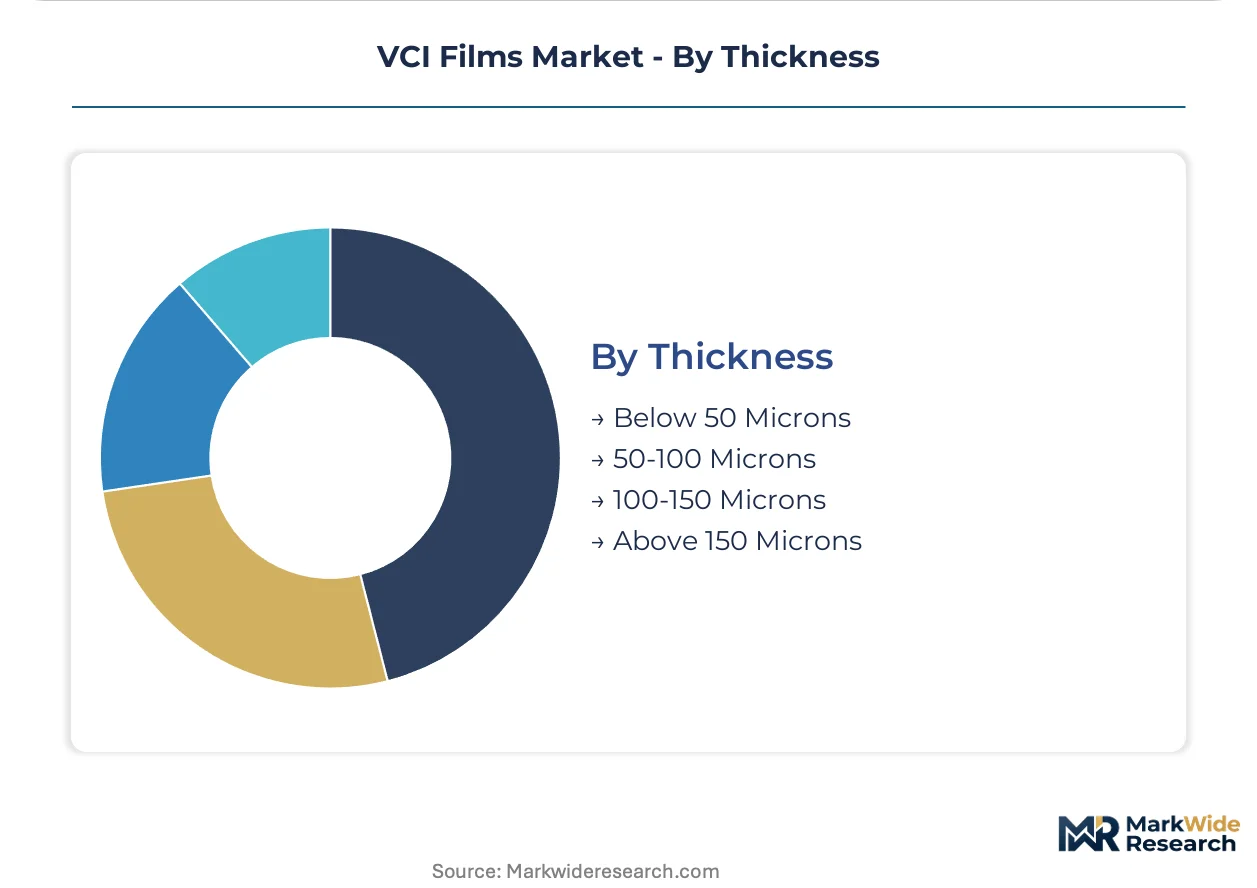
- 50-100 Microns:This band occupies the largest machinery and electronics packaging share, balancing cost efficiency with adequate vapor-phase barrier formation.
- 100-150 Microns:Mid-range protection for automotive components during extended transits.
- Above 150 Microns:Puncture-critical heavy equipment crating applications displace rigid VCI paperboard in port-adjacent North American and European clusters.
The 50-100 micron band holds the largest share; above-150 micron constructions gain share fastest on heavy equipment export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders command pricing premiums through ECHA-registered formulations, while Chinese converters in the Yangtze River Delta compete on volume scale for precision machinery exports. This asymmetry shapes procurement patterns across automotive and electronics corridors.
United States
Automotive OEMs in Detroit and engine component manufacturers in the Midwest specify multi-layer VCI films for extended supply chain transits. EPA TSCA Section 6 enforcement restricts hexavalent chromium and secondary amine nitrites, compelling domestic formulators to certify amine-free chemistries through NACE TM0208 protocols. Port-adjacent clusters near Houston and Los Angeles concentrate heavy equipment export crating above 150 microns.
Germany
REACH Annex XVII limitations on CMR-classified substances block legacy nitrite-based films from CE-marked industrial packaging. Stuttgart automotive suppliers unbundle film supply from crating services, selecting inhibitors based on NACE test results rather than micron ratings. Hamburg logistics hubs anchor regional stocking density for European export corridors.
China
SAMR is drafting GB standards intersecting corrosion inhibitor films with food-contact regulations, enabling multi-purpose specifications for processed machinery exports. The Yangtze River Delta manufacturing belt concentrates demand for humidity-activated release profiles protecting high-value electronics shipments to Southeast Asian assembly plants. Precision machinery exporters in Shanghai and Suzhou drive specification for 24-month protection duration.
Japan
Automotive electronics exporters specify sub-50 micron precision thickness control for ocean freight protection. METI standards govern vapor-phase inhibitor efficacy testing for ferrous and non-ferrous substrates. Nagoya and Osaka industrial clusters concentrate specialized blown-film operators capable of multi-layer coextrusion at tight tolerances.
India
Formal BIS standardization for corrosion inhibitor packaging remains underdeveloped, creating first-mover advantage for ECHA-registered suppliers establishing local compounding partnerships. Mumbai and Pune automotive component manufacturers represent emerging specification demand for engine protection films. Distribution channels in the Delhi-NCR corridor show fragmented procurement patterns favoring regional converters.
VCI Films Market Competitive Landscape
Concentration sits with integrated resin producers and specialty compounders who control captive VCI masterbatch synthesis. The vendor base spans three tiers: multinational material science firms with backward polymer integration, regional converters operating commoditized blown-film lines, and niche specialists in precision thickness control. Strategic moves center on M&A for formulation technology access and geographic expansion through regional stocking density near automotive clusters and port logistics hubs.
Within the integrated compounder tier, Cortec Corporation exemplifies margin capture through in-house VCI masterbatch production across polyethylene and polypropylene substrates. Aicello Corporation anchors the precision specialist position through sub-50 micron film capabilities for Japanese electronics exporters. Daubert Cromwell represents the regional density archetype with conversion facilities positioned near Detroit automotive clusters and Hamburg port logistics corridors.
| Leading Market Players |
|---|
| Cortec Corporation |
| Aicello Corporation |
| Armor Protective Packaging |
| Daubert Cromwell |
| Transcendia Inc. |
| Protective Packaging Corporation |
| BRANOpac |
| Packaging Aids |
| Tiberchem |
| Others |
Value Network & Pricing Analysis
Amine-free VCI chemistry substitution for legacy nitrite formulations is simultaneously relocating formulation expertise toward ECHA-registered European compounders and compressing margin capture for non-integrated regional converters dependent on imported masterbatches. This dual restructuring concentrates pricing power among captive synthesis operators while exposing commoditized blown-film lines to raw material volatility.
Pricing Analysis
Customization-premium spreads separate configured-to-order amine-free formulations from standard nitrite-based commodity films. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with NACE TM0208-validated products commanding substantial premiums. Pricing pressure stems from polyethylene resin cost volatility linked to naphtha-cracker economics. Tier-one automotive OEMs exhibit lowest price sensitivity, while fragmented retail distribution channels in underdeveloped standardization markets demonstrate acute cost consciousness.
Supply Chain Analysis
Just-in-time inventory strategies dominate precision electronics packaging for Japanese automotive exporters, whereas strategic stockpiling characterizes automotive OEM procurement for extended supply chain transits. Geographic supply concentration centers on Germany, China, and the United States for integrated formulation and conversion. Raw material dependencies draw from ethylene feedstocks, VCI active ingredient precursors, and multi-layer coextrusion equipment. Single-source vulnerability in specialized blown-film technician pools constrains capacity expansion. Distribution runs through regional stocking facilities near Detroit automotive clusters and Hamburg port logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VCI film demand tracks automotive production cycles, with precision machinery export volumes providing the cyclical recovery justification for sustained capacity investment.
For Market Incumbents: Shield market position through backward integration into captive VCI masterbatch synthesis and accelerated ECHA registration for amine-free chemistries. Nitrite-based formulation obsolescence under REACH Annex XVII threatens legacy product lines, while regional converter consolidation creates acquisition opportunities near Yangtze River Delta manufacturing belts. For New Entrants and Emerging Players: Lead with NACE TM0208-certified amine-free formulations targeting India's BIS standardization gap, where formal corrosion inhibitor packaging regulations remain underdeveloped. Precision electronics protection for ocean freight applications offers the most penetrable segment, with technical partnership strategies enabling rapid specification entry alongside Japanese automotive electronics exporters. For Investors and Strategic Acquirers: REACH Annex XVII enforcement reshapes the acquisition landscape toward ECHA-registered compounders with demonstrated 24-month ferrous protection certification. Long-term viability over the coming decade rests on formulation chemistry transition completion and multi-layer coextrusion technical capability. The signal to monitor is SAMR GB standard finalization intersecting corrosion inhibitor films with food-contact regulations, which would trigger multi-purpose specification demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCI Masterbatch Synthesis | Cortec Corporation's captive production model sustains margin capture across polyethylene and polypropylene substrates. |
| ECHA Registration Investment for Amine-Free Chemistries | German compounders command CE-marked industrial packaging premiums through REACH Annex XVII compliance. |
| Regional Stocking Density Expansion | Daubert Cromwell's Detroit and Hamburg facilities anchor procurement proximity to automotive OEM clusters. |
| Precision Thickness Control Capability Buildout | Aicello Corporation's sub-50 micron specialization captures Japanese electronics export specifications. |
| Long-Term Supply Agreement with Yangtze River Delta Exporters | Humidity-activated release profile partnerships secure multi-layer barrier film volume commitments. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at blown-film conversion facilities, procurement leads at German and U.S. automotive OEMs, distribution channel partners in European port logistics hubs, and technical R&D directors at specialty compounders provided operational perspective. Secondary sources include ECHA registration databases, EPA TSCA Section 6 enforcement records, SAMR GB standard draft documents, customs and trade data for polyethylene and polypropylene resin flows, and SEC 10-K filings from integrated material science firms. Bottom-up demand modeling from end-use applications triangulates against top-down supply-side capacity assessments.
Sensitivity analysis across feedstock cost scenarios and regulatory implementation timelines informs the projection framework. Segmentation dimensions include substrate type, application vertical, thickness band, and regional manufacturing cluster. CAGRs derive from regression analysis of historical volume patterns against automotive production indices and precision machinery export trajectories. Forecast inputs incorporate blown-film line commissioning schedules, REACH Annex XVII amendment implementation, and electric vehicle powertrain thermal specification evolution.
The analysis sits within stated boundaries; outcomes outside sustained automotive OEM procurement expansion and REACH-compliant chemistry transition would require recalibration. Forecasts reflect documented assumptions regarding resin cost stabilization and technician pool availability. Revision becomes warranted when ethylene feedstock volatility exceeds historical bands or when SAMR accelerates GB standard implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Card Films Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Twist Tie Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Thermoformed Trays Market