
 Middle East and Africa Single-Use Packaging Market | 2026-2036
Middle East and Africa Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Single-Use Packaging Market Insights
Petrochemical feedstock expansion along the Arabian Gulf is repositioning regional resin availability for converted packaging. Berry Global Inc leverages its blown film capacity across multiple Gulf states to supply food-grade polyethylene. Hotpack Packaging Industries LLC anchors the quick-service disposable segment through integrated thermoforming lines in the United Arab Emirates. Amcor Group GmbH competes on barrier laminate technology for extended shelf-life applications in ambient-climate distribution.
Single-use packaging encompasses containers, films, and wraps designed for one consumer interaction before disposal, typically manufactured through extrusion, thermoforming, or injection molding processes using polyethylene, polypropylene, or molded fiber substrates. These items function primarily to protect perishables from contamination, extend commercial viability in high-temperature logistics, and enable portion-controlled retail formats. Plastics continues to dominate value capture given resin integration advantages, though paper formats are gaining structural traction where food-contact heat resistance permits substitution. Bags and containers together absorb the majority of unit volume across the region's food service and retail grocery channels.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Emirates Authority for Standardization and Metrology (ESMA) enforce material migration limits and labeling protocols that filter non-compliant imports from Asian suppliers. South Africa's National Regulator for Compulsory Specifications (NRCS) implements mandatory standards for food-contact plastics that raise technical barriers for uncertified entrants. Stakeholders must monitor evolving extended producer responsibility frameworks across the region's largest economies to anticipate compliance cost shifts and material substitution timelines.
Market Dynamics
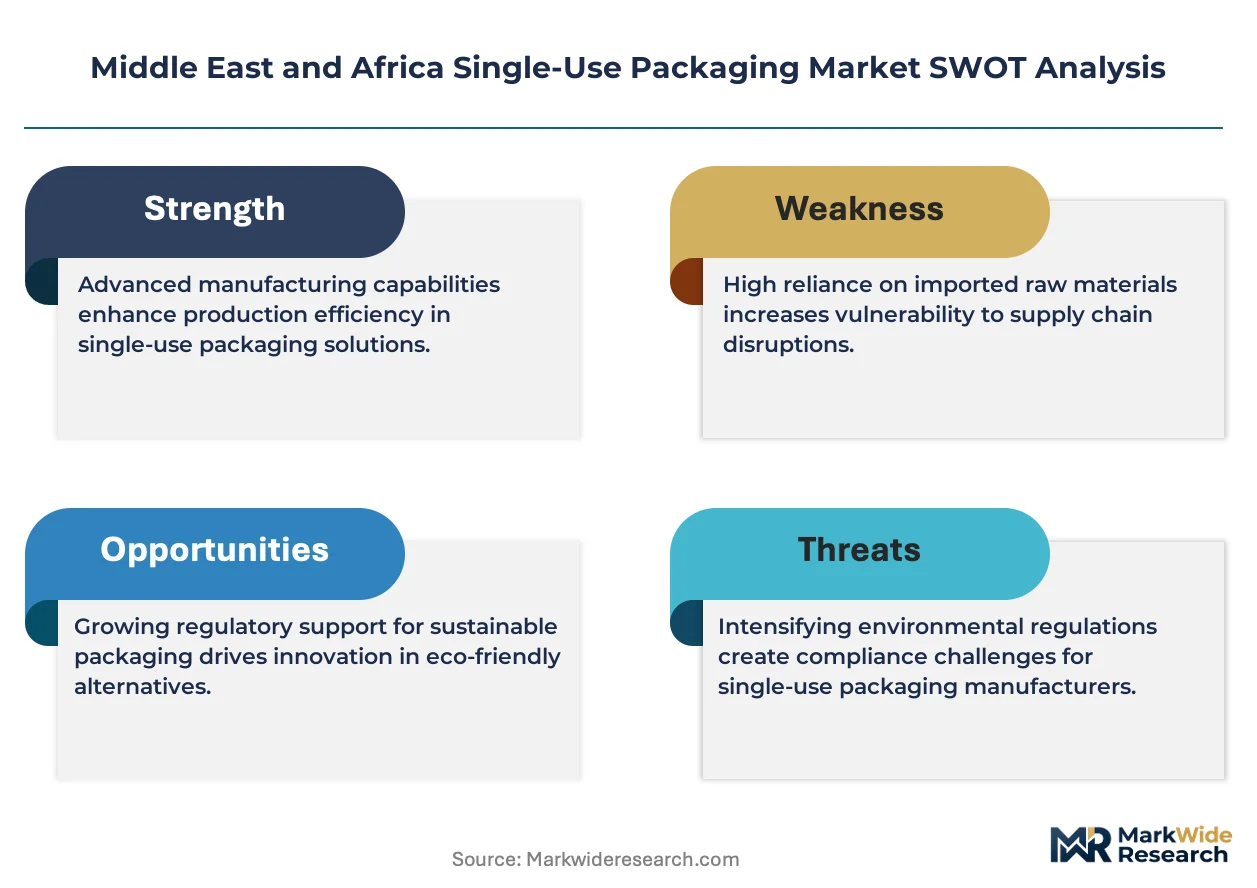
Extended producer responsibility frameworks across South Africa and the Gulf Cooperation Council are forcing converters to restructure material sourcing and end-of-life accountability, compressing margins for non-integrated suppliers while rewarding resin-backed operations.
Growth Catalysts
- Quick-service restaurant expansion:Gulf Cooperation Council chains are scaling disposable packaging procurement to match outlet growth in Riyadh, Dubai, and Jeddah.
- Petrochemical feedstock localization:Arabian Gulf resin capacity additions are reducing import dependency for polyethylene and polypropylene substrates.
- Nigeria's urban food retail corridor:Informal vendor networks in Lagos and Kano are driving volume for low-cost plastic bags and containers.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with crude oil benchmarks, squeezing converter margins.
- Import dependency for barrier laminates:High-performance oxygen barrier films remain concentrated among Asian and European suppliers.
- SASO migration limits:Saudi Standards, Metrology and Quality Organization testing protocols filter non-compliant Asian imports, extending certification timelines.
Strategic Opportunities
- Kenya's packaged food transition:Nairobi's supermarket expansion is creating first-mover advantage for certified food-contact suppliers.
- Biodegradable mandates in Tunisia and Morocco:North African policy incentives are opening substitution windows for polylactic acid and starch-based alternatives.
- E-commerce grocery logistics:Last-mile delivery platforms in Cairo and Johannesburg are demanding portion-controlled, tamper-evident formats.
Industry Challenges
- Food-contact certification timelines:Emirates Authority for Standardization and Metrology laboratory backlogs delay product launches by four to eight months.
- Thermoforming equipment scarcity:Skilled technicians for high-speed forming line maintenance are concentrated in the UAE and Saudi Arabia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Single-Use Packaging Market |
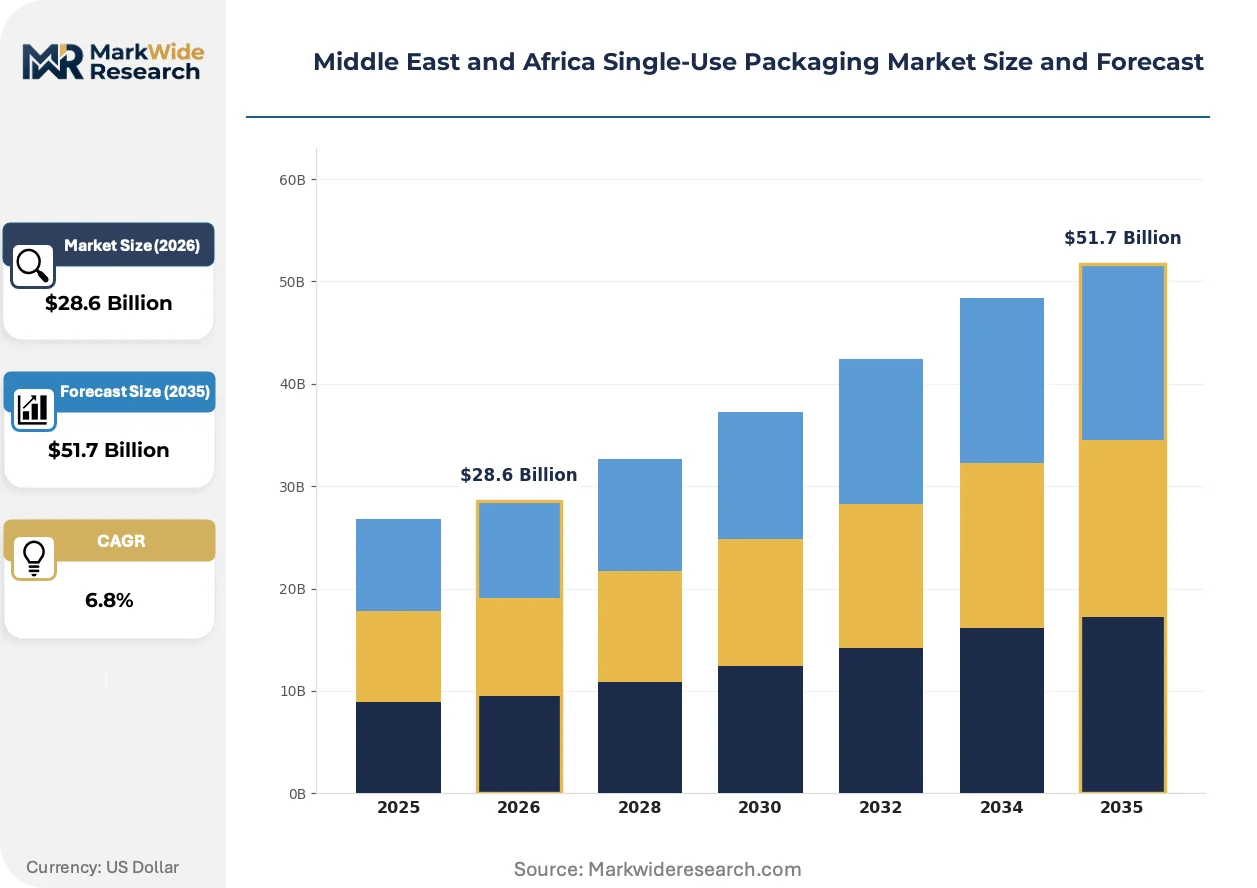
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Paper, Metals, Composites End Use: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Technology: Injection Molding, Blow Molding, Thermoforming, Flexographic Printing Packaging Format: Bags, Containers, Cups, Trays |
| Companies Covered | Berry Global Inc, Amcor Group GmbH, Huhtamaki Oyj, Hotpack Packaging Industries LLC, Gulf East Paper and Plastic Industries LLC, Falcon Pack, Al Bayader International, Cristal Plastic Industrial LLC, Detpak - Detmold Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Single-Use Packaging Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape substrate selection and conversion technology across the region's packaging value chain.
Barrier-coated paperboard is integrating mineral and bio-based sealant layers to achieve grease resistance and moisture protection previously requiring plastic laminates. Quick-service operators in Dubai and Abu Dhabi are piloting these formats for hot-food applications. The technology is integrating heat-seal performance with repulpability claims, enabling premium positioning against conventional polyethylene-coated board.
South Africa's National Regulator for Compulsory Specifications is tightening food-contact plastics standards, mandating heavy metal testing and traceability documentation. This is elevating technical barriers for uncertified Asian suppliers while creating compliance service opportunities for domestic laboratories. Medium-sized converters in Gauteng and Western Cape provinces are responding by consolidating testing partnerships with SANAS-accredited facilities.
Consolidated procurement by Gulf-based quick-service franchise operators is displacing fragmented vendor relationships. Master franchisees in Saudi Arabia and Kuwait are centralizing packaging specification authority at regional headquarters, compressing supplier counts from dozens to preferred panels of three to five converters. This concentration is most visible in Riyadh, where procurement teams now dictate substrate specifications across hundreds of outlets.
Middle East and Africa Single-Use Packaging Market Segmentation
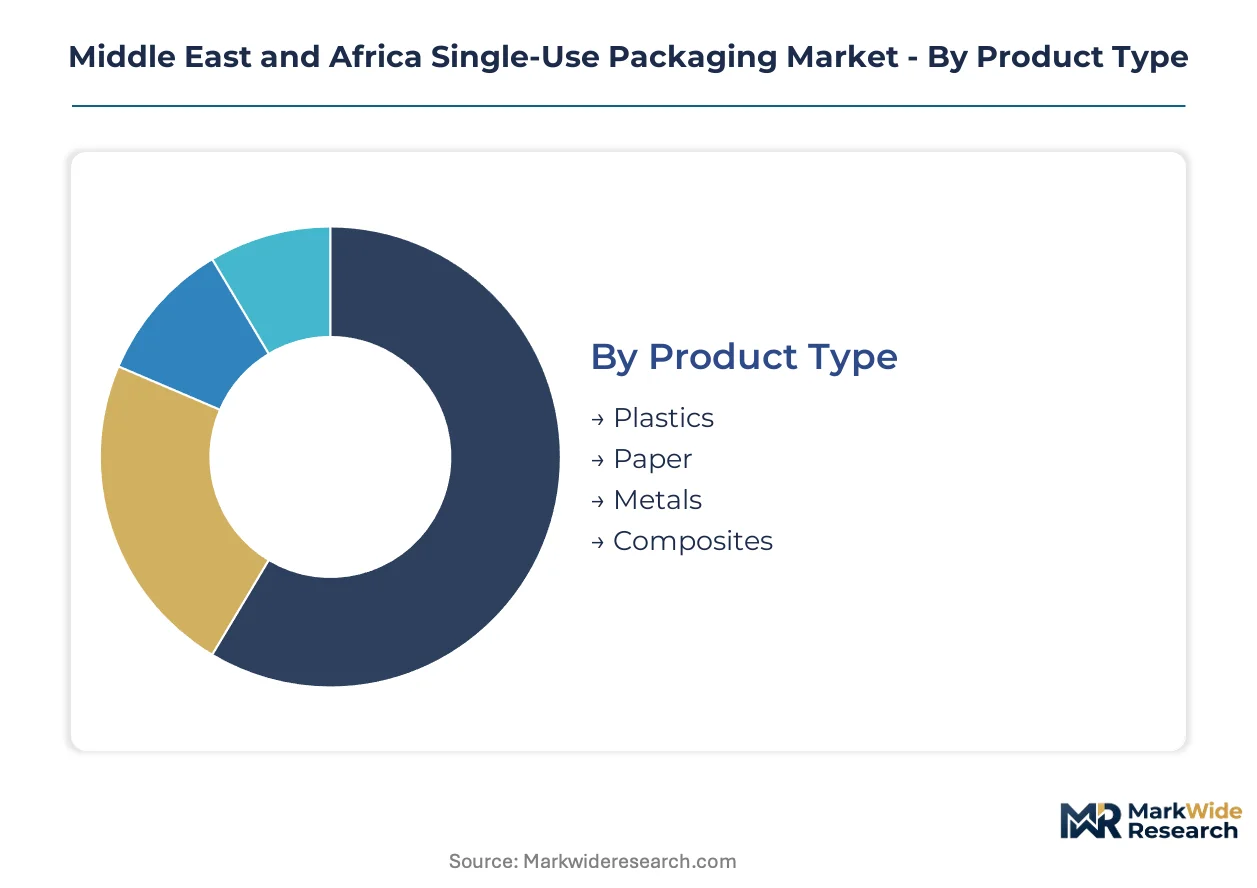
Material substrate selection and conversion technology determine compliance pathways and margin structures across Middle East and Africa single-use packaging. Segmentation reveals where petrochemical integration advantages concentrate versus where import dependency persists.
Product Type:
Customization spans from commodity resin formulations to certified food-contact laminates, with standardization dominant in bulk polyethylene and polypropylene supply.
- Plastics:Polyethylene and polypropylene substrates dominate through extrusion and thermoforming, with Arabian Gulf resin capacity reducing import costs for converters in Saudi Arabia and the UAE. Quick-service restaurant chains in Dubai and Riyadh specify these materials for heat resistance and seal integrity in ambient-climate distribution.
- Paper:Barrier-coated boards and molded fiber formats are gaining traction where grease resistance and moisture protection meet repulpability demands. Nairobi's supermarket expansion and Dubai's quick-service pilots are driving specification shifts toward mineral-sealant layers.
- Metals:Aluminum foils and laminates serve pharmaceutical blister packs and premium food segments requiring complete oxygen and light barriers.
- Composites:Multi-layer structures combining plastic, paper, and foil substrates address extended shelf-life requirements in ambient distribution across Nigeria and Egypt.
Leading the category by volume: Plastics. Expanding most quickly: Paper.
End Use:
Application requirements range from basic contamination barriers in informal retail to validated pharmaceutical serialization systems.
- Food & Beverage:Portion-controlled formats for quick-service chains and ambient-stable packaging for Nigeria's urban vendor networks absorb the majority of regional unit volume. SASO migration limits and ESMA labeling protocols filter supplier eligibility for this segment.
- Pharmaceuticals:Blister packs, vials, and compliance-prompting formats require barrier laminates and child-resistant closures. South Africa's NRCS mandates heavy metal testing and traceability documentation that elevate technical barriers for uncertified imports.
- Personal Care:Sachets, tubes, and pump dispensers for shampoo and lotion formats concentrate in Egypt's manufacturing zones and Morocco's export-oriented production.
- Household Products:Detergent pods, cleaning wipes, and spray bottles prioritize chemical resistance and child-safety features over food-contact certification complexity.
Food & Beverage generates the highest unit volume. Pharmaceuticals commands the steepest margin tier.
Technology:
Capital intensity and skilled technician availability create geographic concentration in conversion capabilities.
- Injection Molding:High-speed production of rigid containers, caps, and closures dominates in Saudi Arabia's industrial cities where petrochemical feedstock integration supports integrated operations.
- Blow Molding:Bottles and hollow forms for beverages and personal care rely on Arabian Gulf resin supply, with capacity concentrated in UAE and Saudi converter parks.
- Thermoforming:Thin-wall cups, trays, and lids for quick-service applications require skilled maintenance technicians concentrated in Dubai and Riyadh, creating equipment scarcity constraints elsewhere.
- Flexographic Printing:High-volume label and flexible film decoration serves food and beverage branding requirements across the region's retail grocery expansion.
Thermoforming and injection molding anchor production capacity. Flexographic printing is gaining share fastest with flexible packaging growth.
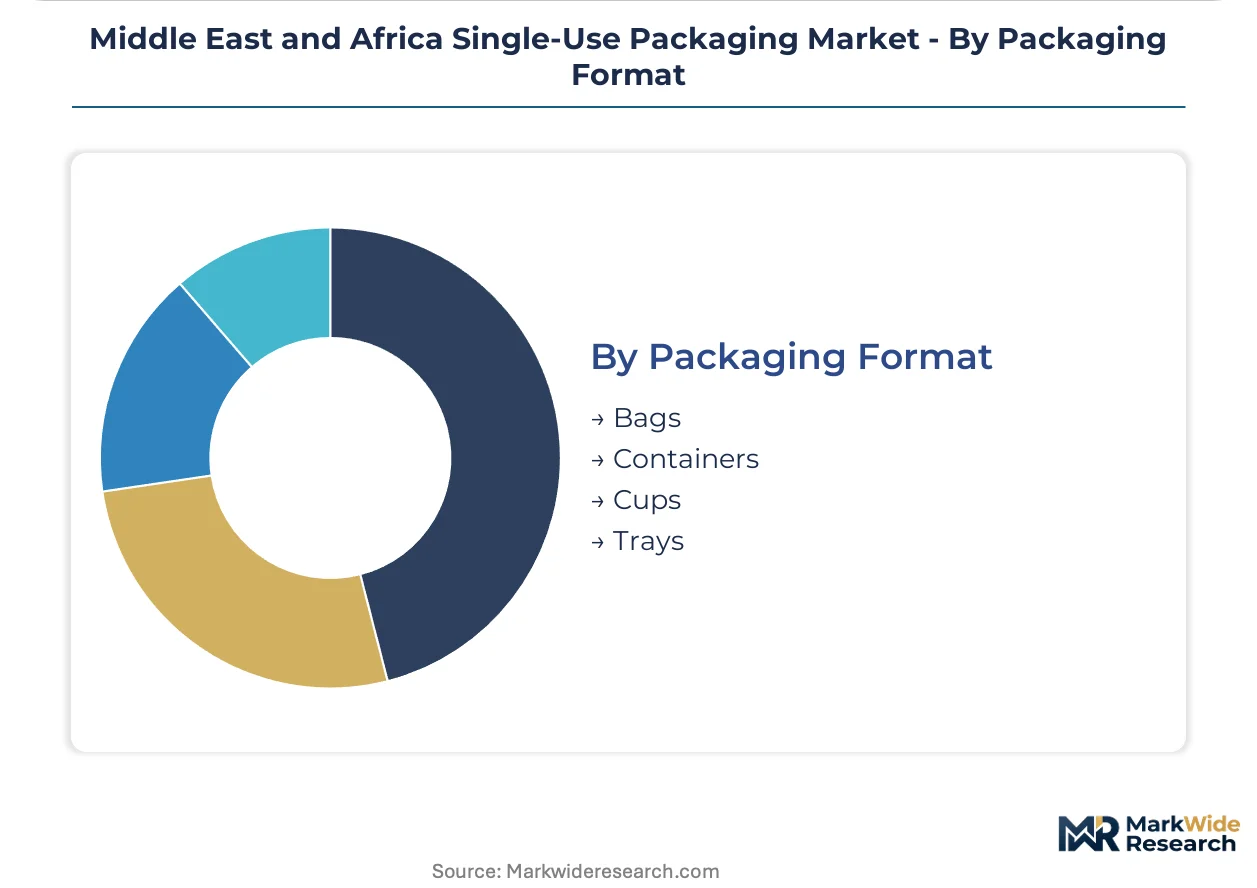
Packaging Format:
Format selection tracks distribution channel requirements from informal vendor portability to e-commerce tamper evidence.
- Bags:Low-density polyethylene carrier bags and pouches dominate Nigeria's Lagos and Kano vendor corridors, with South Africa's extended producer responsibility regulations reshaping material compliance obligations.
- Containers:Rigid tubs, jars, and bottles serve dairy, spreads, and pharmaceutical solids across Kenya's packaged food transition and Gulf retail modernization.
- Cups:Single-serve beverage and foodservice formats concentrate in quick-service procurement panels centralized by Saudi and Kuwaiti master franchisees.
- Trays:Modified atmosphere and vacuum-skin formats for fresh protein and produce are expanding with supermarket cold chain development in Cairo and Johannesburg.
Bags and containers together absorb majority unit volume. Trays show the steepest expansion trajectory with fresh protein retail modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arabian Gulf petrochemical clusters anchor resin supply for converted packaging across the Middle East and Africa, with Saudi Arabia and the UAE hosting integrated polyethylene and polypropylene capacity that feeds downstream thermoforming and extrusion operations.
Saudi Arabia
Quick-service restaurant chains in Riyadh and Jeddah are scaling disposable packaging procurement to match outlet expansion. SASO migration limits and food-contact certification protocols filter non-compliant Asian imports, extending supplier qualification timelines. The Eastern Province industrial corridor hosts integrated resin-to-converter operations that capture margin through captive feedstock supply.
United Arab Emirates
Dubai's master franchise operators are consolidating procurement panels from dozens of vendors to preferred groups of three to five converters. ESMA labeling protocols and laboratory backlogs delay product launches by four to eight months for uncertified entrants. Jebel Ali industrial zones concentrate thermoforming capacity for quick-service cup, tray, and lid production.
South Africa
Nairobi's supermarket expansion is creating first-mover advantage for certified food-contact suppliers serving packaged food transition. The National Regulator for Compulsory Specifications mandates heavy metal testing and traceability documentation that elevates technical barriers for uncertified imports. Gauteng and Western Cape provinces are consolidating testing partnerships with SANAS-accredited facilities to accelerate compliance.
Nigeria
Informal vendor networks in Lagos and Kano are driving volume for low-cost polyethylene bags and containers. Extended producer responsibility frameworks are reshaping material compliance obligations for formal retail channels. The urban food retail corridor is absorbing imported flexible films and rigid containers for ambient-stable distribution.
Egypt
E-commerce grocery logistics platforms in Cairo are demanding portion-controlled, tamper-evident formats for last-mile delivery. Personal care sachet and tube manufacturing concentrates in export-oriented production zones serving regional markets. Cold chain development for fresh protein retail is expanding modified atmosphere tray specifications.
Middle East and Africa Single-Use Packaging Market Competitive Landscape
Global majors compete with regional champions across material integration and certification capabilities, creating a tiered structure where resin-backed operations command margin advantages over import-dependent converters. The vendor base separates into petrochemical-integrated multinationals, Gulf-based thermoforming specialists, and compliance-focused regional laboratories. Three archetypes dominate: upstream-integrated resin converters, quick-service procurement panelists, and certification service providers. Competitive moves concentrate on backward integration into feedstock supply and consolidation of testing partnerships with national accreditation bodies.
Within the integrated multinational tier, Berry Global Inc and Amcor Group GmbH exemplify scale-driven positioning through blown film and barrier laminate capabilities. Hotpack Packaging Industries LLC anchors the quick-service disposable segment as a UAE-based specialist. Gulf East Paper and Plastic Industries LLC represents regional champion archetype with proximity to Arabian Gulf resin supply. These three occupy distinct competitive spaces: global technology leadership, quick-service operational integration, and regional feedstock access respectively.
| Leading Market Players |
|---|
| Berry Global Inc |
| Amcor Group GmbH |
| Huhtamaki Oyj |
| Hotpack Packaging Industries LLC |
| Gulf East Paper and Plastic Industries LLC |
| Falcon Pack |
| Al Bayader International |
| Cristal Plastic Industrial LLC |
| Detpak - Detmold Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed petrochemical producers in Saudi Arabia and the UAE anchor resin supply for regional converters, translating captive feedstock access into pricing discipline that import-dependent competitors cannot match. This ownership pattern compresses margins for non-integrated suppliers while rewarding Gulf-based operations with cost structures insulated from polyethylene and polypropylene spot volatility.
Pricing Analysis
Warranty and certification bundling separates compliant Gulf converters from uncertified Asian imports competing purely on unit cost. Three-tier pricing structure across certified food-contact, industrial-grade, and commodity resin tiers reflects ESMA and SASO compliance investment. Price differentiation hinges on migration testing documentation and volume scale, with master franchisee procurement panels squeezing mid-tier suppliers. Informal vendor networks in Nigeria remain most price-sensitive, while pharmaceutical blister pack buyers absorb premium barrier laminate pricing.
Supply Chain Analysis
Direct-to-converter channels from Arabian Gulf resin parks feed thermoforming and extrusion operations across Saudi Arabia, the UAE, and Egypt. Raw material flows draw from polyethylene and polypropylene feedstock clusters, with barrier laminates and mineral-coated paperboard resting on European and Asian import streams. Single-source vulnerability concentrates in high-performance oxygen barrier films. Distribution runs through master franchisee procurement panels and informal vendor networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SASO and ESMA certification timelines erect barrier-to-entry moats favoring incumbent laboratories and resin-integrated converters over speculative entrants.
For Market Incumbents: Deepen backward integration into captive resin supply at Jubail and Yanbu industrial corridors to defend against Asian import price pressure. Consolidate SANAS-accredited testing partnerships in Gauteng to accelerate NRCS compliance turnaround. Certification backlog arbitrage represents the priority defensive lever against emerging regional laboratories. For New Entrants and Emerging Players: Nairobi's supermarket procurement teams present an underserved buyer archetype seeking first-mover food-contact suppliers for Kenya's packaged food transition. Polylactic acid substitution windows in Tunisia and Morocco offer white-space positioning ahead of biodegradable mandate enforcement. Go-to-market execution should anchor on rapid ESMA pre-certification investment before Dubai procurement panel consolidation hardens. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap thermoforming specialists with stranded equipment in Egypt and South Africa facing extended producer responsibility compliance cost spikes. Long-term viability centers on acquisition targets with existing master franchisee relationships and laboratory accreditation pathways. Monitor ESMA laboratory backlog duration as inflection signal for certification service provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene access at Jubail industrial city insulates converters from import cost volatility. |
| SANAS Laboratory Partnership Consolidation | Accelerated NRCS certification turnaround captures South African food-contact substitution demand. |
| Biodegradable Substrate Capacity Addition | Polylactic acid lines in Tunisia address Moroccan and Tunisian mandate-driven procurement shifts. |
| Master Franchisee Procurement Panel Positioning | Preferred supplier status with Riyadh and Dubai quick-service operators locks multi-year volume commitments. |
| Thermoforming Equipment Maintenance Network | Skilled technician pools in Dubai and Riyadh constrain competitor expansion into quick-service cup and tray segments. |
Research Methodology
Multi-period observation of ESMA certification timelines, SASO migration test backlogs, and master franchisee procurement consolidation anchored the trend analysis, supplemented by interviews with thermoforming plant managers, quick-service supply chain directors, SANAS-accredited laboratory technical leads, and petrochemical procurement officers at downstream converters. Secondary validation drew from customs trade records, SEC filings of listed packaging multinationals, Gulf petrochemical capacity expansion disclosures, and National Regulator for Compulsory Specifications enforcement bulletins. Bottom-up unit volume modeling across bags, containers, cups, and trays triangulated against top-down resin consumption forecasts.
Input-output matrices mapped polyethylene and polypropylene feedstock flows through injection molding, blow molding, thermoforming, and flexographic printing conversion stages across the projection horizon. Segmentation dimensions encompassed material substrate, end-use application, packaging format, and technology type with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of outlet expansion in Riyadh and Dubai, supermarket square footage growth in Nairobi and Johannesburg, and informal vendor network density in Lagos and Kano.
Revisions become necessary when ESMA or SASO protocol amendments extend certification timelines, when crude oil benchmarks shift polyethylene and polypropylene cost structures, or when extended producer responsibility frameworks accelerate material substitution timelines beyond base assumptions. Periodic stress-testing of base assumptions against laboratory backlog duration and master franchisee procurement panel consolidation velocity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Book Wraps Market
Packaging Materials
Standard Liner Market
Packaging Materials
Card Films Market
Packaging Materials
VCI Films Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Europe Single-Use Packaging Market