
 Cash Management Supplies Packaging Market | 2026-2036
Cash Management Supplies Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Management Supplies Packaging Market Outlook
North American specialty paper mills is decoupling from commodity-grade capacity, redirecting furnish toward security-grade substrates. Amcor leverages multi-layer extrusion expertise to produce tamper-evident films for banking envelopes. WestRock sustains a dominant position in corrugated cash boxes through integrated containerboard capacity. Berry Global differentiates via blown film lines optimized for opaque, tear-resistant cash bags.
Cash management supplies packaging encompasses engineered containment systems designed to secure currency, coins, and negotiable instruments during transit, storage, and processing, typically incorporating tamper-evident adhesives, tear-resistant substrates, and sequential numbering to maintain chain-of-custody integrity. Paper-based envelopes dominate retail deposit applications where fiber recyclability aligns with corporate sustainability mandates, while serialized technology segments are gaining traction in casino and government end uses where RFID-enabled pouches enable real-time tracking and automated reconciliation. Plastic composites retain share in high-frequency banking environments where moisture resistance and repeated handling durability outweigh material cost premiums.
The EPA regulates volatile organic compound emissions from adhesive lamination processes used in security envelope manufacturing, while FDA indirect food contact standards constrain coatings applied to packaging for coins handled in retail food service settings. OSHA workplace safety rules influence ergonomic specifications for large-denomination cash boxes used in vault operations. Stakeholders must weigh fiber substitution timelines against the performance thresholds that armored carriers and central banks enforce for burst strength and seal integrity.
Market Dynamics
Serialized packaging mandates from armored carriers are compressing supplier lead times while EU fiber-substitution rules force converters to revalidate seal-integrity performance against plastic baselines.
Growth Catalysts
- EU Green Deal fiber mandates:The EU Green Deal is accelerating converter investment in kraft-based tamper-evident pouches for retail cash deposits across France, Germany, and Italy.
- Casino RFID adoption:Gaming operators in Nevada and Macau are deploying RFID-enabled cash bags for automated vault reconciliation and real-time chain-of-custody tracking.
- Central bank serialization:Federal Reserve cash handling guidelines are requiring sequential numbering and barcoding for all transit packaging used in wholesale currency distribution.
Market Restraints
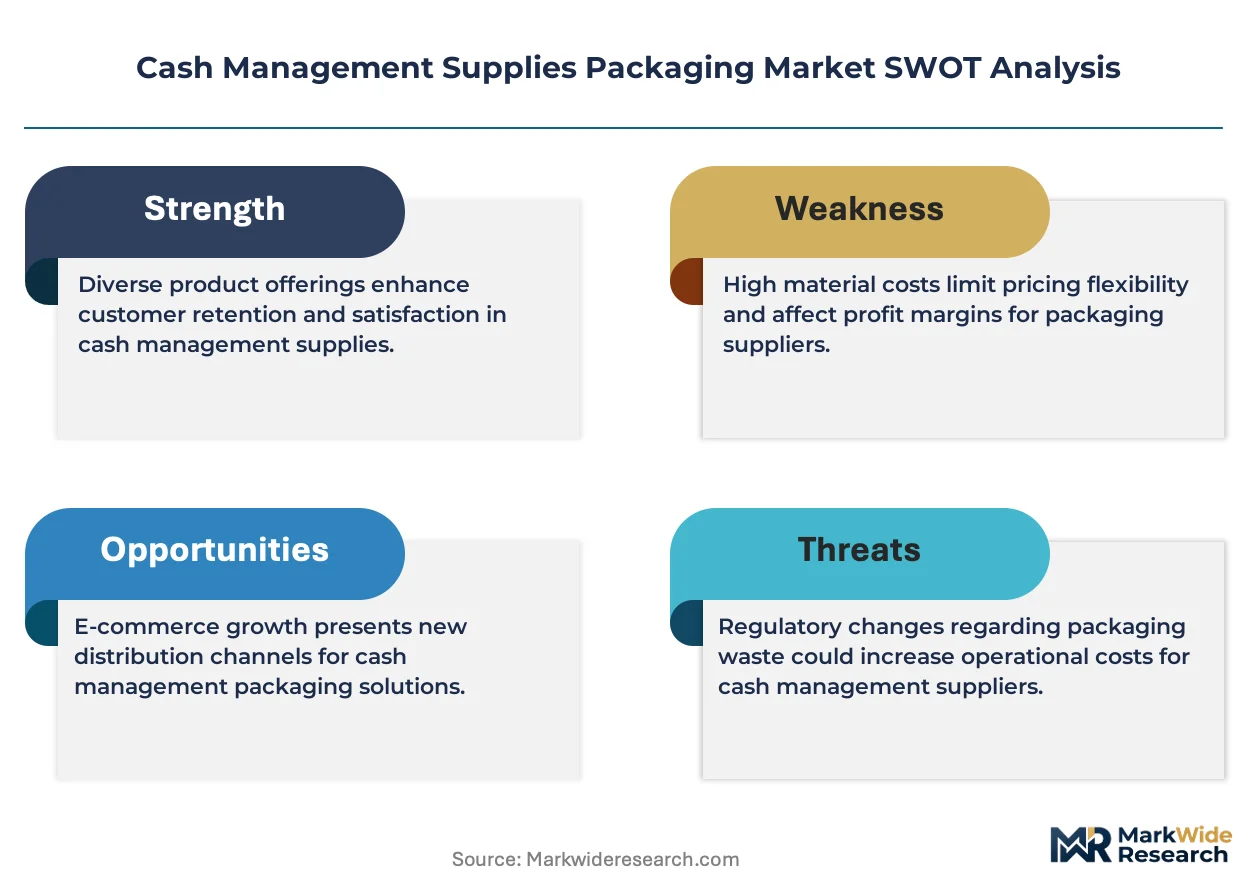
- Pulp furnish volatility:Specialty security-grade kraft pulp commands 15-20% premiums over commodity grades, squeezing envelope converters with fixed-price banking contracts.
- Adhesive supply concentration:Tamper-evident hot-melt formulations rely on a concentrated base of North American and German chemical suppliers, creating single-source vulnerability.
- Seal-integrity trade-offs:Fiber-based alternatives to multi-layer plastic films struggle to match burst-strength thresholds under humid conditions, limiting deployment in tropical banking corridors.
Strategic Opportunities
- India cash logistics modernization:RBI guidelines for ATM replenishment are creating demand for serialized, GPS-tracked cash pouches in Mumbai, Delhi, and Bangalore.
- Blockchain-integrated reconciliation:Distributed ledger technology paired with serialized packaging is enabling real-time settlement between retailers and armored carriers.
- Biodegradable security films:PLA and PHA formulations with tamper-evident properties are opening positioning for converters targeting B Corp-certified credit unions.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise for pressure-sensitive tamper-evident adhesives is concentrated among retiring specialists at legacy security printers.
- Validation timeline compression:Central banks in the US and EU are shortening certification cycles for new substrate-seal combinations from 18 months to 9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Management Supplies Packaging Market |
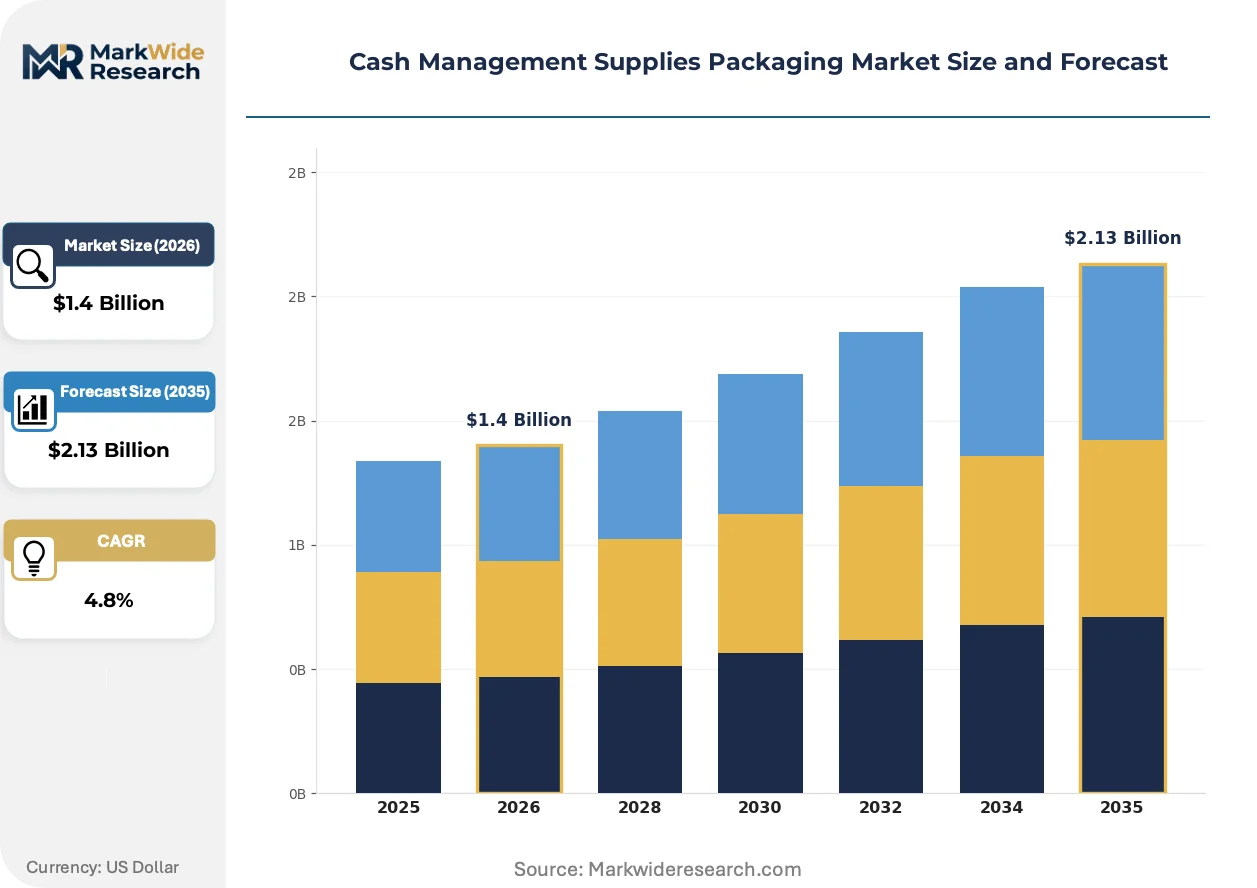
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Envelope, Bag, Box, Pouch Material: Paper, Plastic, Metal, Composite End User: Retail, Banking, Casinos, Government Technology: Serialized, RFID, Barcode, Secure Sealing |
| Companies Covered | Amcor, WestRock, International Paper, Berry Global, Smurfit Kappa, DS Smith, Mondi, Crown Holdings, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Management Supplies Packaging Market Strategic Shifts
Multi-layer extrusion and fiber-forming technologies are converging to produce hybrid substrates that satisfy both sustainability mandates and armored-carrier performance specifications.
RFID-inlay integration is unifying physical security with digital traceability in cash transit packaging. Casino operators and central bank vaults are adopting UHF-enabled pouches at replacement cycle rates of 24-36 months. This convergence is compressing the addressable market for standalone barcode-only products while expanding total solution value per unit.
REACH restrictions on phthalate plasticizers are forcing adhesive reformulation across European converter operations. The industrial consequence is a 12-18 month requalification window for all tamper-evident laminates sold into EU banking channels. German and French armored carriers are responding by consolidating supplier lists to those with in-house REACH-compliant chemistry capabilities.
Retailer procurement departments are unbundling packaging supply from armored-carrier service contracts. Large grocery and pharmacy chains in the United States are issuing direct RFPs for serialized deposit bags, bypassing traditional carrier-mediated sourcing. This disintermediation is most visible in California and Texas, where regional retailers operate captive cash vaults with independent reconciliation systems.
Cash Management Supplies Packaging Market Segmentation
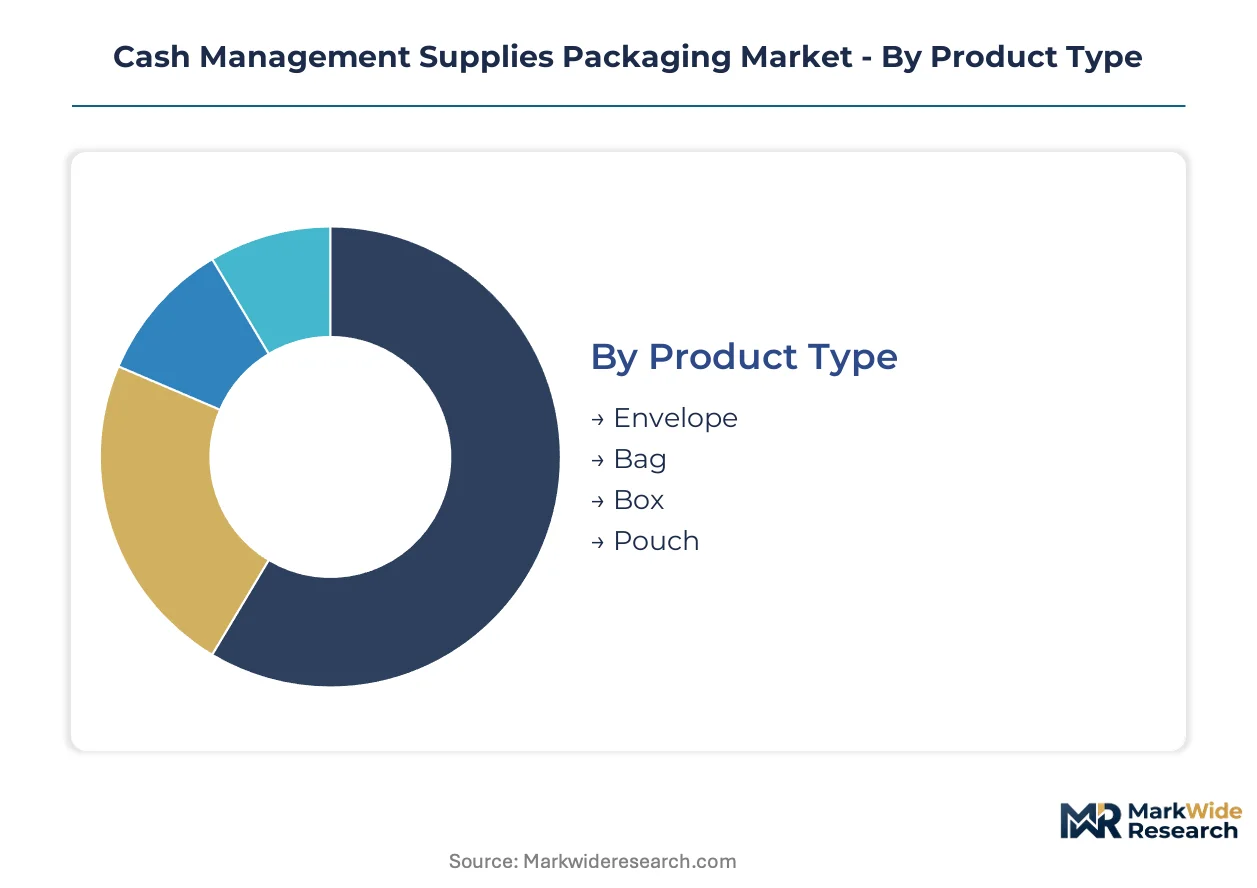
Cash management supplies packaging segments diverge sharply by security tier, handling frequency, and regulatory exposure. Procurement decisions hinge on whether the application demands single-use tamper evidence, reusable durability, or real-time digital traceability.
Product Type:
Armored carriers select containment formats based on cash volume per transit and reconciliation automation level.
- Envelope:Single-use kraft or Tyvek constructions with pressure-sensitive tamper-evident closures dominate retail deposit capture. Banking networks in the United States favor these for daily branch deposits where fiber recyclability satisfies ESG procurement scorecards.
- Bag:Multi-layer polyethylene or coextruded films with sequential numbering serve high-frequency ATM replenishment and casino vault operations. Demand concentrates in Nevada and Macau where gaming operators require opaque, tear-resistant containment for bulk currency.
- Box:Corrugated fiberboard with reinforced corners and locking lids protects large-denomination reserves during inter-vault transfers. Central bank wholesale distribution networks specify burst-strength thresholds that limit viable suppliers to integrated containerboard producers.
- Pouch:Flexible laminated structures with zip-seal or heat-seal closures accommodate coin and small-denomination currency. Transit agencies and municipal fare collection systems represent the primary end-use cluster for this format.
Envelope leads on scale; bag leads on momentum.
Material:
Substrate selection balances EU Green Deal fiber mandates against moisture resistance requirements in tropical banking corridors.
- Paper:Specialty security-grade kraft with tamper-evident adhesive patterns dominates retail and government applications. French and German armored carriers are accelerating conversion from plastic under EU single-use packaging directives.
- Plastic:Blown and cast films in polyethylene, polypropylene, and multi-layer coextrusions retain share in high-humidity environments. Burst-strength performance under humid conditions keeps plastic dominant in Southeast Asian and Gulf banking networks.
- Metal:Aluminum-laminated structures and steel-reinforced edges appear in high-value vault storage and bullion transit. Central bank reserves management represents the concentrated demand pool.
- Composite:Hybrid paper-plastic laminates and fiber-reinforced polymers bridge sustainability and performance requirements. Japanese and South Korean converters are advancing these substrates for next-generation serialized pouches.
Paper commands volume share; composite climbs the fastest.
End User:
Each vertical imposes distinct authentication, tracking, and disposal protocols that shape packaging specifications.
- Retail:Grocery and pharmacy chains with captive cash vaults issue direct RFPs for serialized deposit bags. California and Texas retailers are disintermediating armored-carrier-mediated sourcing.
- Banking:Commercial banks and credit unions drive standardization through Federal Reserve cash handling guidelines. Sequential numbering and barcoding are now mandatory for wholesale currency distribution packaging.
- Casinos:Gaming operators deploy RFID-enabled cash bags for automated vault reconciliation. Nevada and Macau properties are replacing barcode-only products at 24-36 month cycles.
- Government:Tax collection, postal services, and transit authorities require audit-trail documentation. RBI guidelines for ATM replenishment are expanding serialized pouch demand across Mumbai, Delhi, and Bangalore.
Banking anchors volume; casino expands most quickly.
Technology:
Security feature integration determines unit economics and supplier qualification timelines.
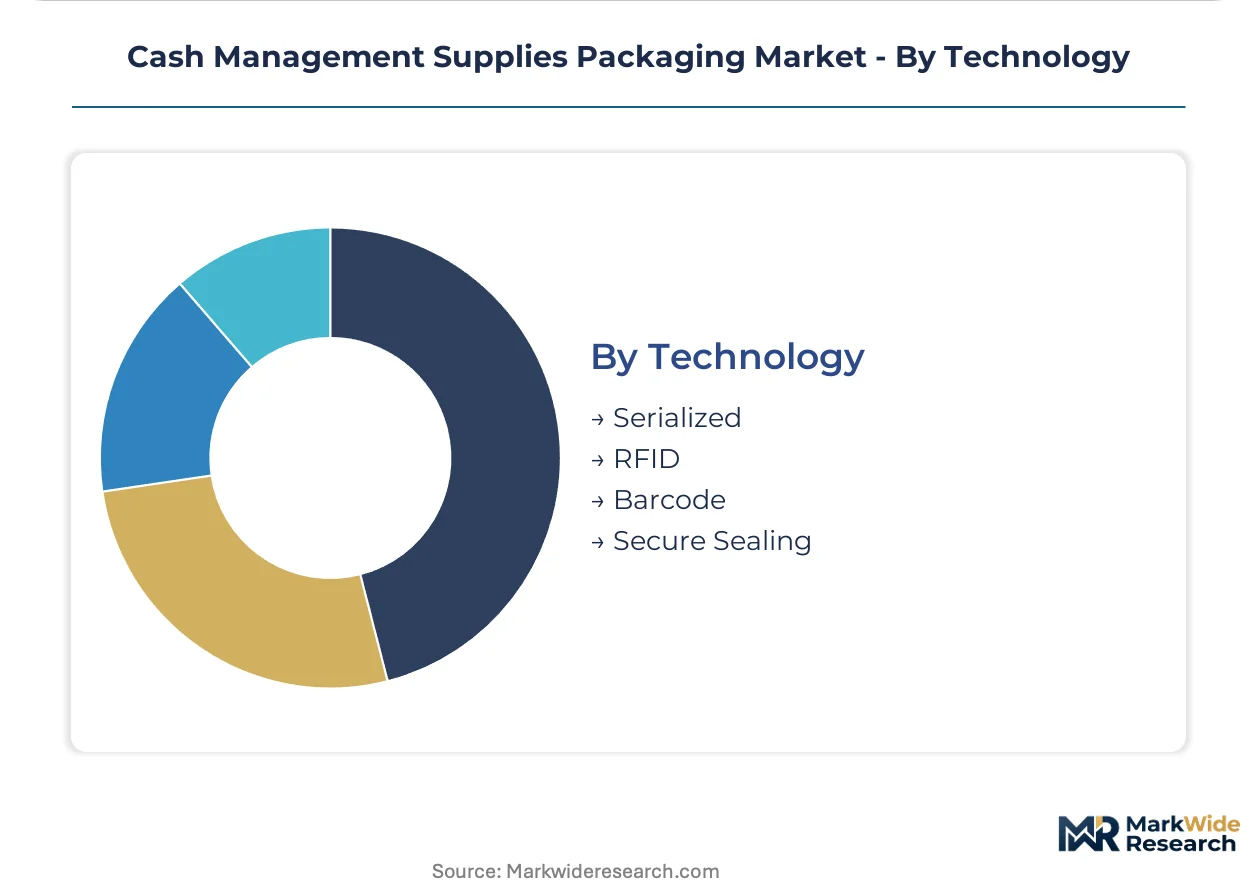
- Serialized:Sequential numbering, barcoding, and unique identifiers enable chain-of-custody documentation. Federal Reserve guidelines and EU armored carrier mandates are compressing supplier lead times for these products.
- RFID:UHF inlay integration unifies physical security with digital traceability. Casino operators and central bank vaults are adopting these pouches for real-time location and automated reconciliation.
- Barcode:Linear and 2D symbologies remain the baseline for cost-sensitive retail applications. Standalone barcode products are losing share to RFID-serialized hybrids.
- Secure Sealing:Tamper-evident adhesives, frangible films, and mechanical locks provide first-line intrusion detection. REACH restrictions on phthalate plasticizers are forcing 12-18 month requalification cycles for European converters.
Serialized dominates current procurement; RFID gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are arbitraging regulatory cost gaps, shifting security-grade substrate production toward jurisdictions with streamlined REACH-equivalent compliance timelines. German and French armored carriers consolidate supplier lists to firms with in-house chemistry capabilities, while Southeast Asian banking networks retain plastic-dominant formats where humidity performance thresholds override fiber mandates.
United States
Federal Reserve cash handling guidelines mandate sequential numbering and barcoding for wholesale currency distribution packaging. EPA volatile organic compound regulations constrain adhesive lamination processes for security envelope manufacturing. Armored carrier services in California and Texas are upgrading tamper-evident standards as retailers issue direct RFPs for serialized deposit bags.
Germany
French and German armored carriers accelerate conversion from plastic pouches to kraft-based alternatives under EU single-use packaging directives. REACH restrictions on phthalate plasticizers force 12-18 month requalification cycles for tamper-evident laminates. Industrial clusters along the Rhine corridor house converters with captive REACH-compliant chemistry capabilities.
India
RBI guidelines for ATM replenishment create demand for serialized, GPS-tracked cash pouches across Mumbai, Delhi, and Bangalore. The central bank's cash logistics modernization program mandates audit-trail documentation for retail deposit capture. Maharashtra-based converters are expanding capacity for hybrid paper-plastic laminates serving both domestic and export banking networks.
Japan
METI industrial standards for cash handling equipment influence packaging specifications for central bank vault operations. Japanese converters advance fiber-reinforced polymer substrates for next-generation serialized pouches. The Kanto region around Tokyo concentrates precision film lamination capacity serving casino and government end-use clusters.
Brazil
ANVISA indirect food contact standards constrain coatings for coin packaging used in retail food service settings. The country's national central bank maintains burst-strength thresholds for inter-vault transfer containers that limit viable suppliers to integrated containerboard producers. São Paulo-based armored carriers are piloting RFID-enabled cash bags for automated reconciliation.
Cash Management Supplies Packaging Market Competitive Environment
North American integrated producers anchor the scale tier; European specialty converters hold the compliance-advantaged niche. The vendor base separates into three tiers: multinational packaging conglomerates with security-grade substrate divisions, mid-cap regional specialists with captive adhesive chemistry, and niche RFID-technology integrators. Consolidation proceeds through backward integration into specialty pulp furnish and strategic partnerships with armored carriers for co-development of serialized formats.
Within the integrated conglomerate tier, Amcor, WestRock, and Berry Global exemplify divergent strategic positions. Amcor leverages multi-layer extrusion expertise across banking envelope applications. WestRock sustains dominant positioning in corrugated cash boxes through captive containerboard capacity. Berry Global occupies the blown-film specialization vector with opaque, tear-resistant formats optimized for casino and high-frequency banking environments. These three anchors demonstrate how substrate technology footprints determine competitive boundaries in security packaging procurement.
| Leading Market Players |
|---|
| Amcor |
| WestRock |
| International Paper |
| Berry Global |
| Smurfit Kappa |
| DS Smith |
| Mondi |
| Crown Holdings |
| Ball Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized adhesive chemist concentration in the Rhine corridor and New England mill towns connects labor-cost differentials to spreads between premium serialized pouches and commodity kraft envelopes. Armored carriers in Germany absorb 12-18 month REACH requalification premiums while Southeast Asian banking networks trade fiber mandates for humidity-tested plastic durability.
Pricing Analysis
Distributor margins on security-grade substrates compress as retailers in California and Texas issue direct RFPs for serialized deposit bags, bypassing traditional carrier-mediated sourcing. Three-tier pricing structure across premium RFID-enabled, standard serialized, and economy barcode-only levels separates casino operators from grocery chains from municipal transit agencies. Pricing pressure stems from specialty security-grade kraft pulp premiums over commodity grades squeezing converters with fixed-price banking contracts. Grocery and pharmacy chains with captive vaults exhibit highest price sensitivity; central bank wholesale distributors show lowest.
Supply Chain Analysis
Federal Reserve certification timelines and EU REACH-compliant chemistry capabilities gate supplier qualification, compressing viable sources to German, French, and North American converters with in-house formulation expertise. Raw material flows draw from specialty kraft pulp mills in the southeastern United States, tamper-evident adhesive suppliers in Germany, and RFID inlay producers in Japan. Single-source vulnerability in hot-melt adhesive formulations creates structural risk. Distribution runs through armored carrier service contracts and direct retailer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Federal Reserve serialization mandates and EU fiber-substitution rules concentrate procurement on premium-specification suppliers with validated chemistry capabilities.
For Market Incumbents: To counter disintermediation by retailers issuing direct RFPs, deepen captive supply of specialty security-grade kraft pulp and accelerate REACH-compliant adhesive formulation capacity in the Rhine corridor. Consolidate supplier lists with German and French armored carriers before 12-18 month requalification windows close.
For New Entrants and Emerging Players: Biodegradable security film technology with tamper-evident PLA and PHA formulations opens positioning for B Corp-certified credit unions underserved by legacy converters. Target Maharashtra-based expansion for RBI-mandated serialized GPS-tracked pouches in Mumbai, Delhi, and Bangalore. Lead with blockchain-integrated reconciliation pilots to bypass established armored carrier relationships.
For Investors and Strategic Acquirers: Integrated packaging conglomerates with security-grade substrate divisions are the most active acquirers in this space, seeking mid-cap regional specialists with captive adhesive chemistry. Long-term viability hinges on fiber-plastic hybrid substrate leadership as sustainability mandates tighten. Watch for Federal Reserve compression of certification cycles from 18 months to 9 months as inflection signal for qualification-timeline arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Kraft Pulp | North American mills decouple from commodity-grade capacity to serve security-grade substrate demand. |
| REACH-Compliant Adhesive Formulation Investment | German and French converters capture requalification-window premiums from armored carrier consolidation. |
| RFID Inlay Integration Partnership | Casino operators in Nevada and Macau replace barcode-only products at 24-36 month replacement cycles. |
| Blockchain-Integrated Reconciliation Pilot | Distributed ledger technology enables real-time settlement between retailers and armored carriers. |
| Biodegradable Security Film Development | PLA and PHA formulations open positioning for B Corp-certified credit union procurement channels. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with armored carrier procurement directors, security envelope converters, adhesive chemists, casino vault operations managers, and central bank cash handling officers with secondary validation against EPA volatile organic compound filings, Federal Reserve cash handling guidelines, EU REACH substance restrictions, RBI ATM replenishment circulars, and trade data on specialty kraft pulp imports. Bottom-up unit economics on serialized pouch production and top-down banking sector packaging spend estimates were triangulated.
Segment-weighting across product type, material substrate, end-user vertical, and technology tier informed value distribution modeling across the analysis window. Security feature integration levels, fiber substitution timelines against plastic performance baselines, and regional regulatory compliance cost differentials anchored CAGR derivation. Humidity-performance thresholds in tropical banking corridors and RFID adoption rates in gaming operations served as industry-specific forecast inputs.
The model holds under stable regulatory certification timelines and adhesive supply concentration; deviation in Federal Reserve mandate acceleration or REACH restriction expansion would shift supplier viability distributions. A model refresh is warranted upon material change in central bank serialization requirements or EU single-use packaging directive enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
PET Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Standard Liner Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Fanfold Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Face Stock Films Market