
 Packaging Machinery Market | 2026-2036
Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Machinery Market Analysis
China's manufacturing corridor is rewriting capacity geography for packaging machinery, with coastal provinces adding automated assembly halls for export-bound equipment. Krones AG leverages its beverage-system specialization to anchor premium filling lines across European bottling networks. Tetra Laval Group sustains R&D intensity in aseptic carton technology, competing for dairy and juice processor contracts. Syntegon Technology GmbH dominates pharmaceutical packaging segments with isolator-barrier systems for sterile drug delivery formats.
Packaging machinery encompasses electromechanical systems designed to form, fill, seal, label, and palletize containers with throughput rates spanning 50 to 1,200 units per minute depending on format complexity. These systems integrate servo-driven motion control, vision inspection, and human-machine interfaces to ensure seal integrity, weight accuracy, and traceability across food, pharmaceutical, and industrial supply chains. Filling machines occupy the largest installed base due to universal demand across liquid, powder, and viscous product categories, though robotic packaging cells represent the fastest-expanding technology segment as labor costs rise and batch flexibility requirements tighten. Pharmaceutical packaging commands premium margin pools where isolator technology and serialization compliance create barriers to commoditization.
FDA's Current Good Manufacturing Practice regulations and the EU Machinery Directive shape equipment validation protocols, inspection regimes, and cross-border market access requirements for suppliers serving regulated industries. China's SAMR enforces GB standards for food-contact materials and mechanical safety, compelling design adaptations for equipment destined for domestic versus export assembly lines. REACH and RoHS constraints in Europe restrict certain lubricants and electrical components, pushing manufacturers toward certified material substitutions. Stakeholders must monitor how divergent national certification timelines affect platform standardization strategies and service network economics.
Market Dynamics
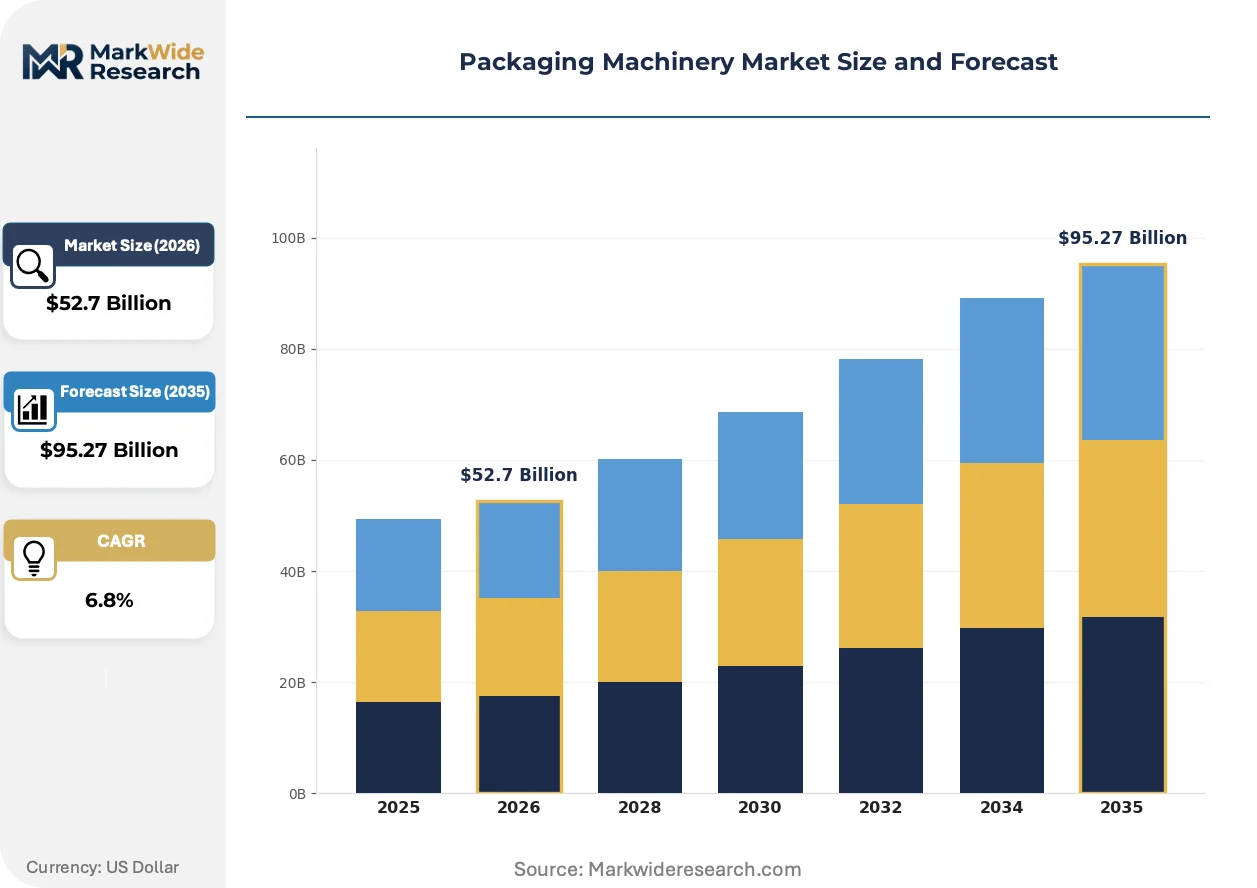
Serialization mandates under EU MDR and FDA DSCSA are compressing replacement cycles for pharmaceutical packaging lines, forcing capital deployment toward track-and-trace compliant systems before regulatory deadlines lock in equipment choices.
Growth Catalysts
- EU MDR serialization mandates:European pharmaceutical manufacturers must retrofit filling and labeling equipment with aggregation-capable vision systems, creating immediate replacement demand across contract packaging organizations and in-house operations.
- India's PLI scheme for food processing:Domestic equipment demand is accelerating as subsidy-linked capacity expansions in dairy and edible oil segments require aseptic filling and pouch-forming machinery.
- Servo-driven motion control:Electromechanical precision is displacing pneumatic actuation in high-speed bottling halls, enabling format changeovers under 15 minutes and reducing change-part inventory burdens.
Market Restraints
- Stainless steel alloy volatility:Grade 316L and 304 price swings compress margin visibility for fabricators of hygienic filling systems, particularly for mid-tier suppliers without forward-contracting leverage.
- German precision component concentration:Servo motors, linear drives, and hygienic bearings cluster in Baden-Württemberg and Bavaria, exposing lead-time risk from single-source dependencies.
- REACH substance restrictions:Lubricant reformulation requirements for food-contact zones extend validation timelines and force material qualification costs onto smaller equipment builders.
Strategic Opportunities
- Vietnam's dairy processing corridor:Foreign direct investment in UHT milk and yogurt production is outpacing local equipment supply, opening slots for European and Chinese machinery vendors with regional service presence.
- Cell and gene therapy packaging:Cryogenic filling and cold-chain secondary packaging for regenerative medicines represent white-space demand with limited incumbent specialization.
- Digital twin integration:Virtual commissioning and predictive maintenance convergence is lowering total cost of ownership for pharmaceutical buyers, creating differentiation leverage for vendors with software capabilities.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers capable of integrating servo systems, vision inspection, and PLC programming command premium compensation, constraining R&D throughput for mid-cap builders.
- FAT/SAT protocol complexity:Factory and site acceptance testing for isolator-barrier systems under FDA cGMP extends project timelines and requires dedicated validation documentation teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Machinery Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filling Machines, Labeling Machines, Wrapping Machines, Cartoning Machines Application: Food Packaging, Pharmaceutical Packaging, Electronics Packaging, Consumer Goods Packaging Technology: Automatic, Semi-Automatic, Manual, Robotic End User: Food & Beverage, Healthcare, Electronics, Chemicals |
| Companies Covered | Robert Bosch GmbH, Krones AG, Tetra Laval Group, Coesia S.p.A., Syntegon Technology GmbH, IMA Group S.p.A., Barry-Wehmiller Companies Inc., MULTIVAC Group, SACMI Imola SC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Machinery Market Emerging Trajectories
Equipment intelligence and regulatory traceability requirements are converging to redefine competitive positioning, with machinery vendors now judged on software depth and compliance architecture rather than mechanical throughput alone.
Collaborative robotic palletizing and case-packing cells are rendering obsolete fixed-automation lines in contract packaging environments. Third-party logistics providers and co-manufacturers are adopting these systems at 15-20% annual clip in North America and Western Europe. The technology is rendering obsolete capital-intensive dedicated lines by enabling batch-size-one flexibility without mechanical changeover downtime.
REACH and RoHS substance restrictions are forcing lubricant and electrical component substitutions across equipment destined for European food and pharmaceutical plants. Manufacturers must qualify alternative bearing greases and cable sheathing materials, extending design cycles by 6-12 months. Dairy and infant nutrition processors face the tightest compliance windows, with some accelerating supplier audits to preempt certification gaps.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in beverage and dairy segments. Large bottlers are separating spare parts procurement from technical support, using third-party MRO distributors for consumables while retaining OEM expertise for critical overhauls. This pattern is most pronounced in Germany and the Netherlands, where consolidated bottling groups leverage purchasing scale to fragment vendor revenue streams.
Packaging Machinery Market Segmentation
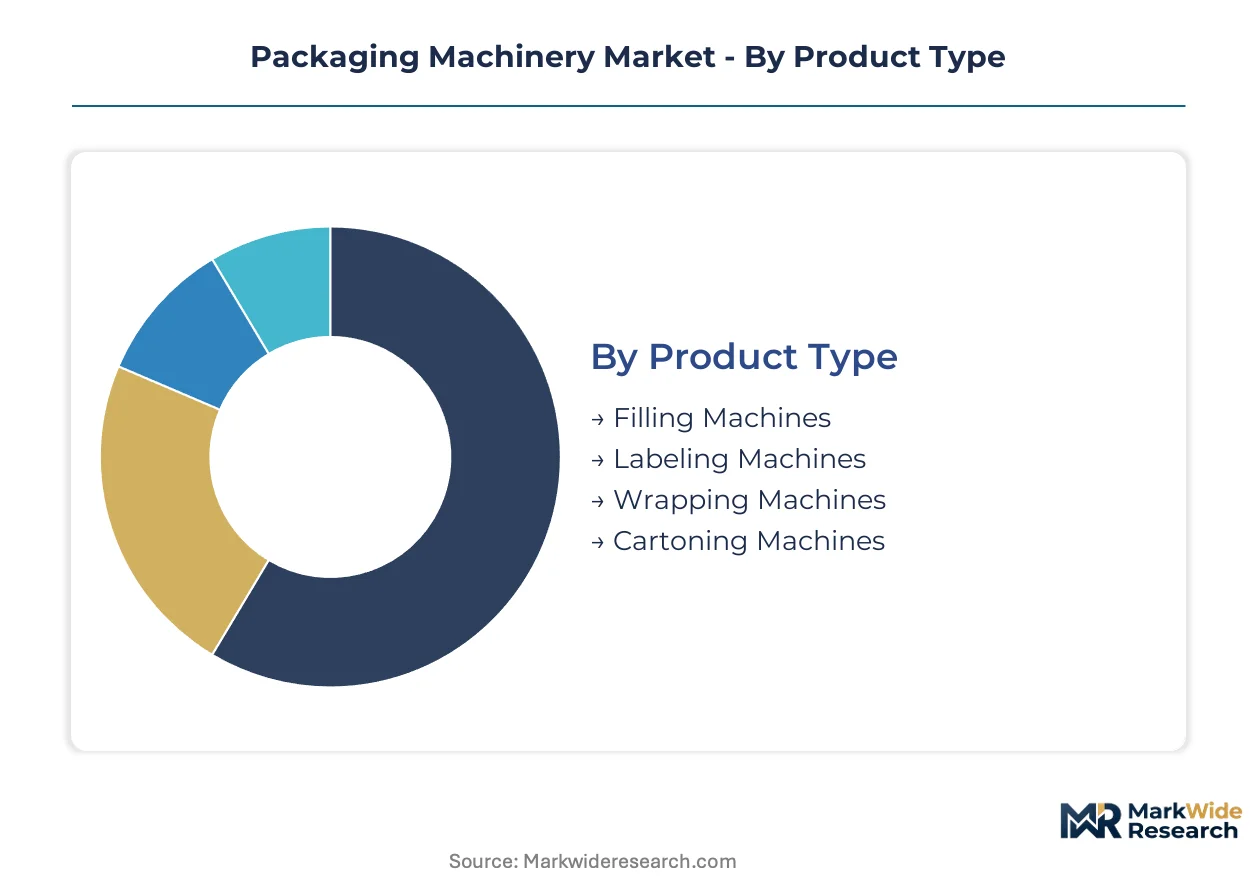
Equipment specification varies sharply across packaging machinery categories, with replacement cycles spanning from 3 years for high-wear filling systems to 12 years for integrated robotic cells. Segmentation discipline separates volume-driven commodity purchases from premium isolator-barrier installations where validation documentation commands price premiums.
Product Type:
Filling machines turn over fastest due to mechanical wear from product contact and seal degradation, while cartoning systems operate on slower replacement cycles tied to format stability.
- Filling Machines:Electromechanical systems meter liquid, powder, and viscous products into primary containers with servo-driven precision. Dairy processors in Germany and pharmaceutical aseptic lines in India concentrate replacement demand as EU MDR and FSSAI compliance deadlines compress procurement timelines.
- Labeling Machines:Pressure-sensitive and sleeve-application systems integrate vision inspection for serialization compliance. Pharmaceutical contract packers in the United States prioritize aggregation-capable units under FDA DSCSA mandates, displacing legacy equipment ahead of enforcement phases.
- Wrapping Machines:Stretch and shrink systems secure palletized loads for distribution.
- Cartoning Machines:Horizontal and vertical cartoners form secondary packaging for retail-ready formats.
Filling machines dominate installed base. Labeling machines are where expansion concentrates.
Application:
Cost tiers separate pharmaceutical installations with isolator-barrier premiums from food packaging lines where stainless steel standardization drives procurement.
- Food Packaging:Aseptic filling and modified-atmosphere systems preserve shelf stability for dairy, meat, and prepared meals. India's PLI scheme for food processing accelerates capacity additions in Uttar Pradesh and Maharashtra, requiring pouch-forming and UHT lines.
- Pharmaceutical Packaging:Isolator-barrier systems and serialization-ready labeling lines serve sterile drug delivery and track-and-trace mandates. EU MDR and FDA DSCSA compliance windows in Germany and the United States force capital deployment toward aggregation-capable equipment.
- Electronics Packaging:Anti-static and moisture-barrier systems protect semiconductors and components.
- Consumer Goods Packaging:Flexible formats and decorative finishing systems serve cosmetics and personal care.
Food packaging commands volume leadership. Pharmaceutical packaging captures margin concentration.
Technology:
Volume deployment favors automatic systems in high-throughput bottling halls, while batch-size flexibility elevates robotic adoption in contract packaging.
- Automatic:Continuous-motion systems achieve throughput rates exceeding 1,000 units per minute with integrated vision inspection and reject stations. Beverage bottlers in Germany and the Netherlands deploy these lines for standardized SKUs with minimal changeover requirements.
- Robotic:Collaborative palletizing and case-packing cells enable batch-size-one flexibility without mechanical changeover downtime. Third-party logistics providers in North America and Western Europe adopt these systems at accelerating rates to displace fixed-automation lines.
- Semi-Automatic:Operator-assisted systems bridge manual and fully automatic operations for mid-scale producers.
- Manual:Hand-fed equipment serves artisanal and pilot-scale production with minimal capital outlay.
Automatic systems anchor production scale. Robotic technology is climbing the fastest.
End User:
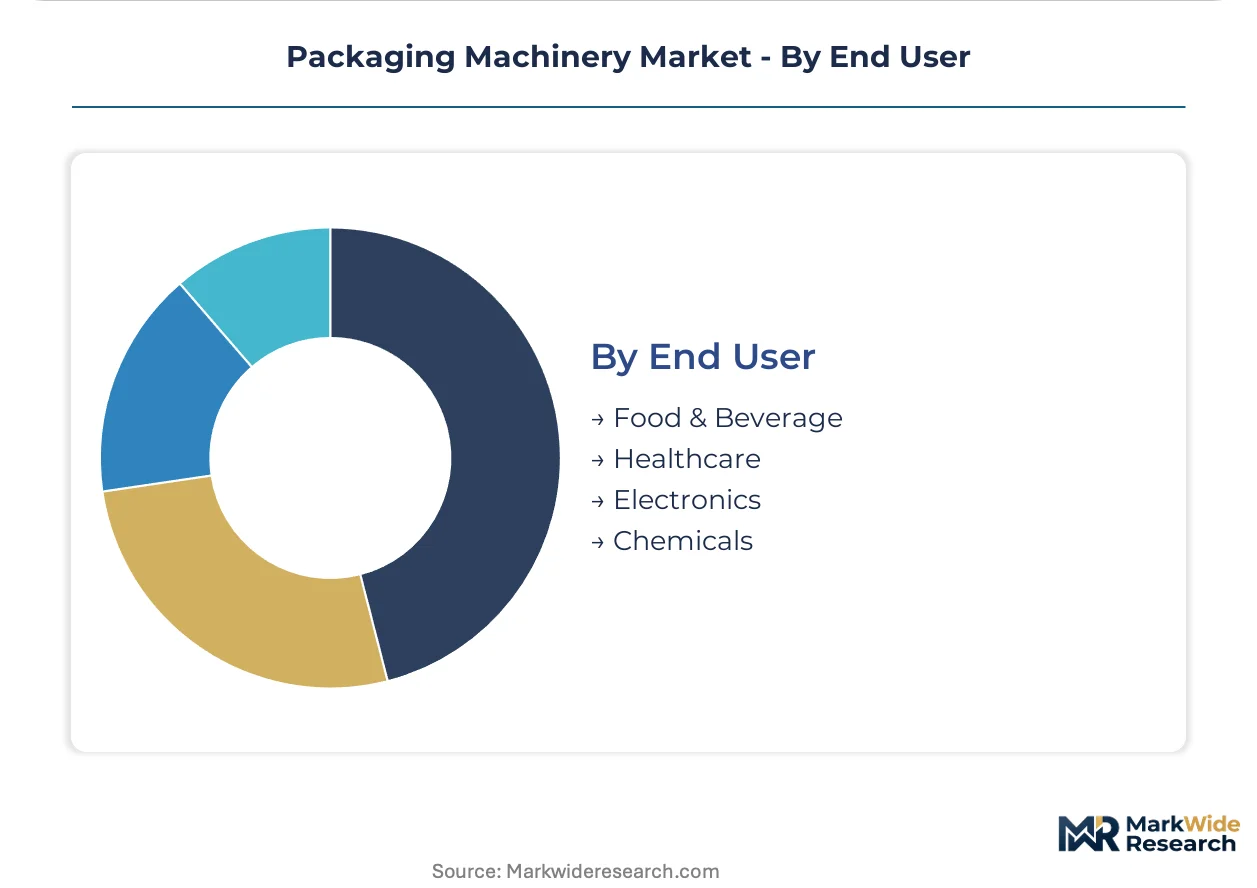
Customer type determines specification intensity, with healthcare and food sectors driving regulatory-grade equipment while chemicals tolerates standardized configurations.
- Food & Beverage:Dairy, brewery, and edible oil processors require aseptic filling, capping, and labeling systems with hygienic design certifications. China's coastal manufacturing corridors add automated assembly capacity for export-bound equipment serving this segment.
- Healthcare:Pharmaceutical and medical device manufacturers mandate isolator-barrier systems, serialization integration, and FDA cGMP validation documentation. Syntegon Technology GmbH anchors this segment with sterile drug delivery expertise.
- Electronics:Semiconductor and component manufacturers specify anti-static and cleanroom-compatible handling systems.
- Chemicals:Fertilizer, agrochemical, and industrial product packagers prioritize corrosion-resistant materials and explosion-proof electrical enclosures.
Food & beverage holds volume dominance. Healthcare concentrates premium-margin procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging machinery consumption patterns diverge sharply by geography: pharmaceutical serialization drives premium equipment procurement in Germany and the United States, while India's food processing subsidies accelerate mid-tier capacity additions, and China's coastal export corridors reshape equipment sourcing economics.
United States
FDA DSCSA enforcement phases compress replacement cycles for pharmaceutical contract packers. Serialization-capable labeling and aggregation systems dominate capital deployment ahead of compliance deadlines. New Jersey and North Carolina biopharma clusters anchor demand for isolator-barrier filling lines.
Germany
Bavaria and Baden-Württemberg concentrate precision component supply for servo-driven motion systems. EU MDR mandates force dairy and pharmaceutical processors toward aseptic filling retrofits. The country's machinery fabricators leverage proximity to automotive and chemical end-users for cross-sector technology transfer.
China
SAMR enforces GB standards for food-contact materials that diverge from export specifications. Yangtze River Delta and Pearl River Delta provinces add automated assembly halls for equipment bound for Southeast Asian dairy and beverage markets. Coastal manufacturing corridors capture cost advantages in stainless steel fabrication.
India
FSSAI compliance windows and PLI scheme subsidies accelerate dairy and edible oil capacity additions. Maharashtra and Gujarat pharmaceutical zones drive demand for track-and-trace labeling systems. Domestic equipment procurement is displacing import dependency for mid-speed filling applications.
Vietnam
Foreign direct investment in UHT milk and yogurt production outpaces local equipment supply capacity. The country's dairy processing corridor opens procurement slots for European and Chinese vendors with regional service networks. Ho Chi Minh City industrial zones concentrate foreign-owned packaging operations.
Packaging Machinery Market Vendor Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified machinery conglomerates. The vendor base stratifies across three tiers: integrated beverage-system suppliers with captive after-sales networks, pharmaceutical isolator specialists commanding validation premiums, and regional fabricators competing on stainless steel fabrication cost. M&A activity targets software-enabled predictive maintenance capabilities, while geographic expansion focuses on Southeast Asian dairy corridors.
Within the German precision-engineering tier, Krones AG and Syntegon Technology GmbH exemplify divergent specialization vectors—beverage-system integration versus pharmaceutical isolator-barrier technology. Tetra Laval Group occupies a position bridging aseptic carton R&D with global dairy processor relationships. These three entities represent the competitive archetypes shaping procurement negotiations: scale-driven system integration, compliance-premium specialization, and format-specific technology leadership.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Krones AG |
| Tetra Laval Group |
| Coesia S.p.A. |
| Syntegon Technology GmbH |
| IMA Group S.p.A. |
| Barry-Wehmiller Companies Inc. |
| MULTIVAC Group |
| SACMI Imola SC |
| Others |
Supply Flow & Price Mechanics
Stainless steel alloy volatility compresses margin visibility for fabricators of hygienic filling systems, forcing a pricing structure where premium isolator-barrier systems command validation-documentation premiums while mid-tier commodity equipment faces cost-driven consolidation. This input-cost uncertainty simultaneously concentrates procurement leverage among large bottlers with forward-contracting power and fragments revenue streams for smaller builders unable to hedge grade 316L and 304 exposure.
Pricing Analysis
German precision-engineered servo systems trade at substantial premiums over Chinese export equipment, with price differentiation resting on CE-marked hygienic certifications and integrated validation documentation. Pharmaceutical buyers in Bavaria and New Jersey tolerate premium-mid-economy pricing differentiation for isolator-barrier systems because FDA cGMP and EU MDR compliance windows compress substitution options. Cost compression in mid-speed beverage lines is intensifying because India's PLI-subsidized capacity additions expand local supply alternatives. Contract packaging organizations exhibit highest price sensitivity, while sterile drug delivery manufacturers prioritize compliance architecture over unit economics.
Supply Chain Analysis
Tariff exposure between China and European Union markets dominates supply chain risk calculations for stainless steel fabrication and servo motor procurement. Component manufacturing clusters in Baden-Württemberg, Bavaria, and Yangtze River Delta provinces anchor electromechanical precision supply, with raw material dependencies centering on nickel-alloy feedstock, rare-earth magnet materials, and certified food-contact lubricants. Single-source vulnerability in German linear drive production extends lead-time risk for pharmaceutical OEMs with fixed regulatory deadlines. Distribution runs through OEM captive service networks for premium installations and third-party MRO channels for consumables and spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing across standard filling equipment categories, while predictive maintenance software subscriptions and validation-documentation service contracts expand at multiples of base machinery growth. This service-attach opportunity redefines vendor economics toward recurring-revenue models.
For Market Incumbents: Insulate pharmaceutical isolator-barrier positions through captive validation-documentation teams and backward integration into precision servo component supply. Emerging Chinese equipment vendors with PLI-linked Indian market access threaten mid-tier beverage-system margins; defend through regional service density in Southeast Asian dairy corridors and software-enabled remote diagnostics capabilities that lock in switching costs. For New Entrants and Emerging Players: Pursue Vietnam's dairy processing corridor where foreign direct investment in UHT milk capacity outpaces local equipment supply, and cell-and-gene therapy cryogenic filling where incumbent specialization remains limited. Contract packaging's batch-size-one flexibility requirements render collaborative robotic palletizing cells the most penetrable technology segment. A software-first go-to-market angle—digital twin commissioning and predictive maintenance modules—sidesteps capital-intensive fabrication barriers. For Investors and Strategic Acquirers: EU MDR and FDA DSCSA enforcement phases reshape the acquisition landscape toward serialization-capable labeling and aggregation-system specialists with installed base migration potential. Long-term viability favors vendors bridging mechanical precision with software depth, not pure-play fabricators exposed to stainless steel cost volatility. Acquisition target archetype: mid-cap builders with isolator technology expertise and underdeveloped aftermarket service monetization. The signal to watch is regulatory deadline acceleration compressing replacement cycle timing beyond incumbent production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Virtual commissioning reduces pharmaceutical FAT/SAT timelines and lowers total cost of ownership for sterile drug delivery lines. |
| Backward Integration into Servo Components | In-house production of linear drives and hygienic bearings mitigates Baden-Württemberg supply concentration risk. |
| Regional Service Network Expansion | Ho Chi Minh City and Maharashtra presence captures Vietnam dairy and Indian pharmaceutical procurement slots. |
| Predictive Maintenance Platform Launch | Software subscriptions transform one-time equipment sales into recurring revenue from beverage bottlers and contract packagers. |
| Isolator-Barrier Technology Licensing | Validation-documentation expertise monetizes Syntegon and Krones competitive moats through technology transfer agreements. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers at dairy and pharmaceutical processors, aftermarket service heads at OEMs, procurement teams at contract packaging organizations, and regulatory affairs leads navigating FDA DSCSA and EU MDR compliance windows, then refined against secondary validation from SEC filings of listed machinery conglomerates, German mechanical engineering association production statistics, Indian PLI scheme disbursement records, and SAMR GB standard enforcement notices. Bottom-up equipment shipment tallies and top-down industrial capital expenditure aggregates were triangulated to anchor market sizing.
Demand-supply balance modeling across the projection horizon calibrated installed base replacement cycles against regulatory deadline compression and greenfield capacity additions in Vietnam and India. Segmentation dimensions spanned equipment type, application sector, automation technology tier, and end-user industry vertical, with regional regulatory clusters treated as distinct demand determinants. CAGRs were derived from curve-fitting historical capital expenditure patterns against announced capacity expansion pipelines, incorporating servo-drive adoption rates and serialization mandate enforcement phasing as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in stainless steel alloy pricing, central bank policy rates affecting capital expenditure timing, or trade policy shifts affecting China-EU equipment flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory deadline adherence and subsidy scheme continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Bubble Wrap Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Kraft Paper Machines Market