
 PET Strap Market | 2026-2036
PET Strap Market Size, Share, and Industry Trends Forecast 2026-2036
PET Strap Market Intelligence
Skilled polymer compounding expertise is redrawing competitive boundaries as virgin-grade PET resin formulations become harder to source at stable cost. Teufelberger leverages its Austrian fiber technology heritage to sustain premium positioning in high-tenacity strap grades. Cordstrap anchors its position through integrated extrusion and weaving operations across European and Asian plants. Samuel Strapping competes aggressively on North American logistics contracts with dedicated toll-manufacturing partnerships.
PET strap consists of oriented polyethylene terephthalate ribbon, typically extruded at widths from 9 mm to 32 mm and tensile strengths exceeding 450 MPa, designed to secure palletized loads during transit and storage. Flat strap dominates volume consumption across heavy-gauge industrial applications where break strength and elastic recovery matter most. Printed strap represents the fastest-growing product type as brand owners embed batch codes and handling instructions directly onto securing materials. Reinforced strap captures concentrated margin pools in specialized construction and agricultural bundling where UV stabilization and edge resistance justify price premiums over standard grades.
ISO 18616 and ASTM D3950 establish baseline tensile and elongation benchmarks that determine product qualification for cross-border freight, while EPA guidelines on recycled content thresholds shape domestic sourcing decisions for North American converters. ECHA's REACH restrictions on certain plasticizers and additives force reformulation cycles that favor suppliers with in-house polymer laboratories. Stakeholders must monitor how diverging regional certification requirements affect interchangeability of strap inventories across multinational distribution networks.
Market Dynamics
Steel-to-PET substitution in heavy-load logistics is compressing established material hierarchies as freight operators prioritize weight reduction and corrosion elimination across multimodal supply chains.
Growth Catalysts
- China's GB packaging recyclability standards:Tightening material specifications force converters toward mono-material PET designs that simplify post-consumer recovery streams.
- Textile export hub concentration:India's western industrial corridor in Gujarat and Maharashtra generates sustained demand for printed and reinforced strap grades serving garment palletization.
- Lightweighting imperatives:Asia-Pacific logistics operators systematically replace steel strapping to cut shipment weight and eliminate rust-related cargo damage.
Market Restraints
- Virgin-grade PET resin volatility:Polymer compounding expertise scarcity limits converter access to stable-cost high-tenacity formulations.
- REACH additive restrictions:ECHA's plasticizer and stabilizer limitations force costly reformulation cycles without guaranteed supply continuity.
- Polypropylene strap substitution:Lower-cost PP alternatives capture light-duty bundling applications where break strength requirements remain modest.
Strategic Opportunities
- Construction and agricultural bundling:UV-stabilized reinforced strap commands margin premiums in outdoor exposure applications underserved by standard grades.
- Direct-to-strap printing technology:Brand owners embed batch codes and handling instructions, eliminating secondary labeling steps.
- India's textile export corridor expansion:Underpenetrated secondary hubs in Tamil Nadu and Karnataka offer white-space demand for specialized strap configurations.
Industry Challenges
- ISO 18616 and ASTM D3950 qualification timelines:Cross-border freight certification delays inventory interchangeability across multinational distribution networks.
- Polymer laboratory capex requirements:In-house reformulation capabilities demand sustained R&D infrastructure investment beyond mid-tier converter reach.
- Skilled extrusion technician scarcity:Oriented PET ribbon production requires specialized expertise in draw ratio control and heat-setting optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Strap Market |
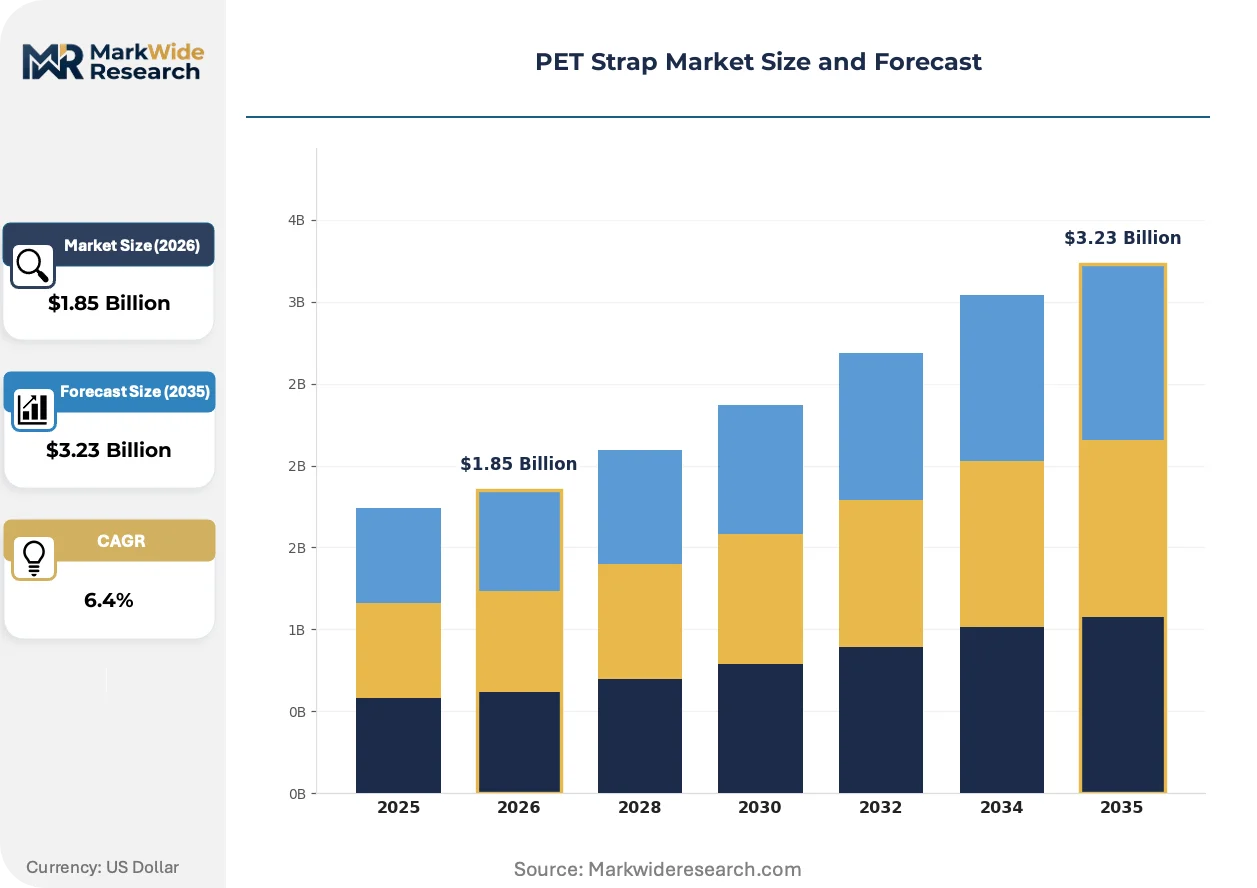
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polyamide, Polypropylene, Nylon, Cotton, Jute End Use Industry: Packaging, Construction, Agriculture, Textile, Transportation, Logistics Product Type: Flat Strap, Round Strap, Perforated Strap, Printed Strap, Reinforced Strap Distribution Channel: Direct Sales, Wholesale Distributors, Retailers, Online Marketplaces, Industrial Suppliers |
| Companies Covered | Teufelberger, Cordstrap, Signode, STEK, Samuel Strapping, FROMM Group, Polychem, M.J. Maillis Group, Mosca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Strap Market Strategic Shifts & Innovations
Digital printing integration and regulatory-driven material redesign are converging to transform PET strap from a commodity securing material into a traceable, compliance-embedded logistics component.
Multi-layer coextrusion with embedded RFID and QR-readable surface layers is fragmenting traditional strap commoditization. Pharmaceutical and food exporters in Germany and the Netherlands adopt these intelligent formats to satisfy serialization mandates. The technology is fragmenting price structures by separating traceable premium grades from undifferentiated standard offerings.
EPA recycled content thresholds for North American converters are tightening domestic sourcing requirements. Post-industrial PET flake qualification protocols now exclude certain additive-contaminated feedstreams. Strap producers in the US Midwest and Southeast reconfigure supply agreements to secure bottle-grade rPET of sufficient purity for high-tenacity extrusion.
Consolidated buying by third-party logistics providers is compressing supplier margins while demanding technical service bundling. Large European freight operators now specify strap performance guarantees tied to automated warehouse compatibility. This pattern concentrates procurement leverage in the Benelux and Rhine-Ruhr logistics clusters where distribution center automation penetration runs highest.
PET Strap Market Segmentation
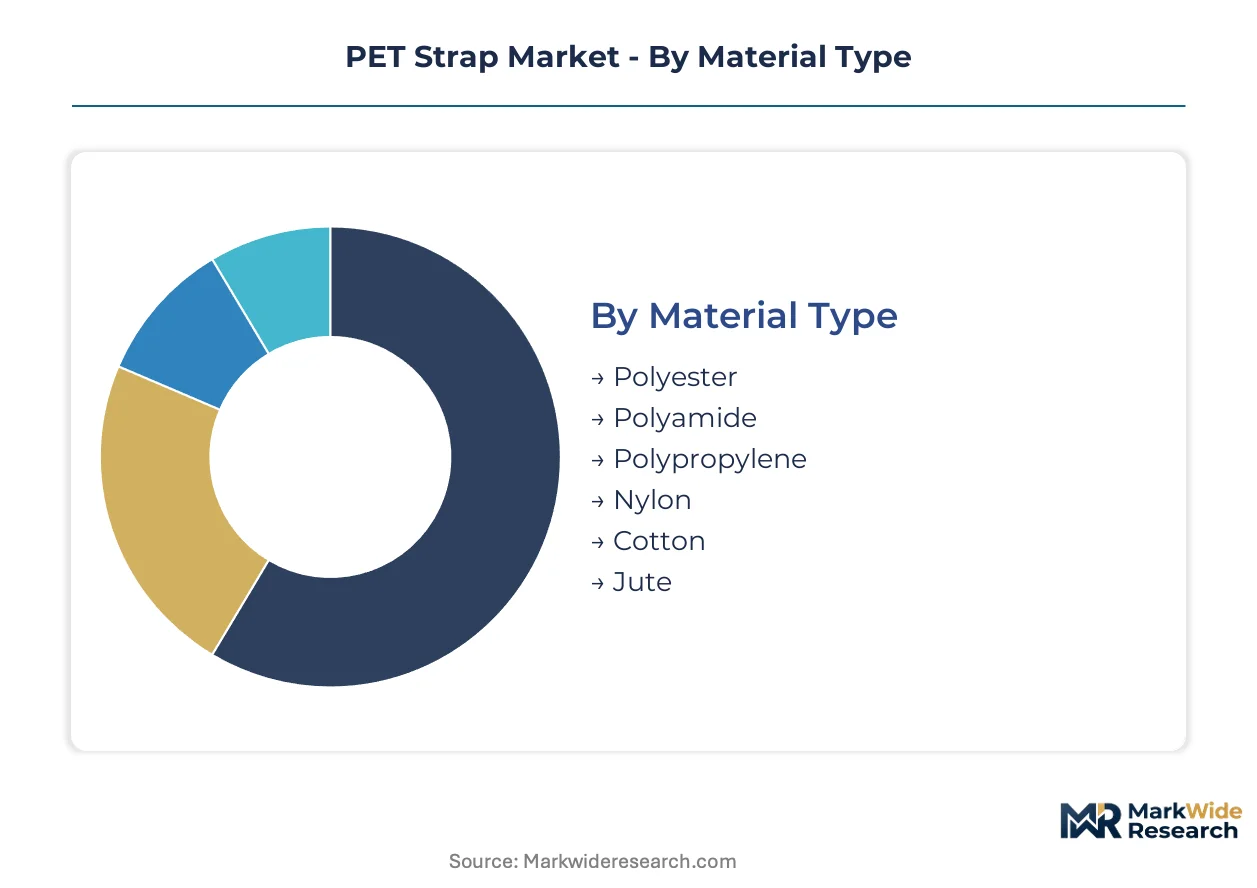
PET strap segmentation reveals divergent supply chain configurations across material grades and distribution pathways. Product specifications vary sharply between domestic industrial users and export-oriented logistics operators demanding certified performance guarantees.
Material Type:
Domestic consumption concentrates on commodity-grade polyester formulations, while export-led demand drives specialized polyamide and hybrid constructions for cross-border freight certification.
- Polyester:Oriented polyethylene terephthalate ribbon extruded at 9-32 mm widths delivers tensile strengths exceeding 450 MPa for palletized load security. Demand clusters in India's Gujarat and Maharashtra textile export hubs where garment palletization requires consistent elastic recovery performance under tropical humidity conditions.
- Polypropylene:Lower-density alternative captures light-duty bundling applications where break strength thresholds remain modest and cost sensitivity dominates procurement decisions. China's GB packaging recyclability standards favor mono-material PP designs in domestic circulation loops.
- Polyamide:High-tenacity synthetic fiber formulations serve specialized agricultural bundling requiring UV stabilization across extended outdoor exposure cycles.
- Nylon:Abrasion-resistant grades penetrate construction material securing where rough handling and sharp edges threaten strap integrity.
- Cotton:Biodegradable natural fiber options satisfy niche pharmaceutical and food export segments demanding compostable securing materials.
- Jute:Renewable fiber constructions address sustainability mandates in European agricultural cooperatives seeking plastic reduction credentials.
Polyester commands the established base. The steepest expansion runs through polypropylene substitution in weight-sensitive logistics applications.
End Use Industry:
Volume distribution follows regional industrial specialization, with margin concentration in sectors demanding certified performance guarantees and technical service bundling.
- Packaging:Primary consumption segment spanning food, beverage, and consumer goods palletization where automated warehouse compatibility determines supplier qualification. European third-party logistics providers in the Benelux cluster now specify strap performance guarantees tied to high-velocity distribution center throughput.
- Logistics:Multimodal freight operators across Asia-Pacific systematically replace steel strapping to eliminate corrosion damage and reduce shipment tare weight. India's western industrial corridor generates sustained demand for printed strap grades with embedded batch codes.
- Construction:Heavy-gauge applications require reinforced strap configurations with edge resistance for brick, block, and timber bundle securing.
- Agriculture:Seasonal demand peaks for UV-stabilized grades in hay bale and produce crate bundling across North American Midwest growing regions.
- Textile:Garment export palletization in Tamil Nadu and Karnataka secondary hubs drives specialized printed strap configurations.
- Transportation:Rail and trucking carriers specify ISO 18616-qualified strap for cross-border freight liability coverage.
Packaging anchors procurement volumes. Logistics is climbing the fastest as freight operators consolidate supplier relationships around technical service capabilities.
Product Type:
Manufacturing complexity separates commodity extrusion from value-added configurations requiring coextrusion, surface treatment, or embedded traceability features.
- Flat Strap:Dominant volume format across heavy-gauge industrial applications where break strength and elastic recovery determine load security during transit vibration. Standard extrusion lines in the US Midwest and Southeast serve regional manufacturing clusters with post-industrial rPET formulations.
- Printed Strap:Direct-to-strap digital printing embeds batch codes, handling instructions, and brand identifiers, eliminating secondary labeling steps. German and Dutch pharmaceutical exporters adopt these formats to satisfy serialization mandates under EMA traceability requirements.
- Reinforced Strap:Multi-layer constructions with embedded fiber cores command margin premiums in outdoor construction and agricultural bundling where UV stabilization and edge resistance justify price premiums over standard grades.
- Round Strap:Specialized profile for pipe and cylinder securing where uniform pressure distribution prevents surface marking.
- Perforated Strap:Ventilated designs for agricultural produce crates requiring airflow penetration to maintain shelf stability.
Flat strap holds the volume base. Printed configurations are gaining share fastest as brand owners integrate securing materials into packaging traceability systems.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and inventory velocity needs across industrial procurement segments.
- Direct Sales:Large-volume logistics operators and automated warehouse operators negotiate performance guarantees and technical service bundling through dedicated account structures. Consolidated buying by European third-party logistics providers compresses margins while demanding strap-warehouse automation compatibility certification.
- Industrial Suppliers:Technical distributors serve mid-tier converters requiring polymer compounding expertise and formulation guidance for REACH-compliant additive selection.
- Wholesale Distributors:Regional inventory positioning serves construction and agricultural seasonal demand spikes with standard grade availability.
- Online Marketplaces:Emerging channel for small-batch procurement by specialty exporters seeking printed strap with short lead times.
- Retailers:Limited penetration in consumer-facing hardware channels for light-duty bundling applications.
Direct sales commands the established base. Industrial suppliers represent the steepest expansion trajectory as mid-tier converters seek technical partnership beyond commodity transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards issued by China's national standardization authority anchor Asia-Pacific regulatory momentum, while EPA recycled content thresholds reshape North American sourcing patterns. Divergent certification timelines across ISO 18616 and ASTM D3950 frameworks complicate inventory interchangeability for multinational logistics operators.
China
Steel-to-PET substitution accelerates across multimodal freight corridors as logistics operators prioritize weight reduction and corrosion elimination. GB packaging recyclability standards tighten material specifications, forcing converters toward mono-material designs that simplify post-consumer recovery. The Yangtze River Delta manufacturing cluster hosts extrusion facilities serving pharmaceutical exporters adopting intelligent strap formats with embedded traceability layers.
India
Textile export palletization drives sustained demand for printed and reinforced strap grades across garment logistics hubs. BIS certification requirements for packaging materials influence converter qualification protocols for cross-border freight. The western industrial corridor spanning Gujarat and Maharashtra anchors procurement volumes, while Tamil Nadu and Karnataka secondary hubs offer white-space expansion for specialized strap configurations.
Germany
Pharmaceutical and food exporters adopt multi-layer coextrusion formats with RFID-readable surface layers to satisfy EMA serialization mandates. ECHA REACH restrictions on plasticizers and stabilizers force reformulation cycles favoring suppliers with in-house polymer laboratories. The Rhine-Ruhr logistics cluster concentrates procurement leverage as third-party logistics providers specify strap performance guarantees tied to automated warehouse compatibility.
United States
Post-industrial PET flake qualification protocols exclude additive-contaminated feedstreams under tightening EPA guidelines. Midwest and Southeast converters reconfigure supply agreements to secure bottle-grade rPET purity for high-tenacity extrusion. Toll-manufacturing partnerships serve regional logistics contracts as Samuel Strapping competes aggressively on North American freight operator procurement.
Netherlands
Benelux distribution center automation penetration drives technical service bundling requirements for strap suppliers serving consolidated logistics buyers. EU Green Deal packaging sustainability targets accelerate mono-material adoption across circular economy pilot programs. Rotterdam-Antwerp port logistics corridors generate demand for ISO 18616-qualified strap configurations serving cross-border freight liability coverage.
PET Strap Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with fiber technology heritage separating premium-grade specialists from volume-driven toll manufacturers. The vendor base organizes around three strategic groupings: integrated extrusion-weaving operators with captive polymer laboratories, toll-manufacturing partners serving regional logistics contracts, and mid-tier converters dependent on external compounding expertise. Dominant competitive moves center on backward integration into virgin-grade resin sourcing and geographic expansion through dedicated account structures for automated warehouse operators.
Among European-heritage specialists, Teufelberger and Cordstrap exemplify divergent paths to defensible positioning. Teufelberger leverages Austrian fiber technology heritage to sustain premium positioning in high-tenacity strap grades, while Cordstrap anchors its position through integrated extrusion and weaving operations across European and Asian plants. Samuel Strapping occupies a position on the North American volume tier, competing through toll-manufacturing partnerships rather than captive resin integration. These three players collectively represent the technology-cost spectrum that structures competitive rivalry.
| Leading Market Players |
|---|
| Teufelberger |
| Cordstrap |
| Signode |
| STEK |
| Samuel Strapping |
| FROMM Group |
| Polychem |
| M.J. Maillis Group |
| Mosca |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between European logistics operators and Austrian fiber technology specialists lock in both virgin-grade PET resin access and twelve-month price visibility against polymer compounding volatility. These contracts insulate premium-grade buyers from spot market swings while compressing margins for toll-manufacturing competitors serving price-sensitive North American freight contracts.
Pricing Analysis
Geographic price spreads widen substantially between Benelux automated warehouse operators and Indian textile export palletizers, with the former absorbing technical service bundling premiums and the latter driving hard volume discounts on printed strap configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18616-qualified traceable grades from commodity extrusions and polypropylene substitutes. Pricing pressure stems from consolidated procurement leverage among third-party logistics providers specifying automation compatibility guarantees. Small-batch specialty exporters exhibit highest price sensitivity, while pharmaceutical serialization-mandated buyers accept premium positioning for RFID-embedded formats.
Supply Chain Analysis
China and India anchor oriented PET ribbon extrusion capacity, with the Yangtze River Delta and Gujarat-Maharashtra corridor hosting integrated extrusion-weaving operations serving pharmaceutical and textile export demand respectively. Virgin-grade PET resin, post-industrial rPET flake, and UV stabilizer additives constitute critical input dependencies. Single-source vulnerability concentrates in Austrian fiber technology heritage for high-tenacity draw ratio control. Distribution runs through direct sales channels for large-volume logistics operators, industrial suppliers for mid-tier converters, and wholesale distributors for seasonal construction and agricultural demand spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as steel-to-PET substitution fragments procurement specifications across weight-sensitive logistics, corrosion-critical freight, and automation-compatible warehouse applications, creating tiered service requirements that favor specialized positioning over commodity scale.
For Market Incumbents: Fortify captive polymer laboratory capabilities to accelerate REACH-compliant reformulation cycles ahead of ECHA additive restriction timelines. Deepen backward integration into bottle-grade rPET purification partnerships across US Midwest and Southeast converter networks to secure EPA-threshold-compliant feedstreams against post-industrial flake qualification tightening. For New Entrants and Emerging Players: BIS certification fast-track for India's Tamil Nadu and Karnataka textile export hubs offers white-space penetration before incumbent technical service bundling locks in garment palletization contracts. Target printed strap configurations with direct-to-surface batch coding as the most penetrable application, leveraging short-lead-time online marketplace channels to bypass established direct sales relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated extrusion-weaving operators with captive resin qualification protocols and established pharmaceutical serialization-mandate relationships. Long-term viability hinges on differentiation durability against polypropylene substitution in light-duty segments. Watch for inflection signals in China's GB packaging recyclability standard enforcement timelines, which would accelerate mono-material PET design adoption and compress hybrid-grade margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Purification | Secures EPA-compliant feedstream access for US Midwest and Southeast converters. |
| Direct-to-Strap Digital Printing Capacity | Captures EMA serialization mandate demand from German and Dutch pharmaceutical exporters. |
| UV Stabilization Formulation Investment | Commands margin premiums in North American Midwest agricultural hay bale bundling applications. |
| Automated Warehouse Compatibility Certification | Qualifies suppliers for Benelux third-party logistics provider consolidation contracts. |
| India Western Corridor Technical Service Expansion | Defends position against BIS-certified new entrants in Gujarat and Maharashtra textile hubs. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with polymer compounding specialists, extrusion plant managers, logistics procurement leads, and textile export operations directors; and secondary validation against customs trade records, SEC filings of listed packaging converters, EPA recycled content guideline documentation, and ECHA REACH restriction updates. Bottom-up triangulation across regional production capacity estimates and top-down demand validation from end-use industry consumption patterns ensured cross-verified outputs.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning material grade tier, end-use industry vertical, product type complexity, and distribution channel structure. CAGRs derived from weighted regression of historical shipment volumes against identified catalyst and restraint trajectories. Industry-specific inputs included polymer resin price volatility indices and logistics automation penetration rates by regional distribution cluster.
Underlying assumptions cover sustained steel-to-PET substitution momentum and REACH additive restriction enforcement timelines, with deviation risk concentrated in polypropylene substitution acceleration and virgin-grade resin supply disruption. Recalibration cycles align with material shifts in China's GB standard implementation pace and EPA recycled content threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Desiccant Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
MDO Films Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Vacuum Thermoformed Packaging Market