
 Cassava Bags Market | 2026-2036
Cassava Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cassava Bags Market Outlook
Aftermarket service revenue from composting infrastructure partnerships is narrowing as manufacturers vertically integrate into waste collection networks. Biogreen Bags Co. Ltd leverages its Thai manufacturing base to control raw cassava starch sourcing costs. Evoware anchors its position through proprietary film-forming technology that extends shelf stability in humid climates. Oikos Sustainable Solutions, Inc. specializes in custom-printed retail bags for Southeast Asian grocery chains.
Cassava bags are thermoplastic films extruded from native or modified cassava starch, typically blended with glycerol plasticizers and aliphatic polyesters to achieve tensile strengths of 15-25 MPa and biodegradation within 90-180 days in industrial composting conditions; they serve as drop-in replacements for conventional polyethylene in retail carry, food contact, and agricultural mulch applications. Compostable bags dominate current volume as municipal organic waste programs expand across Indonesia and Vietnam, while reusable bags capture expanding margin pools through brand-loyalty programs in Thailand's supermarket sector. Flat bags lead production mix due to simpler extrusion die requirements, though gusseted bags are gaining traction in industrial bulk packaging for agricultural cooperatives.
Indonesia's Ministry of Environment and Forestry enforces plastic waste reduction targets that mandate biodegradable alternatives in traditional markets, while Thailand's National Hazardous Substances Committee regulates starch-based film compostability claims through industrial testing protocols. Vietnam's Ministry of Natural Resources and Environment coordinates provincial pilot programs linking cassava bag distribution to municipal composting facilities. Stakeholders must monitor whether emerging biodegradability certification schemes in ASEAN member states converge or fragment, as divergent standards would reshape cross-border manufacturing location decisions.
Market Dynamics
Indonesia's national plastic waste reduction mandate is compressing conversion timelines for food service operators, forcing immediate sourcing switches from polyethylene to cassava-derived films while municipal composting infrastructure races to match end-of-life processing capacity.
Growth Catalysts
- Biodegradable Mandates:Indonesia's Ministry of Environment and Forestry enforces plastic waste reduction targets that compel traditional market vendors to adopt cassava-based alternatives.
- Composting Infrastructure:Vietnam's provincial pilot programs linking bag distribution to municipal composting facilities create closed-loop demand pull.
- Starch Supply Proximity:Thailand's cassava cultivation belt provides raw material concentration that reduces feedstock logistics costs for film extruders.
Market Restraints
- Glycerol Price Volatility:Plasticizer input costs fluctuate with biodiesel co-product markets, squeezing margin predictability for compounders.
- Single-Region Supply Risk:Native cassava starch processing concentrates in Southeast Asian crushing facilities, exposing buyers to climate-driven crop yield variation.
- Industrial Composting Dependency:Biodegradation claims require municipal facility access that remains patchy outside Vietnam's urban grocery corridors.
Strategic Opportunities
- Agricultural Mulch Films:Cassava-based mulch addresses soil microplastic accumulation in Thailand's intensive vegetable farming zones.
- Brand-Loyalty Programs:Thai supermarket chains are integrating reusable cassava bags into customer retention mechanics.
- ASEAN Certification Convergence:Emerging biodegradability standards across member states could harmonize cross-border manufacturing location decisions.
Industry Challenges
- Film-Forming Expertise Gap:Humid-climate shelf stability engineering requires polymer science specialization that outpaces regional talent pipelines.
- Compostability Testing Bottlenecks:Thailand's National Hazardous Substances Committee protocols create certification backlogs that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cassava Bags Market |
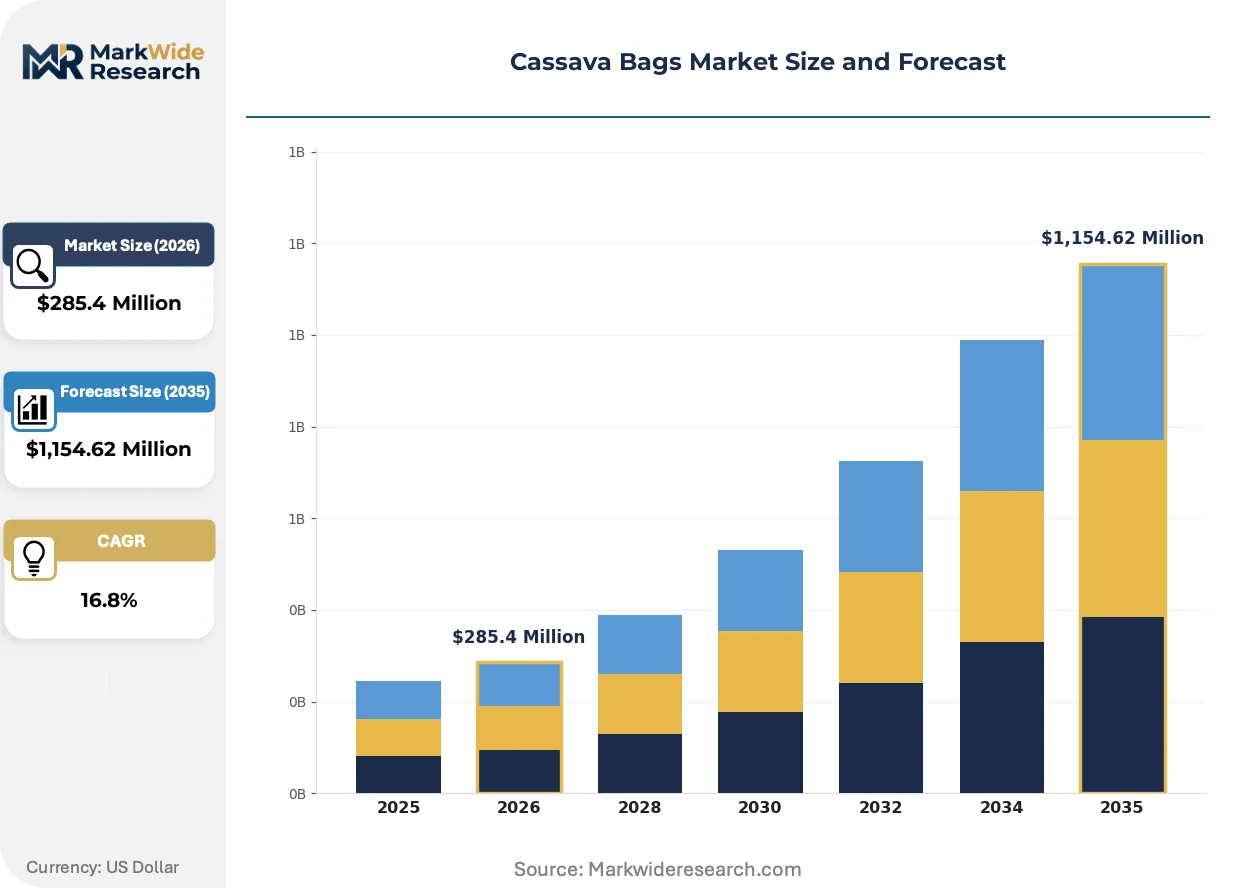
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Compostable Bags, Reusable Bags, Single-use Bags End Use Industry: Agriculture, Retail, Food Service, Industrial Packaging Type: Flat Bags, T-Shirt Bags, Block Bottom Bags, Gusseted Bags Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Avani Eco, Biogreen Bags Co. Ltd, Evoware, Affinity Supply Co., Biopak, Henan Baolai Packaging Co., Ltd., Urban Plastik, Tipa, Oikos Sustainable Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cassava Bags Market Strategic Shifts
Extrusion technology advances are compressing the performance gap between starch-based films and conventional polyethylene, while regulatory pressure accelerates formulation innovation and supply chain reconfiguration across Southeast Asian manufacturing bases.
Modified cassava starch blends with aliphatic polyesters are virtualizing the moisture-barrier limitations that previously restricted cassava films to dry-goods packaging. Food service operators in Indonesia's quick-service restaurant sector are adopting these formulations at compressed conversion timelines. The technology is virtualizing the historical trade-off between biodegradation speed and shelf stability, enabling humid-climate distribution without secondary packaging.
Thailand's National Hazardous Substances Committee has tightened compostability claim verification through mandatory industrial testing protocols. Film manufacturers must now submit to standardized biodegradation trials before marketing products as compostable. Small compounders without in-house testing capacity are outsourcing certification to accredited laboratories, extending product development cycles.
Retail procurement patterns are consolidating vendor relationships around vertically integrated suppliers capable of guaranteeing both raw material traceability and composting partnership documentation. Southeast Asian grocery chains are reducing their approved supplier lists from multiple trading houses to single-source contracts with compounders controlling captive starch processing. This concentration is most visible in Vietnam's urban grocery sector, where municipal composting infrastructure creates compliance verification requirements that favor integrated vendors.
Cassava Bags Market Segmentation
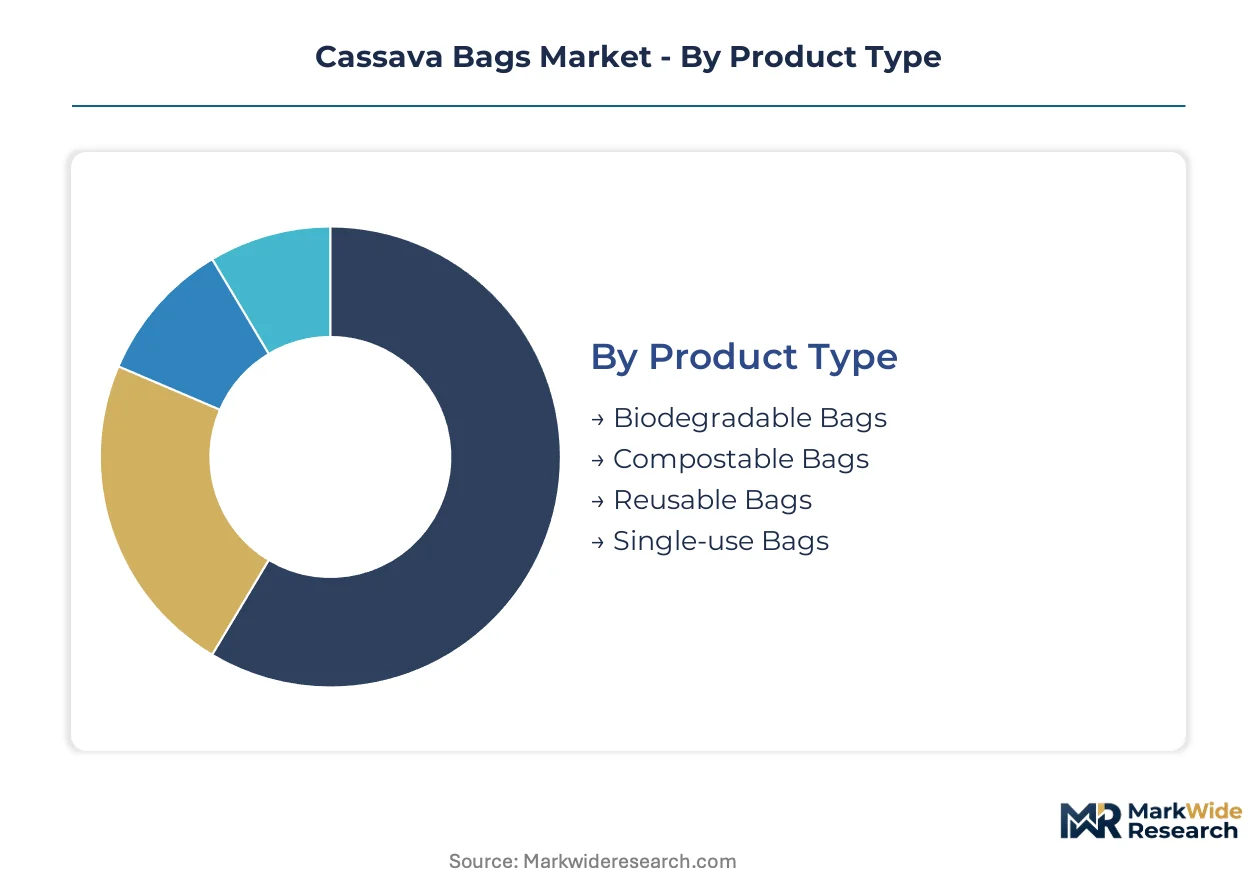
Cassava bag manufacturers configure production lines around distinct biodegradation timelines and reuse cycles. Segment-specific formulation requirements dictate raw material sourcing strategies and extrusion equipment investments.
Product Type:
Compostable bags turn inventory fastest through municipal procurement cycles, while reusable variants sit in distribution channels longest due to brand-customization lead times.
- Compostable Bags:These films blend native cassava starch with aliphatic polyesters to achieve industrial composting certification within 90-180 days. Indonesia's Ministry of Environment and Forestry procurement mandates are concentrating demand among traditional market vendors facing immediate compliance deadlines.
- Reusable Bags:Thicker gauge constructions incorporate glycerol plasticizers at higher loadings for durability across 50+ use cycles. Thai supermarket chains are embedding these into customer retention programs, extending replacement intervals and compressing per-unit margin pressure.
- Biodegradable Bags:Formulations prioritize rapid soil disintegration for agricultural mulch applications without industrial composting infrastructure.
- Single-use Bags:Thin-gauge extrusions serve quick-service restaurant takeout packaging with minimal material cost.
Compostable bags anchor the volume base while reusable bags gain share at the steepest rate.
End Use Industry:
Cost tiers separate capital-intensive agricultural mulch films from high-margin customized retail packaging.
- Retail:Custom-printed carry bags demand film-forming expertise for humid-climate shelf stability. Vietnam's urban grocery sector is concentrating procurement around vertically integrated compounders capable of composting partnership documentation.
- Food Service:Quick-service restaurant operators in Indonesia require moisture-barrier formulations that virtualize historical trade-offs between biodegradation speed and grease resistance.
- Agriculture:Mulch films address soil microplastic accumulation in Thailand's intensive vegetable farming corridors.
- Industrial:Bulk packaging for agricultural cooperatives specifies gusseted constructions with higher tensile strength thresholds.
Retail commands the widest formulation diversity while food service expands most quickly.
Packaging Type:
Volume concentration favors simpler die geometries, though structural complexity unlocks premium pricing in bulk applications.
- Flat Bags:Simpler extrusion die requirements reduce capital equipment barriers for entry-level compounders. Municipal composting programs across Vietnam's provincial pilot networks are standardizing on this geometry for cost-efficient distribution.
- Gusseted Bags:Side-fold constructions expand cubic capacity for agricultural cooperative bulk purchasing. Thailand's National Hazardous Substances Committee testing protocols create certification backlogs that favor established manufacturers with in-house laboratory capacity.
- T-Shirt Bags:Die-cut handles serve traditional market carry applications with minimal material usage.
- Block Bottom Bags:Self-standing constructions target premium retail presentation with higher starch loading requirements.
Flat bags dominate unit volume while gusseted bags climb the fastest.
Distribution Channel:
Customer type fragmentation separates specification-heavy institutional procurement from price-sensitive spot purchasing.
- Supermarkets:Thai grocery chains are consolidating approved vendor lists from multiple trading houses to single-source contracts demanding captive starch processing and traceability documentation.
- Wholesale:Traditional market vendor aggregation in Indonesia compresses transaction costs but extends payment cycles. The country's national plastic waste reduction mandate is forcing immediate sourcing switches that strain working capital.
- Online Retail:Direct-to-consumer channels serve specialty biodegradable product segments with higher per-unit logistics costs.
- Specialty Stores:Eco-focused retailers stock premium compostable variants with certification markup.
Supermarkets anchor procurement volume while wholesale channels expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia consumes cassava bags predominantly through food service mandates, while Vietnam concentrates procurement around municipal composting programs and Thailand channels volume through supermarket loyalty mechanics.
Indonesia
Traditional market vendors and quick-service restaurants drive demand through immediate compliance requirements. The Ministry of Environment and Forestry enforces plastic waste reduction targets with compressed conversion timelines. Jakarta's urban procurement clusters coordinate sourcing switches that strain working capital across wholesale distribution networks.
Vietnam
Urban grocery chains anchor volume through composting partnership documentation requirements. The Ministry of Natural Resources and Environment coordinates provincial pilot programs linking bag distribution to municipal facilities. Ho Chi Minh City's retail procurement corridors concentrate demand around vertically integrated compounders with captive starch processing.
Thailand
Supermarket customer retention programs expand reusable bag adoption across 50-plus use cycles. The National Hazardous Substances Committee regulates compostability claims through mandatory industrial testing protocols. Bangkok's manufacturing belt leverages cassava cultivation proximity to reduce feedstock logistics costs for film extruders.
Philippines
Traditional wet market vendors generate spot demand for single-use carry bags with minimal certification requirements. The national solid waste management framework incentivizes biodegradable alternatives through local government unit procurement. Metro Manila's distribution networks aggregate fragmented vendor demand into consolidated wholesale purchasing.
Malaysia
Specialty eco-retailers stock premium compostable variants with certification markup for affluent urban consumers. The Department of Environment coordinates voluntary biodegradable packaging adoption in federal territories. Kuala Lumpur's boutique retail corridors test higher-margin block-bottom constructions for premium brand presentation.
Cassava Bags Market Competitive Environment
Capability concentration sits with integrated compounders controlling captive starch processing; scale advantage sits with regional trading houses aggregating fragmented traditional market demand. The vendor base stratifies across three tiers: vertically integrated manufacturers with in-house testing laboratories, mid-scale compounders outsourcing certification to accredited facilities, and trading houses without extrusion capacity. Dominant competitive moves include backward integration into raw material sourcing and consolidation of approved supplier lists by retail procurement teams.
Among Southeast Asian specialists, Biogreen Bags Co. Ltd represents the vertically integrated archetype with Thai manufacturing positioning, while Evoware exemplifies technology-focused differentiation through proprietary formulation approaches. Oikos Sustainable Solutions, Inc. occupies a position within the custom-printing tier serving retail brand requirements. These three anchors illustrate the geographic and capability segmentation shaping vendor selection criteria across Indonesian food service, Vietnamese grocery, and Thai supermarket channels.
| Leading Market Players |
|---|
| Avani Eco |
| Biogreen Bags Co. Ltd |
| Evoware |
| Affinity Supply Co. |
| Biopak |
| Henan Baolai Packaging Co., Ltd. |
| Urban Plastik |
| Tipa |
| Oikos Sustainable Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Bangkok-Laem Chabang freight corridor moves raw cassava starch from Thailand's central plains to film extrusion facilities, with logistics cost differentials creating pricing power asymmetries between integrated compounders and trading houses dependent on spot feedstock purchases.
Pricing Analysis
Long-term offtake contracts dominate procurement between Vietnamese grocery chains and vertically integrated manufacturers, locking in volume commitments that insulate compounders from glycerol price volatility while compressing margins for spot-market buyers. Price differentiation rests on certification tier—Thailand's National Hazardous Substances Committee industrial composting protocols command premium positioning—and customization depth for humid-climate shelf stability. Cost compression in standard-grade compostable bags is intensifying because Indonesian wholesale distributors aggregate fragmented traditional market demand into consolidated purchasing. Quick-service restaurant operators exhibit highest price sensitivity due to compressed conversion timelines under Ministry of Environment and Forestry mandates, while Thai supermarket loyalty programs absorb premium pricing for reusable variants.
Supply Chain Analysis
Extended payment terms from Indonesian wholesale distributors strain working capital across mid-scale compounders lacking supply-chain finance facilities, forcing outsourcing of compostability certification to accredited laboratories and extending product development cycles. Raw material sourcing draws from Thailand's cassava cultivation belt, Vietnam's emerging starch processing investments, and Indonesian crushing facilities. Feedstock logistics hinge on climate-driven crop yield variation concentrated in Southeast Asian growing regions. Single-region supply risk exposes buyers to monsoon disruption patterns. Distribution runs through vertically integrated compounders with captive starch processing, municipal procurement coordinators in Vietnam's provincial pilot programs, and wholesale aggregators serving Indonesia's traditional market vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Thai supermarket chains consolidate approved vendor lists from multiple trading houses to single-source contracts, fragmenting negotiating leverage among smaller compounders without integrated supply chains.
For Market Incumbents: Pre-empt margin erosion from glycerol price volatility by securing backward integration into Thai cassava starch processing or captive glycerol supply arrangements. Defend positioning against emerging mid-scale compounders by accelerating in-house laboratory capacity for Thailand's National Hazardous Substances Committee testing protocols, compressing certification timelines that currently delay product launches. For New Entrants and Emerging Players: The Philippines' traditional wet market vendor base offers white-space expansion with minimal certification requirements under local government unit procurement incentives. Target agricultural mulch film applications in Thailand's intensive vegetable farming corridors where soil microplastic concerns outpace existing supplier coverage. Pursue direct partnerships with provincial composting facility operators to bypass established wholesale distribution networks. For Investors and Strategic Acquirers: Carve-out targets emerge from regional trading houses without extrusion capacity that hold fragmented Indonesian wholesale relationships but lack backward integration into raw material sourcing. Long-term viability hinges on certification convergence across ASEAN biodegradability standards; integrated compounders with in-house testing infrastructure represent durable acquisition archetypes. Monitor Indonesia's Ministry of Environment and Forestry enforcement intensity as inflection indicator for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Starch Processing | Captive feedstock supply insulates Biogreen Bags Co. Ltd from climate-driven crop yield variation. |
| In-House Compostability Certification Laboratory | Accelerated Thailand National Hazardous Substances Committee testing compresses product launch timelines. |
| Municipal Composting Partnership Documentation | Vietnam's Ministry of Natural Resources and Environment pilot programs require integrated vendor verification. |
| Proprietary Humid-Climate Film-Forming Technology | Evoware's shelf stability engineering virtualizes historical biodegradation speed trade-offs. |
| Custom-Printed Retail Bag Capability | Oikos Sustainable Solutions anchors Vietnamese grocery chain loyalty through brand differentiation. |
Study Parameters
Desk research of customs trade records, ASEAN regulatory filings, and starch industry association reports preceded structured interviews with film extrusion plant managers, grocery chain procurement directors, municipal composting facility coordinators, and food service packaging buyers. Primary fieldwork validated formulation specifications, certification timelines, and vendor selection criteria against secondary data from Thailand's National Hazardous Substances Committee disclosure databases, Vietnam's Ministry of Natural Resources and Environment pilot program documentation, and Indonesian Ministry of Environment and Forestry enforcement circulars. Bottom-up demand aggregation across retail, food service, and agricultural segments triangulated against top-down supply capacity estimates from regional crushing facility utilization rates.
Assumptions held fixed across the modeling period include current ASEAN regulatory enforcement intensity, existing municipal composting infrastructure deployment rates, and observed glycerol price volatility patterns derived from biodiesel co-product market dynamics. Segmentation dimensions modeled encompass product type tier, end-use industry vertical, packaging geometry, and distribution channel structure. CAGRs were derived from volume trajectory analysis calibrated to procurement mandate compliance timelines and infrastructure build-out schedules. Industry-specific forecast inputs incorporated cassava starch yield sensitivity to precipitation patterns and industrial composting facility capacity expansion pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale compounders or accelerated certification harmonization across ASEAN member states would shift outcomes. Macroeconomic deviation, regulatory enforcement intensity variation, or breakthrough biodegradable polymer alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Garbage Bag Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Type-C Bulk Bags Market