
 PET Material Packaging Market | 2026-2036
PET Material Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PET Material Packaging Market Analytics
Capital-intensity divergence between integrated resin producers and regional converters is unwinding competitive stability in PET packaging. Amcor plc leverages captive preform manufacturing across multiple continents to sustain margin control against volatile resin pricing. Berry Global anchors its position through blown-film extrusion scale in North American personal care supply chains. Resilux NV specializes in custom preform design for premium beverage clients, competing on mold flexibility rather than tonnage.
PET material packaging comprises thermoformed or blow-molded containers fabricated from polyethylene terephthalate resin, typically with intrinsic viscosity between 0.70 and 0.84 dL/g for carbonated beverage grades and barrier-enhanced multilayer structures for oxygen-sensitive contents. The material serves primarily to extend shelf life while reducing unit weight versus glass or metal alternatives. Bottles occupy the dominant volume position across beverage and personal care applications, though pouches represent the fastest-expanding format in single-serve food segments where flexible barrier films displace rigid formats. Rigid containers still capture the majority of value pools in pharmaceutical and household product channels where dimensional stability and child-resistance specifications command premium positioning.
FDA food-contact notification requirements and EU REACH compliance on monomer migration limits shape formulation choices and recycling stream eligibility for PET packaging sold in the United States and European markets. EFSA evaluations of recycled PET process efficacy directly determine rPET incorporation ceilings in food-contact applications across EU member states. India's BIS certification for food-grade plastics and China's GB standards for packaging materials add parallel compliance layers for exporters serving Asian manufacturing networks. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical recycling pathway approvals as these regulatory instruments increasingly determine viable feedstock strategies and capital allocation priorities.
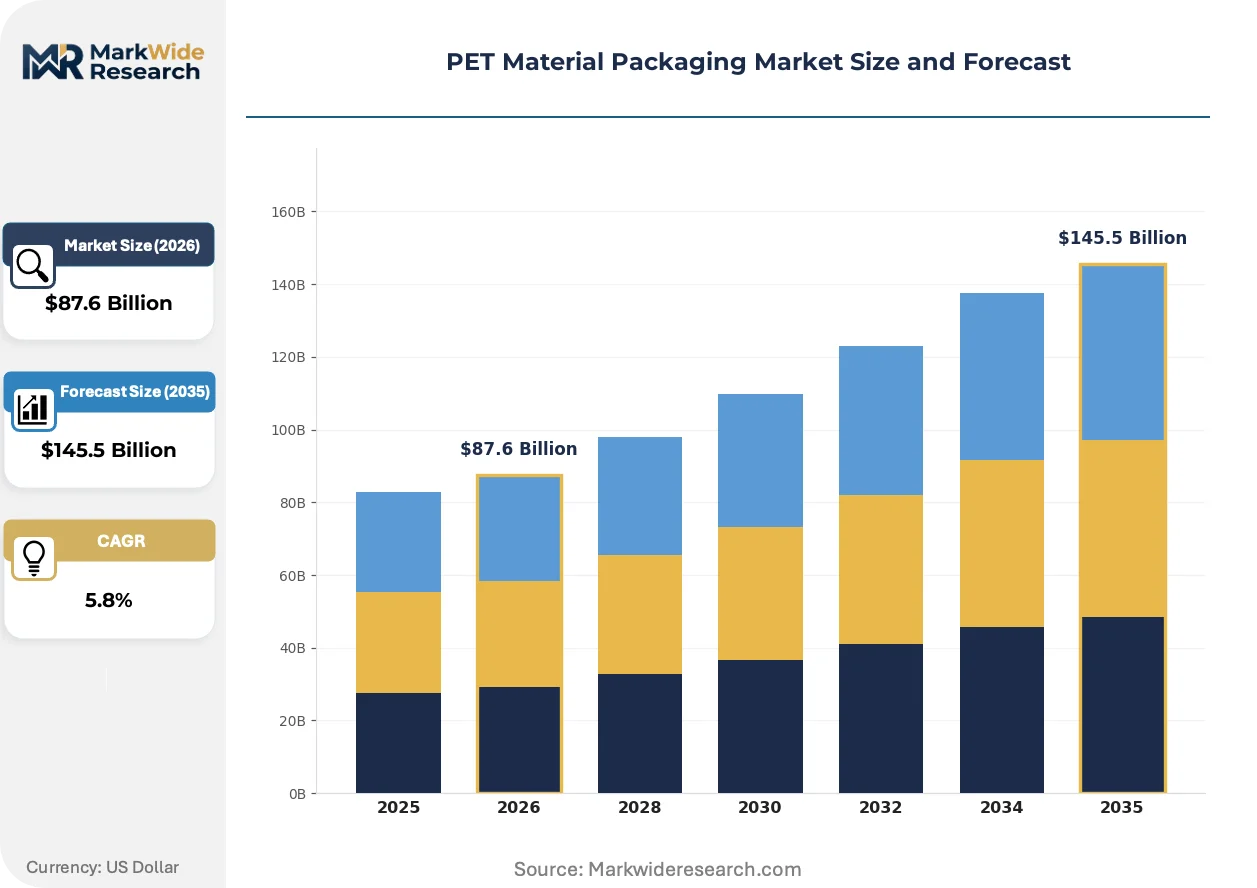
Market Dynamics
Lightweighting mandates and rPET integration requirements are compressing format transitions across beverage supply chains, forcing converters to reconfigure extrusion and blow-molding assets faster than depreciation cycles allow.
Growth Catalysts
- EFSA rPET process approvals:Elevated food-contact ceilings enable higher recycled content ratios in EU bottling operations, accelerating capital redeployment toward chemical recycling infrastructure.
- Carbonated soft drink bottlers:North American and European beverage producers are expanding lightweight PET adoption to hit scope 3 emissions targets ahead of 2030 deadlines.
- Barrier-enhanced multilayer co-injection:Oxygen-scavenging technologies extend shelf life for sensitive contents, opening pharmaceutical and nutraceutical applications previously reserved for glass.
Market Restraints
- Paraxylene and PTA price volatility:Raw material cost swings compress converter margins when resin producers pass through feedstock movements faster than contract structures allow.
- Gulf Coast resin concentration:Hurricane exposure and freeze-event disruption risk at integrated PTA-PET complexes create supply vulnerability for non-captive converters.
- Monomer migration limits under REACH:EU regulatory ceilings on cyclic oligomer content restrict regrind ratios and complicate closed-loop recycling economics.
Strategic Opportunities
- India's BIS food-grade certification expansion:Domestic bottling capacity investments create demand for imported preform technology and mold-fabrication partnerships.
- Aseptic blow-fill-seal integration:Convergence of sterile filling and PET forming eliminates intermediate handling, cutting logistics costs for dairy and ready-to-drink tea.
- Extended producer responsibility frameworks:Deposit-return schemes in Germany and emerging EU member states create revenue streams from collected flake that subsidize virgin resin premiums.
Industry Challenges
- Intrinsic viscosity degradation management:Maintaining mechanical properties through multiple mechanical recycling loops demands precise solid-state polymerization control that few converters have mastered.
- Food-contact notification timelines:FDA clearance for novel barrier additives or recycled content processes stretches 18-24 months, delaying product launches against faster-moving competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Material Packaging Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Pouches, Trays End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Form: Rigid, Flexible, Semi-Rigid, Blister Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Amcor plc, Berry Global, Gerresheimer AG, Silgan Holdings, Graham Packaging Company, Resilux NV, ALPLA Werke Alwin Lehner GmbH and Co KG, Plastipak, KLöckner Pentaplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Material Packaging Market Evolving Landscape
Material science advances and regulatory pressure on circularity are splitting the market between high-performance barrier structures and cost-optimized lightweight formats, with technology choices increasingly locked in by end-use certification requirements.
Mono-material barrier coatings are bifurcating the oxygen-sensitive packaging segment. Plasma-enhanced chemical vapor deposition applies silicon oxide layers directly to PET bottle interiors, eliminating multilayer co-injection complexity. Premium cosmetics and pharmaceutical brands in Switzerland and Germany are adopting these structures to maintain recyclability credentials while extending shelf life. The technology is compressing demand for conventional multilayer preforms with discrete EVOH or nylon cores.
EU Green Deal packaging and packaging waste regulations are mandating minimum recycled content thresholds and design-for-recycling standards. These rules force converters to eliminate problematic additives and adhesives that contaminate mechanical recycling streams. Food-contact beverage applications face the steepest compliance curves, with brand owners reformulating colorants and stabilizers to maintain EFSA clearance under stricter migration testing protocols.
Direct-to-retail bulk dispensing is altering procurement patterns for household and personal care products. Refill stations in German and French supermarket chains reduce single-use bottle volumes, shifting value toward durable dispenser designs and concentrate pouch formats. Personal care brands are responding with concentrated formulations that trade water weight for shipping efficiency, compressing traditional blow-molded bottle demand in urban catchments where refill infrastructure penetrates fastest.
PET Material Packaging Market Segmentation
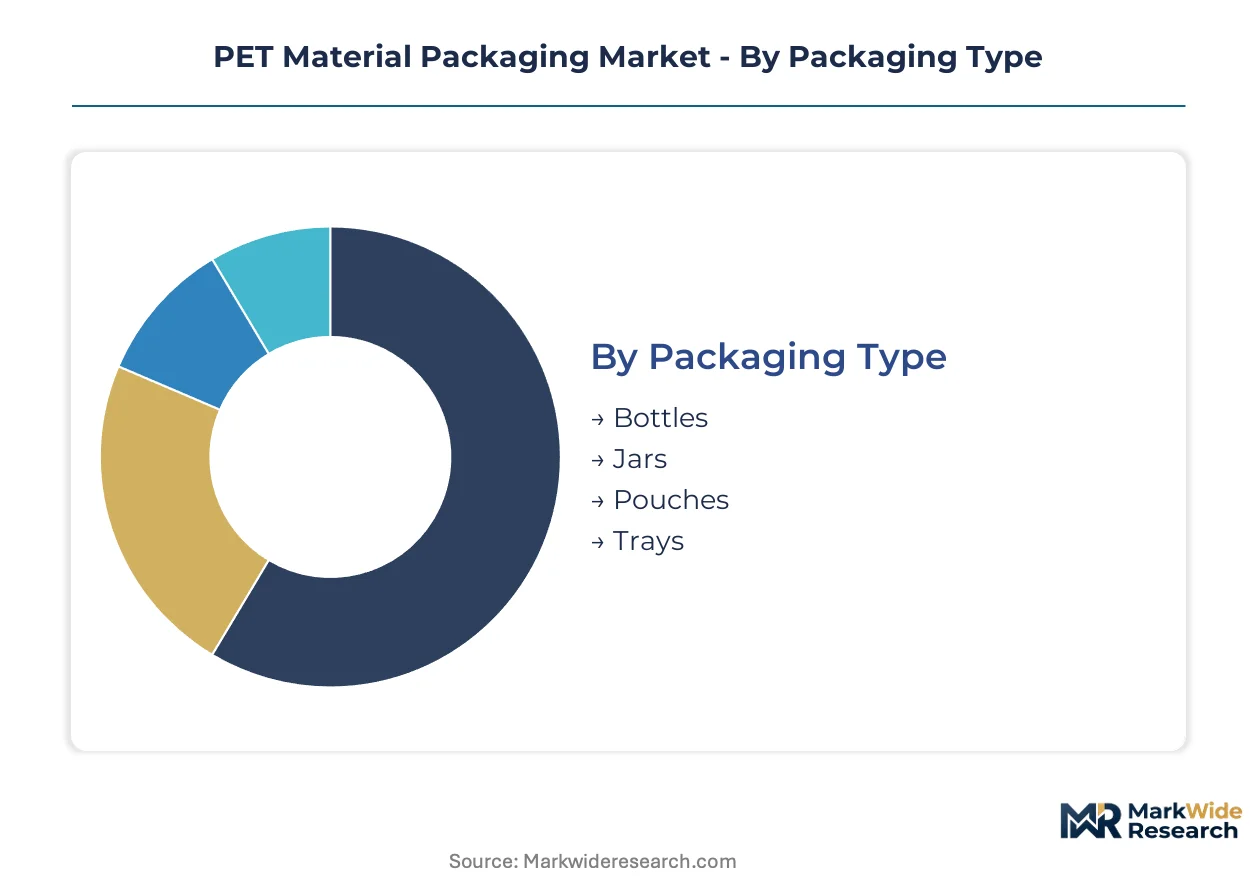
PET packaging segmentation reflects divergent regulatory compliance burdens across food-contact and non-food applications. Format selection directly determines which EFSA migration limits, FDA notification pathways, or BIS certification requirements apply.
Packaging Type:
EFSA food-contact ceilings and FDA monomer migration thresholds create tiered compliance costs that reshape competitive economics by format.
- Bottles:Blow-molded containers with intrinsic viscosity between 0.70 and 0.84 dL/g dominate carbonated beverage applications. German bottlers are driving lightweighting adoption under EU Green Deal mandates, compressing gram weights per unit while maintaining EFSA clearance for rPET integration.
- Pouches:Flexible barrier films displace rigid formats in single-serve food segments, climbing fastest where retail refill infrastructure penetrates urban catchments. Oxygen-scavenging multilayer structures complicate mechanical recycling economics despite operational cost advantages.
- Jars:Wide-mouth thermoformed containers serve spreads and personal care creams requiring scoop access. India's BIS food-grade certification expansion is accelerating domestic preform technology imports for this format.
- Trays:Thermoformed structures for fresh produce and ready meals face steep compliance curves under EU packaging waste regulations. Design-for-recycling standards are eliminating problematic adhesives and colorants.
Established volume favors bottles; emerging adoption favors pouches.
End Use Industry:
Customer procurement patterns split between high-volume beverage contracts and specification-intensive pharmaceutical tenders.
- Food & Beverage:Carbonated soft drink bottlers in North America and Europe anchor demand, expanding lightweight PET adoption to hit scope 3 emissions targets. EFSA rPET process approvals enable higher recycled content ratios, accelerating capital redeployment toward chemical recycling infrastructure.
- Pharmaceuticals:Barrier-enhanced multilayer co-injection extends shelf life for oxygen-sensitive contents, opening applications previously reserved for glass. FDA food-contact notification timelines for novel barrier additives stretch 18-24 months.
- Personal Care:Premium cosmetics brands in Switzerland and Germany adopt plasma-enhanced silicon oxide coatings to maintain recyclability credentials. Direct-to-retail bulk dispensing shifts value toward durable dispenser designs.
- Household Products:Concentrate pouch formats trade water weight for shipping efficiency, compressing traditional blow-molded bottle demand where refill infrastructure penetrates fastest.
Procurement concentration sits with food and beverage; margin expansion favors pharmaceuticals.
Form:
Dimensional stability requirements and recycling stream compatibility determine format selection across end-use segments.
- Rigid:Blow-molded and thermoformed containers capture majority value pools where dimensional stability and child-resistance specifications command premium positioning. Pharmaceutical and household product channels favor this format.
- Flexible:Barrier films and pouches represent the steepest expansion trajectory in single-serve food segments. EU Green Deal regulations force elimination of problematic additives that contaminate mechanical recycling streams.
- Semi-Rigid:Intermediate stiffness structures serve dairy and ready-to-drink tea applications where aseptic blow-fill-seal integration cuts logistics costs.
- Blister:Thermoformed cavity packs for pharmaceuticals demand precise solid-state polymerization control to maintain mechanical properties through multiple recycling loops.
Unit economics favor rigid; sustainability positioning favors flexible.
Distribution Channel:
Channel selection determines packaging specification complexity and order fragmentation patterns.
- Retail:Supermarket and hypermarket chains in Germany and France drive refill station penetration, shifting procurement toward durable dispenser designs. Deposit-return schemes create revenue streams from collected flake.
- E-commerce:Direct-to-consumer fulfillment demands optimized dimensional weight ratios, favoring lightweight formats and concentrated formulations that reduce shipping costs.
- Wholesale:Bulk procurement by institutional buyers emphasizes cost-optimized standard specifications over custom barrier enhancements.
- Direct Sales:Brand-owned channels enable premium positioning through custom preform design and mold flexibility rather than tonnage scale.
Volume scale concentrates in retail; margin capture favors direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German converters commanding premium terms on rPET-certified preforms, while Indian fabricators absorb margin compression from BIS compliance costs and import-dependent resin supply.
Germany
Deposit-return schemes and EU Green Deal mandates drive rPET integration at bottling facilities across Bavaria and North Rhine-Westphalia. EFSA process approvals for chemical recycling pathways enable higher food-contact ceilings than mechanical alternatives. The Düsseldorf-Cologne corridor hosts preform technology clusters where lightweighting investments compress gram weights per unit.
United States
Carbonated soft drink bottlers expand lightweight PET adoption to hit scope 3 emissions targets ahead of 2030 deadlines. FDA food-contact notification requirements shape formulation choices for barrier-enhanced multilayer structures. Gulf Coast resin concentration exposes non-captive converters to hurricane disruption risk at integrated PTA-PET complexes.
India
Domestic bottling capacity investments accelerate format transitions in Maharashtra and Gujarat under BIS food-grade certification expansion. FSSAI alignment with BIS standards adds parallel compliance layers for exporters. The Pune-Ahmedabad industrial belt attracts imported preform technology and mold-fabrication partnerships.
Switzerland
Premium cosmetics brands adopt plasma-enhanced silicon oxide coatings to maintain recyclability credentials while extending shelf life. Swissmedic pharmaceutical packaging standards drive demand for barrier-enhanced structures previously reserved for glass. Basel-Zurich supply chains specialize in custom preform design for oxygen-sensitive contents.
China
GB standards for packaging materials and dual carbon goals reshape converter investment priorities in Yangtze River Delta manufacturing networks. MIIT industrial policy accelerates chemical recycling infrastructure deployment. The Shanghai-Ningbo corridor concentrates blown-film extrusion scale for personal care export supply chains.
PET Material Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding upstream margin capture while regional converters compete on mold flexibility and format specialization. The vendor base splits between multinational packaging conglomerates with captive preform manufacturing and mid-cap specialists focused on custom barrier design. Three archetypes dominate: scale-driven resin-integrated multinationals, technology-focused barrier specialists, and geography-bound converters serving regional bottling networks. M&A activity concentrates on chemical recycling asset acquisition, while strategic partnerships target aseptic blow-fill-seal integration for dairy applications.
Among the scale-driven multinationals, Amcor plc exemplifies the resin-integrated archetype through captive preform manufacturing across multiple continents. Berry Global anchors North American positioning through blown-film extrusion scale. Resilux NV occupies a specialist tier focused on custom preform design for premium beverage clients, competing on mold flexibility rather than tonnage throughput.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Gerresheimer AG |
| Silgan Holdings |
| Graham Packaging Company |
| Resilux NV |
| ALPLA Werke Alwin Lehner GmbH and Co KG |
| Plastipak |
| KLöckner Pentaplast |
| Others |
Value Network & Pricing Analysis
EFSA rPET process approvals gate both supply qualification and price differentiation simultaneously, as converters without certified recycling pathways face exclusion from EU food-contact contracts while commanding no premium for virgin-only formulations. This regulatory filter compresses margin structures for non-compliant fabricators and elevates pricing power for certified preform suppliers serving German beverage bottlers.
Pricing Analysis
Customization-premium spreads separate configured-to-order preform pricing from standard catalog offerings by 15-40% depending on mold complexity and barrier specification. Contract-based long-term offtake dominates carbonated beverage supply chains, with price differentiation driven by rPET certification tier and volume scale commitments. Cost compression in standard-grade virgin PET is intensifying because Gulf Coast resin producers pass through paraxylene volatility faster than contract structures allow. Private-label beverage bottlers exhibit highest price sensitivity, while Swiss pharmaceutical brands tolerate premium positioning for oxygen-scavenging multilayer structures.
Supply Chain Analysis
Germany and the United States anchor integrated PTA-PET resin production and captive preform manufacturing for multinational beverage networks. China and India feed raw material dependencies through purified terephthalic acid exports and domestic bottle-grade chip fabrication. Supply chain risk centers on hurricane exposure and freeze-event disruption at Gulf Coast complexes. Distribution runs through converter-direct relationships with bottling facilities, bypassing traditional distributor networks for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage bottler consolidation across North America and Europe is shifting procurement leverage toward fewer buyers with larger contract volumes, compressing converter margin buffers and demanding greater supply security commitments.
For Market Incumbents: Compound barrier technology differentiation through plasma-enhanced coating investments that EVOH multilayer incumbents cannot replicate without asset write-downs. Deepen captive chemical recycling exposure ahead of EFSA pathway approvals that will strand mechanical-only competitors. Prioritize aseptic blow-fill-seal integration for dairy applications where Swiss and German brands seek sterile supply chain consolidation. For New Entrants and Emerging Players: Custom mold-fabrication partnerships for India's BIS-certified food-grade preform demand represent the most penetrable white-space, as domestic bottling capacity investments outpace local technical capability. Target Maharashtra and Gujarat industrial belts with technology licensing arrangements that transfer lightweighting expertise without capital-heavy resin integration. Lead with mold flexibility and format specialization rather than tonnage scale to bypass incumbent cost advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters holding German deposit-return scheme flake collection contracts but lacking chemical recycling upgrade capital. Five-to-ten year viability hinges on EFSA approval velocity for advanced recycling pathways and brand owner rPET content mandates. Watch EFSA novel food process opinion publication timelines as the critical inflection signal for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | EFSA pathway approvals for depolymerization technologies unlock food-contact rPET ceilings unavailable to mechanical recyclers. |
| Aseptic Blow-Fill-Seal Integration | Swiss dairy and ready-to-drink tea brands eliminate intermediate handling costs through sterile forming-filling convergence. |
| Custom Preform Technology Licensing | India's BIS certification expansion creates partnership demand for lightweighting mold expertise in Pune-Ahmedabad corridor. |
| Plasma-Enhanced Barrier Coating Deployment | German premium cosmetics brands maintain recyclability credentials while displacing non-recyclable multilayer EVOH structures. |
| Deposit-Return Scheme Flake Collection Contracts | German and emerging EU member state schemes generate revenue streams that subsidize virgin resin premiums for integrated converters. |
Research Methodology
Operator-level perspectives from preform manufacturing plant managers, beverage bottler procurement leads, resin distribution channel partners, and EFSA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA food-contact notification databases, EFSA scientific opinions on recycling processes, BIS certification registries, and SEC filings of publicly traded packaging conglomerates. Bottom-up volume modeling triangulated against top-down resin consumption estimates from trade associations.
Sensitivity analysis tested forecast outputs against variable rPET integration ceilings, paraxylene price volatility bands, and regulatory approval timeline scenarios across the projection horizon. Segmentation dimensions modeled include packaging format, end-use industry, form rigidity, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for announced capacity investments and mandate-driven substitution effects. Industry-specific inputs incorporated EFSA process approval pipelines and India's BIS certification expansion schedules.
Forecasts assume regulatory continuity in EFSA food-contact evaluations, FDA monomer migration thresholds, and India's BIS-FSSAI alignment frameworks; material policy shifts would require re-modeling. Specific risks include REACH cyclic oligomer limit revisions, Gulf Coast supply disruption events, and chemical recycling pathway rejection. Recalibration cycles align with material shifts in EFSA opinion publication schedules and major bottler scope 3 target announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
China Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Mylar Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Liquid Encapsulation Market