
 Plastic Vials and Ampoules Market | 2026-2036
Plastic Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Vials and Ampoules Market Outlook
Maintenance contracts for cold-chain validation equipment is restructuring how pharmaceutical packaging vendors monetize their customer relationships. Gerresheimer leverages its blow-fill-seal technology leadership to sustain recurring service revenue across European biologic manufacturers. Berry Global anchors North American supply through high-volume polypropylene vial production for generic injectables. Stevanato Group differentiates via integrated glass-to-plastic conversion services that extend its value capture beyond unit sales.
Plastic vials and ampoules are sterile, single-use containers manufactured through injection blow molding or injection stretch blow molding, typically composed of cyclic olefin polymer, polypropylene, or polyethylene terephthalate with wall thickness calibrated to maintain barrier integrity against moisture and oxygen ingress for parenteral drug storage. Their primary purpose is to replace glass in biologic, vaccine, and cytotoxic drug delivery where breakage risk and weight reduction drive conversion. Polypropylene dominates material selection for its thermal stability during autoclave sterilization, while PET gains traction in diagnostic reagent applications requiring optical clarity. Flip-off closures command the largest closure-type position due to universal compatibility with aluminum overseals in aseptic filling lines, though tamper-evident designs are gaining fastest in retail pharmacy channels where diversion control has intensified.
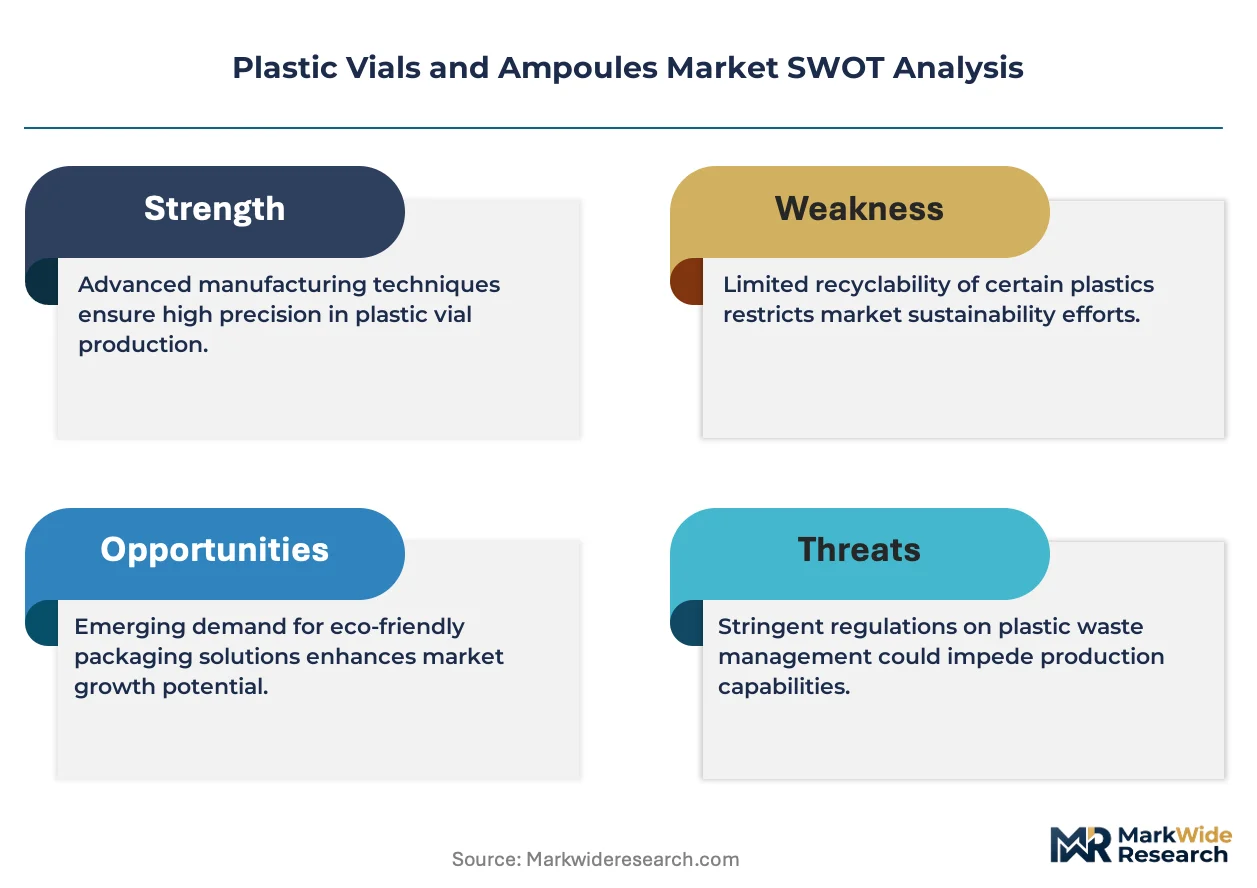
FDA's Drug Supply Chain Security Act and EU MDR traceability requirements are forcing serialization upgrades across plastic container production lines, raising capital barriers for mid-tier converters while creating compliance-driven demand for pre-validated packaging systems. ISO 15378 and USP Class VI testing standards govern material biocompatibility, with FDA Type III drug master file submissions now expected for new resin qualifications in parenteral applications. Stakeholders must monitor how EMA's evolving guidelines on extractables and leachables for plastic primary containers reshape resin selection criteria ahead of biologics license application reviews.
Market Dynamics
Biologic drug manufacturers are forcing a material conversion wave from glass to polymer primary containers, driven by breakage elimination needs and cold-chain weight reduction targets that reshape converter capacity planning.
Growth Catalysts
- EU MDR serialization mandates:Traceability requirements for sterile plastic containers are accelerating pre-validated packaging system procurement among contract manufacturing organizations.
- Cyclic olefin polymer adoption:Biologic drug packaging lines specify this material for its moisture barrier performance during lyophilized product storage.
- Rhine-Main pharmaceutical cluster concentration:German biologics manufacturers anchor European demand for blow-fill-seal capacity expansion.
Market Restraints
- Resin qualification costs:FDA Type III drug master file submission requirements for new parenteral resin grades create capital barriers for mid-tier converters.
- Autoclave compatibility limits:Polyethylene terephthalate thermal instability restricts its penetration in terminal sterilization applications.
- Extractables testing burden:EMA evolving guidelines on leachables for plastic primary containers extend biologics license application timelines.
Strategic Opportunities
- Diagnostic reagent optical clarity demand:PET vials capture share in laboratory consumables where visual inspection protocols require transparency.
- Retail pharmacy diversion control:Tamper-evident closure designs penetrate pharmacy channels where counterfeit interception has intensified.
- Maintenance contract monetization:Cold-chain validation equipment service agreements convert unit sales into recurring revenue streams.
Industry Challenges
- Blow-fill-seal technician scarcity:Aseptic processing specialization shortages constrain European converter capacity expansion timelines.
- Serialization line retrofit capex:FDA Drug Supply Chain Security Act compliance forces mid-volume manufacturers into multi-year capital deployment cycles.
- Glass-to-plastic conversion validation:USP Class VI biocompatibility retesting requirements delay generic injectable container substitution programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Vials and Ampoules Market |
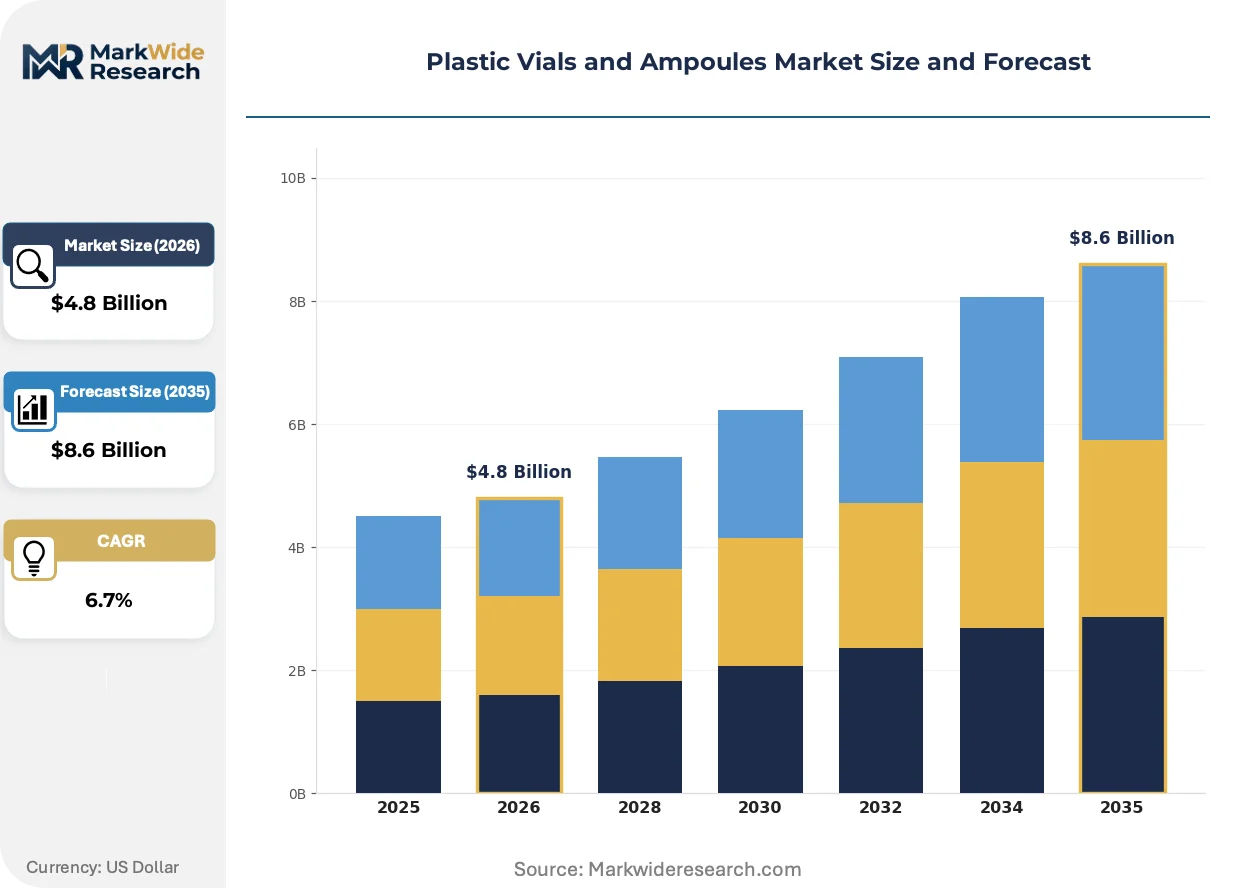
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polypropylene, Polyethylene, PVC, PET Closure Type: Flip Off, Push On, Screw Cap, Tamper Evident End User: Pharmaceuticals, Biotechnology, Healthcare, Research Labs Size: 1 mL, 5 mL, 10 mL, 20 mL |
| Companies Covered | Gerresheimer, Schott AG, SGD Pharma, Nipro Corporation, West Pharmaceutical Services, Berry Global, Stevanato Group, Amcor Plc, Origin Pharma Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Vials and Ampoules Market Strategic Shifts
Container closure integrity testing automation and polymer barrier engineering are compressing development cycles for parenteral packaging, while regulatory serialization deadlines force line architecture redesigns across sterile manufacturing.
Multi-layer co-injection molding is modularizing how converters configure oxygen and moisture barrier properties without resin substitution. Biologics manufacturers in Germany and Switzerland specify these structures for protein stability during extended shelf life. The technology is modularizing converter service offerings from commodity supply toward customized barrier engineering partnerships.
EMA extractables and leachables guidelines for plastic primary containers are tightening ahead of biologics license application reviews. This policy shift forces resin suppliers into expanded characterization studies and toxicological risk assessments. Cyclic olefin polymer grades with pre-submitted drug master files capture preference among European contract manufacturing organizations facing compressed approval timelines.
After-sales service unbundling from equipment procurement is restructuring converter customer relationships. Cold-chain validation maintenance contracts now generate recurring revenue independent of unit volume for blow-fill-seal technology providers. This pattern concentrates among North American generic injectable manufacturers seeking operational expenditure predictability over capital deployment cycles.
Plastic Vials and Ampoules Market Segmentation
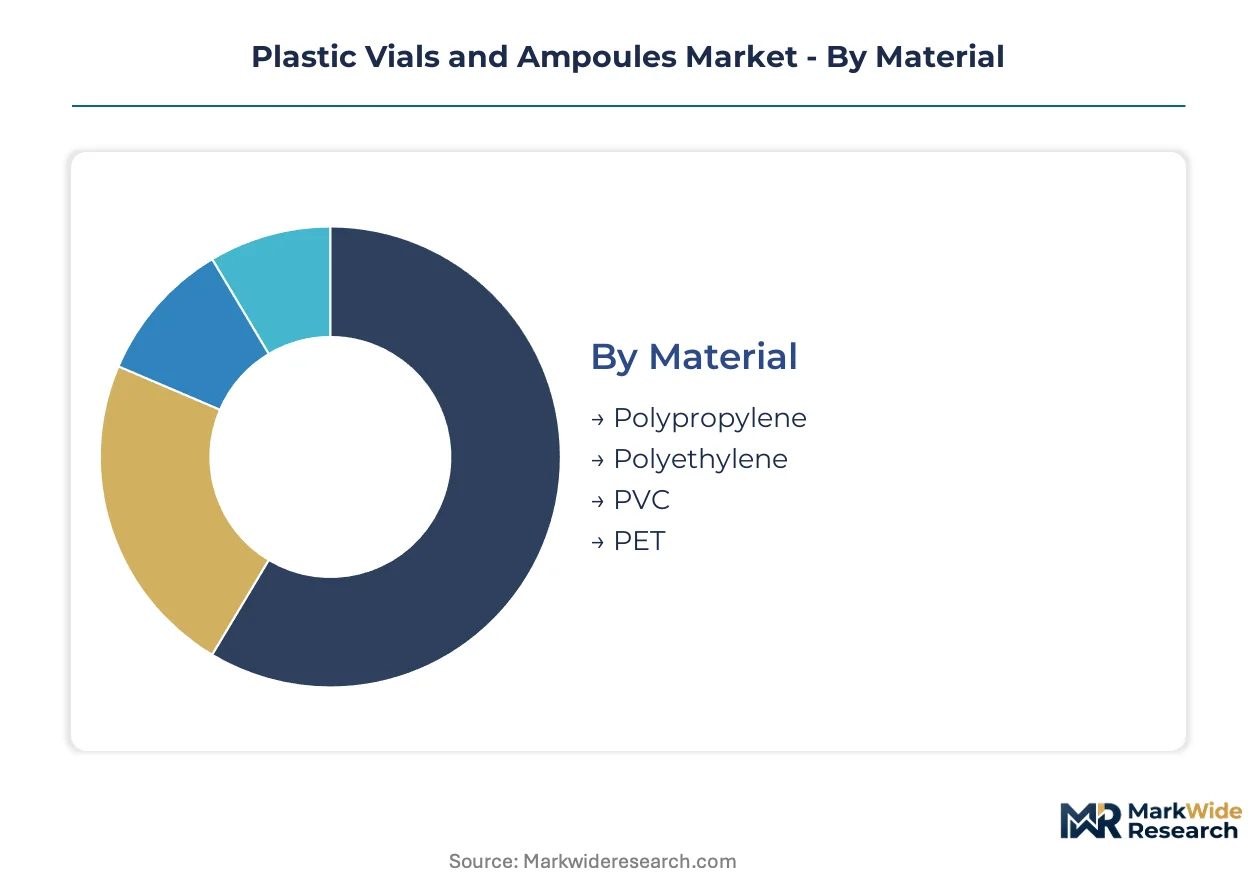
Material chemistry and closure integrity specifications determine barrier performance against moisture ingress and oxygen permeation in parenteral drug storage. Segmentation reveals how resin thermal stability and closure compatibility with aseptic filling lines reshape procurement decisions across biologics manufacturers.
Material:
Polymer selection pivots on autoclave sterilization tolerance and extractables profiles under EMA evolving guidelines.
- Polypropylene:Cyclic olefin polymer variants dominate terminal sterilization applications for biologic drug packaging. German biologics manufacturers in the Rhine-Main cluster specify this material for lyophilized product stability during extended shelf life.
- PET:Injection stretch blow molding yields optical clarity essential for diagnostic reagent visual inspection protocols. Laboratory consumables procurement in North America favors PET vials where transparency supports quality control automation.
- Polyethylene:Lower thermal stability restricts penetration in autoclave sterilization workflows but captures cost-sensitive generic injectable segments.
- PVC:Plasticizer migration concerns constrain parenteral adoption; residual presence limited to non-injectable diagnostic applications.
Polypropylene leads on scale; PET leads on momentum.
Closure Type:
Compatibility with aluminum overseals and aseptic filling line automation drives specification divergence across pharmaceutical packaging procurement.
- Flip Off:Universal aluminum overseal compatibility makes this the default for high-speed aseptic filling operations. Contract manufacturing organizations in Europe standardize on flip-off designs to minimize line changeover downtime.
- Tamper Evident:Retail pharmacy diversion control requirements accelerate adoption where counterfeit interception has intensified. North American pharmacy channels specify these closures for controlled substance packaging.
- Push On:Rapid application suits diagnostic reagent kits requiring frequent access without specialized removal tools.
- Screw Cap:Reclosure functionality captures research laboratory segments where multi-dose protocols predominate.
Flip Off dominates installed base; Tamper Evident climbs the fastest on regulatory pressure.
End User:
Application-specific barrier requirements and validation burden intensity segment value capture opportunities.
- Pharmaceuticals:Generic injectable manufacturers drive high-volume polypropylene vial demand with standardized USP Class VI validation requirements.
- Biotechnology:Protein stability demands concentrate procurement toward cyclic olefin polymer with pre-submitted FDA Type III drug master files.
- Healthcare:Hospital pharmacy compounding operations prioritize break-resistant polymer containers for cytotoxic drug handling.
- Research Labs:Small-lot flexibility and optical clarity requirements favor PET vials in analytical chemistry applications.
Pharmaceuticals anchor volume; Biotechnology commands premium positioning.
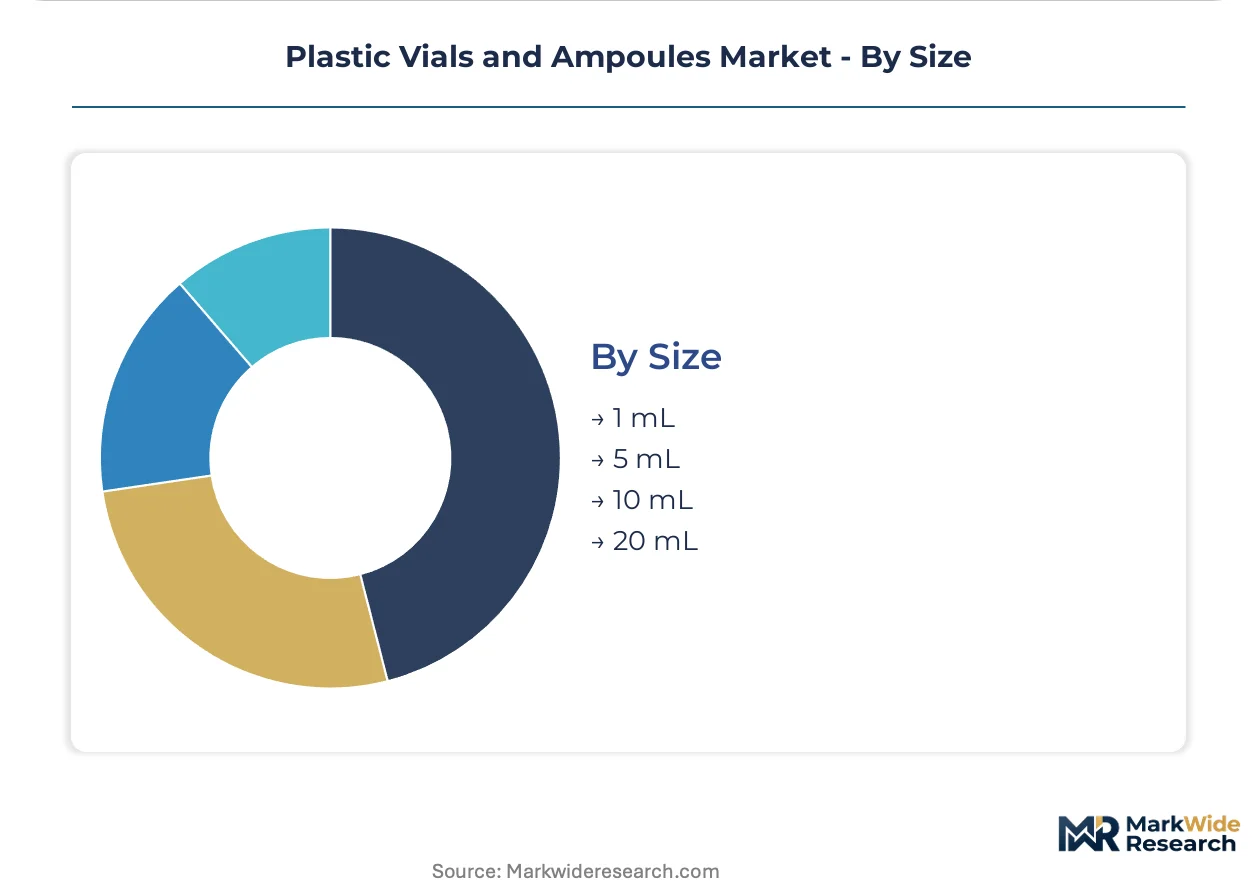
Size:
Fill volume alignment with dose concentration and cold-chain logistics efficiency shapes converter capacity allocation.
- 10 mL:Standard biologic dose volumes concentrate demand for blow-fill-seal capacity expansion in European contract manufacturing.
- 5 mL:Pediatric and geriatric dose fractionation drives specification in vaccine packaging where multi-dose vial conservation matters.
- 1 mL:High-potency biologics and ophthalmic preparations require precise fill accuracy in specialized aseptic processing lines.
- 20 mL:Diagnostic reagent bulk packaging and veterinary applications sustain niche converter utilization.
10 mL captures the largest production share; 5 mL gains share fastest on dose optimization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates blow-fill-seal capacity expansion for biologics packaging, while the United States drives generic injectable polypropylene demand through high-volume contract manufacturing. Switzerland and Japan anchor premium cyclic olefin polymer adoption for protein stability applications. India's CDSCO regulatory alignment is accelerating local converter qualification for export-oriented pharmaceutical packaging.
Germany
Rhine-Main pharmaceutical cluster biologics manufacturers specify cyclic olefin polymer for lyophilized product stability. EU MDR serialization mandates force pre-validated packaging system procurement among contract manufacturing organizations. Frankfurt-Mainz corridor blow-fill-seal capacity expansion targets cold-chain weight reduction for mRNA vaccine distribution.
United States
Generic injectable manufacturers drive high-volume polypropylene vial consumption through standardized USP Class VI validation. FDA Drug Supply Chain Security Act compliance forces serialization line retrofits across mid-volume converter operations. New Jersey-Pennsylvania pharmaceutical corridor concentrates blow-fill-seal maintenance contract monetization for operational expenditure predictability.
Switzerland
Basel-area biologics manufacturers prioritize cyclic olefin polymer grades with pre-submitted FDA Type III drug master files. Swissmedic extractables and leachables guidelines tighten ahead of biologics license application reviews. Lake Geneva region contract manufacturing organizations specify multi-layer co-injection molding for oxygen barrier customization.
Japan
PMDA serialization requirements align with FDA traceability standards for export-oriented parenteral packaging. Osaka-Tokyo pharmaceutical belt biologics manufacturers specify polymer containers for breakage elimination in automated filling lines. Kansai region converter capacity targets PET diagnostic reagent vials for laboratory consumables optical clarity.
India
CDSCO harmonization with USP Class VI and ISO 15378 standards accelerates resin qualification for export contract manufacturing. Maharashtra-Gujarat pharmaceutical clusters expand polypropylene vial production for generic injectable export markets. Hyderabad-Bengaluru biotech corridor demand concentrates on pre-validated packaging systems for biosimilar license applications.
Plastic Vials and Ampoules Market Competitive Environment
Top-tier vendors anchor integrated packaging system supply, while mid-tier converters compete on resin qualification speed and regional logistics proximity. Market structure tilts toward consolidation around blow-fill-seal technology holders and multi-material platform operators. Three archetypes dominate: integrated glass-to-plastic converters, high-volume commodity resin specialists, and barrier engineering technology licensors. Capacity expansion in European biologics corridors and strategic partnerships for serialization compliance represent the dominant competitive vectors.
Within the integrated packaging tier, Gerresheimer and Stevanato Group exemplify technology-led positioning through blow-fill-seal platform control and glass-to-plastic conversion service bundling. Berry Global occupies a scale-driven position in North American polypropylene vial supply for generic injectables. These three entities represent contrasting archetypes: European technology integration, North American volume manufacturing, and multi-material platform diversification.
| Leading Market Players |
|---|
| Gerresheimer |
| Schott AG |
| SGD Pharma |
| Nipro Corporation |
| West Pharmaceutical Services |
| Berry Global |
| Stevanato Group |
| Amcor Plc |
| Origin Pharma Packaging |
| Others |
Value Chain & Pricing Dynamics
Cyclic olefin polymer resin spot indices in Northwest Europe cascade through converter pricing tiers, compressing margins for mid-tier blow-fill-seal operators while premium multi-layer co-injection molding commands certification-linked premiums. German biologics manufacturers absorb these input fluctuations through long-term offtake agreements that lock in barrier-grade resin supply.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard polypropylene vials used in generic injectables. Three-tier pricing structure across premium cyclic olefin polymer, standard polypropylene, and economy polyethylene grades separates biologics applications from commodity diagnostics. Cost compression in the standard tier intensifies as Indian converters scale FDA Type III drug master file submissions. Generic injectable manufacturers exhibit highest price sensitivity; biotechnology firms prioritize barrier performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical clusters are reshaping sourcing patterns for export-oriented contract manufacturing organizations. Raw material supply concentrates in Germany, the United States, and China for resin compounding and precision molding equipment. Converter operations draw from cyclic olefin polymer feedstocks, aluminum closure components, and serialization-ready labeling systems. Single-source vulnerability around blow-fill-seal machinery spare parts constrains European capacity expansion timelines. Distribution runs through pharmaceutical corridor logistics hubs serving Rhine-Main, New Jersey-Pennsylvania, and Hyderabad-Bengaluru manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic vials and ampoules market functions as a stable compounder anchored by irreversible biologic drug conversion from glass to polymer primary containers. Regulatory serialization mandates create recurring compliance expenditure that sustains incumbent revenue predictability.
For Market Incumbents: To counter resin qualification cost barriers erected by FDA Type III drug master file requirements, leading converters should deepen backward integration into cyclic olefin polymer compounding and expand maintenance contract monetization for cold-chain validation equipment. Certification investment in pre-validated packaging systems captures procurement preference among European contract manufacturing organizations facing compressed biologics license application timelines. For New Entrants and Emerging Players: Capture diagnostic reagent PET vial demand in North American laboratory consumables where optical clarity requirements and lower regulatory validation burdens enable faster market entry. Target India's CDSCO-aligned export contract manufacturing corridor for polypropylene generic injectable supply. Partner with established serialization technology providers to bypass multi-year capital deployment cycles for FDA Drug Supply Chain Security Act compliance. For Investors and Strategic Acquirers: Asymmetric upside sits with multi-material platform operators possessing both glass-to-plastic conversion capabilities and blow-fill-seal technology licensing positions. Long-term viability rests on biologics pipeline expansion rather than cyclical generic injectable volume. Watch EMA extractables and leachables guideline tightening as the inflection trigger that accelerates preference toward pre-qualified resin grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Cyclic olefin polymer captive supply secures margin control against spot price volatility. |
| Pre-Validated Packaging System Certification | FDA Type III drug master file submission accelerates European biologics license approvals. |
| Maintenance Contract Monetization | Cold-chain validation service agreements convert unit sales into recurring revenue streams. |
| Multi-Layer Co-Injection Molding Partnership | Oxygen barrier customization captures Swiss biologics manufacturer specification preference. |
| Serialization Line Architecture Redesign | EU MDR traceability compliance creates compliance-driven demand for integrated packaging systems. |
Study Parameters
Bottom-up pharmaceutical packaging procurement modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with blow-fill-seal operations directors, regulatory affairs leads at contract manufacturing organizations, hospital pharmacy procurement managers, and diagnostic reagent kit developers combined with secondary validation from FDA drug master file submissions, EMA marketing authorization databases, USP monograph updates, and ISO 15378 certification registries. Triangulation across these sources ensures demand-side consumption patterns align with supply-side utilization rates.
Historical trendline analysis of material substitution cycles and serialization compliance investment waves informs the projection framework. Segmentation modeling spans material chemistry, closure type, end-use application, and regional regulatory cluster dimensions across the analysis window. CAGRs derive from capacity expansion announcements, resin qualification timelines, and biologics pipeline advancement rates. Forecast inputs incorporate blow-fill-seal technician availability constraints and EMA extractables guideline evolution.
Raw material price volatility, regulatory timeline compression, and biologics pipeline attrition are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about resin substitution velocity and serialization compliance deadlines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market