
 VCI Packaging Market | 2026-2036
VCI Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
VCI Packaging Market Analytics
Specialized polymer chemists and corrosion-engineering talent is rotating toward VCI formulation houses as metal-finishing customers demand application-specific protection protocols. Cortec Corporation leverages its in-house corrosion-research laboratories to sustain proprietary amine-carboxylate chemistry portfolios. Daubert Cromwell anchors North American automotive supply chains through captive VCI film extrusion and custom-blend capabilities.
VCI packaging denotes flexible or rigid materials impregnated with volatile corrosion inhibitors that sublime at ambient temperatures to form molecular adsorption layers on ferrous and non-ferrous metal surfaces, typically delivering 6–24 months of protection without oils or greases. The primary industrial purpose centers on eliminating post-manufacturing rust during intercontinental shipping and long-cycle inventory storage. Films and bags occupy the dominant share of product-type value as unit-dose convenience aligns with automated packaging lines in automotive and electronics sectors. Bioplastics within the material dimension represent the fastest-growing structural pocket, though polyethylene still commands volume leadership due to cost parity and established recycling infrastructure.
EPA oversight of volatile organic compound emissions shapes VCI formulation choices in the United States, while REACH registration requirements in Europe restrict certain traditional nitrite-based chemistries. OSHA workplace-exposure thresholds further constrain manufacturing processes, creating compliance-driven R&D investment cycles. Stakeholders must monitor evolving state-level extended producer responsibility laws and bioplastic certification standards to anticipate raw-material qualification timelines and capital-planning horizons.
Market Dynamics
Automotive OEMs now mandate corrosion-protection protocols spanning 18-month supply cycles, forcing VCI formulators to engineer chemistries that withstand multi-modal transits through humidity-variable climates without residue or re-work.
Growth Catalysts
- REACH Phase-Out of Nitrite-Based Inhibitors:ECHA restrictions on traditional chemistries accelerate converter migration toward amine-carboxylate and plant-derived alternatives, creating qualification demand for compliant film extruders.
- Extended Automotive Supply Chains:Tier suppliers shipping precision-machined powertrain components from Central European clusters to Mexican assembly plants require VCI films rated for 24-month protection cycles.
- Bioplastic Feedstock Integration:PLA and PHA resin advances enable VCI masterbatch compatibility with compostable substrates, opening certification pathways under EU packaging waste directives.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene resin prices tied to naphtha cracking economics compress converter margins and destabilize annual contract pricing with automotive procurement teams.
- Concentrated VCI Active Ingredient Supply:Three specialty chemical houses control global benzotriazole and tolyltriazole production, creating single-source vulnerability for regional film extruders.
- Performance Validation Timelines:ASTM B117 salt-spray and MIL-STD-3010 cyclic humidity testing protocols require 90-180 day qualification cycles that delay new formulation commercialization.
Strategic Opportunities
- Indian Export Manufacturing Expansion:Pune and Chennai metalworking clusters serving European automotive OEMs lack indigenous VCI film capacity, creating local production incentives under PLI scheme provisions.
- Electronics Cold-Chain Integration:Semiconductor capital equipment manufacturers now specify VCI protection for ion-implanter components during refrigerated ocean freight, merging corrosion inhibition with thermal packaging.
- Digital Inventory Tracking Convergence:RFID-embedded VCI films enable real-time humidity exposure logging, allowing predictive replacement scheduling in aerospace MRO operations.
Industry Challenges
- Polymer-Chemistry Hybrid Talent Scarcity:Formulation houses struggle to recruit professionals conversant in both corrosion electrochemistry and blown-film extrusion process control.
- Recyclability Certification Complexity:Multi-layer VCI laminates containing EVOH barrier layers and desiccant pockets fail mechanical recycling streams, forcing converters to navigate fragmented extended producer responsibility schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCI Packaging Market |
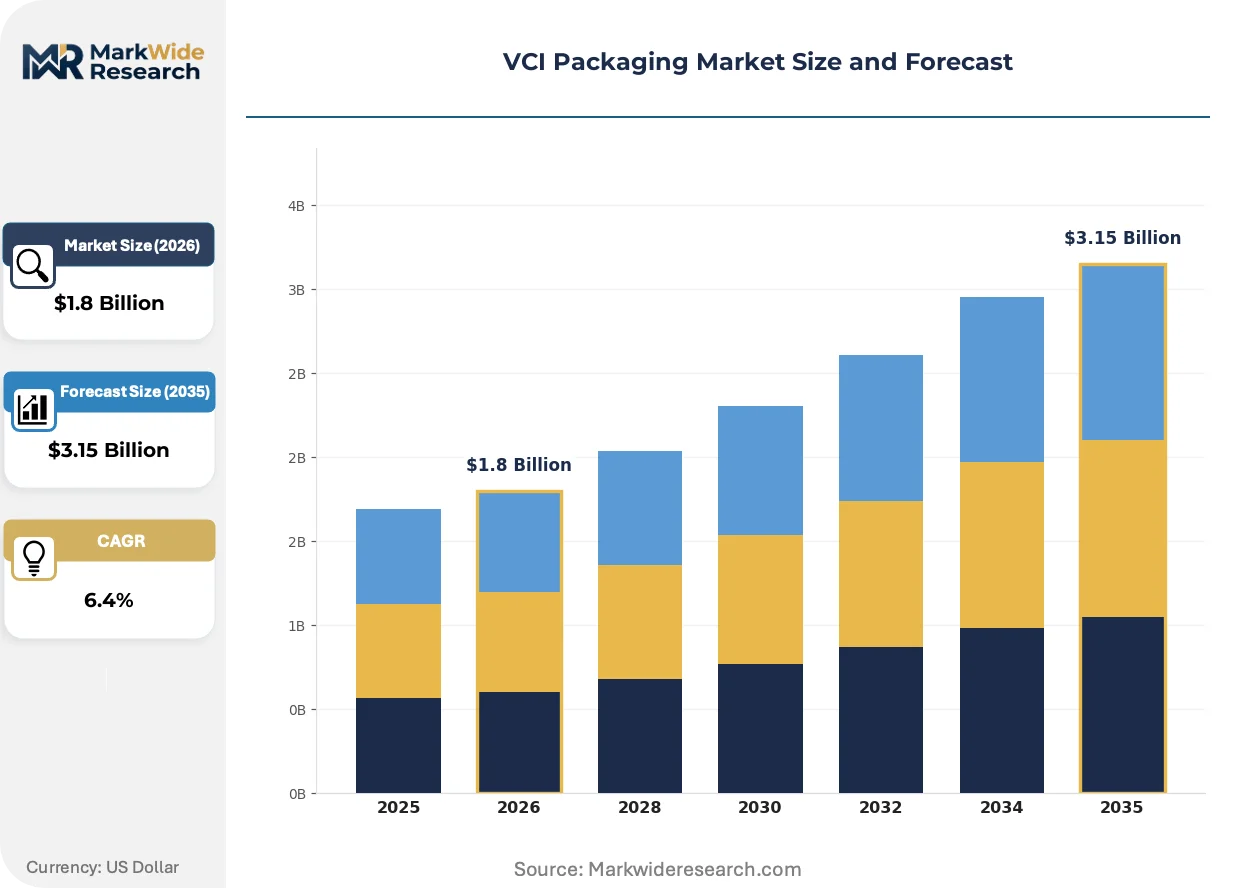
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Bags, Papers, Emitters End User: Aerospace, Automotive, Electronics, Manufacturing Material: Polyethylene, Paper, Aluminum, Bioplastics Application: Corrosion Prevention, Shipping, Storage, Maintenance |
| Companies Covered | Ströbel GmbH, Armor Protective Packaging, Cortec Corporation, TPC Packaging Solutions, Protective Packaging Corporation, Intertape Polymer Group, Rust-X, Daubert VCI, Daubert Cromwell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCI Packaging Market Evolving Landscape
Active packaging intelligence and substrate sustainability are converging to redefine value capture in corrosion protection, with chemistry performance now inseparable from end-of-life credentials and supply chain traceability.
Multilayer coextrusion technology with nanoscale VCI dispersion is miniaturizing inhibitor particle distribution to sub-micron levels, enabling thinner gauge films without protection degradation. Automotive electronics suppliers in Germany and Japan have adopted 25-micron specifications for printed circuit board pouch applications. This gauge compression is miniaturizing material throughput per protected unit by 30-40% versus legacy 75-micron constructions, directly attacking polyethylene consumption intensity.
EPA Method 24 VOC testing protocols and state-level air quality management district rules are tightening emission thresholds for VCI formulation facilities in California and Texas. Converters face capital decisions on solvent recovery systems versus aqueous coating line conversions. The regulatory pressure is accelerating water-based VCI lacquer adoption in North American metal-stamping supply chains, particularly for coil-wrap applications serving appliance manufacturers.
Consignment inventory arrangements are displacing spot purchasing for high-volume automotive tier suppliers, with VCI film vendors maintaining buffer stock at customer logistics hubs and billing only upon consumption. This model transfers working capital burden upstream while locking in volume commitments. The shift is most pronounced in Just-in-Sequence supply chains serving BMW and Mercedes-Benz assembly plants in Bavaria and Baden-Württemberg, where production volatility demands flexible consumption patterns without procurement friction.
VCI Packaging Market Segmentation
VCI packaging segmentation reflects divergent technical requirements across corrosion-protection protocols, with each dimension carrying distinct regulatory footprints and qualification barriers. Understanding these structural divisions enables targeted positioning against specific compliance burdens and performance specifications.
Product Type:
EPA Method 24 VOC testing and REACH substance restrictions create divergent formulation pathways across physical formats, with film extruders facing distinct emission thresholds versus paper coating operations.
- Films:Multilayer coextrusions with nanoscale VCI dispersion enable 25-micron gauge specifications for printed circuit board applications in German and Japanese automotive electronics supply chains. German Mittelstand metalworking clusters and export-heavy Bavarian automotive production anchor volume demand for 75-micron legacy constructions rated for 24-month protection cycles.
- Bags:Unit-dose pouch configurations align with automated packaging lines in Just-in-Sequence supply chains serving BMW and Mercedes-Benz assembly operations, with consignment inventory arrangements transferring working capital burden upstream to converters.
- Papers:Kraft-based substrates with aqueous VCI coatings serve coil-wrap applications in North American metal-stamping supply chains, particularly for appliance manufacturers facing EPA air quality management district rules in California and Texas.
- Emitters:Compact sachet and foam formats protect void spaces in aerospace MRO operations and semiconductor capital equipment shipments, with RFID-embedded variants enabling real-time humidity exposure logging.
Established volume favors Films; emerging adoption favors Emitters with digital tracking integration.
End User:
Customer procurement patterns range from spot purchasing to consignment arrangements, with automotive tier suppliers demanding 18-month protection warranties and electronics manufacturers specifying residue-free protocols.
- Automotive:Tier suppliers shipping precision-machined powertrain components from Central European clusters to Mexican assembly plants mandate VCI films rated for extended humidity-variable transits without re-work requirements.
- Aerospace:MRO operations in Germany and the United States specify predictive replacement scheduling through RFID-embedded films, with maintenance protocols governed by MIL-STD-3010 cyclic humidity testing standards.
- Electronics:Semiconductor capital equipment manufacturers now require VCI protection for ion-implanter components during refrigerated ocean freight, merging corrosion inhibition with thermal packaging specifications.
- Manufacturing:General metalworking operations in Pune and Chennai serving European automotive OEMs lack indigenous VCI film capacity, creating local production incentives under India's PLI scheme provisions.
Procurement concentration sits with Automotive; steepest expansion trajectory belongs to Electronics cold-chain integration.
Material:
Feedstock selection determines recyclability certification pathways and extended producer responsibility obligations, with bioplastic compatibility opening EU packaging waste directive compliance routes.
- Polyethylene:Naphtha-crack economics drive resin price volatility that compresses converter margins and destabilizes annual contract pricing with automotive procurement teams, though established mechanical recycling infrastructure sustains volume leadership.
- Bioplastics:PLA and PHA resin advances enable VCI masterbatch compatibility with compostable substrates, with qualification timelines accelerating under EU Green Deal packaging waste directives.
- Paper:Aqueous coating line conversions dominate North American metal-stamping supply chains as converters face capital decisions on solvent recovery systems versus water-based lacquer adoption.
- Aluminum:Foil-laminate constructions with EVOH barrier layers serve high-value aerospace and semiconductor applications, though multi-layer configurations fail mechanical recycling streams and force navigation of fragmented extended producer responsibility schemes.
Cost parity sustains Polyethylene dominance; regulatory pressure is climbing fastest for Bioplastics certification.
Application:
Performance validation timelines stretch from 90-day salt-spray protocols to 180-day cyclic humidity cycles, with each use case imposing distinct ASTM B117 and MIL-STD-3010 qualification burdens.
- Corrosion Prevention:Molecular adsorption layer formation on ferrous and non-ferrous surfaces delivers 6–24 month protection without oils or greases, eliminating post-manufacturing rust during intercontinental shipping.
- Shipping:Multi-modal transits through humidity-variable climates demand VCI chemistries that withstand 18-month supply cycles without residue or re-work, particularly for Central European-to-Mexican automotive component flows.
- Storage:Long-cycle inventory protection in German Mittelstand metalworking clusters requires stable sublimation rates across ambient temperature variations.
- Maintenance:Aerospace MRO operations leverage predictive replacement scheduling through humidity exposure logging, with RFID-embedded films enabling real-time condition monitoring.
Contract volume concentrates in Shipping; technology convergence favors Maintenance with digital inventory tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance frameworks anchor European formulation standards, while EPA air quality rules and India's PLI manufacturing incentives shape parallel development corridors across three continents.
Germany
Bavarian automotive electronics clusters and Mittelstand metalworking operations in Baden-Württemberg drive precision-component protection demand. REACH Phase-Out of nitrite-based inhibitors forces converters toward amine-carboxylate chemistries. Stuttgart and Munich anchor 24-month rated VCI film procurement for BMW and Mercedes-Benz Just-in-Sequence supply chains.
United States
Texas and California metal-stamping operations face EPA Method 24 VOC emission thresholds that accelerate aqueous coating line conversions. OSHA workplace-exposure constraints further restrict manufacturing processes. Houston and Los Angeles logistics hubs concentrate consignment inventory arrangements for automotive tier suppliers.
India
Pune and Chennai metalworking clusters serving European automotive OEMs lack indigenous VCI film capacity, creating local production incentives. PLI scheme provisions support domestic manufacturing scale-up. Maharashtra and Tamil Nadu export corridors drive qualification demand for 18-month protection protocols.
China
Yangtze River Delta precision machining operations supply semiconductor capital equipment manufacturers requiring cold-chain VCI integration. MEE environmental standards tighten volatile organic compound oversight. Shanghai and Suzhou clusters merge corrosion inhibition with thermal packaging specifications for ion-implanter components.
Japan
Kansai region automotive electronics suppliers adopt 25-micron gauge specifications for printed circuit board pouch applications. METI industrial standards govern sublimation rate stability across ambient temperature variations. Osaka and Nagoya manufacturing bases miniaturize material throughput per protected unit by 30-40% versus legacy constructions.
VCI Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with chemistry houses controlling active ingredient supply and regional extruders competing on formulation customization and logistics proximity. The market structure concentrates around proprietary amine-carboxylate portfolios and captive film extrusion capabilities. Two strategic archetypes dominate: integrated corrosion-research laboratories with in-house masterbatch development, and regional converters leveraging custom-blend flexibility for automotive procurement teams. Competitive moves center on bioplastic substrate certification and RFID-embedded film development for predictive maintenance applications.
Within the integrated research tier, Cortec Corporation and Daubert Cromwell exemplify archetypes combining proprietary chemistry portfolios with captive manufacturing capabilities. Armor Protective Packaging and Protective Packaging Corporation occupy positions among North American specialty converters serving metal-stamping and appliance manufacturing supply chains. Ströbel GmbH anchors European formulation expertise with German Mittelstand customer proximity.
| Leading Market Players |
|---|
| Ströbel GmbH |
| Armor Protective Packaging |
| Cortec Corporation |
| TPC Packaging Solutions |
| Protective Packaging Corporation |
| Intertape Polymer Group |
| Rust-X |
| Daubert VCI |
| Daubert Cromwell |
| Others |
Value Network & Pricing Analysis
Amine-carboxylate chemistry substitution for legacy nitrite-based formulations simultaneously redistributes manufacturing capacity toward REACH-compliant extrusion hubs in Germany and compresses formulation cost structures as specialty chemical houses consolidate active ingredient supply. This dual displacement concentrates pricing power among three benzotriazole producers while forcing regional converters to absorb qualification-driven margin erosion.
Pricing Analysis
Price spreads between German automotive-grade VCI films and North American metal-stamping alternatives reflect divergent regulatory compliance burdens and certification timelines. Three-tier pricing structure across premium amine-carboxylate, standard hybrid, and economy nitrite-legacy tiers differentiates based on REACH certification status and automotive OEM qualification depth. Pricing pressure stems from polyethylene resin volatility tied to naphtha cracking economics, with spot purchasing tier suppliers exhibiting highest price sensitivity versus consignment-arranged BMW and Mercedes-Benz procurement teams.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability across Central European-to-Mexican automotive component trade lanes. Supply concentrates in Germany, the United States, and China, with active ingredient production anchored in German and Chinese specialty chemical clusters. Raw material dependencies encompass benzotriazole corrosion inhibitors, polyethylene resins, and PLA bioplastic feedstocks. Single-source vulnerability pervades benzotriazole and tolyltriazole procurement. Distribution runs through consignment inventory arrangements at Bavarian and Baden-Württemberg logistics hubs serving Just-in-Sequence automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation around extended 18-month protection warranties has shifted negotiating leverage toward tier supplier networks, fragmenting individual converter pricing power across dispersed metalworking clusters.
For Market Incumbents: Shield proprietary amine-carboxylate portfolios through captive corrosion-research laboratory investment and accelerate bioplastic substrate certification under EU packaging waste directives. ECHA REACH Phase-Out timelines threaten nitrite-legacy revenue streams. Backward integration into PLA resin masterbatch development secures feedstock qualification timelines. For New Entrants and Emerging Players: EU Green Deal packaging waste directive fast-track certification opens white-space penetration in Pune and Chennai metalworking clusters lacking indigenous VCI film capacity. India's PLI scheme provisions reduce capital barriers for domestic extrusion scale-up. Target semiconductor capital equipment cold-chain integration as the most penetrable application segment, leveraging aqueous coating line conversions for EPA-compliant North American market entry. For Investors and Strategic Acquirers: ECHA REACH Phase-Out of nitrite-based inhibitors reshapes the acquisition landscape toward amine-carboxylate chemistry houses with captive film extrusion capabilities. Long-term viability centers on formulation-customization proximity to automotive Just-in-Sequence supply chains. Monitor bioplastic certification completion rates as the primary inflection signal for substrate transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Cortec Corporation's captive amine-carboxylate production insulates against benzotriazole supply concentration. |
| Bioplastic Substrate Certification | PLA and PHA compatibility unlocks EU Green Deal compliance routes for German automotive electronics suppliers. |
| RFID-Embedded Film Development | Real-time humidity logging enables predictive replacement scheduling in German aerospace MRO operations. |
| Consignment Inventory Arrangement Expansion | Buffer stock positioning at Bavarian logistics hubs locks BMW and Mercedes-Benz volume commitments. |
| Aqueous Coating Line Conversion | Water-based VCI lacquer adoption satisfies EPA Method 24 thresholds in California and Texas metal-stamping corridors. |
Research Methodology
A standing panel of VCI formulation chemists, blown-film extrusion process engineers, automotive tier supplier procurement directors, and aerospace MRO maintenance planners provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH substance registrations, EPA Method 24 VOC test protocols, EU packaging waste directive drafts, and German automotive production databases. Bottom-up segment sizing triangulated against top-down polymer consumption estimates from European Plastics Association and American Chemistry Council trade disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material substrate, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators and industry-specific inputs including automotive production forecasts and semiconductor capital equipment shipment patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH Phase-Out implementation timelines and stable automotive Just-in-Sequence supply chain configurations; material deviation would warrant model refresh. Specific risk factors encompass polyethylene resin price volatility, bioplastic feedstock qualification delays, and extended automotive supply chain restructuring. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Book Wraps Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
EPE Liner Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Aerosol Packaging Market