
 Cosmetic and Toiletry Containers Market | 2026-2036
Cosmetic and Toiletry Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic and Toiletry Containers Market Outlook
The EU Green Deal is recalibrating procurement criteria across European beauty supply chains, forcing container suppliers to certify recycled content thresholds and carbon footprints. Albea leverages its integrated tube and dispensing portfolio to secure multi-year contracts with brands pursuing plastic reduction pledges. Gerresheimer anchors premium glass demand through specialized molding capabilities for fragrance and skincare houses. Berry Global competes aggressively in North American personal care through scale manufacturing of HDPE and PET bottles with post-consumer recycled integration.
Cosmetic and toiletry containers encompass primary and secondary packaging vessels engineered from materials including polyethylene terephthalate, borosilicate glass, aluminum alloys, and molded fiber composites, manufactured through blow molding, injection stretch blow molding, or tubular glass forming to preserve product integrity, enable controlled dispensing, and communicate brand positioning at point of sale. Plastic bottles and jars sustain the largest volume share across mass-market hair care and body wash segments, though glass jars command premium positioning in facial skincare where perceived quality and chemical compatibility justify higher unit costs. Pump closures are displacing traditional screw caps in liquid foundation and serum categories as brands prioritize dosing precision and contamination prevention.
FDA cosmetic labeling requirements and the EU Packaging and Packaging Waste Regulation jointly constrain material choices and mandate recyclability disclosures, while REACH chemical restrictions limit certain additives in colorants and coatings applied to container surfaces. China's GB standards for cosmetic packaging safety and Japan's METI recycling guidelines add compliance layers for suppliers serving multinational brand portfolios. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material design standards to anticipate which container formats will retain market access across major economies.
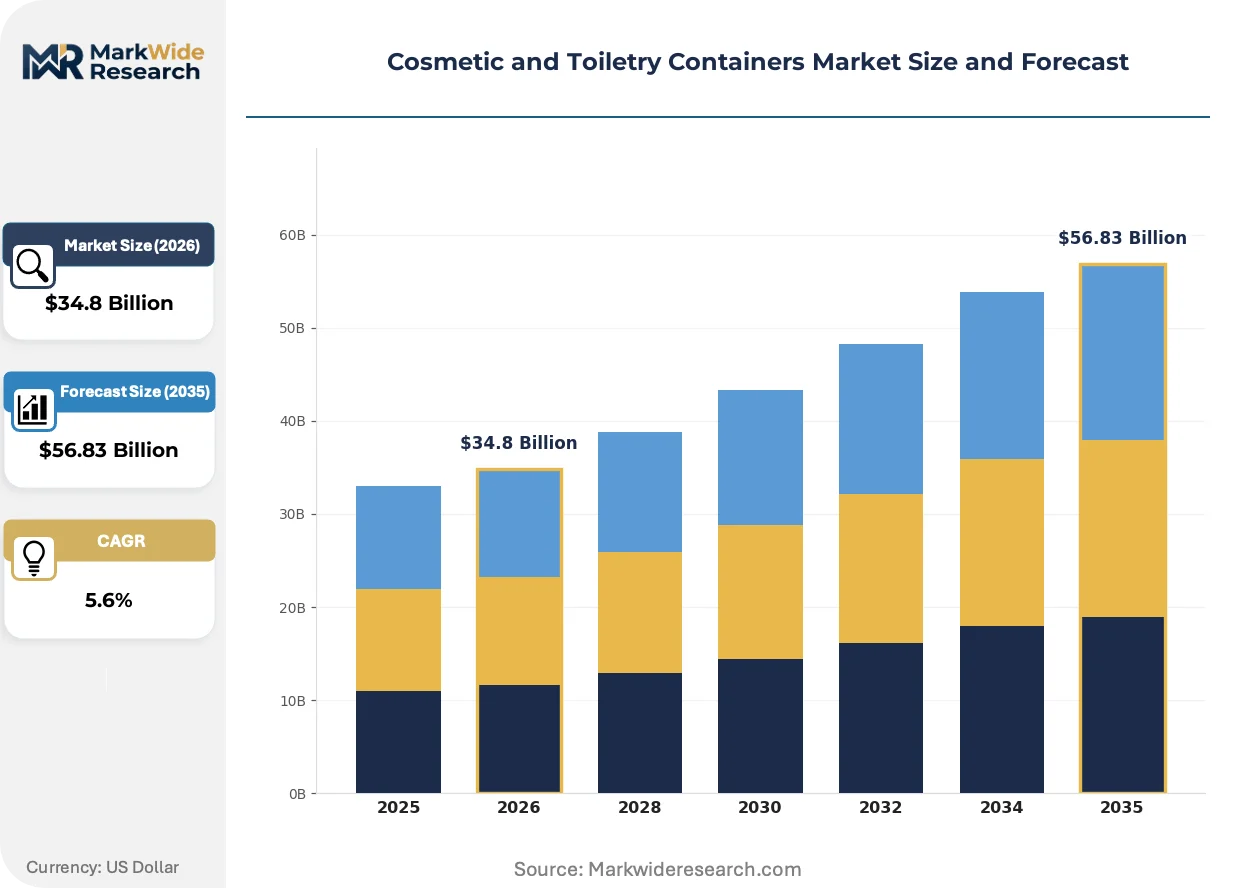
Market Dynamics
Airless pump systems and refillable formats are forcing container suppliers to reengineer production lines, as premium skincare brands demand precise dosing mechanisms and plastic reduction commitments that obsolete conventional jar-and-cap assemblies.
Growth Catalysts
- EU Green Deal procurement mandates:Beauty supply chains must now certify recycled content thresholds and carbon footprints, redirecting R&D budgets toward mono-material designs.
- Pump closure technology:Liquid foundation and serum categories are adopting precision dosing systems that prevent contamination and extend product shelf life.
- South Korea sustainable packaging adoption:Regulatory enforcement and consumer preference alignment are concentrating demand for post-consumer recycled integration in East Asian manufacturing hubs.
Market Restraints
- Post-consumer recycled resin volatility:HDPE and PET feedstock quality inconsistency raises defect rates in blow-molded bottles.
- REACH chemical restrictions:Additive limitations in colorants and coatings constrain surface treatment options for decorative containers.
- Aluminum alloy substitution pressure:Metal packaging competes for fragrance and aerosol segments where perceived sustainability advantages attract brand switching.
Strategic Opportunities
- Mono-material design standards:EU Packaging and Packaging Waste Regulation recyclability disclosures reward simplified polymer structures.
- Molded fiber composite emergence:Tubular forming technologies converge with barrier coating advances to create biodegradable alternatives for dry powder cosmetics.
- Direct-to-consumer refill channels:Subscription models for concentrate-and-reuse systems bypass traditional retail packaging volumes.
Industry Challenges
- Injection stretch blow molding reconfiguration:Legacy equipment requires substantial capital redeployment to handle thinner-walled, recycled-content preforms.
- Extended producer responsibility timeline compression:Germany's packaging compliance deadlines outpace supplier certification capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic and Toiletry Containers Market |
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $56.83 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paperboard Closure Type: Flip-top, Screw Cap, Pump, Spray Product Type: Jars, Bottles, Tubes, Sachets End User: Beauty Brands, Personal Care Manufacturers, Retailers, Distributors |
| Companies Covered | SKS Bottle & Packaging, Albea, Gerresheimer, Silgan Holdings, APC Packaging, Berry Global, Amcor, FusionPKG, HCP Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic and Toiletry Containers Market Strategic Shifts
Dispensing precision and material circularity are rewriting technical specifications across cosmetic packaging, with three converging developments altering supplier capability requirements and brand procurement criteria.
Digital printing on glass and plastic substrates is decentralizing decoration workflows, enabling short-run customization for limited-edition skincare releases. Niche fragrance houses and indie beauty brands are adopting this capability to compress launch timelines from months to weeks. The technology is decentralizing geographic concentration of label production, allowing regional filling facilities to manage full decoration in-house.
REACH compliance expansion into polymer additives is tightening material sourcing for colored containers across European manufacturing. Suppliers must now document additive migration testing and substitution assessments for surface coatings. Facial skincare segments with premium positioning are responding fastest, reformulating packaging specifications ahead of enforcement dates to secure shelf access.
Refill station networks in urban retail environments are altering how consumers acquire liquid personal care products. Concentrate formats and durable primary vessels are displacing single-use bottles in body wash and hair care categories. France and South Korea display the most visible deployment of this model, with department stores and dedicated beauty retailers installing automated dispensing infrastructure.
Cosmetic and Toiletry Containers Market Segmentation
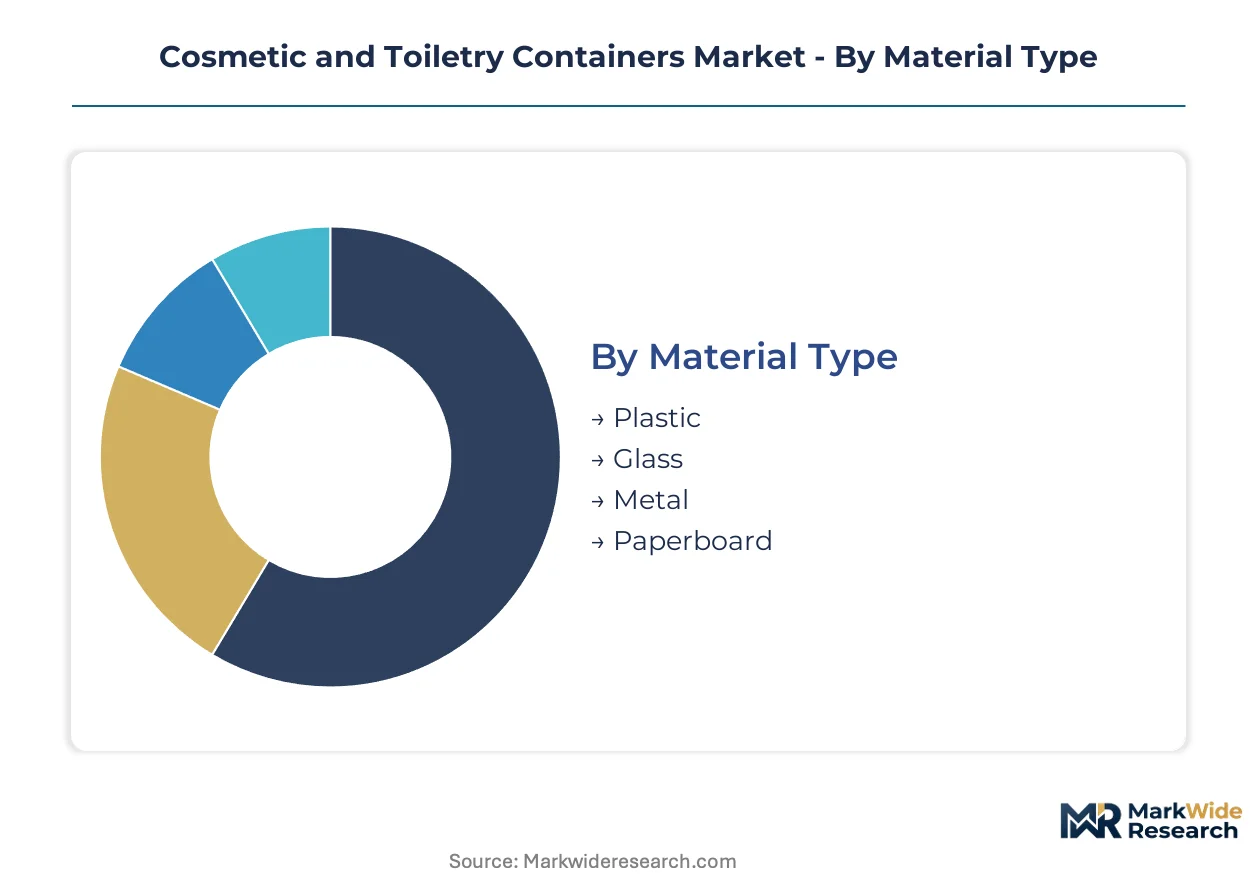
Container specifications diverge sharply across cosmetic categories, with material chemistry and closure mechanics determining shelf stability, dosing precision, and recyclability credentials. Procurement teams now weight mono-material compatibility and post-consumer recycled integration as heavily as unit cost.
Material Type:
Upgrade cycles in cosmetic packaging are accelerating as brands replace legacy multi-material formats with certified recyclable alternatives to meet EU Green Deal procurement mandates.
- Plastic:Polyethylene terephthalate and high-density polyethylene dominate mass-market hair care and body wash through blow-molded bottles with integrated post-consumer recycled streams. South Korean manufacturing hubs are concentrating demand for rPET certification as domestic brands advance plastic reduction pledges ahead of regulatory deadlines.
- Glass:Borosilicate and soda-lime formulations serve premium facial skincare where chemical inertness and perceived quality justify higher unit costs. Germany's fragrance houses anchor specialized molding demand through Albea's tubular glass capabilities and Gerresheimer's decorative finishing lines.
- Metal:Aluminum alloys compete for aerosol and solid fragrance formats where lightweighting and infinite recyclability attract sustainability-positioned brands.
- Paperboard:Molded fiber composites with barrier coatings are emerging for dry powder cosmetics and secondary cartons as biodegradable alternatives displace plastic folding boxes.
Plastic sits at the top of the volume ranking, with paperboard climbing the fastest as barrier coating technologies mature.
Closure Type:
Cost tiering in closure procurement separates precision-dosing premium formats from commodity screw-cap assemblies, with pump mechanisms commanding 3-4x unit premiums.
- Flip-top:Polypropylene hinge mechanisms dominate shampoo and conditioner bottles where one-handed dispensing drives consumer preference. Mass-market personal care manufacturers in North America specify these for high-throughput filling lines.
- Screw Cap:Standard threaded closures persist in jar formats and travel-size toiletries where cost minimization outweighs convenience features. REACH chemical restrictions on colorant additives are constraining decorative options for European-sourced caps.
- Pump:Airless dispensing systems with precision piston mechanisms serve liquid foundations and serums where contamination prevention extends product shelf life. Premium skincare brands in France are accelerating multi-year supply contracts for these formats.
- Spray:Fine-mist actuators and bag-on-valve systems target fragrance and hair styling products where particle size distribution affects consumer experience.
Pump mechanisms capture the steepest expansion trajectory as serum and foundation categories displace traditional jar packaging.
Product Type:
Application-driven format selection aligns container geometry with viscosity, oxidation sensitivity, and usage ritual across cosmetic subcategories.
- Jars:Wide-mouth glass and thick-walled PET containers serve creams and balms where finger access dominates application behavior. Facial skincare brands are responding fastest to REACH compliance expansion by reformulating packaging specifications ahead of enforcement dates.
- Bottles:Cylindrical and oval blow-molded formats accommodate liquid shampoos, conditioners, and body washes across mass and prestige tiers. Berry Global's scale manufacturing in North American personal care centers on HDPE and PET bottles with post-consumer recycled integration.
- Tubes:Laminated and mono-material extruded formats target toothpaste, hair masks, and hand creams where controlled extrusion and portability matter. Albea's integrated tube portfolio secures multi-year contracts with brands pursuing plastic reduction pledges.
- Sachets:Single-dose flexible pouches serve sample distribution and travel retail where minimal material weight reduces logistics cost.
Bottles maintain volume leadership, with tubes gaining share fastest as brands convert jar formats to squeeze-dispense alternatives.
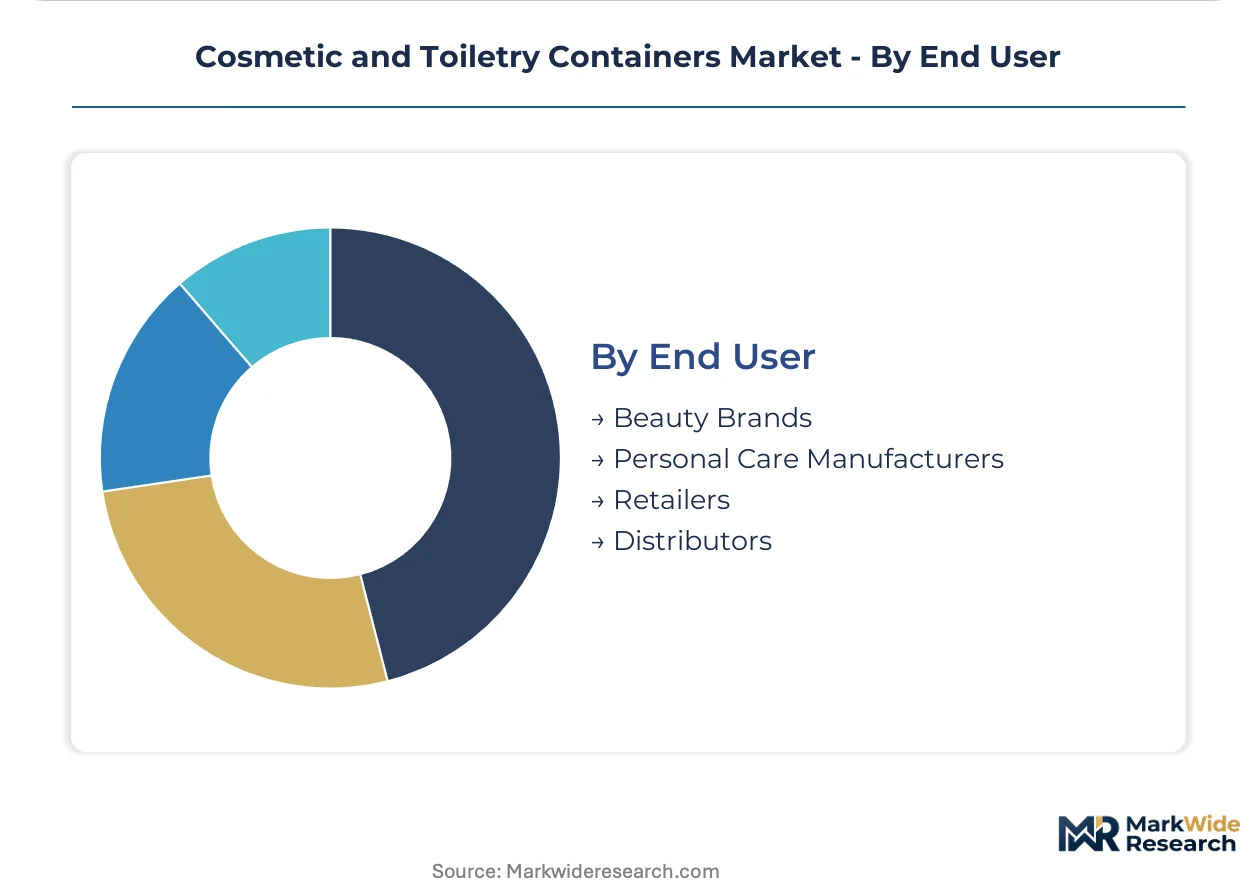
End User:
Customer-type segmentation reveals divergent procurement priorities between multinational brand houses optimizing for scale and indie beauty companies prioritizing customization velocity.
- Beauty Brands:Prestige and masstige cosmetic houses specify container aesthetics and dispensing mechanics as core brand identity elements. Digital printing adoption is decentralizing decoration workflows for limited-edition skincare releases.
- Personal Care Manufacturers:Contract fillers and private-label producers prioritize line efficiency and material standardization across high-volume hair care and body wash programs.
- Retailers:Private-label beauty programs and refill station operators are altering acquisition models toward durable primary vessels and concentrate formats. Department stores in France and South Korea are installing automated dispensing infrastructure.
- Distributors:Wholesale and specialty channel intermediaries aggregate fragmented brand demand for standardized container formats that reduce inventory complexity.
Beauty brands command the largest procurement volume, with retailers expanding most quickly as refill channel infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic container manufacturing first industrialized in France and Germany during the post-war luxury goods expansion, with glassworks and metal forming clusters establishing the technical foundations that later spread to Asian manufacturing hubs.
Germany
Fragrance houses in the Rhine-Ruhr corridor drive specialized glass molding demand for premium perfume packaging. The country's national packaging regulator enforces extended producer responsibility deadlines that outpace supplier certification capacity. Cologne and Hamburg anchor tubular glass finishing capabilities serving multinational brand portfolios.
France
Prestige skincare brands in the Île-de-France region accelerate multi-year supply contracts for airless pump systems. EU Green Deal procurement mandates force container suppliers to certify recycled content thresholds and carbon footprints. Paris department stores install automated dispensing infrastructure for refill station networks.
South Korea
Domestic beauty brands advance plastic reduction pledges ahead of regulatory deadlines, concentrating demand for rPET certification. The country's Ministry of Environment recycling guidelines add compliance layers for surface coating specifications. Seoul manufacturing hubs integrate post-consumer recycled streams into blow-molded bottle production.
United States
Mass-market personal care manufacturers prioritize line efficiency across high-volume hair care and body wash programs. FDA cosmetic labeling requirements constrain material choices and mandate recyclability disclosures. Berry Global's scale manufacturing in North American personal care centers on HDPE and PET bottles with post-consumer recycled integration.
China
GB standards for cosmetic packaging safety govern barrier coating technologies and additive migration testing. The Pearl River Delta and Yangtze River Delta clusters produce molded fiber composites with barrier coatings for dry powder cosmetics. Domestic brands respond fastest to compliance expansion by reformulating packaging specifications ahead of enforcement dates.
Cosmetic and Toiletry Containers Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specialization and dispensing technology tiers, with glass and precision pump specialists commanding 3-4x unit premiums over standard bottle fabricators. The vendor base organizes into three strategic archetypes: integrated tube-and-dispensing portfolio suppliers, scale manufacturers of recycled-content polymers, and specialized glass molding houses for fragrance and skincare. Dominant competitive moves include backward integration into recycled resin sourcing and technology licensing for airless pump mechanisms.
Among France-based packaging specialists, Albea occupies a position exemplifying the integrated portfolio archetype, while Germany's Gerresheimer AG represents specialized glass molding capabilities. Berry Global, Inc. sits within the scale manufacturing tier, anchoring North American personal care supply through volume production of certified recyclable formats.
| Leading Market Players |
|---|
| SKS Bottle & Packaging |
| Albea |
| Gerresheimer |
| Silgan Holdings |
| APC Packaging |
| Berry Global |
| Amcor |
| FusionPKG |
| HCP Packaging |
| Others |
Value Chain & Pricing Dynamics
Airless pump system reengineering is simultaneously compressing production economics and redrawing supplier concentration maps, as precision molding capabilities and mono-material certification requirements force capital redeployment toward specialized manufacturing clusters in Germany, France, and South Korea.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates airless dispensing systems from conventional pump closures from commodity screw-cap assemblies, with precision piston mechanisms commanding 3-4x unit premiums over standard formats. Price differentiation rests on certification grade for post-consumer recycled content and customization level for digital-printed decoration. Cost compression in mass-market HDPE bottles is intensifying because post-consumer recycled resin volatility raises defect rates. Contract fillers and private-label producers exhibit highest price sensitivity, while prestige skincare houses prioritize dispensing precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Cologne, Hamburg, and Seoul anchor hub-and-spoke patterns for glass and precision polymer components, with secondary nodes in Paris and the Pearl River Delta serving fragrance finishing and molded fiber composite production. Manufacturing concentrates in Germany, France, and South Korea for specialized glass and pump systems, while China and the United States dominate blow-molded bottle volume. Feedstock draws from rPET certification streams, borosilicate glassworks, and aluminum alloy smelters. Single-source vulnerability in post-consumer recycled resin qualification creates bottleneck risk. Distribution runs through brand-house direct procurement and contract filler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
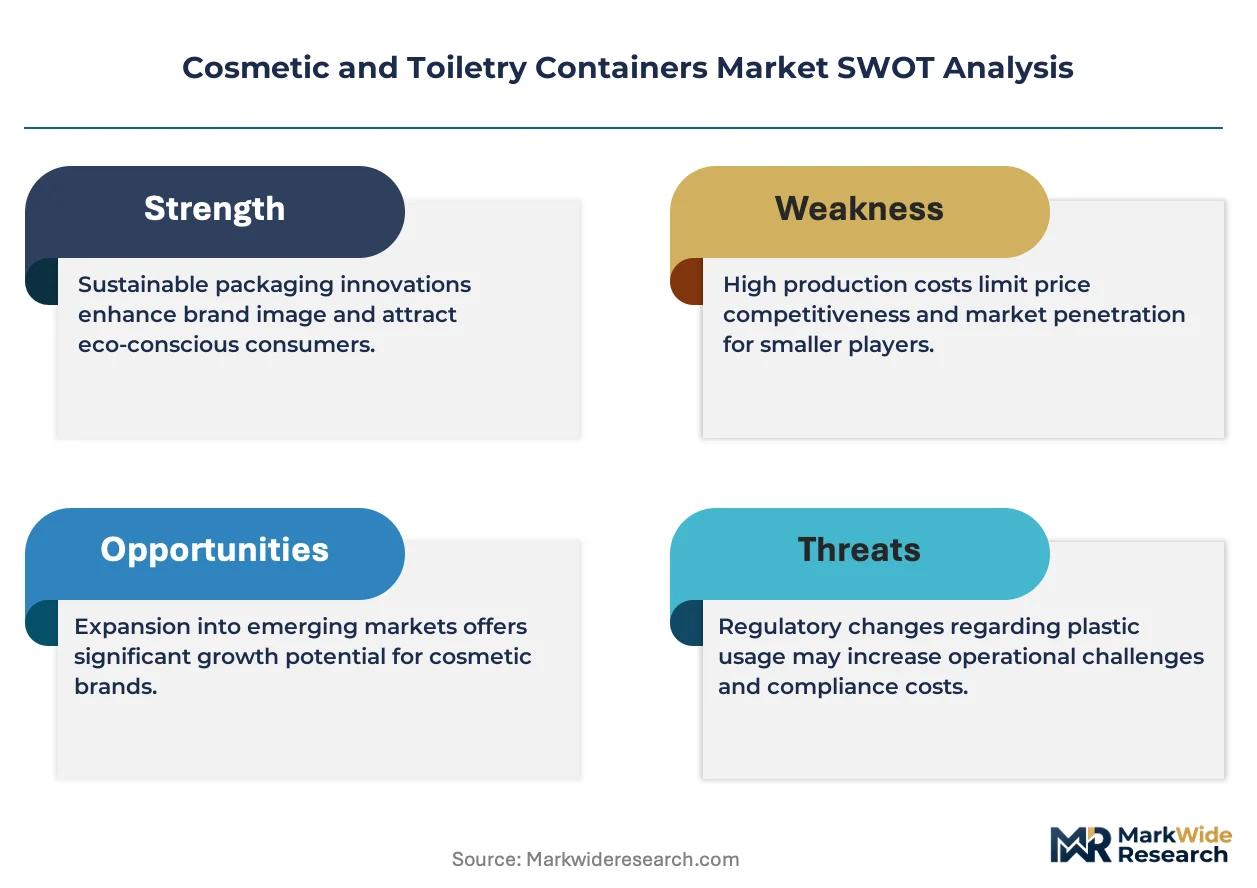
This market represents a late-cycle quality story as serum and foundation categories displace traditional jar packaging, with procurement criteria weighting mono-material compatibility and carbon footprint certification as heavily as unit economics.
For Market Incumbents: Hedge against aluminum alloy substitution in fragrance segments by deepening captive supply of certified recycled polymers and securing multi-year airless pump technology licenses. Capacity addition in South Korean manufacturing hubs addresses rPET certification demand from domestic beauty brands advancing plastic reduction pledges ahead of regulatory deadlines. For New Entrants and Emerging Players: The mid-tier price gap between premium glass skincare vessels and economy plastic bottles offers white-space entry for molded fiber composite specialists targeting dry powder cosmetics. Refill station infrastructure in French and South Korean urban retail presents the most penetrable channel, with direct-to-consumer concentrate subscription models as the viable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among scale manufacturers of commodity HDPE and PET bottles facing margin compression from recycled resin volatility. Long-term viability favors specialized glass molding houses and integrated tube-and-dispensing portfolio suppliers with proven REACH compliance pathways. Watch for inflection in extended producer responsibility deadline acceleration across German packaging compliance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Captive rPET certification streams reduce defect rates and secure EU Green Deal procurement eligibility for blow-molded bottles. |
| Airless Pump Technology Licensing | Precision dispensing patents from German and French specialists extend product shelf life for liquid foundation and serum categories. |
| Digital Printing Capability Deployment | Short-run decoration workflows compress launch timelines for limited-edition skincare releases from Paris and Seoul brand houses. |
| Refill Station Infrastructure Partnership | Automated dispensing installations in French department stores and South Korean beauty retailers displace single-use bottle volumes. |
| Mono-Material Design Certification Investment | EU Packaging and Packaging Waste Regulation recyclability disclosures reward simplified polymer structures with retained market access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at multinational beauty houses, plant engineers at blow-molding facilities, regulatory affairs leads navigating REACH compliance, and category buyers at French and South Korean retailers with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA additive restriction updates, customs records for rPET trade flows, and SEC disclosures from scale polymer manufacturers. Bottom-up container volume modeling and top-down beauty market sizing provided cross-verification.
Comparable-period anchoring used historical shipment data across the analysis window to establish baseline growth trajectories for the projection horizon. The analytical framework modeled segmentation across material type, closure mechanism, product format, and end-user archetype, with CAGRs derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs included airless pump adoption curves in premium skincare and post-consumer recycled resin availability projections from certification body pipelines.
The model assumes a particular technology adoption path; alternative pathways for molded fiber composite barrier coatings would alter the outlook if biodegradability standards tighten faster than anticipated. Forecasts reflect documented assumptions around EU Green Deal enforcement timelines and South Korean plastic reduction pledge acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market