
 Thailand Packaging Market | 2026-2036
Thailand Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Packaging Market Outlook
Food and beverage demand is rebalancing Thailand's packaging procurement mix toward higher-value formats. SCG Packaging Public Company anchors domestic containerboard supply through integrated pulp-to-box operations. Crown Seal Public Company dominates metal closure manufacturing for beverage brands across Southeast Asia. Thai Plaspac Public Company specializes in thermoformed rigid trays serving ready-meal processors.
Packaging encompasses engineered enclosures manufactured from plastic resins, cellulose fibers, metal alloys, or silica-based glass, formed through extrusion, thermoforming, blow molding, or papermaking processes to protect, preserve, and present goods for distribution and sale. Flexible packaging leads volume in snack and condiment applications due to lightweight material efficiency and printability. Rigid plastic bottles command premium placement in personal care segments where dispenser functionality and shelf visibility determine brand selection. Paperboard boxes carry the fastest structural growth in e-commerce fulfillment as corrugated specifications tighten for automated handling compatibility.
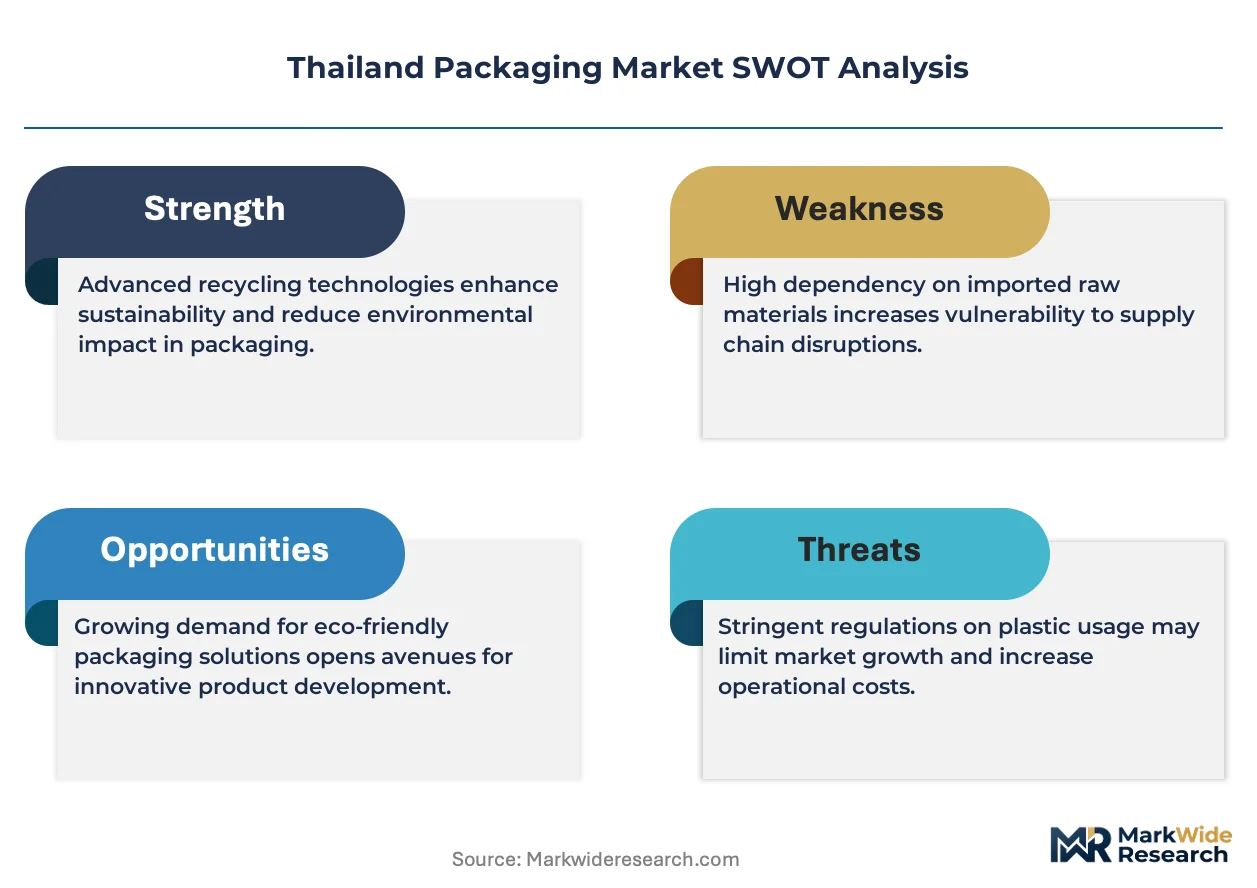
Thailand's Ministry of Industry enforces plastic waste management rules that mandate recycled content thresholds and extended producer responsibility frameworks for packaging producers. The Thai Industrial Standards Institute certifies food-contact material safety under TIS standards that align with ASEAN harmonization protocols. Stakeholders must monitor how bioplastics certification pathways and carbon border adjustment preparations will reshape material qualification requirements and supplier qualification timelines.
Market Dynamics
Thailand's packaging sector faces a structural compression between the Ministry of Industry's plastic waste management roadmap and the Eastern Economic Corridor's industrial clustering, forcing converters to requalify materials while scaling capacity within tightened environmental boundaries.
Growth Catalysts
- ASEAN Food Export Mandates:Processors serving regional halal and ready-meal supply chains are expanding cold-chain compatible barrier packaging procurement to meet shelf-life specifications for cross-border distribution.
- Extended Producer Responsibility Framework:Thailand's Ministry of Industry mandates recycled content thresholds that lock in long-term demand for post-consumer resin qualification and domestic recycling infrastructure.
- Bioplastics Feedstock Availability:Cassava-derived PLA and sugarcane-based ethanol streams from Northeast Thailand agricultural zones are reducing raw material transport costs for biodegradable film producers.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and polyethylene resin prices track naphtha spreads from Singapore refining hubs, compressing converter margins during crude price spikes.
- Containerboard Supply Concentration:Integrated pulp-to-box operations in Prachinburi and Rayong provinces control domestic kraft linerboard availability, limiting independent converters' sourcing alternatives.
- Mechanical Recycling Contamination Limits:Multi-layer flexible packaging structures containing metallized films and adhesive laminates exceed current Thai recycling facility sorting capabilities.
Strategic Opportunities
- E-Commerce Corrugated Specifications:Bangkok metropolitan fulfillment centers are demanding edge-crush-tested and print-ready boxes compatible with automated sortation systems, opening premium specification tiers.
- Pharmaceutical Serialization Compliance:Track-and-trace mandates for export-oriented drug packaging create demand for high-resolution digital printing and tamper-evident closure integration.
- Carbon Border Adjustment Preparation:EU-bound exporters are pre-qualifying packaging suppliers with verified lifecycle assessments to avoid future tariff exposure on embedded emissions.
Industry Challenges
- Bioplastics Certification Timeline:TIS industrial standards institute approval pathways for novel compostable materials extend qualification periods beyond typical product development cycles.
- Skilled Thermoforming Technician Scarcity:Precision mold setup and thin-gauge sheet calibration expertise concentrates among veteran operators in Samut Prakan industrial zones, constraining new facility ramp rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Packaging Market |
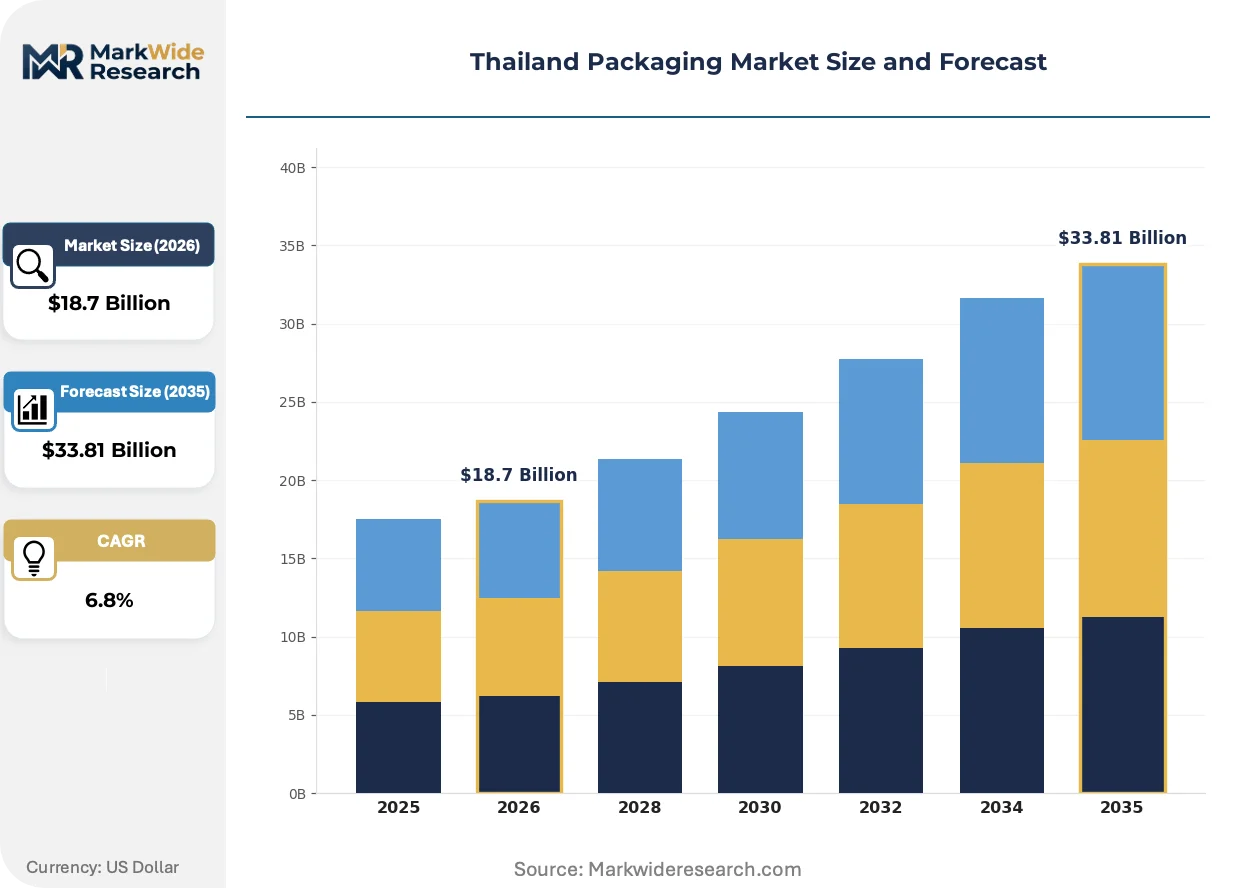
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
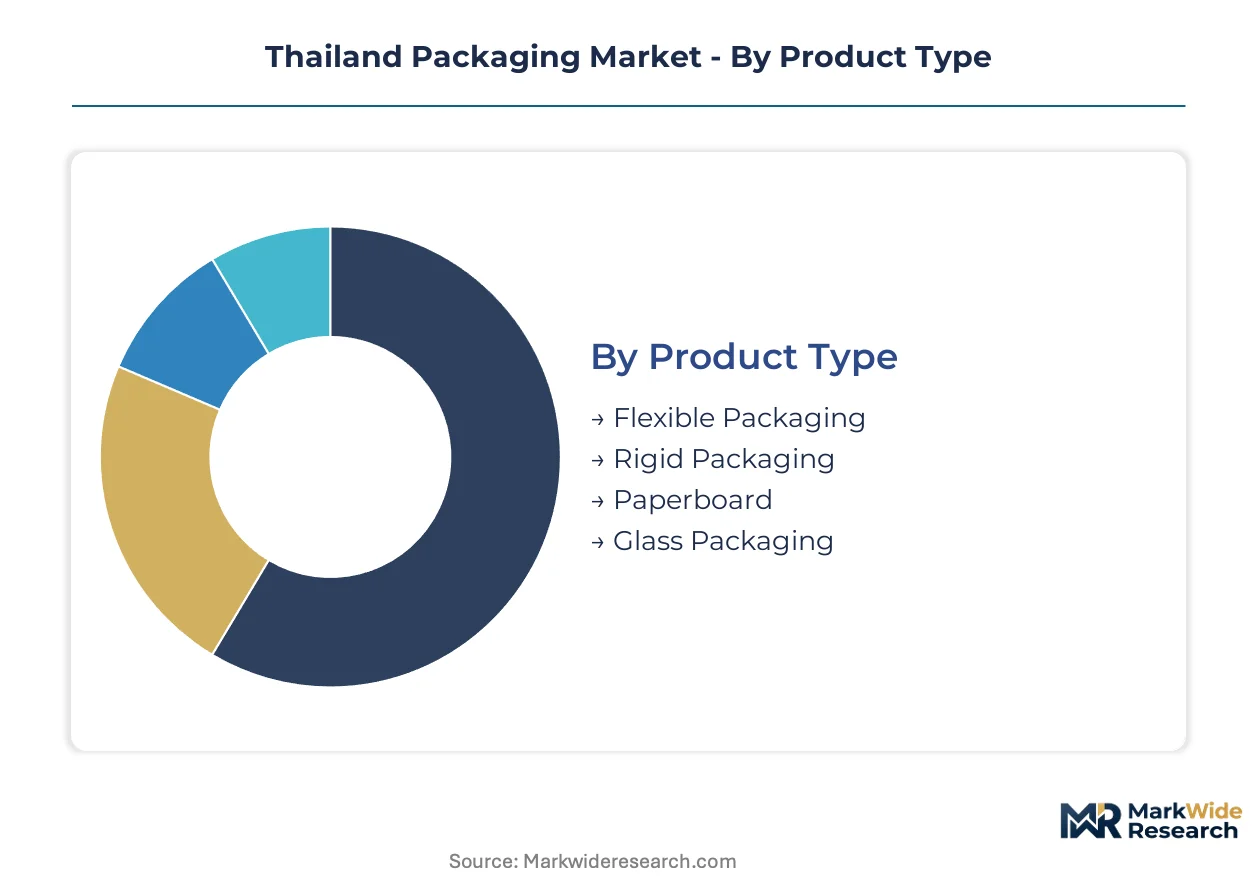
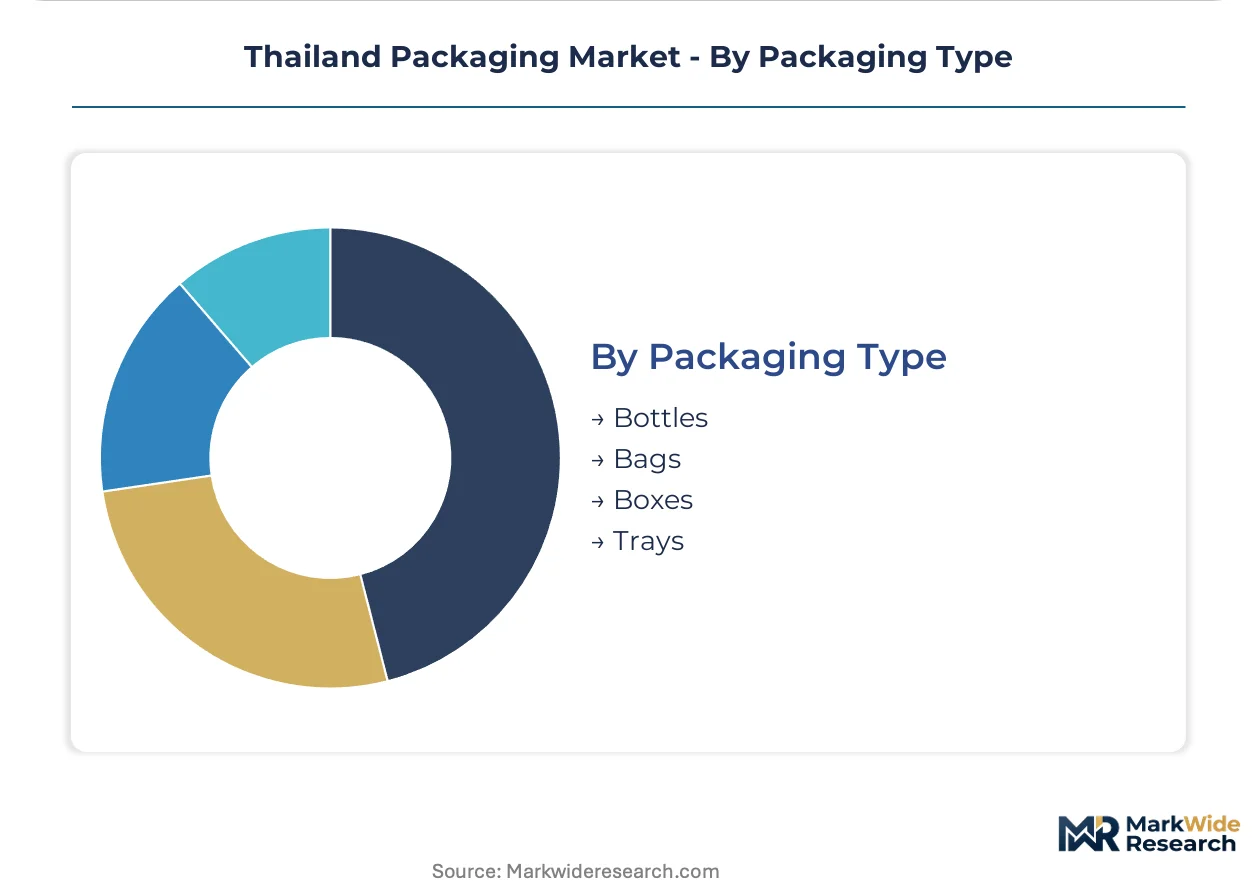
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard, Glass Packaging End Use: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material: Plastic, Paper, Metal, Wood Packaging Type: Bottles, Bags, Boxes, Trays |
| Companies Covered | Srithai Superware Public Company, Crown Seal Public Company, SCG Packaging Public Company, Starflex Public Company, Thantawan Industry Public Company, BG Container Glass Public Company, Thai Plaspac Public Company, A.J. Plast Public Company, Thai Metal Drum Manufacturing Public Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Packaging Market Strategic Shifts
Digital printing and smart packaging interfaces are compressing traditional offset production runs while enabling batch-level customization for Thailand's export-oriented food and cosmetics sectors.
Barrier-coated paper substrates are integrating oxygen and moisture resistance directly into cellulose structures, eliminating separate plastic film lamination layers. Premium chocolate and dried fruit exporters in Chonburi province are adopting these materials for European retail compliance. The technology is integrating monomaterial recyclability into packaging formats previously classified as non-recyclable composites.
Thailand's Ministry of Industry plastic waste management rules now enforce recycled content thresholds and extended producer responsibility frameworks for packaging producers. Converters must document post-consumer resin sourcing through certified recycling facility partnerships. Food-contact applications face the tightest compliance windows under TIS harmonization with ASEAN safety protocols.
Consolidated buying by modern trade retailers and quick-commerce platforms is compressing supplier bases and demanding just-in-time replenishment with smaller minimum order quantities. Regional supermarket chains in the Bangkok metropolitan area are replacing annual procurement tenders with quarterly volume commitments tied to promotional calendars. Cosmetics brands pivoting to direct-to-consumer channels are driving this pattern most visibly in Samut Prakan and Pathum Thani production zones.
Thailand Packaging Market Segmentation
Thailand's packaging procurement patterns diverge sharply between export-oriented food processors demanding barrier performance and domestic e-commerce fulfillment centers optimizing for automated handling. Material qualification timelines and recycled content mandates from the Ministry of Industry are compressing supplier selection criteria across all specification tiers.
Product Type:
Structural performance and shelf-life extension capabilities define competitive positioning in Thailand's converter base.
- Flexible Packaging:Multi-layer films and pouches incorporate oxygen barrier metallization and adhesive lamination for snack and condiment applications. Bangkok metropolitan ready-meal processors are expanding procurement of retort-compatible structures to serve ASEAN export mandates.
- Rigid Packaging:Injection-molded and thermoformed containers deliver dimensional stability for personal care dispensers and pharmaceutical tablet bottles. Samut Prakan industrial zones concentrate precision mold setup expertise for thin-gauge sheet calibration.
- Paperboard:Corrugated fiberboard and folding cartons integrate edge-crush specifications for automated sortation compatibility. Eastern Economic Corridor fulfillment centers are tightening box performance standards for cross-border e-commerce.
- Glass Packaging:Silica-based bottles and jars provide inert containment for premium cosmetics and pharmaceutical syrups. High thermal mass limits adoption in weight-sensitive export logistics.
Mature deployment sits with Flexible Packaging. Newer deployment is concentrated in Paperboard.
End Use:
Regulatory compliance intensity and shelf-life specifications segment converter capabilities across application verticals.
- Food & Beverage:Halal certification requirements and cold-chain barrier specifications dominate procurement criteria for ASEAN export processors. Chonburi province chocolate and dried fruit exporters are adopting barrier-coated paper substrates for European retail compliance.
- Pharmaceuticals:Track-and-trace serialization mandates require high-resolution digital printing and tamper-evident closure integration. The Thai Industrial Standards Institute certifies food-contact material safety under TIS standards that align with ASEAN harmonization protocols.
- Personal Care:Dispenser functionality and shelf visibility determine brand selection for rigid bottles and jars. Direct-to-consumer channel expansion in Pathum Thani production zones is compressing minimum order quantities.
- Household Products:Chemical resistance and child-safety closure specifications govern container design for cleaning formulations. Concentrated refill formats are displacing primary packaging volume in modern trade channels.
Food & Beverage anchors volume concentration. Pharmaceuticals is gaining share fastest on compliance-driven specification upgrades.
Material:
Feedstock availability and circular economy infrastructure shape regional sourcing patterns within Thailand's industrial zones.
- Plastic:Polypropylene and polyethylene resins track naphtha spreads from Singapore refining hubs. Cassava-derived PLA and sugarcane-based ethanol streams from Northeast Thailand agricultural zones are reducing transport costs for biodegradable film producers.
- Paper:Kraft linerboard supply concentrates in Prachinburi and Rayong integrated pulp-to-box operations. Post-consumer recycled fiber qualification is accelerating under extended producer responsibility frameworks.
- Metal:Aluminum and steel closures dominate beverage packaging with Crown Seal Public Company anchoring regional supply. Metal alloys command premium placement where oxygen exclusion extends shelf life.
- Wood:Pallets and crates serve bulk agricultural export logistics with lower specification barriers than consumer-facing formats. Plantation timber availability from domestic forestry concessions limits import dependency.
Plastic retains volume leadership. Paper is climbing the fastest on e-commerce corrugated demand and recycled content mandates.
Packaging Type:
Form factor selection aligns with distribution channel requirements and automated handling infrastructure deployment.
- Bottles:Blow-molded and injection-stretch configurations deliver dispenser functionality for beverages and personal care. Rigid plastic bottles command premium placement where shelf visibility determines brand selection.
- Bags:Pillow pouches and stand-up configurations minimize material weight for snack and condiment applications. Lightweight material efficiency drives volume concentration in flexible formats.
- Boxes:Corrugated RSC and die-cut designs integrate print-ready surfaces for brand communication. Bangkok metropolitan fulfillment centers demand edge-crush-tested specifications compatible with automated sortation systems.
- Trays:Thermoformed rigid structures serve ready-meal processors with modified atmosphere compatibility. Thai Plaspac Public Company specializes in thin-gauge sheet calibration for precision food contact applications.
Bags dominate material efficiency metrics. Boxes are expanding most quickly on e-commerce infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor tax-incentive zone concentrates packaging investment through bonded warehouse privileges and streamlined customs processing for export-oriented converters.
Central Region
Bangkok metropolitan fulfillment centers drive corrugated box demand for automated sortation compatibility. The Ministry of Industry enforces recycled content thresholds that lock in post-consumer resin procurement. Samut Prakan industrial zones concentrate precision thermoforming expertise for thin-gauge sheet calibration.
Eastern Region
Rayong and Chonburi provinces anchor integrated pulp-to-box operations serving ASEAN food export mandates. The Thai Industrial Standards Institute certifies food-contact material safety under TIS standards aligning with ASEAN harmonization protocols. Chonburi chocolate and dried fruit exporters adopt barrier-coated paper substrates for European retail compliance.
Northeastern Region
Cassava-derived PLA and sugarcane-based ethanol streams from Khon Kaen and Nakhon Ratchasima agricultural zones reduce transport costs for biodegradable film producers. Extended producer responsibility frameworks mandate domestic recycling infrastructure development. Bioplastics feedstock availability is accelerating qualification timelines for compostable packaging formats.
Northern Region
Chiang Mai and Lampang provinces host specialty paperboard converters serving premium cosmetics and pharmaceutical serialization requirements. Track-and-trace mandates for export-oriented drug packaging create demand for high-resolution digital printing capabilities. Local clusters are pre-qualifying suppliers with verified lifecycle assessments for EU carbon border adjustment preparation.
Southern Region
Songkhla and Surat Thani provinces support rubber and palm oil export logistics through bulk agricultural packaging demand. The country's plastic waste management roadmap tightens environmental boundaries for multi-layer flexible structures. Regional converters face mechanical recycling contamination limits that exceed current sorting capabilities.
Thailand Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-box operations commanding linerboard supply and independent converters competing on specification flexibility. The market structure concentrates around three archetypes: captive pulp-to-box integrators, precision thermoforming specialists, and regional metal closure fabricators. Competitive moves center on backward integration into agricultural feedstocks and strategic partnerships with certified recycling facilities.
Within the integrated pulp-to-box tier, SCG Packaging Public Company anchors domestic containerboard supply. Crown Seal Public Company exemplifies the metal closure fabrication archetype for beverage brands across Southeast Asia. Thai Plaspac Public Company occupies a position among thermoformed rigid tray specialists serving ready-meal processors. These three entities represent distinct capability concentrations that shape procurement alternatives for export-oriented food and personal care brands.
| Leading Market Players |
|---|
| Srithai Superware Public Company |
| Crown Seal Public Company |
| SCG Packaging Public Company |
| Starflex Public Company |
| Thantawan Industry Public Company |
| BG Container Glass Public Company |
| Thai Plaspac Public Company |
| A.J. Plast Public Company |
| Thai Metal Drum Manufacturing Public Company |
| Others |
Value Chain & Pricing Dynamics
Bangkok metropolitan fulfillment centers' automated sortation specifications are forcing corrugated converters to absorb premium substrate costs while competing on just-in-time delivery windows. This demand-side compression squeezes margins across the Eastern Economic Corridor's integrated pulp-to-box operations and independent sheet plants alike.
Pricing Analysis
Short lead-time premiums dominate converter pricing structures, with Bangkok e-commerce fulfillment centers paying 15-20% markups for 48-hour turnaround on edge-crush-tested specifications. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded tiers separates food-contact TIS-compliant grades from general-purpose containerboard. Pricing pressure stems from Singapore naphtha-linked resin volatility feeding into multi-layer flexible film costs. Small ready-meal processors show highest price sensitivity, while pharmaceutical serialization mandates render premium digital printing tiers relatively inelastic.
Supply Chain Analysis
Thai Industrial Standards Institute food-contact certification gates access to ASEAN export channels, extending qualification timelines for novel barrier-coated paper substrates. Raw material sourcing draws from domestic kraft pulp in Prachinburi and Rayong, Singapore-refined polyolefin resins, and Northeast Thailand cassava-derived PLA streams. Single-source vulnerability concentrates in SCG Packaging's linerboard dominance across the Eastern Economic Corridor. Distribution runs through bonded warehouse zones offering streamlined customs processing for cross-border ASEAN shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's packaging sector sits in a materials-transition phase as barrier-coated paper substrates displace multi-layer plastic laminations for European export compliance. This technology shift rewrites supplier qualification requirements and procurement patterns simultaneously.
For Market Incumbents: To counter bioplastics certification timeline delays at TIS, anchor market position through backward integration into Northeast Thailand cassava feedstock zones. Accelerate post-consumer resin qualification partnerships with certified recycling facilities before extended producer responsibility mandates tighten. Lock in long-term offtake agreements with Bangkok metropolitan fulfillment centers to secure automated sortation-compatible volume commitments. For New Entrants and Emerging Players: Begin with pharmaceutical serialization compliance services in Northern Region clusters, where track-and-trace mandate gaps create immediate specification arbitrage opportunities. Target barrier-coated paper substrate production for Chonburi chocolate and dried fruit exporters seeking European retail compliance. Pursue direct engagement with quick-commerce platforms demanding quarterly volume commitments with promotional calendar flexibility. For Investors and Strategic Acquirers: The window for entry favors precision thermoforming specialists with thin-gauge sheet calibration expertise concentrated in Samut Prakan industrial zones. Long-term viability hinges on circular economy infrastructure positioning as carbon border adjustment mechanisms mature. Monitor EU carbon border adjustment preparation progress among export-oriented food processors as the inflection signal for premium specification tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Cassava-derived PLA sourcing from Khon Kaen agricultural zones reduces transport cost exposure for biodegradable film producers. |
| Post-Consumer Resin Qualification Partnership | Certified recycling facility alliances lock in extended producer responsibility compliance ahead of Ministry of Industry enforcement windows. |
| Barrier-Coated Paper Capacity Expansion | Oxygen and moisture resistance integration directly into cellulose structures eliminates separate plastic lamination for European retail compliance. |
| Digital Printing Serialization Capability | High-resolution track-and-trace infrastructure captures pharmaceutical export mandates requiring tamper-evident closure integration. |
| Automated Sortation Specification Certification | Edge-crush-tested corrugated formats secure premium placement in Bangkok metropolitan fulfillment center procurement tenders. |
Study Parameters
Trade flow databases, Thai Industrial Standards Institute certification registries, and Eastern Economic Corridor investment promotion records formed the secondary backbone for this analysis. Primary interviews with corrugated plant managers, ready-meal procurement directors, pharmaceutical regulatory affairs leads, and quick-commerce supply chain heads combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling anchored volume estimates in named converter capacity and utilization rates across Rayong, Prachinburi, and Samut Prakan industrial zones, while top-down cross-checks applied sectoral spending ratios from national manufacturing surveys. Segmentation dimensions included product type, end-use vertical, material feedstock, and packaging format across the projection horizon. CAGRs derived from regression analysis against industrial production indices and export shipment volumes, with specific inputs from ASEAN food trade flow acceleration and e-commerce fulfillment infrastructure buildout rates.
Underlying measurement precision varies by segment; rigid plastic and paperboard categories carry tighter precision than emerging bioplastics formats where TIS approval pathways remain unsettled. Forecasts reflect assumptions about Ministry of Industry enforcement consistency and EU carbon border adjustment implementation sequencing. A model refresh is warranted upon material change in extended producer responsibility mandate timelines or significant feedstock cost dislocation in Singapore refining hubs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Chemical Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Construction Films Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Packaging Straps and Buckles Market