
 Vacuum Packaging Market | 2026-2036
Vacuum Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Packaging Market Intelligence
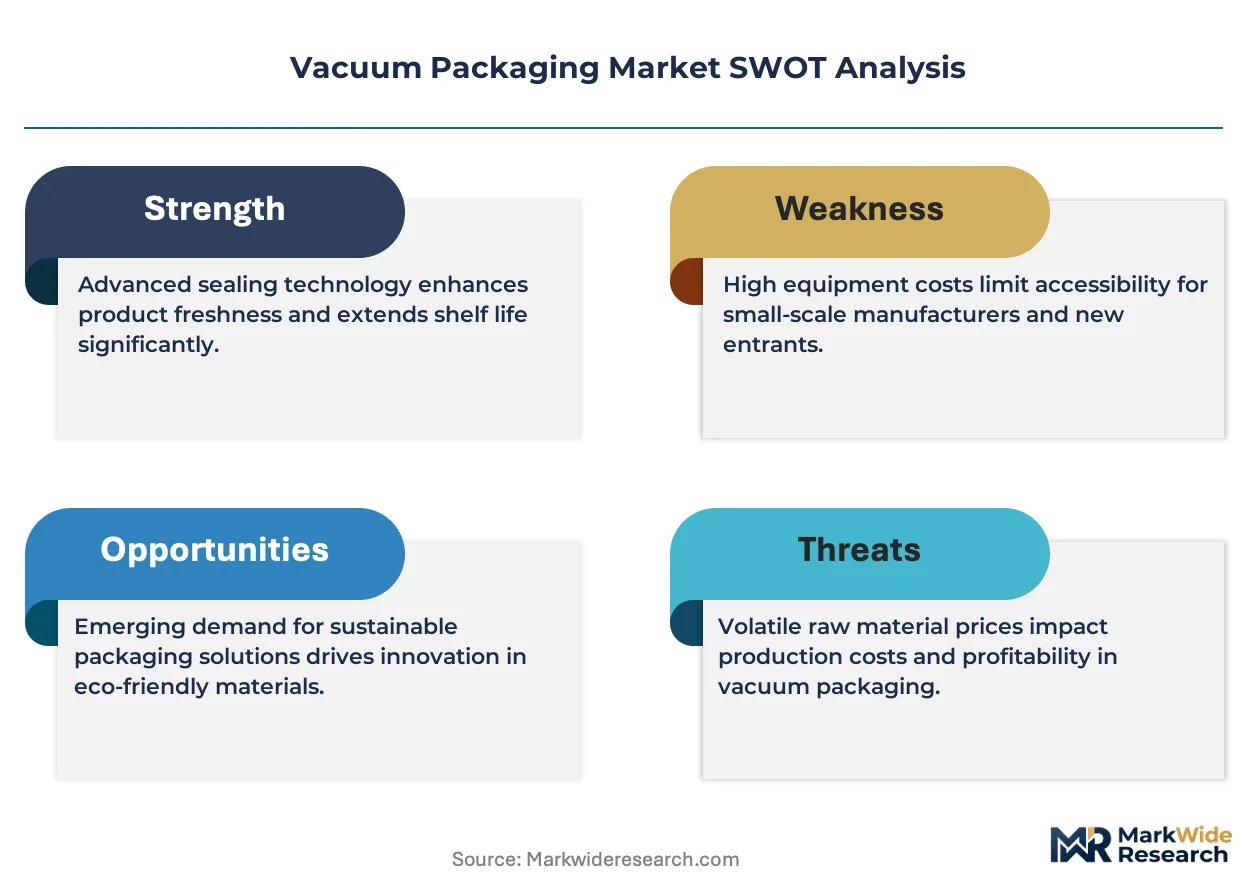
Polyethylene terephthalate (PET) barrier laminates is hardening as the cost-effective alternative to ethylene vinyl alcohol (EVOH) coextrusions in mid-tier food applications. Amcor plc leverages its integrated film extrusion network across Europe and North America to control resin conversion costs. Sealed Air Corporation anchors its position through proprietary Cryovac shrink-bag technology for protein processors. Mondi Group differentiates via kraft-paper-based vacuum solutions targeting fiber-recyclability mandates.
Vacuum packaging denotes the hermetic evacuation of air from a sealed enclosure to inhibit oxidative degradation and microbial proliferation, typically achieving residual oxygen levels below 1% through suction pumps or chamber systems. The process relies on multilayer coextruded films combining polyethylene sealant layers with nylon or polyethylene terephthalate structural plies to balance gas barrier performance, puncture resistance, and heat-seal integrity. Flexible bags dominate volume due to their ubiquity in fresh protein and processed cheese formats, while rigid containers capture premium margin pools in ready-meal and pharmaceutical applications where dimensional stability and resealability command price premiums. Modified atmosphere technology represents the fastest-expanding segment as nitrogen and carbon dioxide flushing protocols extend shelf life beyond simple vacuum evacuation for delicate produce and baked goods.
The U.S. Food and Drug Administration governs migration limits for food-contact substances under 21 CFR, while the European Food Safety Authority evaluates recycling process safety for post-consumer content incorporation into new vacuum films. REACH compliance obligations on phthalate plasticizers and perfluorinated substances are forcing material reformulations across nylon and polyethylene supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and decide between investing in chemical recycling infrastructure or pivoting to mono-material polyethylene structures that satisfy emerging sortability standards without sacrificing barrier performance.
Market Dynamics
Multilayer film recyclability mandates under the EU Packaging and Packaging Waste Regulation are forcing material architecture redesigns across protein, dairy, and pharmaceutical packaging formats, compressing development cycles for converters.
Growth Catalysts
- Modified atmosphere protocols:Nitrogen and carbon dioxide flushing systems extend shelf life for delicate produce and baked goods beyond simple vacuum evacuation, penetrating fresh-cut salad and artisan bread segments.
- Automation in German meat processing:Chamber sealer upgrades accelerate as processors retrofit lines for higher throughput and labor reduction, concentrating equipment demand in Bavaria and Lower Saxony processing clusters.
- Meal-kit distribution expansion:Vacuum-sealed protein and produce formats proliferate as food service operators and direct-to-consumer distributors standardize portion-controlled packaging for subscription fulfillment.
Market Restraints
- Resin cost volatility:Nylon and polyethylene terephthalate feedstock prices fluctuate with crude oil derivatives and polymer capacity constraints, squeezing converter margins on fixed-price contracts.
- Multilayer film incompatibility:Current mechanical recycling infrastructure cannot sort and process bonded polyethylene-nylon-EVOH structures, creating stranded waste volumes and compliance exposure under extended producer responsibility schemes.
- Perfluorinated substance restrictions:REACH compliance obligations on PFAS and phthalate plasticizers force reformulation of sealant layers and barrier coatings, extending qualification timelines for food-contact approvals.
Strategic Opportunities
- Mono-material polyethylene structures:Sortability-compliant barrier films that satisfy emerging recycling standards without sacrificing oxygen transmission performance open premium positioning in private-label retail channels.
- Chemical recycling infrastructure:Pyrolysis and depolymerization investments enable closed-loop recovery of multilayer film waste, creating feedstock security for converters with offtake agreements.
- Pharmaceutical cold-chain expansion:Rigid vacuum containers with dimensional stability and resealability capture margin pools in temperature-sensitive biologics distribution, particularly in parenteral drug formats.
Industry Challenges
- Barrier performance trade-offs:Achieving sub-1% residual oxygen levels with mono-material polyethylene structures requires nanocomposite or bio-based coating innovations that remain unproven at commercial scale.
- Migration testing complexity:21 CFR food-contact substance evaluations and EFSA recycling process safety assessments demand 18-24 month approval cycles, delaying product launches for reformulated film structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Packaging Market |
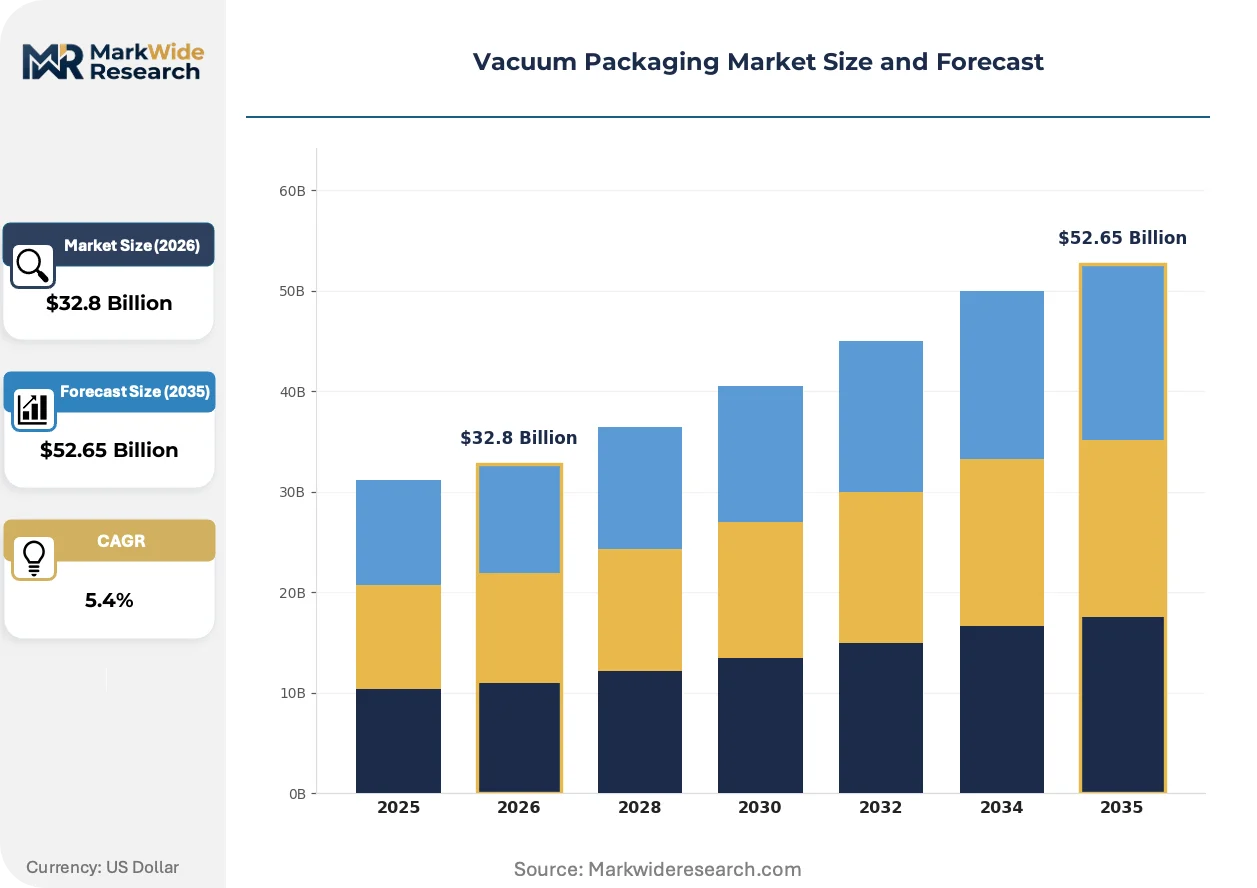
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Rigid Containers, Vacuum Sealers, Pouches Material: Polyethylene, Nylon, Polypropylene, Paper End User: Food Industry, Pharmaceuticals, Electronics, Retail Technology: Modified Atmosphere, Heat Sealing, Vacuum Chamber, Shrink Wrapping |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global, Mondi Group, Winpak Ltd., Coveris, ULMA Packaging, Klöckner Pentaplast Group, Multivac Sepp Haggenmüller SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging integration is transforming vacuum formats from passive containment into sensor-enabled supply chain nodes, with oxygen scavengers and freshness indicators migrating from premium pharmaceutical applications into mainstream protein retail.
High-barrier polyethylene furanoate (PEF) films are electrifying sustainable packaging roadmaps as a bio-based alternative to petroleum-derived polyethylene terephthalate, with pilot lines in the Netherlands and Germany validating thermoformability and seal strength parity. Protein processors in Scandinavia are qualifying PEF trays for modified-atmosphere bacon and sliced deli formats, compressing the timeline for fossil-based barrier material displacement in mid-tier retail segments.
REACH restrictions on per- and polyfluoroalkyl substances are compelling fluoropolymer-free barrier coating development, with ECHA evaluations of PFAS bans forcing converters to accelerate silicone oxide and aluminum oxide vapor deposition alternatives. Nylon film suppliers face the steepest reformulation burden, as legacy grease-resistant treatments rely on C6 fluorochemistry now targeted for restriction across EU member states.
Direct-store-delivery consolidation is compressing order cycles for vacuum-sealed case-ready meat, with retail buyers consolidating supplier bases around converters offering integrated tray-sealing and labeling capabilities. Regional grocery chains in the US Midwest and German discount formats are mandating vendor-managed inventory programs, shifting forecasting risk upstream to film converters and equipment OEMs with the balance-sheet capacity to absorb working capital expansion.
Vacuum Packaging Market Segmentation
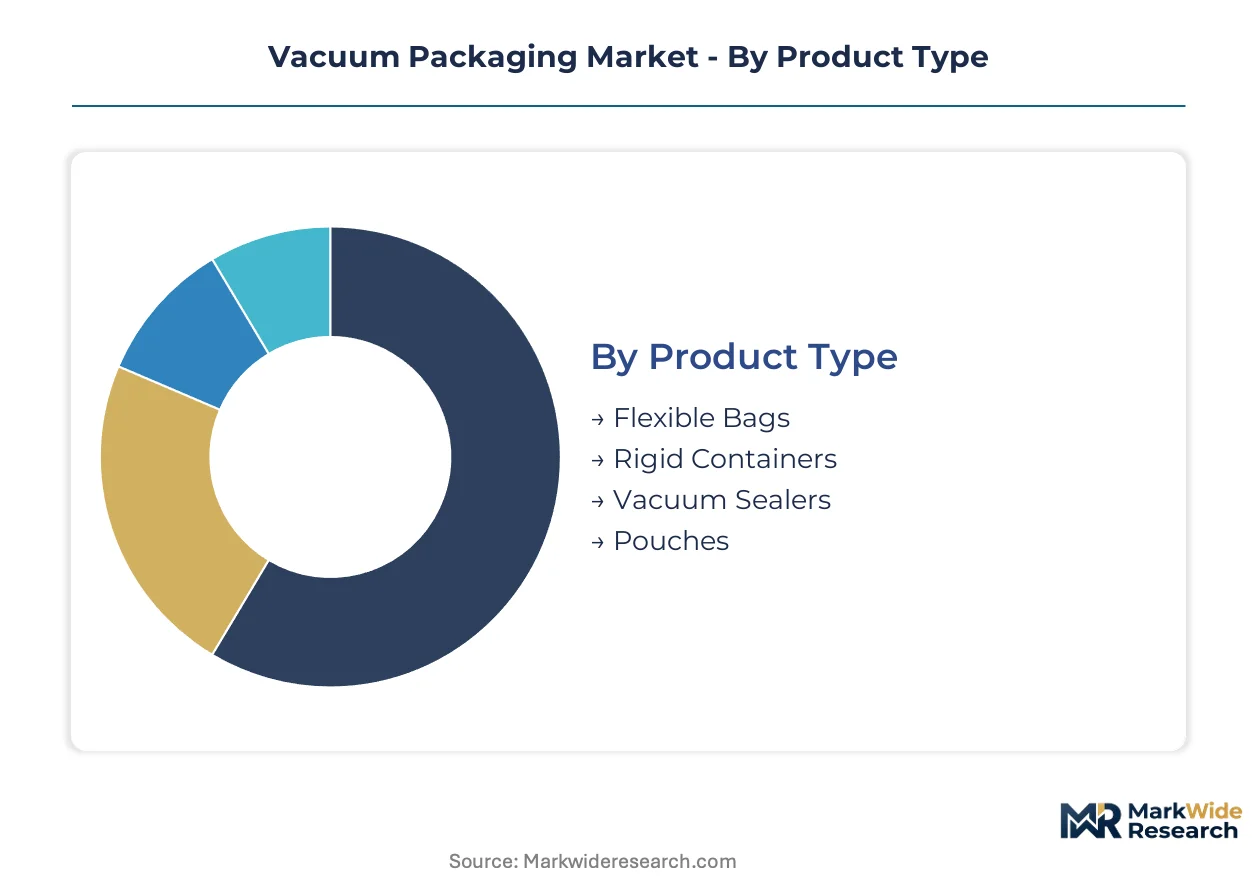
Vacuum packaging segmentation reveals how material choices and technology formats align with distinct supply chain economics. Product architecture decisions cascade through converter capacity planning, equipment procurement cycles, and regulatory compliance pathways.
Product Type:
Supply concentration among European film extruders and Asian equipment OEMs shapes availability and lead times across each format category.
- Flexible Bags:Multilayer coextruded films combining polyethylene sealant layers with nylon or PET structural plies deliver puncture resistance and sub-1% residual oxygen performance. Demand concentrates in German meat processing clusters and US Midwest protein packers as automation retrofits accelerate chamber sealer throughput. EFSA migration limits under 21 CFR and REACH compliance obligations force ongoing reformulation of adhesive and barrier layers.
- Rigid Containers:Thermoformed trays and lidded formats provide dimensional stability for ready-meals and pharmaceutical cold-chain applications where resealability commands premium positioning. Pharmaceutical distributors in Switzerland and biologics shippers in the Netherlands specify these formats for temperature-sensitive parenteral drugs.
- Vacuum Sealers:Chamber and external suction systems span manual tabletop units through automated inline configurations. Bavarian and Lower Saxony processing clusters drive equipment upgrade cycles.
- Pouches:Pre-formed three-side-seal and stand-up formats serve portion-controlled meal-kit distribution and retail cheese segments. Scandinavian bacon processors and Dutch deli meat converters qualify these for modified-atmosphere protocols.
Today's leader: Flexible Bags. Tomorrow's challenger: Rigid Containers.
Material:
Resin cost volatility and recyclability mandates are rebalancing procurement priorities across converter networks.
- Polyethylene:Dominates sealant layers and mono-material structure development as converters pursue sortability-compliant barrier films. Pilot lines in Germany validate high-barrier PE formulations with nanocomposite coatings.
- Nylon:Structural ply providing puncture resistance and thermoformability in multilayer laminates. REACH restrictions on perfluorinated grease-resistant treatments compel fluoropolymer-free coating alternatives.
- Polypropylene:Clarity and moisture barrier properties suit retort and hot-fill applications. Demand clusters in Asian processed food exports.
- Paper:Kraft-based vacuum solutions target fiber-recyclability mandates under EU Packaging and Packaging Waste Regulation. Nordic retail channels specify these for private-label meat and cheese.
Polyethylene holds current volume leadership. Paper-based alternatives are climbing the fastest as EPR schemes tighten.
End User:
Application-specific barrier requirements and approval timelines segment converter customer portfolios.
- Food Industry:Fresh protein, processed cheese, and baked goods formats drive the majority of flexible film demand. German discount retailers and US Midwest grocery chains mandate vendor-managed inventory programs.
- Pharmaceuticals:Rigid containers and high-barrier pouches for biologics distribution require 18-24 month FDA and EMA qualification cycles. Swiss and Dutch cold-chain specifications dominate this segment.
- Electronics:Moisture and oxygen exclusion for semiconductor and component shipping. Asian manufacturing hubs concentrate demand.
- Retail:Case-ready meat and modified-atmosphere produce formats for direct-store-delivery consolidation. Private-label specifications increasingly require integrated tray-sealing and labeling capabilities.
Food Industry maintains structural dominance. Pharmaceuticals offers the steepest expansion trajectory as biologics distribution scales.
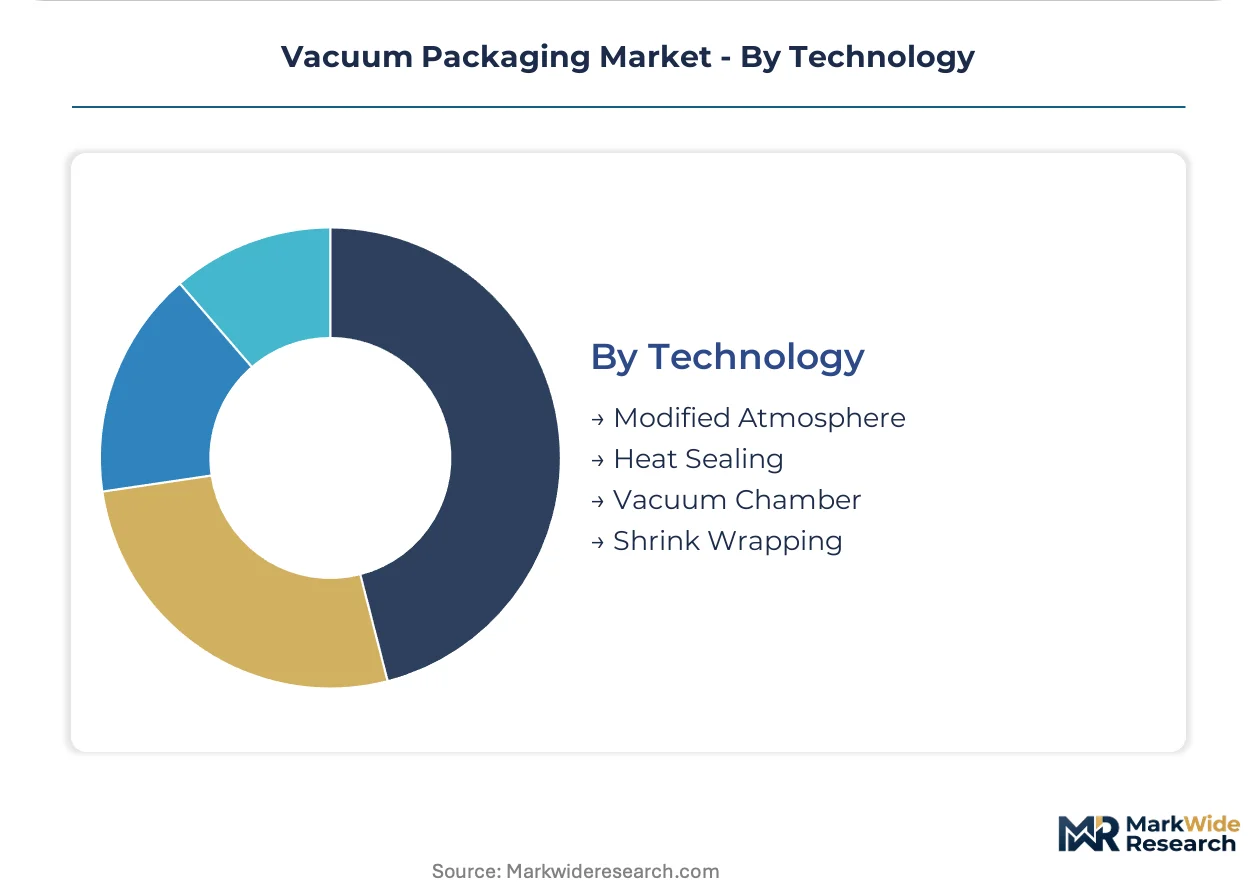
Technology:
Equipment and process selection determines shelf-life extension performance and capital deployment intensity.
- Modified Atmosphere:Nitrogen and carbon dioxide flushing protocols extend shelf life beyond simple vacuum evacuation for delicate produce and artisan bread. Fresh-cut salad processors in the Netherlands and Scandinavian bacon packers lead adoption.
- Heat Sealing:Bar and impulse sealing systems for flexible bag closure. Universal applicability across protein and dairy formats.
- Vacuum Chamber:Batch processing systems achieving highest oxygen evacuation rates for premium protein applications. German automation retrofits concentrate demand.
- Shrink Wrapping:Cryovac and comparable shrink-bag technologies for protein processors seeking retail-ready presentation. Proprietary equipment ties converters to specific film supply agreements.
Modified Atmosphere represents the fastest-growing trajectory. Vacuum Chamber retains entrenched position in high-throughput protein processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat processing clusters in Bavaria and Lower Saxony anchor equipment upgrade cycles as automation retrofits accelerate chamber sealer throughput. Regulatory pressure from Brussels reshapes material specifications across converter networks.
Germany
Automation in meat processing drives chamber sealer upgrades across Bavarian and Lower Saxony processing clusters. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates for multilayer films, forcing material architecture redesigns. Frankfurt-area film extruders pilot mono-material polyethylene structures with nanocomposite barrier coatings.
United States
Food service operators and meal-kit distributors expand vacuum-sealed protein and produce formats for subscription fulfillment. FDA migration limits under 21 CFR govern food-contact substance approvals, extending qualification timelines for reformulated films. Midwest protein packers concentrate demand as direct-store-delivery consolidation compresses order cycles.
Netherlands
Fresh-cut salad processors and artisan bread packers adopt modified atmosphere protocols with nitrogen and carbon dioxide flushing systems. EFSA evaluates recycling process safety for post-consumer content incorporation into new vacuum films. Eindhoven-region pilot lines validate high-barrier polyethylene furanoate thermoformability for bacon and deli formats.
Switzerland
Pharmaceutical distributors specify rigid vacuum containers for temperature-sensitive biologics and parenteral drug distribution. Swissmedic oversees qualification cycles for cold-chain packaging formats. Basel-area logistics hubs concentrate demand for dimensional stability and resealability in premium pharmaceutical applications.
China
Electronics manufacturers deploy vacuum formats for moisture and oxygen exclusion in semiconductor component shipping. SAMR and GB standards govern packaging material safety for export-oriented production. Yangtze River Delta manufacturing hubs concentrate equipment procurement for high-volume contract assembly operations.
Vacuum Packaging Market Key Industry Players
Global majors compete with regional champions across film extrusion networks and equipment manufacturing capabilities. The supplier base organizes around integrated material converters, specialized machinery fabricators, and paper-based sustainable packaging innovators. Three archetypes dominate: resin-integrated multinationals controlling conversion costs, proprietary technology holders locking in protein processor relationships, and fiber-recyclability specialists capturing regulatory-driven specification shifts. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters secure offtake agreements for chemical recycling feedstock.
Within the integrated material tier, Amcor plc and Sealed Air Corporation exemplify contrasting strategic positions. Amcor leverages captive film extrusion networks across Europe and North America to manage resin conversion economics. Sealed Air anchors its market presence through proprietary shrink-bag technology for protein processing applications. Mondi Group occupies a distinct position among fiber-based specialists, targeting kraft-paper vacuum solutions aligned with EU recyclability mandates.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global |
| Mondi Group |
| Winpak Ltd. |
| Coveris |
| ULMA Packaging |
| Klöckner Pentaplast Group |
| Multivac Sepp Haggenmüller SE |
| Others |
Cost & Logistics Intelligence
Resin cost volatility in nylon and polyethylene terephthalate feedstocks cascades through converter pricing tiers as multilayer film structures face recyclability redesign mandates. German meat processors absorb chamber sealer upgrade premiums while Asian electronics manufacturers negotiate spot-market polyethylene sealant layers for semiconductor packaging.
Pricing Analysis
Input-cost pass-through from crude oil derivatives and polymer capacity constraints compresses converter margins on fixed-price contracts with protein packers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade rigid containers from mid-tier flexible bags and commodity shrink-wrap formats. Pricing pressure stems from REACH compliance obligations forcing adhesive and barrier layer reformulations. Food service operators exhibit highest price sensitivity due to subscription fulfillment volume commitments, while Swiss pharmaceutical distributors accept premium positioning for cold-chain dimensional stability.
Supply Chain Analysis
Direct-to-processor channels handle German and US Midwest meat packer demand through integrated tray-sealing and labeling capabilities. Raw material supply concentrates in Germany for film extrusion, China for equipment manufacturing, and the Netherlands for PEF pilot production. Nylon structural plies, EVOH coextrusions, and nanocomposite coatings draw from petrochemical feedstocks tethered to oil price indices. Single-source vulnerability in fluoropolymer-free barrier coating development creates qualification timeline risk. Distribution runs through regional converter networks with vendor-managed inventory programs shifting forecasting risk upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through mono-material polyethylene adoption that satisfies EU sortability standards without sacrificing barrier performance premiums.
For Market Incumbents: Lock in protein processor relationships through proprietary shrink-bag technology and captive film extrusion networks. Invest in chemical recycling offtake agreements to secure multilayer film waste feedstock. Defend against fiber-recyclability specialists by accelerating kraft-paper vacuum solution pilots in Nordic retail channels. For New Entrants and Emerging Players: The mid-tier gap between pharmaceutical rigid containers and economy flexible bags presents white-space opportunity. Target Scandinavian bacon processors and Dutch deli meat converters with modified-atmosphere pouch formats. Pursue direct-store-delivery consolidation through integrated labeling capabilities and vendor-managed inventory programs. For Investors and Strategic Acquirers: Consolidation pressure builds where chemical recycling infrastructure requires balance-sheet capacity for pyrolysis and depolymerization investments. Long-term viability favors converters with backward integration into resin conversion and equipment OEM partnerships. Watch ECHA PFAS restriction timelines as inflection indicator for fluoropolymer-free coating adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Structure Development | Sortability-compliant barrier films open private-label retail positioning under EU Packaging and Packaging Waste Regulation mandates. |
| Chemical Recycling Infrastructure Investment | Pyrolysis offtake agreements create closed-loop feedstock security for converters facing extended producer responsibility schemes. |
| Active Packaging Integration | Oxygen scavenger and freshness indicator migration transforms vacuum formats into sensor-enabled supply chain nodes for protein retail. |
| Pharmaceutical Cold-Chain Expansion | Dimensional stability and resealability specifications capture margin pools in Swiss and Dutch biologics distribution networks. |
| Equipment Automation Retrofit | Chamber sealer throughput upgrades concentrate demand in Bavarian and Lower Saxony processing clusters for labor reduction. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with film extrusion plant managers, meat processor procurement leads, pharmaceutical packaging engineers, and retail category buyers combined with secondary validation from FDA 21 CFR filings, EFSA recycling process safety assessments, EU Packaging and Packaging Waste Regulation drafts, and SEC 10-K disclosures from listed converters. Bottom-up volume modeling and top-down value triangulation anchored segment-level estimates.
Segment-weighting across product type, material architecture, end-use application, and technology format drove the analytical framework over the projection horizon. Flexible bags, rigid containers, vacuum sealers, and pouches each carried distinct growth coefficients reflecting automation retrofit cycles and regulatory compliance timelines. CAGRs derived from equipment procurement patterns, resin cost trajectory assumptions, and adoption curves for modified-atmosphere protocols in fresh-cut produce and artisan bread segments.
Caveats apply where ECHA PFAS restriction enforcement timelines or mechanical recycling infrastructure buildouts could materially shift the outlook. Forecasts rest on assumptions regarding nanocomposite coating scale-up viability and chemical recycling offtake agreement execution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Construction Films Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Fanfold Market
Packaging Materials
Cargo Moisture Control Products Market