
 Card Films Market | 2026-2036
Card Films Market Size, Share, and Industry Trends Forecast 2026-2036
Card Films Market Outlook
ISO/IEC 7810 ID-1 format certification is unwinding competitive access for suppliers lacking qualified lamination and overlay film production. Klöckner Pentaplast Group anchors European supply through captive extrusion lines calibrated to EMV specifications. Innovia Films specializes in high-clarity polyester grades for contactless antenna embedding. Dunmore Corporation controls North American distribution via vertically integrated coating and metallization capabilities.
Card films are multilayer polymer substrates—typically 250–800 micron total thickness—engineered for thermal lamination, print reception, and mechanical durability in credential manufacturing. Polyester dominates contactless applications for dimensional stability during antenna wire embedding, while polypropylene gains share in lower-cost loyalty programs where flex fatigue resistance matters less. Thickness segmentation reveals margin concentration in custom specifications for government ID portfolios requiring embedded holographic security layers.
REACH substance restrictions and EU Green Deal circularity mandates are forcing reformulation of legacy PVC card stocks across European supply chains. EMA and ECHA compliance costs favor larger extruders with dedicated regulatory affairs capacity over regional converters. FDA and EPA frameworks in the US govern food-contact-adjacent retail card programs, creating divergent testing burdens. Stakeholders must monitor polymer pass-through cost trajectories and qualification timelines as substrate substitution accelerates.
Market Dynamics
EMV chip compliance mandates are compressing supplier qualification timelines while REACH substance restrictions force simultaneous substrate reformulation, creating a dual squeeze on extrusion capacity and regulatory bandwidth across card film supply chains.
Growth Catalysts
- Banking sector EMV migration:Payment card issuers in India and Brazil are accelerating PVC and polyester core film procurement to meet chip-card deadlines set by their respective central banks.
- REACH Article 33 phthalate restrictions:European converters are qualifying phthalate-free PVC formulations ahead of ECHA enforcement windows, expanding addressable substrate volumes for compliant extruders.
- China dual carbon policy:Domestic smart card programs under MEE guidelines are redirecting procurement toward bio-based polyester alternatives with verified carbon footprints.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and purified terephthalic acid price swings compress margin predictability for polyester and PVC film producers without long-term offtake contracts.
- Extrusion capacity concentration:Qualified lamination-grade film supply clusters in Germany and China, exposing buyers to single-source risk during logistics disruptions or energy rationing events.
- Legacy PVC incumbency:Decades of optimized print reception and thermal lamination behavior create switching costs that slow bio-based polyester penetration in high-volume banking programs.
Strategic Opportunities
- India financial inclusion programs:Jan Dhan Yojana and RuPay expansion are driving demand for lower-cost polypropylene loyalty cards in tier-2 and tier-3 cities.
- EU Green Deal circularity mandates:CSRD disclosure requirements and extended producer responsibility frameworks create premium positioning for recyclable mono-material card constructions.
- Antenna embedding convergence:Laser-structured copper inlays combined with high-clarity polyester overlays enable thinner contactless credentials for wearable payment devices.
Industry Challenges
- ISO/IEC 7810 qualification timelines:ID-1 format certification for new substrate grades requires 12-18 month testing cycles that delay commercialization of reformulated materials.
- Lamination process revalidation:Banking card manufacturers must recalibrate thermal press parameters for each substrate substitution, consuming engineering resources and production downtime.
- Cross-border chemical compliance:Divergent FDA food-contact rules for retail gift cards and EMA medical device adjacent standards create testing duplication for multi-jurisdiction suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Card Films Market |
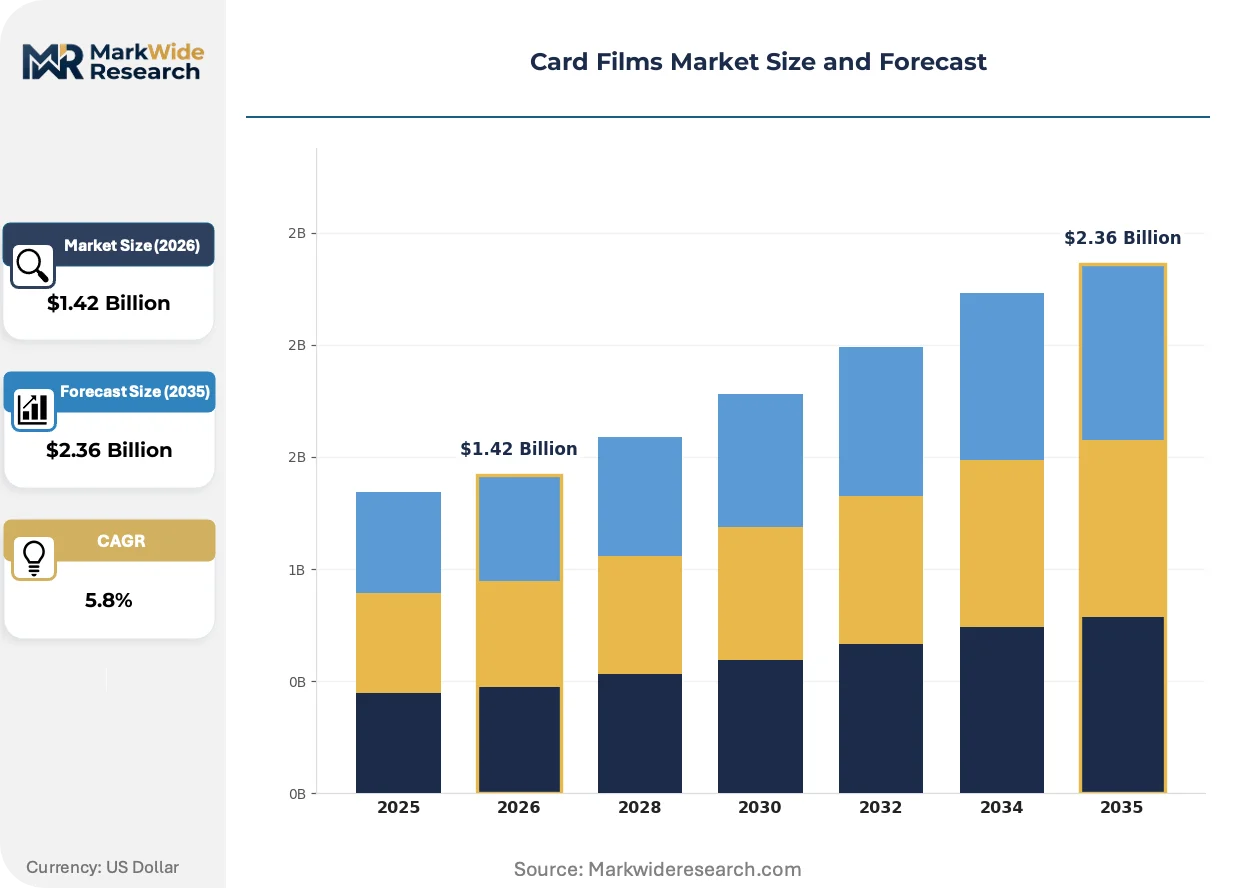
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, PVC, Others End User: Banking, Telecommunications, Retail, Government Application: Identification Cards, Access Control, Membership Cards, Loyalty Programs Thickness: Standard, Thicker, Thinnest, Custom |
| Companies Covered | Dunmore Corporation, Tekra Inc., Klöckner Pentaplast Group, Innovia Films, CCL Industries, D&K Group, Wrapid Manufacturing Ltd, Amcor Plc, Raj Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Card Films Market Strategic Shifts
Substrate chemistry and lamination architecture are undergoing simultaneous transformation as regulatory chemistry restrictions intersect with antenna integration demands and circular economy procurement criteria.
Polylactic acid blends with enhanced thermal stability are displacing conventional PVC in European government ID portfolios where REACH compliance deadlines are non-negotiable. German and French security printers are piloting these formulations for national health card programs, compressing the addressable market for legacy phthalate-containing stocks ahead of ECHA sunset dates.
EU Green Deal circular economy action plan implementation is forcing disclosure of polymer recyclability rates and recycled content percentages across card film supply chains. EMA and ECHA coordinated enforcement is extending from substance restrictions to packaging and end-of-life documentation, compelling extruders to invest in mass-balance certification and chemical recycling partnerships.
Centralized procurement by banking consortiums is consolidating specification-setting power among three to four major payment networks, compressing supplier diversity and accelerating price transparency. This concentration is most visible in China, where UnionPay's unified substrate standards have eliminated regional variation in overlay and core film requirements, forcing smaller extruders to absorb qualification costs or exit the credential supply chain entirely.
Card Films Market Segmentation
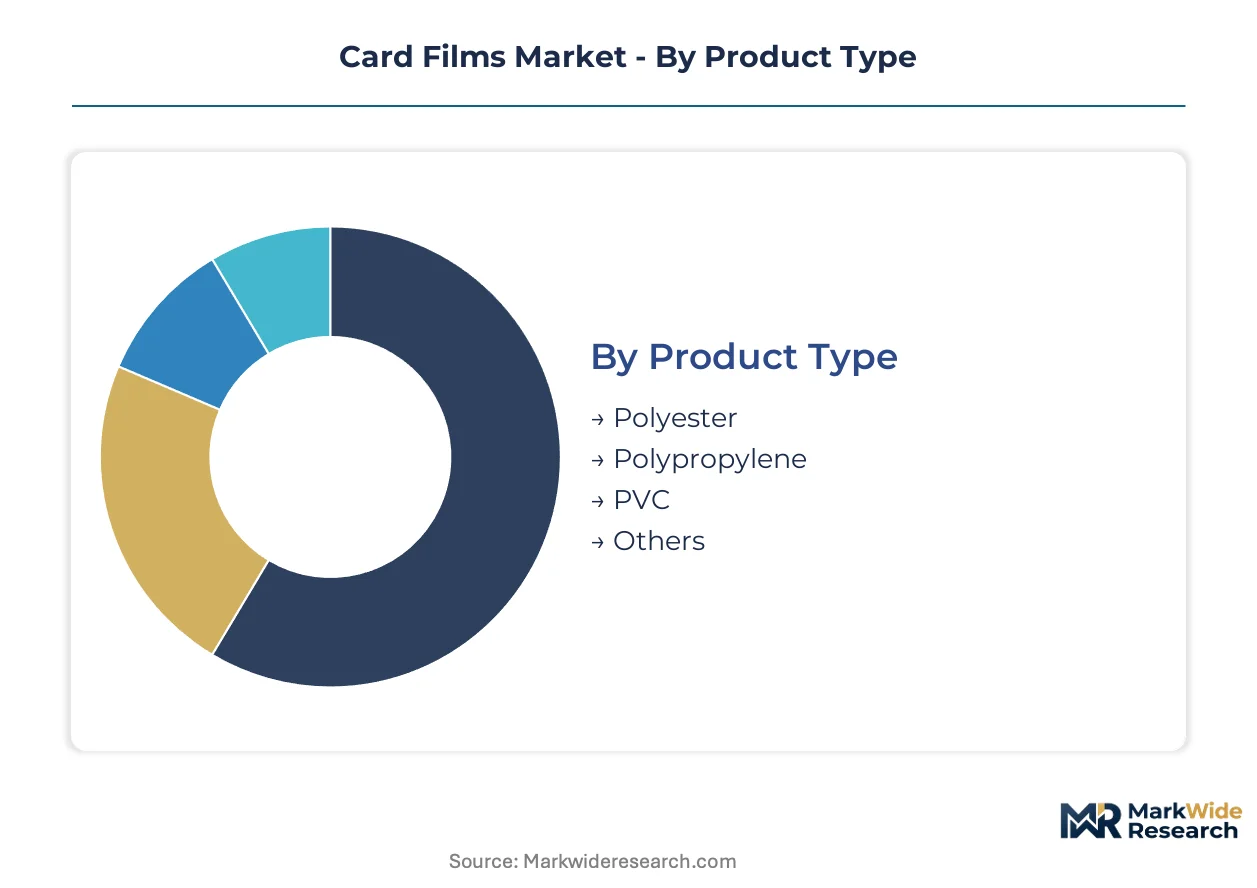
Card film segmentation reveals how substrate chemistry, credential application, and dimensional specification create distinct margin architectures. Procurement patterns diverge sharply between banking-grade EMV compliance and cost-optimized loyalty programs.
Product Type:
Premium margin pools concentrate in specialty polyester grades engineered for contactless antenna embedding and thermal lamination stability.
- Polyester:High-clarity biaxially oriented grades deliver dimensional stability during copper inlay embedding for dual-interface payment cards. UnionPay and RuPay procurement specifications in China and India are standardizing 250-375 micron overlay specifications, compressing supplier qualification windows.
- PVC:Legacy phthalate-containing formulations retain volume dominance in banking programs where decades of optimized print reception create switching friction. REACH Article 33 restrictions are forcing European converters toward phthalate-free alternatives ahead of ECHA enforcement timelines.
- Polypropylene:Lower-density grades serve cost-sensitive retail loyalty programs in India's tier-2 and tier-3 cities under Jan Dhan Yojana expansion.
- Others:Polylactic acid blends and bio-based polyesters are piloting for European government ID portfolios under EU Green Deal circularity mandates.
The dominant share belongs to PVC, while polyester is closing the gap fastest.
End User:
Application-specific certification requirements fragment procurement power across four distinct buyer archetypes with divergent technical specifications.
- Banking:EMV chip compliance mandates from RBI, Brazil's Central Bank, and China's PBOC are compressing supplier qualification timelines for core and overlay films. Payment network consolidation concentrates specification-setting power among three to four major networks.
- Telecommunications:SIM card substrate demand is migrating toward thinner polyester constructions as eSIM adoption displaces physical card volumes in premium handset segments.
- Retail:Gift card programs adjacent to food-contact applications trigger FDA testing burdens in the US, while FSSAI frameworks govern Indian retail card issuance.
- Government:National health and ID card programs in France and Germany are piloting polylactic acid formulations ahead of REACH sunset dates, creating premium positioning for compliant extruders.
Banking commands the largest procurement volume, though government is expanding most quickly.
Application:
Security layer integration requirements stratify margin capture across credential types.
- Identification Cards:Government ID portfolios demand embedded holographic security layers and laser-engraved personalization, requiring custom thickness specifications and extended qualification cycles.
- Access Control:Corporate and facility credentials combine RFID antenna embedding with durability requirements for daily flex cycling.
- Membership Cards:Fitness and hospitality programs prioritize cost efficiency over security integration, favoring standard-thickness PVC constructions.
- Loyalty Programs:High-volume retail issuance in emerging markets drives demand for polypropylene and thin-gauge PVC with minimal security features.
Identification cards retain the highest margin per square meter, with access control gaining share fastest.
Thickness:
Dimensional specification directly determines lamination process compatibility and security layer embeddability.
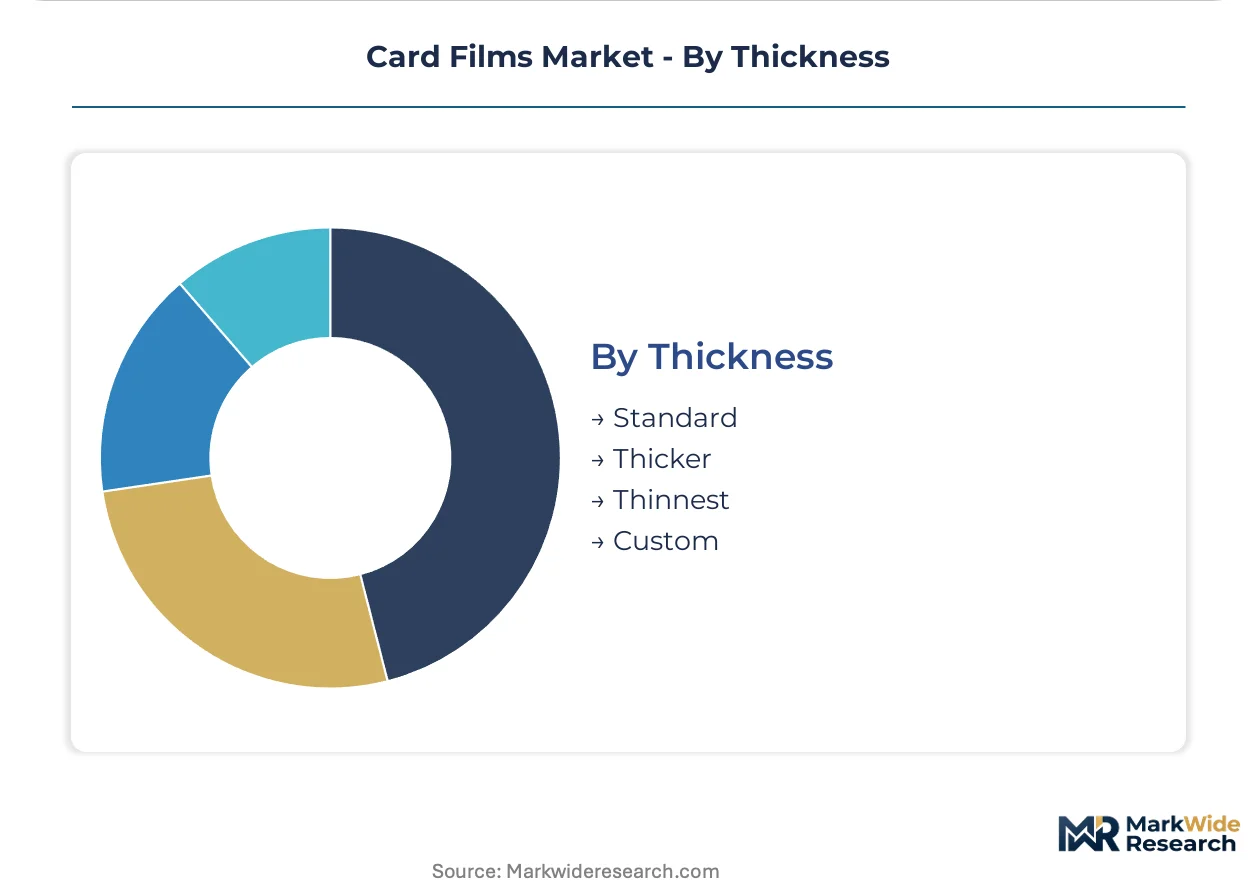
- Standard:760-micron total construction aligns with ISO/IEC 7810 ID-1 format for universal ATM and POS terminal compatibility. Banking EMV migration standardizes procurement around this specification.
- Thicker:800+ micron constructions accommodate embedded holographic foils and tactile security elements for premium government ID portfolios.
- Thinnest:Sub-500 micron specifications enable wearable payment device integration and reduced material costs for disposable retail credentials.
- Custom:Non-standard thicknesses serve antenna embedding convergence for laser-structured copper inlays in next-generation contactless wearables.
Standard thickness dominates issuance volumes, while thinnest specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy and UnionPay standardization are redirecting procurement toward bio-based substrates, while EMV compliance deadlines in India and Brazil compress supplier qualification timelines for core and overlay films.
China
MEE guidelines under dual carbon goals are reshaping procurement for domestic smart card issuance programs. UnionPay's unified substrate standards have eliminated regional variation in overlay specifications, forcing smaller extruders to absorb qualification costs. The Yangtze River Delta hosts the densest concentration of qualified lamination-grade film production.
India
RBI EMV chip compliance mandates are accelerating PVC and polyester core film procurement to meet central bank deadlines. Jan Dhan Yojana and RuPay expansion are driving demand for lower-cost polypropylene loyalty cards in tier-2 and tier-3 cities. Gujarat and Maharashtra host the principal security printing clusters for banking credential production.
Germany
REACH Article 33 phthalate restrictions are forcing converters toward phthalate-free PVC formulations ahead of ECHA enforcement windows. EMA and ECHA coordinated enforcement extends to end-of-life documentation requirements. The Rhine-Main region anchors European supply through captive extrusion lines calibrated to EMV specifications.
United States
FDA food-contact rules for retail gift cards adjacent to food service create testing burdens distinct from banking credential requirements. EPA frameworks govern chemical content disclosure for card stocks used in environmentally sensitive applications. The Midwest industrial corridor maintains vertically integrated coating and metallization capabilities for North American distribution.
Brazil
Brazil's Central Bank EMV migration deadlines are compressing supplier qualification timelines for polyester and PVC core films. ANVISA pharmaceutical-adjacent standards create compliance complexity for health credential programs. São Paulo state concentrates the majority of Latin American card manufacturing and personalization capacity.
Card Films Market Competitive Environment
Player mix skews toward diversified materials conglomerates with captive polymer extrusion capacity. Three to four major payment networks concentrate specification-setting power, compressing supplier diversity. Strategic archetypes include integrated polymer producers with regulatory affairs capacity, specialty film converters with antenna-embedding expertise, and regional distributors with metallization capabilities. Competitive moves center on backward integration into resin supply and mass-balance certification partnerships for circular economy positioning.
Within the integrated extrusion tier, Klöckner Pentaplast Group and Innovia Films exemplify divergent specialization vectors. Klöckner Pentaplast anchors European supply through calibrated production lines. Innovia Films occupies a position in high-clarity polyester grades. Dunmore Corporation represents North American distribution control through coating capabilities.
| Leading Market Players |
|---|
| Dunmore Corporation |
| Tekra Inc. |
| Klöckner Pentaplast Group |
| Innovia Films |
| CCL Industries |
| D&K Group |
| Wrapid Manufacturing Ltd |
| Amcor Plc |
| Raj Incorporated |
| Others |
Value Chain & Pricing Dynamics
Phthalate-free PVC migration under REACH Article 33 is simultaneously relocating qualified extrusion capacity toward Germany and China while compressing margin pools for converters caught between reformulation costs and fixed-price banking contracts. This substitution dynamic concentrates pricing power among integrated producers with captive regulatory affairs capacity, fragmenting procurement leverage for regional distributors dependent on legacy supply relationships.
Pricing Analysis
Certification level creates the primary spread across card film procurement, with ISO/IEC 7810 ID-1 qualified grades commanding substantial premiums over unqualified commodity extrusions. Three-tier pricing structure separates government ID portfolios with embedded holographic security layers from standard banking EMV constructions and economy loyalty programs. Cost compression in the standard tier is intensifying as UnionPay and RuPay procurement consolidation forces volume discounts. Government ID buyers exhibit the lowest price sensitivity due to non-negotiable security specifications, while retail loyalty programs in India's tier-2 cities operate on razor-thin material cost thresholds.
Supply Chain Analysis
BASF Ludwigshafen chemical complex throughput governs European phthalate-free PVC resin availability for qualified film extruders. Qualified lamination-grade production clusters in Germany, China, and the United States, drawing from purified terephthalic acid feedstocks anchored in Asian petrochemical complexes. Single-source vulnerability concentrates in the Yangtze River Delta, where energy rationing events disrupt overlay film shipments to UnionPay personalization bureaus. Distribution runs through vertically integrated security printers with captive metallization and coating capabilities, bypassing independent converters for premium government and banking contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO/IEC 7810 qualification timelines and REACH compliance deadlines have created a bottleneck where regulatory bandwidth, not extrusion capacity, limits market access. Extruders possessing both ECHA-certified formulations and EMV-calibrated production lines command strategic leverage that is difficult to replicate within planning horizons.
For Market Incumbents: Fortify backward integration into bio-based polyester resin supply to secure carbon footprint verification under EU Green Deal circularity mandates. Expand captive extrusion capacity in the Rhine-Main region to capture phthalate-free PVC demand from French and German security printers ahead of ECHA enforcement windows. Klöckner Pentaplast and Innovia Films have anchored this positioning through calibrated production lines and high-clarity grades respectively. For New Entrants and Emerging Players: Regulatory documentation services for mass-balance certification represent a service-layer gap where incumbents under-serve mid-tier converters lacking dedicated compliance teams. India's tier-2 and tier-3 city loyalty card programs under Jan Dhan Yojana expansion offer the most penetrable volume segment, with polypropylene specifications tolerating lower capital intensity. Pursue white-label extrusion partnerships with established metallization houses to bypass ISO/IEC 7810 qualification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty film converters in North America possessing antenna-embedding expertise but lacking European regulatory certification. Long-term viability hinges on circular economy positioning, with mono-material recyclable constructions outperforming multi-layer laminates under extended producer responsibility frameworks. Monitor ECHA sunset date acceleration as the inflection signal for bio-based polyester substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resin Supply | Secures carbon footprint verification for EU Green Deal compliance ahead of ECHA enforcement. |
| Mass-Balance Certification Partnership | Enables circular economy positioning for government ID portfolios under CSRD disclosure requirements. |
| Antenna-Embedding Capacity Expansion | Captures contactless payment migration toward laser-structured copper inlays for wearable devices. |
| Phthalate-Free Formulation Qualification | Preserves banking contract access as REACH Article 33 restrictions eliminate legacy PVC competitors. |
| Regional Extrusion Footprint in India | Addresses RuPay and Jan Dhan Yojana procurement proximity requirements for tier-2 city loyalty programs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extrusion plant managers, procurement leads at security printing houses, regulatory affairs directors at polymer producers, and distribution channel partners serving credential manufacturers. Secondary validation drew from ECHA substance restriction databases, RBI EMV compliance circulars, UnionPay technical specifications, customs trade data for polyester and PVC film shipments, and SEC filings from listed materials conglomerates. Bottom-up volume estimates from individual extrusion lines were triangulated against top-down procurement value assessments from banking consortiums.
Across the analysis window, the forecast framework models polymer chemistry substitution trajectories, credential application mix shifts, and thickness specification migration toward contactless-enabled constructions. Segmentation dimensions include substrate type, end-user sector, security layer integration level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections calibrated to central bank EMV deadline enforcement patterns. Industry-specific inputs encompass petrochemical feedstock price volatility assumptions and qualification timeline compression effects.
Underlying assumptions cover REACH enforcement intensity, UnionPay standardization adherence, and dual carbon policy implementation pace, with deviation risk concentrated in ECHA sunset date acceleration or energy rationing recurrence in Chinese manufacturing clusters. Practitioners should keep alternative scenarios live as MEE guideline revisions and RBI compliance deadline extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Flow Wraps Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Fanfold Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Strip Pack Market
Packaging Materials
Foam Trays Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
PCR Thermoforms Market