
 Global Packaging Foams Market | 2026-2036
Global Packaging Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaging Foams Market Foresight
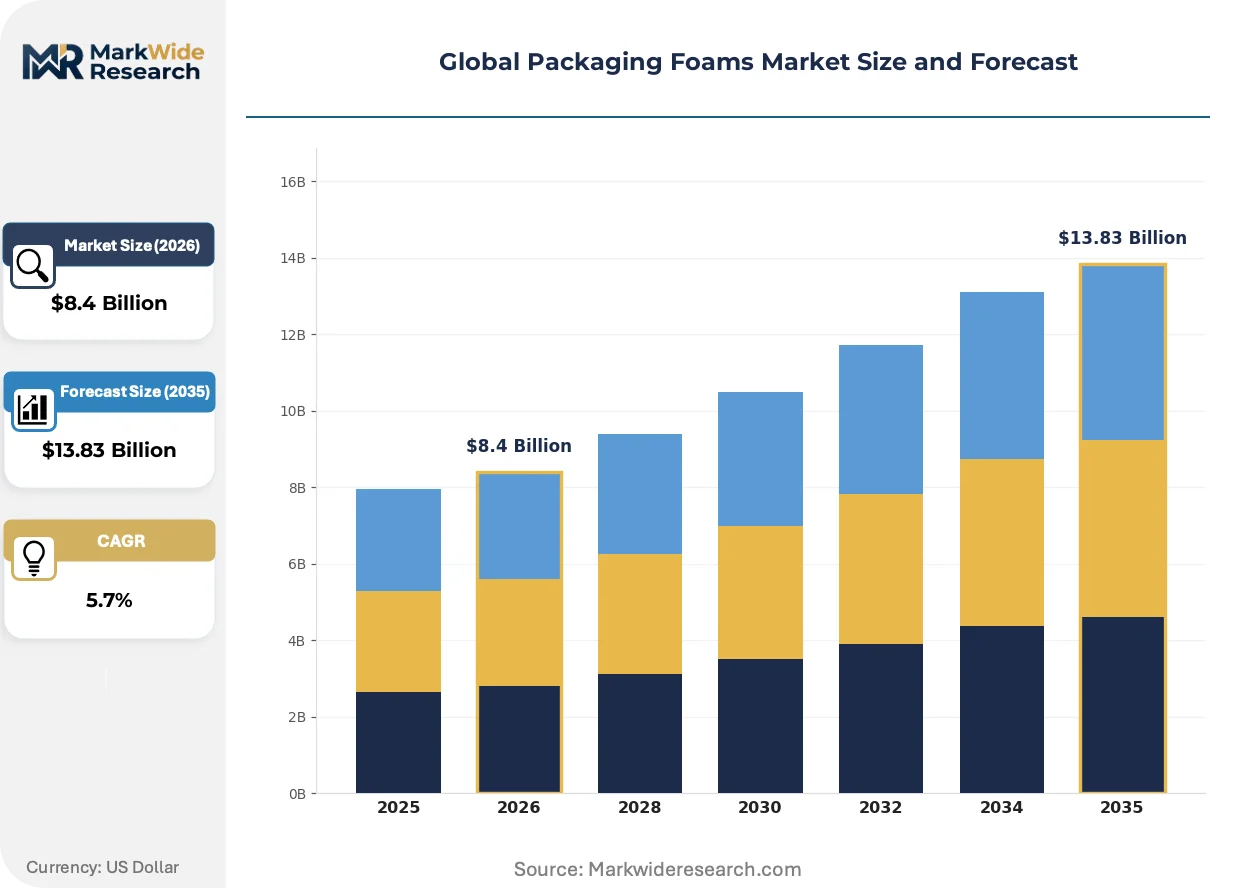
Subscription-based foam recovery and closed-loop refurbishment services is broadening what packaging suppliers monetize beyond virgin material sales. BASF SE leverages its integrated polyol supply chain to control feedstock costs across polyurethane foam grades. Sealed Air sustains technology leadership through proprietary inflatable and foam-in-place systems for electronics protection. Dow anchors its position with polyethylene foam formulations optimized for cold-chain pharmaceutical distribution.
Packaging foams comprise cellular polymer structures engineered with controlled density profiles, typically spanning 15 to 300 kg per cubic meter, manufactured through extrusion, expansion, or molding processes to absorb mechanical shock and thermal energy during transit. Polyurethane foam commands the largest value share due to its versatility across cushioning and insulation applications, while polyethylene foam represents the fastest-expanding category driven by recyclability demands from e-commerce platforms and consumer goods brands. Molded forms capture premium margin pools in medical supplies and electronics protection, where dimensional precision justifies higher unit economics against standard sheet or roll formats.
The EPA regulates volatile organic compound emissions from foam manufacturing facilities under Clean Air Act provisions, while REACH restricts certain flame retardant chemistries in polyurethane systems sold into European consumer goods channels. China's MEE enforces GB standards for foam recyclability that condition market access for imported packaging materials. Stakeholders must monitor evolving extended producer responsibility frameworks and material bans to anticipate which polymer platforms will retain commercial viability across major demand centers.
Market Dynamics
E-commerce fulfillment networks are forcing material transitions away from conventional polystyrene formulations toward recyclable polyethylene and bio-based polyurethane systems. The EU Green Deal and China's GB recyclability standards are accelerating this structural shift across major supply chains.
Growth Catalysts
- REACH compliance mandates:European consumer goods channels are eliminating restricted flame retardant chemistries from polyurethane systems, opening demand for reformulated grades.
- Automotive cluster concentration:Germany's precision-engineered foam packaging requirements from electronics and medical device manufacturing are pulling specialized molded forms.
- Cold-chain pharmaceutical distribution:Temperature-sensitive biologics transport is expanding polyethylene foam insulation demand across North American and Asian logistics networks.
Market Restraints
- Polyol feedstock volatility:BASF SE's integrated supply chain control highlights how upstream petrochemical price swings compress margins for non-integrated foam converters.
- Polystyrene substitution pressure:Extended producer responsibility frameworks in the EU and China are rendering conventional expanded polystyrene economically unviable for consumer packaging.
- Dimensional precision requirements:Medical supplies and electronics protection segments demand molded forms with tight tolerances that sheet extrusion lines cannot achieve without capital-intensive retooling.
Strategic Opportunities
- Closed-loop refurbishment services:Subscription-based foam recovery models allow packaging suppliers to monetize asset recovery beyond virgin material sales.
- India's e-commerce logistics buildout:Fulfillment network expansion in Mumbai and Bangalore is creating demand for protective cushioning in consumer electronics delivery.
- Bio-based polyol convergence:Agricultural feedstock-derived polyurethane formulations are integrating with conventional manufacturing equipment to meet carbon reduction targets.
Industry Challenges
- Multi-jurisdiction compliance timelines:Simultaneous EPA Clean Air Act VOC regulations, REACH restrictions, and China's MEE GB standards create overlapping certification burdens for exporters.
- Legacy equipment incompatibility:Foam-in-place system investments by incumbents create switching costs that slow adoption of next-generation recyclable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaging Foams Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Foam, Polyurethane Foam, Polystyrene Foam, Polyvinyl Chloride Foam, Ethylene Vinyl Acetate Foam Form: Sheet, Block, Molded, Roll, Cushioning Pads Application: Food & Beverage, Electronics Protection, Medical Supplies, Consumer Goods, Industrial Equipment End User: Manufacturers, Distributors, Logistics Providers, Retailers, E-commerce Platforms |
| Companies Covered | BASF SE, Sealed Air, Armacell, Zotefoams plc, Sonoco Products, UFP Technologies, JSP, Smurfit Kappa, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaging Foams Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape polymer platform selection across protective packaging applications.
Bio-based polyurethane formulations derived from agricultural feedstocks are integrating into existing extrusion and molding equipment without process reconfiguration. European appliance manufacturers and North American furniture distributors are adopting these grades at pilot scale. The technology is integrating circular economy mandates into procurement specifications without disrupting established supply relationships.
REACH flame retardant restrictions are eliminating halogenated chemistries from consumer-facing polyurethane applications. Foam converters serving electronics and children's products must reformulate with phosphorus-based or mineral alternatives at higher material cost. German and French packaging suppliers are absorbing compliance costs while pressing for harmonized EU-wide enforcement to prevent regulatory arbitrage.
Direct-to-manufacturer purchasing platforms are compressing distributor margins in standard sheet and roll formats. E-commerce fulfillment operators in the United States and China are consolidating specification power and demanding volume-tiered pricing transparency. This consolidation is most visible in polyethylene foam procurement for last-mile delivery protection, where Amazon and Alibaba logistics subsidiaries now set technical standards that upstream converters must meet.
Global Packaging Foams Market Segmentation
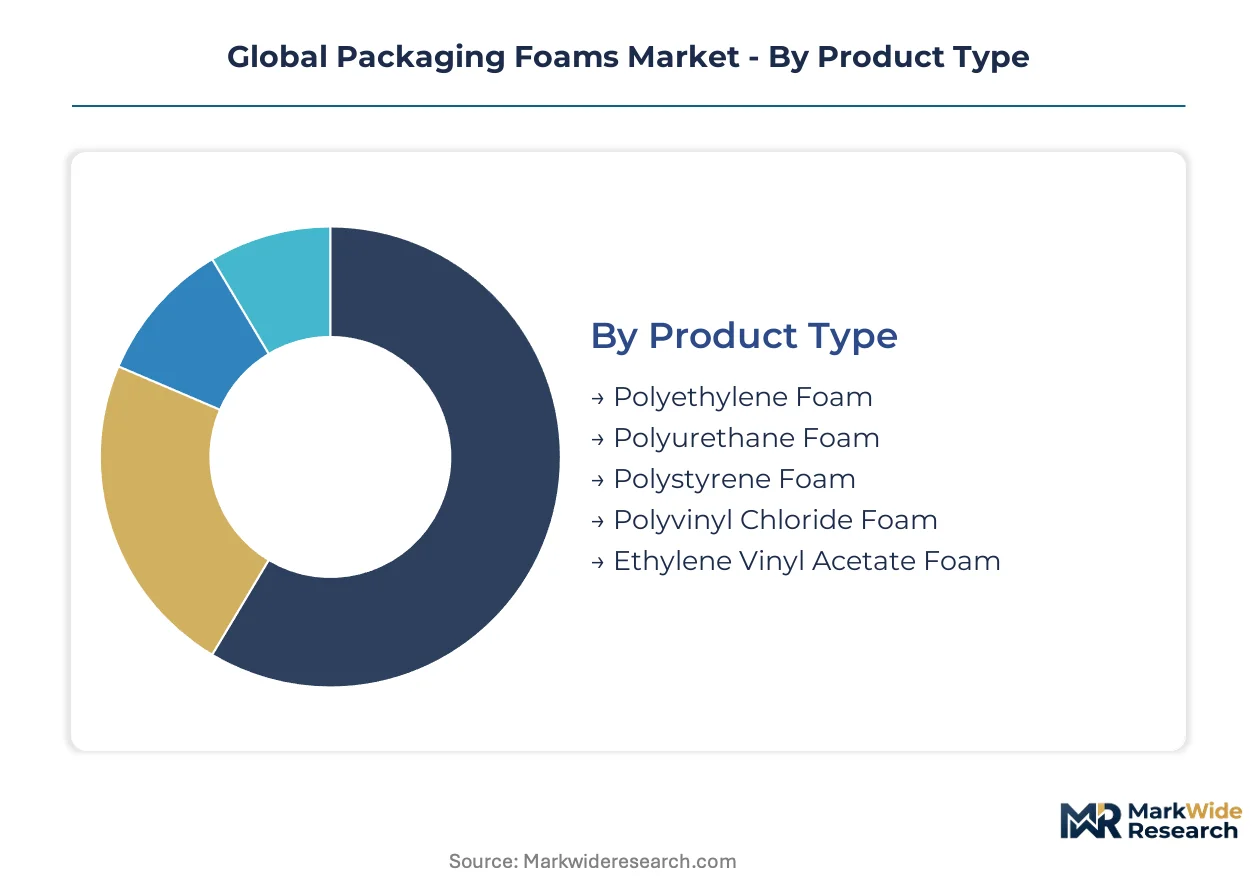
Segmentation in packaging foams reveals how polymer chemistry, physical form, and channel position determine margin capture. Manufacturers configure production assets around density specifications and end-use precision requirements rather than commodity volume plays.
Product Type:
Polymer platform selection governs thermal performance, recyclability compliance, and feedstock cost exposure across manufacturing networks.
- Polyethylene Foam:Closed-cell structure manufactured through extrusion or cross-linking processes delivers moisture resistance and chemical stability. E-commerce fulfillment networks in the United States and China are consolidating procurement specifications around this platform to satisfy extended producer responsibility mandates and GB recyclability standards.
- Polyurethane Foam:Open-cell or rigid formulations produced through polyol-isocyanate reactions offer tunable density gradients from 15 to 300 kg per cubic meter. Automotive electronics clusters in Germany and cold-chain pharmaceutical distributors across North America specify molded polyurethane grades for dimensional precision and thermal insulation performance.
- Polystyrene Foam:Expanded bead structures face substitution pressure from regulatory bans on single-use applications.
- Polyvinyl Chloride Foam:Semi-rigid closed-cell construction serves specialized industrial cushioning with flame-retardant properties.
- Ethylene Vinyl Acetate Foam:Soft, flexible closed-cell material targets sports equipment and consumer goods protection where compression set recovery matters.
Polyurethane leads on scale; polyethylene leads on momentum.
Form:
Physical configuration determines capital intensity and customer switching costs across converter operations.
- Molded:Custom cavity tooling produces dimensionally precise inserts for medical device trays and semiconductor shipping containers. German precision manufacturing clusters and North American biologics distributors absorb premium unit economics for lot-specific packaging validation.
- Sheet:Continuous extrusion outputs standard thickness profiles for high-volume cutting and fabrication. Chinese and United States e-commerce fulfillment centers specify sheet formats for automated die-cutting operations in last-mile protective packaging.
- Block:Bun stock for subsequent fabrication into specialized shapes through CNC or hot-wire cutting.
- Roll:Flexible wound formats for wrapping applications and surface protection during transit.
- Cushioning Pads:Pre-cut inserts for standardized box sizes in consumer electronics and appliance distribution.
Sheet formats dominate volume throughput; molded forms command margin premiums.
Application:
End-use performance specifications drive material certification requirements and customer stickiness.
- Electronics Protection:Anti-static and conductive foam formulations prevent electrostatic discharge damage to semiconductors and displays. Taiwan and South Korea manufacturing clusters specify ionic contamination limits below 10 parts per billion for cleanroom-compatible packaging.
- Medical Supplies:Sterile barrier validation and biocompatibility testing per ISO 10993 standards condition supplier qualification timelines. European and North American medical device manufacturers maintain dual-source molded foam programs to ensure supply continuity for temperature-sensitive diagnostics.
- Food & Beverage:Thermal insulation for cold-chain distribution with FDA and EFSA migration testing compliance.
- Consumer Goods:Cost-optimized cushioning for appliance and furniture protection in retail and direct-to-consumer channels.
- Industrial Equipment:Heavy-duty impact absorption for machinery and automotive components requiring vibration isolation.
Electronics protection concentrates specification power; medical supplies sustain the longest supplier relationships.
End User:
Channel position determines whether procurement emphasizes total cost of ownership or transaction price minimization.
- E-commerce Platforms:Amazon and Alibaba logistics subsidiaries now publish technical standards for recyclable polyethylene foam that upstream converters must certify against. Volume-tiered pricing transparency and sustainability scorecarding compress distributor margins while consolidating specification authority.
- Logistics Providers:DHL, FedEx, and UPS network operations specify damage-rate targets that foam cushioning must achieve across heterogeneous freight profiles. Multi-modal temperature excursions in pharmaceutical lanes drive insulation performance guarantees with financial penalties for excursion events.
- Manufacturers:OEM direct procurement of custom molded forms for inbound component protection and outbound finished goods.
- Distributors:Inventory holding and cutting services for small-lot fabrication customers.
- Retailers:Private-label packaging specifications for store-brand consumer goods protection.
E-commerce platforms concentrate buying power; logistics providers impose performance-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters pull specialized molded foam specifications while China's e-commerce logistics networks drive volume procurement of recyclable polyethylene grades, illustrating how regional industrial structure shapes material demand patterns.
United States
Cold-chain pharmaceutical distribution and semiconductor packaging anchor demand for high-performance insulation and anti-static foam systems. FDA biocompatibility standards and EPA Clean Air Act VOC regulations condition manufacturing facility compliance. The Boston biotech corridor and Austin semiconductor cluster specify lot-validated molded forms for temperature-sensitive biologics and ionic-contamination-controlled electronics protection.
Germany
Automotive electronics and medical device manufacturing concentrate specification power for precision-engineered foam packaging. REACH flame retardant restrictions and EU Green Deal circular economy mandates accelerate reformulation away from halogenated polyurethane chemistries. The Stuttgart automotive cluster and Freiburg medical technology corridor absorb premium unit economics for dimensional precision and sterile barrier validation.
China
E-commerce fulfillment network expansion and consumer electronics manufacturing scale drive polyethylene foam procurement for last-mile protection and inbound component cushioning. MEE GB recyclability standards and dual carbon goals condition material platform selection. The Yangtze River Delta logistics hub and Shenzhen electronics manufacturing cluster consolidate procurement specifications around closed-loop compatible formulations.
Japan
Semiconductor and display manufacturing sustain demand for ultra-clean foam packaging with sub-10 parts per billion ionic contamination limits. METI industrial standards and JIS certification requirements govern supplier qualification timelines. The Kyushu semiconductor foundry cluster and Osaka display manufacturing corridor maintain dual-source molded foam programs to ensure supply continuity.
India
E-commerce logistics buildout in consumer electronics delivery creates demand for protective cushioning in fulfillment networks. BIS standards and PLI scheme incentives for domestic manufacturing influence material sourcing patterns. The Mumbai logistics hub and Bangalore electronics assembly cluster specify cost-optimized polyethylene sheet formats for automated die-cutting operations.
Global Packaging Foams Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical producers controlling upstream polyol supply and downstream foam converters competing on formulation expertise and molding precision. The market structures around three tiers: petrochemical majors with captive feedstock, regional foam specialists with formulation differentiation, and contract manufacturers serving private-label specifications. Capacity expansion in bio-based polyol production and strategic partnerships for closed-loop recovery services represent the dominant competitive moves reshaping positioning.
Within the integrated chemical producer tier, BASF SE anchors upstream control over polyurethane feedstock costs across European manufacturing networks. Sealed Air exemplifies the branded specialist archetype through proprietary foam-in-place and inflatable protection systems. Dow occupies a position in polyethylene foam formulations optimized for temperature-controlled distribution channels. These three represent distinct strategic postures: backward integration, technology differentiation, and application-specific formulation leadership.
| Leading Market Players |
|---|
| BASF SE |
| Sealed Air |
| Armacell |
| Zotefoams plc |
| Sonoco Products |
| UFP Technologies |
| JSP |
| Smurfit Kappa |
| Dow |
| Others |
Supply & Pricing Matrix
Bio-based polyol convergence in polyurethane formulations simultaneously compresses feedstock cost volatility and redistributes supply concentration toward agricultural processing regions. This dual transformation reshapes margin capture across converter networks as petrochemical majors reposition polyol assets.
Pricing Analysis
Capacity additions in China and Germany are reshaping price floors for polyethylene and polyurethane foam grades. Three-tier pricing structure across premium, standard, and economy levels separates lot-validated molded medical forms from commodity sheet extrusions. Price differentiation hinges on ISO 10993 certification tier and volume scale commitments. Pricing pressure stems from e-commerce platform consolidation demanding transparency, with consumer electronics fulfillment operators most price-sensitive and cold-chain pharmaceutical distributors least sensitive due to excursion penalties.
Supply Chain Analysis
China's GB recyclability standards and India's PLI scheme domestic-content mandates are reshaping sourcing patterns for imported packaging materials. Feedstock supply concentrates in China, Germany, and the United States for polyol and polyethylene resin production. Raw material dependencies draw from crude oil derivatives, agricultural feedstocks for bio-based grades, and isocyanate chemistries. Single-source vulnerability runs through concentrated polyol manufacturing. Distribution runs through direct-to-manufacturer platforms and logistics provider networks with consolidated specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through reformulation premiums as REACH flame retardant restrictions eliminate halogenated chemistries and bio-based polyol adoption shifts cost curves.
For Market Incumbents: Hedge against polystyrene substitution pressure by accelerating bio-based polyurethane capacity in European manufacturing networks. Secure backward integration into agricultural feedstock supply through offtake agreements with European and North American crop processors. Certification investment in ISO 10993 biocompatibility tiers protects medical foam margins from Asian contract manufacturer encroachment. For New Entrants and Emerging Players: Capture white space in India's e-commerce logistics buildout where Mumbai and Bangalore fulfillment networks lack qualified local foam converters. Target bio-based polyethylene formulations for Alibaba and Amazon sustainability scorecards as the most penetrable procurement channel. Go-to-market through direct technical sales to logistics subsidiaries bypassing legacy distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional foam specialists with formulation expertise but without captive polyol supply. Five-to-ten year viability favors converters with medical device validation capabilities and closed-loop recovery service infrastructure. Watch for REACH enforcement harmonization across EU member states as the inflection signal for reformulation investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Polyol Capacity Expansion | Positions converters to meet EU Green Deal carbon reduction targets without process retooling. |
| Backward Integration into Feedstock | BASF SE's integrated supply chain demonstrates margin protection against upstream volatility. |
| Closed-loop Recovery Service Launch | Subscription-based foam refurbishment monetizes asset recovery beyond virgin material sales. |
| ISO 10993 Certification Investment | Enables supplier qualification for temperature-sensitive biologics distribution networks. |
| Direct-to-Manufacturer Platform Development | Bypasses distributor margin compression from Amazon and Alibaba consolidation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with foam converter plant managers, procurement leads at e-commerce logistics subsidiaries, medical device packaging engineers, and chemical distribution channel partners. Secondary validation draws from EPA Clean Air Act filings, ECHA REACH registration databases, China MEE GB standard publications, and SEC 10-K disclosures from petrochemical majors. Bottom-up demand modeling and top-down supply triangulation cross-validate segment outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include polymer chemistry platform, physical form configuration, end-use application, and channel position. CAGRs derive from regression analysis against e-commerce penetration rates and regulatory compliance cost curves. Industry-specific inputs incorporate cold-chain pharmaceutical distribution expansion and semiconductor packaging cleanroom requirements.
Polyol feedstock price volatility, REACH enforcement timing, and e-commerce platform procurement consolidation are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory harmonization and bio-based formulation scale-up economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
China Packaging Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Cement Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Strapping Materials Market