
 Aerospace Avionics Market | 2026-2036
Aerospace Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Avionics Market Analysis
Power-by-the-hour leasing and avionics-as-a-service models are reconfiguring capital deployment across the supplier base, lowering barriers for regional operators while concentrating long-term revenue streams with original equipment providers. Collins Aerospace leverages its integrated flight deck architecture to sustain aftermarket attachment rates across Boeing and Airbus platforms. Honeywell International Inc. anchors its position through backward integration into inertial sensors and engine control electronics. Thales competes on sovereign-content requirements in European defense procurement, navigating national security-driven sourcing rules that fragment tender access.
Aerospace avionics encompasses the electronic systems governing aircraft flight, navigation, communication, and mission management, typically operating across MIL-STD-1553 and ARINC 429 data buses with redundancy architectures achieving failure probabilities below 10⁻⁹ per flight hour. These systems serve the fundamental purpose of ensuring safe aircraft operation while optimizing fuel efficiency, reducing crew workload, and enabling precision approach capabilities in all weather conditions. Flight Control Systems command the largest installed base revenue pool given regulatory-mandated refresh cycles, while Integrated Avionics represents the fastest-expanding technology segment as military and commercial operators consolidate discrete boxes into modular open systems architectures. Communication Systems face margin compression from commercial 5G terrestrial alternatives, though satellite connectivity retrofits for narrow-body fleets are creating offset demand.
The FAA mandates DO-178C software assurance and DO-254 hardware verification for all civil avionics certification, creating compliance cost barriers that favor incumbents with established validation infrastructure. EASA's CS-25 updates and the EU AI Act's emerging provisions for autonomous decision-support systems are forcing suppliers to revalidate algorithmic transparency in next-generation flight management computers. China's CAAC bilateral recognition agreements with EASA and the FAA determine market access for Western suppliers serving COMAC's C919 program. Stakeholders must monitor evolving certification reciprocity frameworks and sovereign data-localization requirements as these will determine which suppliers can bid on emerging national aircraft programs.
Market Dynamics
Flight deck consolidation around modular open systems architectures is compressing supplier margins while concentrating design authority with platform-integrated providers who control software-defined functionality roadmaps.
Growth Catalysts
- FAA NextGen Mandate:The Federal Aviation Administration's air traffic modernization timeline is forcing commercial fleet retrofits of GPS-based precision approach systems across narrow-body and regional aircraft categories.
- Power-by-the-hour Leasing:Avionics-as-a-service models lower capital barriers for regional operators while locking in long-term aftermarket revenue streams with original equipment providers.
- Integrated Modular Avionics:Military platform consolidation around ARINC 653 partitioned operating systems reduces line-replaceable unit counts and accelerates technology refresh cycles.
Market Restraints
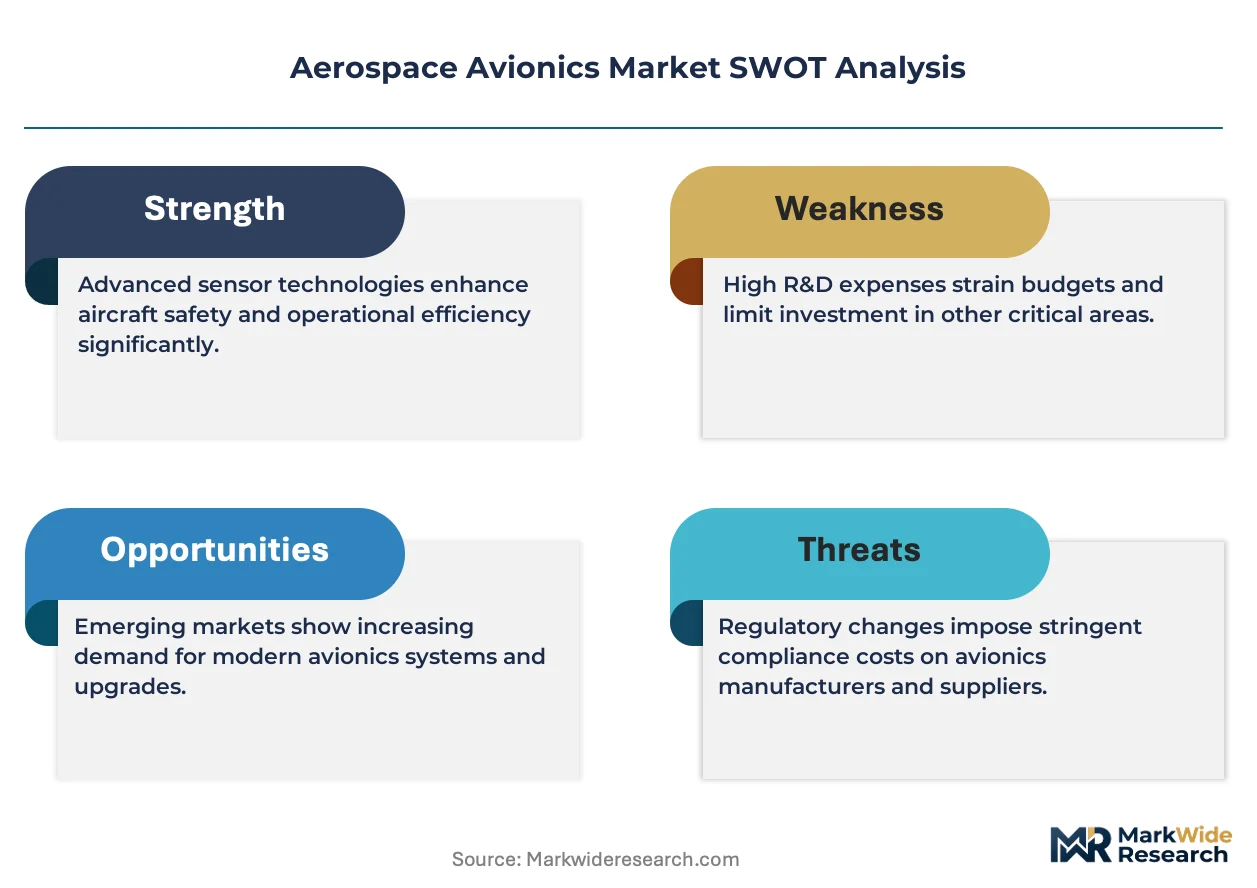
- DO-178C Compliance Costs:FAA software assurance mandates create validation infrastructure barriers that favor incumbents with established certification departments over new entrants.
- Semiconductor Supply Concentration:Radiation-hardened chip fabrication depends on a single qualified foundry in the United States, creating single-point vulnerability for space and defense programs.
- 5G Terrestrial Interference:Commercial cellular spectrum expansion near aviation C-band frequencies threatens radar altimeter reliability and triggers costly filter retrofits.
Strategic Opportunities
- Urban Air Mobility:Emerging eVTOL platforms in the United States require certifiable fly-by-wire systems without the legacy weight constraints of Part 25 transport aircraft.
- EU AI Act Alignment:Algorithmic transparency requirements for autonomous decision-support systems create first-mover advantage for suppliers with explainable flight management architectures.
- Satellite Connectivity Retrofits:Narrow-body fleet operators in Europe are demanding Ka-band terminal upgrades to match passenger connectivity expectations set by wide-body international routes.
Industry Challenges
- DO-254 Hardware Verification Talent:FPGA and ASIC certification expertise concentrates among engineers with 15-plus years of civil aviation program experience, constraining supplier scaling.
- Legacy ARINC 429 Integration:Newer Ethernet-based avionics must maintain backward compatibility with 1970s-era data bus architectures, adding interface complexity and test burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Avionics Market |
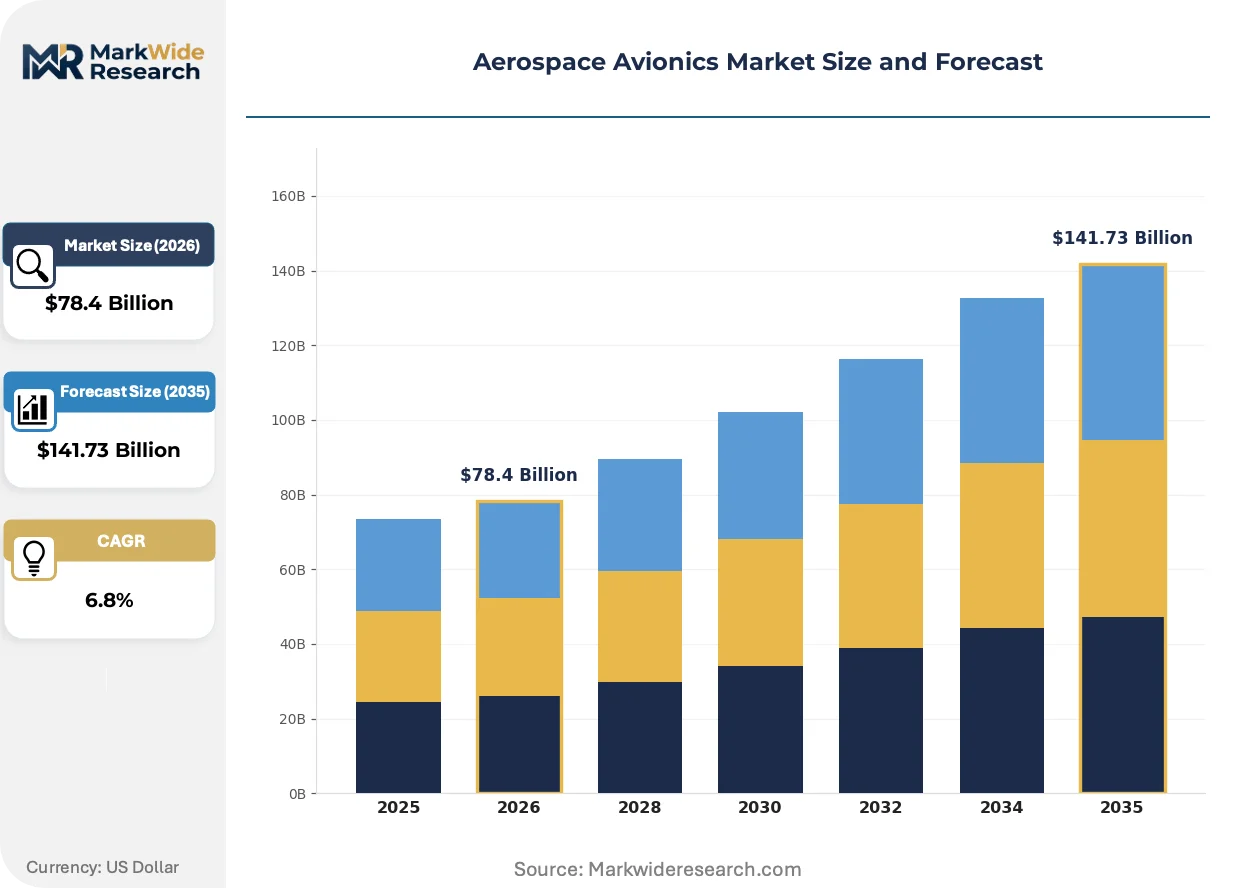
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Systems, Communication Systems, Navigation Systems, Surveillance Systems End User: Commercial Aircraft, Military Aircraft, UAVs, Spacecraft Technology: Digital Avionics, Analog Avionics, Integrated Avionics, Fly-by-Wire Systems Application: Flight Management, Ground Operations, In-flight Entertainment, Safety Systems |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Thales, Garmin Ltd., L3Harris Technologies, RTX, General Electric, Curtiss-Wright, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Avionics Market Emerging Trajectories
Software-defined functionality is displacing hardware-defined boundaries across flight control, navigation, and communication domains, collapsing traditional supplier silos into contested platform-architecture battles.
Multi-core processors with temporal partitioning are rendering obsolete single-core deterministic architectures that dominated safety-critical avionics for three decades. Commercial and military integrators are adopting these processors for consolidated flight management and display processing. This convergence is rendering obsolete the discrete box supplier model that sustained mid-tier avionics vendors through proprietary hardware differentiation.
EASA's CS-25 updates for digital flight controls are mandating formal methods verification for complex electronic hardware, extending certification timelines by 18-24 months for suppliers without established model-based design workflows. European defense procurement is absorbing these requirements fastest through national fighter and rotorcraft programs. Suppliers are responding by acquiring specialized verification automation tools and restructuring hardware design teams around DO-254C anticipation.
Airlines are unbundling avionics maintenance from airframe heavy checks, creating standalone service contracts with dedicated avionics shops rather than OEM-authorized network facilities. This channel fragmentation concentrates in the United States where independent repair stations hold FAA Part 145 certification breadth. Low-cost carriers are driving this shift fastest, trading OEM warranty coverage for 30-40% labor rate savings on line-replaceable unit exchanges.
Aerospace Avionics Market Segmentation
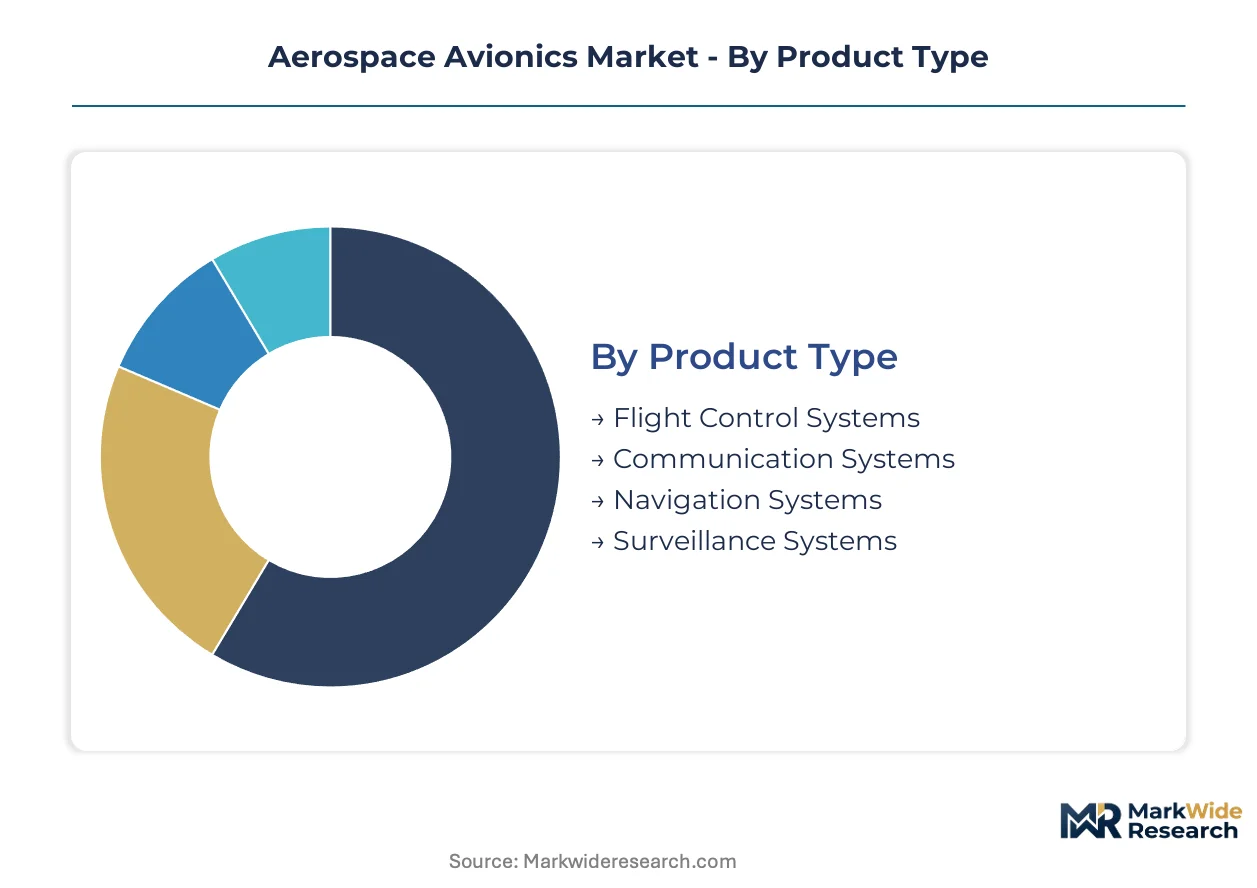
Segmentation in aerospace avionics reveals how regulatory mandates, platform architectures, and operator economics fragment purchasing decisions across fundamentally different technical and commercial requirements. Each dimension exposes distinct supplier capabilities and certification barriers.
Product Type:
Flight decks integrate four functional domains spanning safety-critical control authority through situational awareness augmentation.
- Flight Control Systems:Primary flight computers execute command laws through actuator interfaces with triple-modular redundancy architectures. Commercial retrofits concentrate in the United States around FAA NextGen autopilot upgrades; military demand clusters on fly-by-wire conversions for legacy rotorcraft.
- Communication Systems:VHF, SATCOM, and data link transceivers manage air-ground connectivity across ARINC 739 and ARINC 758 protocols. Narrow-body fleet operators in Europe are driving Ka-band terminal retrofits to match wide-body passenger connectivity standards.
- Navigation Systems:GPS, inertial reference, and multi-mode receivers enable RNAV/RNP precision approaches.
- Surveillance Systems:TCAS, transponders, and weather radar provide traffic and hazard detection.
Established volume favors Flight Control Systems; emerging adoption favors Communication Systems.
End User:
Procurement patterns diverge sharply between commercial operators seeking operational efficiency and defense buyers prioritizing sovereign content.
- Commercial Aircraft:Airlines prioritize integrated flight deck retrofits that reduce fuel burn and crew workload through consolidated display architectures. Fleet modernization concentrates at Boeing and Airbus final assembly lines with aftermarket demand clustering around Dallas-Fort Worth MRO corridors.
- Military Aircraft:Defense procurement mandates domestic supplier participation and ITAR-controlled technology transfer. EASA sovereign-content requirements fragment tender access for non-European suppliers on European fighter programs.
- UAVs:Uncrewed platforms demand certifiable sense-and-avoid systems without pilot-in-the-loop redundancy.
- Spacecraft:Radiation-hardened avionics for launch vehicles and orbital platforms require single-qualified foundry sourcing.
Commercial Aircraft dominates current installed base; UAVs are climbing the fastest on eVTOL platform proliferation.
Technology:
Architecture evolution is collapsing hardware-defined boundaries into software-configurable platforms.
- Digital Avionics:Microprocessor-based systems with ARINC 653 partitioned operating systems enable mixed-criticality consolidation. DO-178C certification costs favor incumbents with established validation infrastructure in the United States.
- Integrated Avionics:Modular open systems architectures reduce line-replaceable unit counts through shared processing resources. Military platforms are adopting these most aggressively to accelerate technology refresh cycles.
- Analog Avionics:Discrete component systems persist in legacy aircraft and cost-sensitive retrofits.
- Fly-by-Wire Systems:Electronic flight control replaces mechanical linkages with digital command paths.
Digital Avionics commands current revenue concentration; Integrated Avionics shows steepest expansion trajectory.
Application:
Functional deployment spans pilot-facing operations through passenger-experience systems with diverging certification rigor.
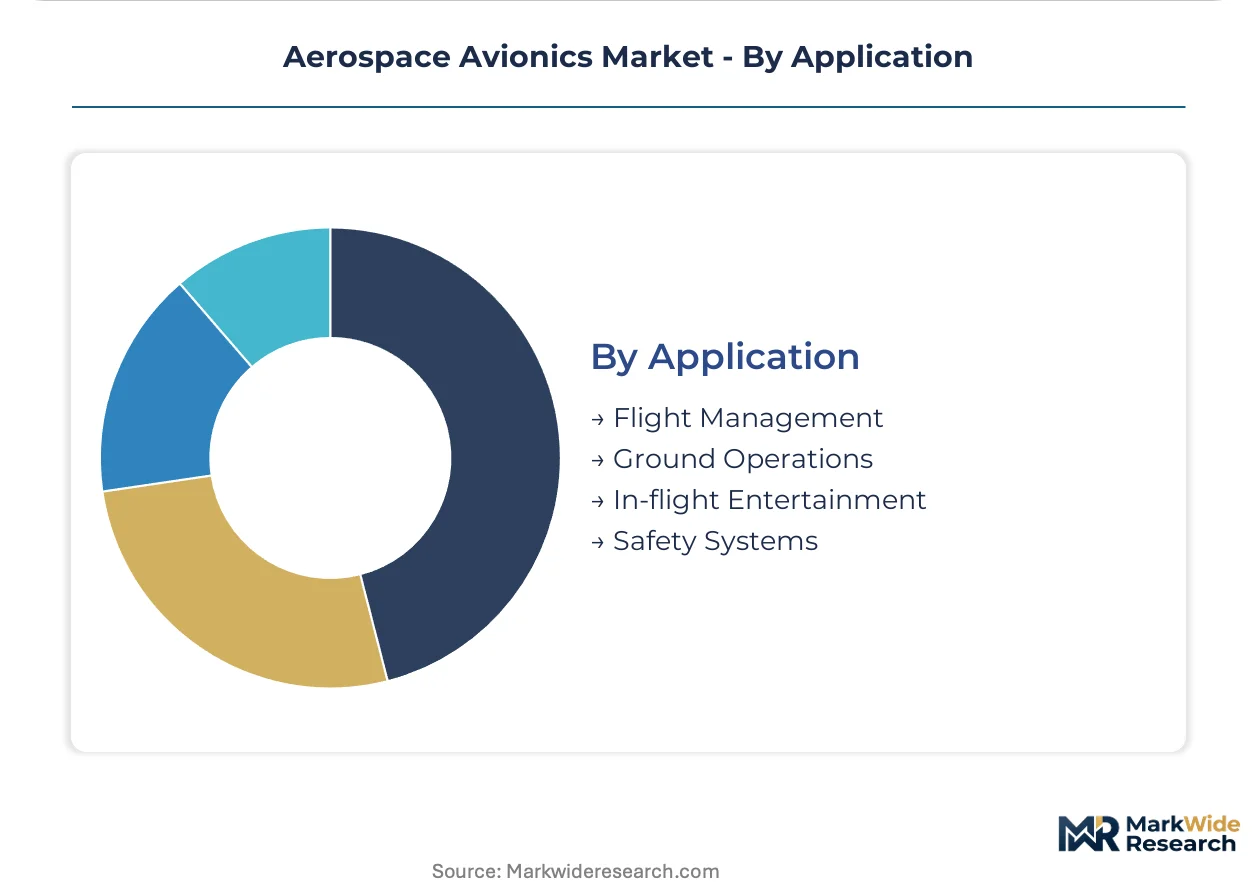
- Flight Management:FMS computers optimize trajectory, fuel, and navigation through algorithmic flight planning. EU AI Act transparency requirements are forcing revalidation of autonomous decision-support architectures for European operators.
- Safety Systems:Terrain awareness, windshear detection, and emergency descent automation carry highest design assurance levels. Regulatory mandates drive mandatory retrofit timelines independent of economic cycles.
- Ground Operations:Electronic flight bags and ground proximity systems support taxi and pre-flight phases.
- In-flight Entertainment:Passenger connectivity and content delivery systems face margin compression from commercial 5G terrestrial alternatives.
Safety Systems maintains non-discretionary demand; Flight Management is gaining share fastest on algorithmic advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in aerospace avionics tilts toward United States suppliers commanding premium rates for DO-178C-certified systems, while Chinese manufacturers compete on cost for COMAC platform content. This asymmetry shapes procurement patterns across national aircraft programs.
United States
FAA NextGen mandates drive GPS-based precision approach retrofits across narrow-body fleets. Defense procurement concentrates in Seattle, Wichita, and Dallas-Fort Worth corridors where Boeing, Spirit AeroSystems, and American Airlines MRO operations cluster. ITAR-controlled technology transfer rules limit foreign supplier participation in military programs.
France
EASA CS-25 certification updates for digital flight controls accelerate technology refresh cycles on Airbus final assembly lines. Thales leverages sovereign-content requirements to secure European fighter program avionics tenders. Toulouse and Paris-Saclay aerospace clusters host concentrated flight control system design authority.
Germany
Luftwaffe platform modernization and Airbus Defence programs sustain demand for integrated modular avionics. National security-driven sourcing rules fragment tender access for non-European suppliers. Munich and Hamburg aerospace corridors concentrate hardware verification expertise for DO-254 compliance.
China
COMAC C919 program expansion creates captive demand for avionics suppliers navigating CAAC-EASA-FAA bilateral recognition frameworks. Domestic suppliers capture increasing content share as certification reciprocity agreements mature. Shanghai and Xi'an aerospace clusters concentrate C919 subsystem integration activity.
United Kingdom
Tempest fighter program and RAF platform upgrades sustain sovereign avionics development. BAE Systems anchors national supply chain for mission-critical electronic systems. Farnborough and Bristol corridors concentrate flight control and surveillance system engineering talent.
Aerospace Avionics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, processors, and verification services. The vendor base organizes into three tiers: full-flight-deck architects controlling software-defined roadmaps; subsystem suppliers with certified hardware platforms; and specialized verification houses addressing DO-178C and DO-254 compliance bottlenecks. Consolidation pressure favors platform-integrated providers with established FAA validation infrastructure. Competitive moves center on backward integration into radiation-hardened semiconductors and acquisition of model-based design automation tools.
Among diversified technology conglomerates, Honeywell International Inc., Collins Aerospace, and Thales occupy positions spanning commercial and defense avionics. Honeywell exemplifies the component-integrated archetype through captive inertial sensor production. Collins Aerospace represents platform-architecture dominance with consolidated flight deck offerings across Boeing and Airbus programs. Thales anchors European sovereign-content positioning, navigating national security procurement rules that shape tender access patterns.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Thales |
| Garmin Ltd. |
| L3Harris Technologies |
| RTX |
| General Electric |
| Curtiss-Wright |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Undercapacity at radiation-hardened semiconductor foundries in the United States is compressing supplier margins while amplifying pricing power for DO-178C-certified system integrators serving FAA-mandated retrofit programs.
Pricing Analysis
Configured-to-order flight control systems command premiums of 40-60% above standard catalog avionics, with price differentiation driven by certification grade and customization level. Three-tier pricing structure across premium DO-254 verified hardware, standard commercial-off-the-shelf modules, and economy-grade retrofit kits dominates procurement. Pricing pressure stems from power-by-the-hour leasing models that shift capital burden to suppliers. Regional operators exhibit highest price sensitivity, while flag carriers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from Tier 1 platform integrators cascade stress to component suppliers, with supply-chain finance facilities emerging as critical liquidity bridges. Radiation-hardened chip fabrication draws from a single qualified foundry in the United States, with FPGA packaging and ceramic substrate sourcing concentrated in Japan and Germany. Single-source vulnerability for space-grade semiconductors creates systemic exposure. Distribution runs through OEM-authorized service networks and independent FAA Part 145 repair stations competing on labor rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FAA and EASA certification entrenchment creates switching costs that lock fleet operators into incumbent supplier ecosystems for decades-long platform lifecycles.
For Market Incumbents: Entrench market position through backward integration into inertial sensor production and captive radiation-hardened semiconductor sourcing. Acquire specialized DO-254 verification automation tools to compress certification timelines against emerging model-based design competitors. Threats from Chinese avionics suppliers on COMAC platforms demand accelerated technology refresh roadmaps. For New Entrants and Emerging Players: Build out certifiable fly-by-wire architectures for eVTOL platforms in the United States, where legacy Part 25 weight constraints do not apply. Urban air mobility represents the most penetrable segment given greenfield certification pathways. Partner with emerging air taxi operators on joint development agreements to amortize validation costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated providers with power-by-the-hour contracts spanning 10-15 year fleet lifecycles. Target acquisition candidates with established FAA validation infrastructure and aftermarket attachment rates above 70%. Monitor CAAC-EASA bilateral recognition progress as inflection signal for Western supplier access to COMAC programs.| Strategic Initiative | Industry Significance |
|---|---|
| DO-254 Verification Automation Acquisition | Compresses hardware certification timelines by 18-24 months for EASA CS-25 compliance. |
| Radiation-Hardened Semiconductor Backward Integration | Captures margin pool and eliminates single-foundry supply risk for space programs. |
| eVTOL Platform Partnership | Positions suppliers for Urban Air Mobility certification without legacy weight constraints. |
| Power-by-the-Hour Service Model Expansion | Locks in long-term aftermarket revenue streams with regional airline operators. |
| EU AI Act Algorithmic Transparency Investment | Creates first-mover advantage for explainable flight management architectures in Europe. |
Methodological Framework
Cross-validation between primary interviews with avionics program managers at Boeing and Airbus Tier 1 suppliers and secondary validation through FAA certification databases and EASA CS-25 amendment filings anchors the qualitative findings. Stakeholder input draws from flight control system engineers, airline fleet modernization directors, MRO procurement leads at Dallas-Fort Worth corridor facilities, and regulatory affairs specialists. Secondary sources include DO-178C and DO-254 guidance documents, SEC 10-K filings from diversified avionics conglomerates, and customs trade data on radiation-hardened semiconductor imports. Bottom-up platform content analysis triangulates against top-down fleet retrofit projections.
Calibration against historical certification timelines and fleet replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology architecture, and application function. CAGRs derive from installed base refresh rates and technology substitution curves. Industry-specific inputs incorporate FAA NextGen mandate compliance deadlines and EASA sovereign-content procurement thresholds.
Practitioners should monitor CAAC bilateral recognition negotiations and radiation-hardened foundry capacity expansion for early signals of supply constraint easing. Forecasts reflect assumptions on certification reciprocity stability and semiconductor supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Customized Avionic Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Electronic Flight Instrument System Market
Avionics
Aircraft EMI Shielding Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Global Helicopter Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Europe Aircraft Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market