
 Europe Military Aircraft Communication Avionics Market | 2026-2036
Europe Military Aircraft Communication Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Aircraft Communication Avionics Market Analytics
Software-defined radio architecture is reshaping how military aircraft communication avionics are engineered and fielded across European defense programs. Thales Group leverages its sovereign French supply base to dominate national fighter and transport platforms. BAE Systems anchors UK-specific programs through deep integration with the Royal Air Force's Tempest and Typhoon fleets. Leonardo S.p.A. competes in tactical datalink segments where its airborne networking solutions serve Italian and export customers.
Europe military aircraft communication avionics encompasses the electronic subsystems enabling secure voice, data, and video transmission between airborne platforms, ground stations, and satellite networks, typically operating across VHF/UHF/L-band spectra with anti-jam and low-probability-of-intercept waveforms. These systems serve the primary purpose of maintaining command-and-control continuity in contested electromagnetic environments where commercial standards fail. Radio communication systems remain the largest product category due to fleet-wide retrofit cycles across aging Panavia Tornado and early Eurofighter Typhoon airframes. Satellite communication represents the fastest-expanding technology segment as beyond-line-of-sight requirements grow for dispersed NATO operations over the Arctic and Baltic theaters. Mesh networking is gaining traction in unmanned combat air vehicle programs where ad-hoc formation relay replaces fixed infrastructure.
EU Green Deal aviation sustainability targets and the F-Gas Regulation are pressuring manufacturers to phase out high-global-warming-potential coolants in avionics thermal management, altering component specifications and supplier qualification paths. EASA military certification frameworks and national military airworthiness authorities in France, the United Kingdom, and Germany maintain divergent security clearance standards that fragment procurement and complicate multinational platform integration. Stakeholders must monitor how the EU's forthcoming Critical Raw Materials Act reshapes semiconductor and rare earth sourcing for gallium nitride power amplifiers and advanced encryption chipsets.
Market Dynamics
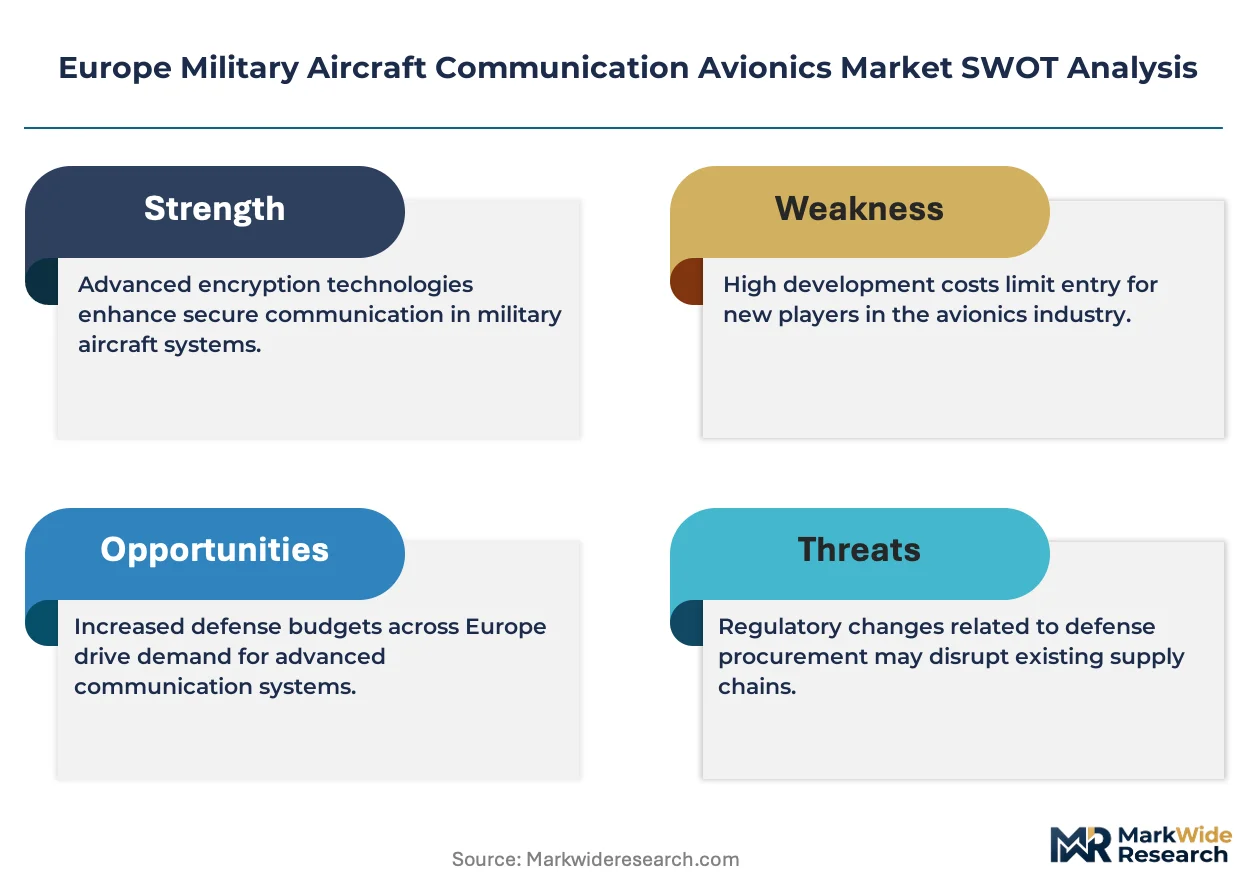
Software-defined radio architecture is collapsing the traditional hardware refresh cycles that once governed European military avionics procurement, compressing capability insertion timelines from platform-centric overhauls into modular software updates.
Growth Catalysts
- European Defence Fund allocations:The EU's pooled procurement mechanism is accelerating cross-border standardization for encrypted wideband systems across NATO air forces.
- Fighter modernization mandates:Aging Panavia Tornado and early Eurofighter Typhoon fleets require fleet-wide radio communication retrofits to maintain electromagnetic spectrum dominance.
- Baltic and Arctic theater dispersion:Beyond-line-of-sight satellite communication demand is intensifying as dispersed NATO operations stretch legacy ground infrastructure.
Market Restraints
- Gallium nitride supply concentration:Rare earth processing bottlenecks in China constrain power amplifier production for advanced encryption chipsets.
- F-Gas Regulation compliance costs:The EU's phasedown of high-global-warming-potential coolants forces thermal management redesigns across qualified avionics suppliers.
- Divergent national security clearances:France's ANSM, Germany's BAAINBw, and UK military airworthiness authorities maintain incompatible certification standards that fragment multinational platform integration.
Strategic Opportunities
- Unmanned combat air vehicle mesh networking:Ad-hoc formation relay architectures replace fixed infrastructure in next-generation drone programs.
- Critical Raw Materials Act reshoring:The EU's forthcoming semiconductor and rare earth sourcing mandates will restructure gallium nitride supply chains toward European foundries.
- Permanent Structured Cooperation frameworks:PESCO's joint capability development clusters create pooled demand for interoperable tactical datalink systems.
Industry Challenges
- Embedded systems cybersecurity certification:EASA military frameworks and national authorities impose divergent encryption validation timelines that delay fielding.
- Legacy platform software integration:1980s-era bus architectures in Tornado and early Typhoon airframes resist modern wideband waveform implementation without airframe modification.
- Skilled radio frequency engineering scarcity:Gallium nitride amplifier design and low-probability-of-intercept waveform development talent concentrates within a handful of defense primes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Aircraft Communication Avionics Market |
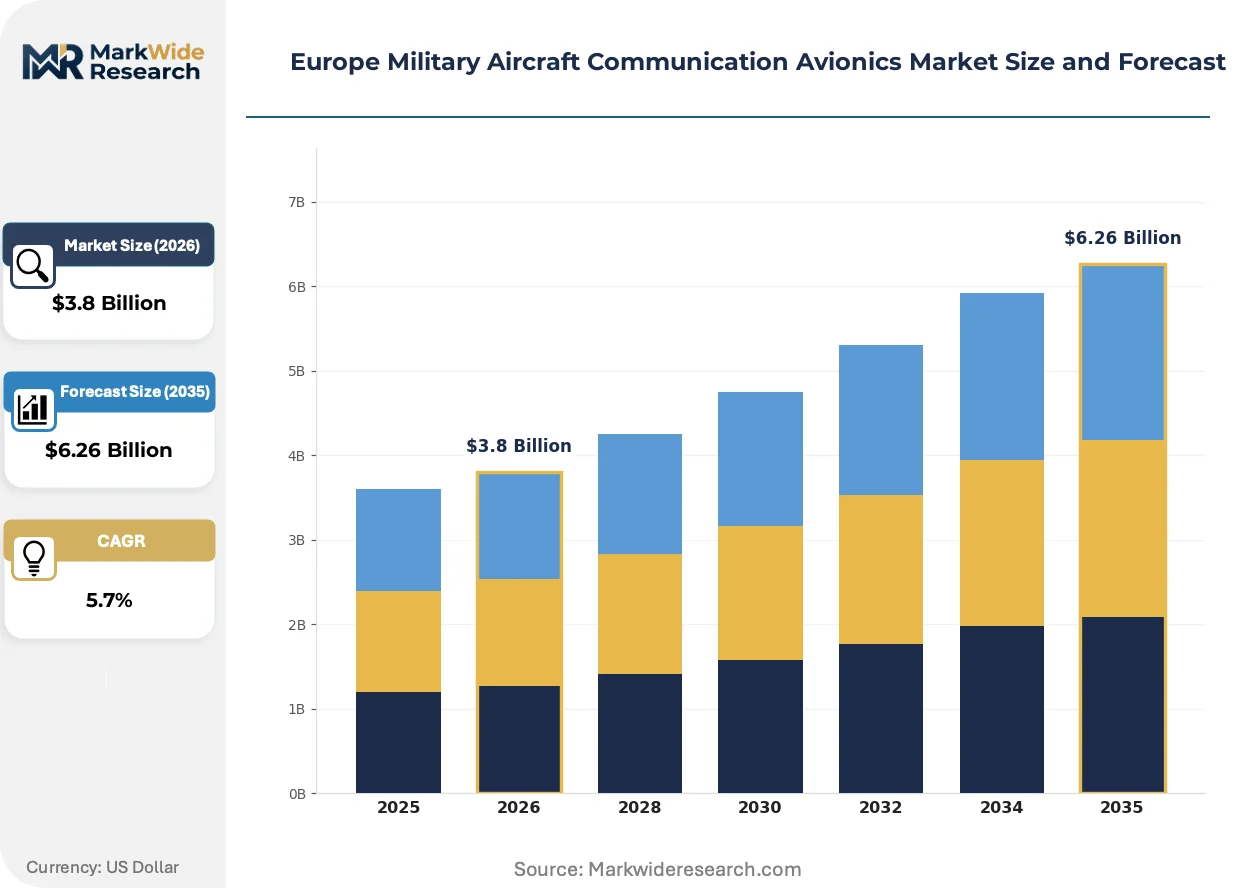
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Communication Systems, Data Link Solutions, Integrated Communication Systems, Intercom Systems Technology: Frequency Hopping, Secure Voice Communication, Satellite Communication, Mesh Networking End User: Government Agencies, Defense Contractors, Military Organizations, Research Institutions Delivery Mode: On-Premises Solutions, Cloud-Based Solutions, Hybrid Solutions, Direct Integration |
| Companies Covered | Thales Group, BAE Systems, Leonardo S.p.A., Safran Electronics & Defense, Airbus SE, L3Harris Technologies, Honeywell International, Collins Aerospace, Rheinmetall, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Aircraft Communication Avionics Market Evolving Landscape
European military avionics engineering is pivoting from hardware-defined platforms to software-centric architectures that enable rapid threat-response updates without airframe downtime.
Software-defined radio is collapsing the distinction between voice, data, and video transmission hardware into unified programmable platforms. NATO air forces are adopting these architectures for fighter and transport fleets to compress capability insertion from years to months. This convergence is collapsing procurement cycles as modular waveform libraries replace dedicated radio boxes.
REACH and the F-Gas Regulation are forcing thermal management redesigns across avionics component specifications. Manufacturers must qualify alternative coolants and heat sink materials that satisfy both electromagnetic performance and environmental compliance. Fighter and transport platform programs in France, Germany, and the United Kingdom are absorbing these redesign costs into current upgrade cycles.
Defense procurement offices are consolidating vendor relationships around full-lifecycle support contracts that bundle hardware, software, and cybersecurity maintenance. Traditional transactional equipment purchases are yielding to performance-based agreements where primes guarantee spectrum dominance outcomes. This shift is most visible in UK Tempest and Franco-German FCAS program sourcing strategies.
Europe Military Aircraft Communication Avionics Market Segmentation
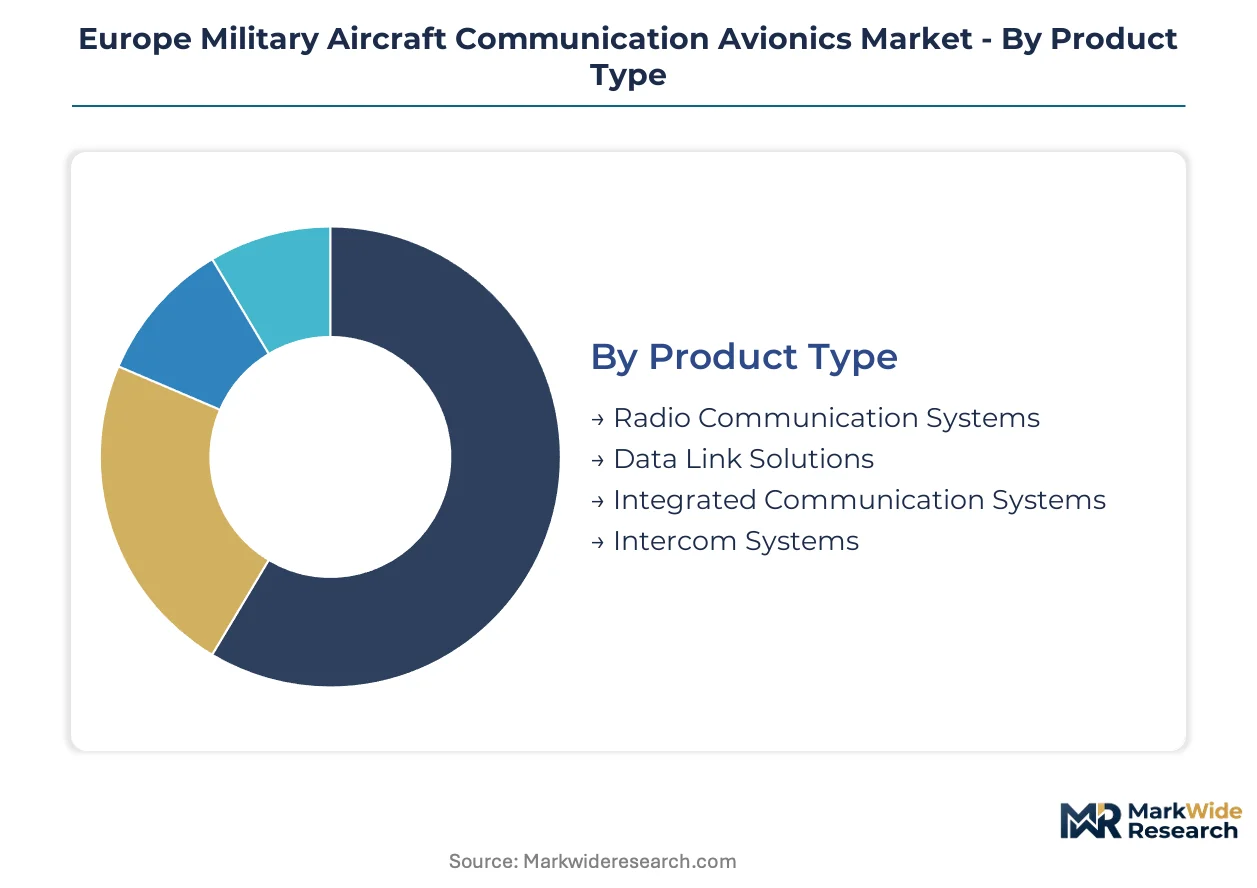
Segmentation in Europe military aircraft communication avionics reveals how procurement priorities diverge across platform types, electromagnetic spectrum requirements, and operational security mandates. Each dimension shapes supplier qualification paths and technology roadmaps differently across NATO air forces.
Product Type:
Cost tier stratification separates fleet-wide retrofits from specialized integrated architectures in European defense procurement.
- Radio Communication Systems:These VHF/UHF/L-band transceivers handle secure voice and tactical data exchange across fighter, transport, and rotary-wing platforms. Demand concentrates in Germany and the United Kingdom where Panavia Tornado and early Eurofighter Typhoon fleets require electromagnetic spectrum upgrades to maintain NATO interoperability. The EU's European Defence Fund accelerates cross-border standardization for encrypted wideband waveforms.
- Data Link Solutions:Tactical datalink systems enable machine-to-machine information exchange between airborne platforms and ground command nodes. French and Italian procurement prioritizes Link-16 and future NATO Universal Command and Control Interface compliance for Rafale and Eurofighter networks. Beyond-line-of-sight requirements for Baltic and Arctic operations intensify adoption.
- Integrated Communication Systems:Unified architectures consolidating radio, satellite, and intercom functions into single avionics suites.
- Intercom Systems:Internal crew communication networks enabling coordinated operations in multi-seat fighter and transport aircraft.
Radio Communication Systems command the established base. The steepest expansion runs through Data Link Solutions.
Technology:
Application maturity varies sharply across electromagnetic protection methods, with software-defined architectures displacing legacy hardware.
- Frequency Hopping:Anti-jam spread-spectrum techniques rapidly switch transmission frequencies to evade electronic warfare threats. German BAAINBw and French ANSM certification mandates drive retrofit demand across legacy fleets operating in contested European airspace. Integration complexity with 1980s-era bus architectures constrains deployment timelines.
- Satellite Communication:Beyond-line-of-sight connectivity via military and commercial satellite constellations. NATO dispersed operations over the Arctic Circle and Baltic states stretch ground infrastructure limits, concentrating procurement in Norway, Poland, and Baltic members. REACH and F-Gas Regulation compliance adds thermal management redesign costs.
- Secure Voice Communication:Encrypted audio transmission resistant to interception and decryption.
- Mesh Networking:Ad-hoc relay architectures enabling formation-wide connectivity without fixed infrastructure.
Frequency Hopping anchors current fleet readiness. Satellite Communication climbs the fastest as theater dispersion accelerates.
End User:
Customer type determines security clearance depth, lifecycle support expectations, and funding stability in European procurement cycles.
- Military Organizations:National air forces and joint command structures operating fighter, transport, and surveillance fleets. France, the United Kingdom, and Germany anchor demand through domestic prime relationships and sovereign supply chain requirements. Permanent Structured Cooperation frameworks create pooled procurement mechanisms for interoperable systems.
- Defense Contractors:Prime integrators and subsystem suppliers managing platform-level avionics integration. UK Tempest and Franco-German FCAS programs consolidate vendor relationships around full-lifecycle performance contracts. Cybersecurity maintenance obligations extend traditional equipment purchase timelines.
- Government Agencies:National defense ministries and cross-border EU bodies coordinating multinational standardization.
- Research Institutions:Academic and government laboratories developing next-generation waveforms and encryption methods.
Military Organizations dominate committed volume. Defense Contractors capture the most rapid capability insertion cycles.
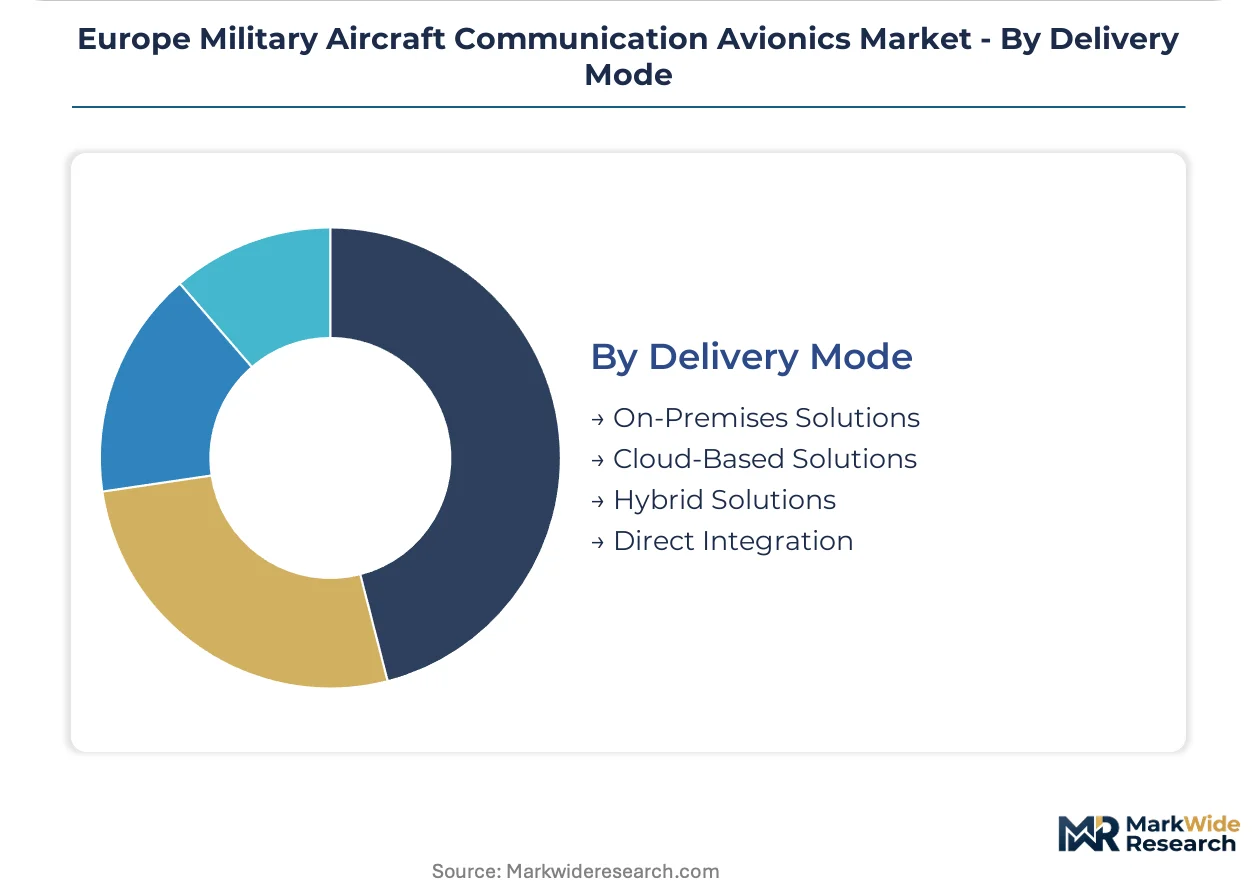
Delivery Mode:
Supply concentration in qualified European foundries shapes how integration architectures reach fielded platforms.
- On-Premises Solutions:Hardware installed directly onto aircraft with dedicated processing and storage. French and German fighter programs favor this model for sovereign control over encryption key management and waveform libraries. EASA military certification and national airworthiness authorities impose divergent validation timelines.
- Hybrid Solutions:Blended architectures combining edge processing with cloud-connected updates. UK Royal Air Force experimentation with rapid software refresh cycles drives adoption for threat-response agility. Critical Raw Materials Act reshoring mandates will restructure semiconductor sourcing for these systems.
- Cloud-Based Solutions:Remotely hosted processing for ground-based mission planning and debrief.
- Direct Integration:Supplier-furnished equipment installed during original platform manufacture.
On-Premises Solutions hold the installed base. Hybrid Solutions gain share fastest as software-defined architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air forces in France, the United Kingdom, and Germany concentrate procurement authority through domestic prime relationships, with smaller NATO members pooling demand via EU defense mechanisms.
France
Dassault Rafale fleet expansion and FCAS program development drive encrypted wideband system procurement. ANSM military airworthiness certification mandates sovereign encryption key management for all fielded platforms. Thales Group anchors national supply chains from its Paris-headquartered operations.
United Kingdom
Royal Air Force Tempest sixth-generation fighter development consolidates vendor relationships around full-lifecycle performance contracts. UK military airworthiness authorities impose divergent cybersecurity validation timelines compared to continental counterparts. BAE Systems integrates deeply with Typhoon and Tempest fleets from its Farnborough and Warton facilities.
Germany
Panavia Tornado retirement timelines and Eurofighter Typhoon capability insertion compress radio communication retrofit schedules. BAAINBw procurement mandates prioritize cross-border interoperability with NATO allies. Rheinmetall and Airbus Defence and Space operations in Bavaria and North Rhine-Westphalia anchor subsystem integration.
Italy
Eurofighter Typhoon network-enabled capabilities and unmanned combat air vehicle mesh networking trials expand tactical datalink demand. Leonardo S.p.A. leverages its Rome-headquartered electronics division for airborne networking solutions. Campania and Lazio regions concentrate avionics engineering talent around Naples and Rome aerospace clusters.
Poland
Baltic theater dispersion and Arctic Circle NATO operations intensify beyond-line-of-sight satellite communication procurement. Polish Armed Forces modernization programs prioritize interoperability with EU and NATO command structures. Warsaw and Łódź regions host emerging integration partnerships with Western primes.
Europe Military Aircraft Communication Avionics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated European defense electronics base. Sovereign supply chain requirements and national security clearance standards limit cross-border vendor mobility. Two strategic archetypes dominate: vertically integrated national champions with full-platform integration authority, and subsystem specialists with waveform or encryption niche expertise. Competitive moves center on full-lifecycle support contract consolidation and rapid software refresh cycle capabilities.
Among French-headquartered primes, Thales Group exemplifies the vertically integrated national champion archetype with sovereign control over fighter and transport platform electronics. BAE Systems occupies a parallel position in UK-specific programs through deep Royal Air Force integration. Leonardo S.p.A. represents the subsystem specialist model, anchoring tactical datalink and airborne networking segments for Italian and export customers.
| Leading Market Players |
|---|
| Thales Group |
| BAE Systems |
| Leonardo S.p.A. |
| Safran Electronics & Defense |
| Airbus SE |
| L3Harris Technologies |
| Honeywell International |
| Collins Aerospace |
| Rheinmetall |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's congestion-driven cost volatility compresses margins for gallium nitride power amplifier shipments from Asian foundries, amplifying price differentiation between sovereign European supply chains and import-dependent tiers. F-Gas Regulation compliance costs feed into thermal management subsystem pricing, widening spreads between qualified and non-qualified supplier bases.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate prime-tier procurement, binding Thales and BAE Systems to semiconductor wafer price adjustments. Three-tier pricing structure across mission-critical, standard military, and commercial-off-the-shelf levels reflects certification depth and security clearance tiers. Cost compression in standard military tiers intensifies as Eastern European NATO members pool demand through European Defence Fund mechanisms. Government procurement offices exhibit lowest price sensitivity; Tier 2 subsystem integrators face acute margin pressure from full-lifecycle support obligations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from BAAINBw and ANSM procurement offices stabilize cash flow for qualified foundries in France and Germany. Gallium nitride substrate production concentrates in China, Japan, and the United States; rare earth processing for magnet materials draws from Chinese and Australian sources. Single-source vulnerability in advanced encryption chipset fabrication threatens platform delivery timelines. Distribution runs through prime integrator channels with direct airframe manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat fortress where national security clearance standards create insurmountable switching costs for non-incumbent suppliers. ANSM, BAAINBw, and UK military airworthiness authorities enforce incompatible validation regimes that entrench domestic champions.
For Market Incumbents: Harden sovereign encryption key management capabilities against quantum-computing decryption threats. Deepen in-house production of gallium nitride amplifiers through captive supply arrangements with French and German foundries. Consolidate vendor relationships around performance-based spectrum dominance contracts that extend beyond traditional equipment purchase timelines. For New Entrants and Emerging Players: Polish and Baltic defense modernization programs present underpenetration opportunities for tactical datalink subsystem specialists. Mesh networking architectures for unmanned combat air vehicles offer the most penetrable segment, bypassing prime-tier platform integration authority. Pursue PESCO joint capability development cluster partnerships as the primary go-to-market pathway. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core communication electronics divisions. Five-to-ten-year viability hinges on software-defined radio waveform library depth and rapid refresh cycle capabilities. Monitor EU Critical Raw Materials Act implementation timelines as the inflection signal for gallium nitride supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Migration | Collapses hardware refresh cycles from years to months for NATO fighter fleets. |
| Sovereign Gallium Nitride Foundry Investment | Secures power amplifier supply against Chinese rare earth processing bottlenecks. |
| Full-Lifecycle Performance Contracting | Bundles cybersecurity maintenance with hardware for UK Tempest and FCAS programs. |
| Mesh Networking Architecture Development | Enables ad-hoc formation relay for next-generation unmanned combat air vehicles. |
| F-Gas Regulation Thermal Redesign | Qualifies alternative coolants for REACH-compliant avionics across French and German platforms. |
Research Methodology
The analysis maps radio communication systems, data link solutions, integrated communication architectures, and intercom networks, each validated through program managers at BAAINBw and ANSM, Royal Air Force capability directors, prime integrator procurement leads, and thermal management subsystem engineers. Primary interview intelligence triangulates against EASA military certification filings, EU Defence Fund allocation disclosures, national airworthiness authority directives, and customs records for gallium nitride substrate imports. Bottom-up platform-level procurement tracking reconciles with top-down defense budget appropriation analysis.
Assumptions hold European Defence Fund allocation growth rates and Tornado retirement timelines within observed patterns; cross-border standardization acceleration and FCAS program schedule shifts constitute key sensitivities. Segmentation models incorporate product type, technology maturity, end-user security clearance depth, and delivery mode architecture across the projection horizon. CAGRs derive from platform retrofit cycle compression and satellite communication adoption curves in Arctic and Baltic theaters.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Rheinmetall or Airbus Defence and Space would shift outcomes through supply chain capture. Macroeconomic defense budget contraction, regulatory divergence between EASA military and national authorities, or quantum-resistant encryption mandate acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Display for Avionics Application Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Military Aircraft Avionics Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Military Avionic Systems Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Customized Avionic Systems Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Aerospace Avionics Market
Avionics
Global Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Aircraft Computers Market
Avionics
Electronic Flight Instrument System Market
Avionics
Commercial Electronic Flight Bag Market