
 Europe Aircraft Avionics Market | 2026-2036
Europe Aircraft Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Avionics Market Foresight
Software-defined mission computing is decoupling hardware refresh cycles from capability upgrades across European fighter and transport programs. Safran leverages its flight control heritage to anchor positions on Rafale and Eurofighter platforms. Thales competes through integrated digital cockpit suites that reduce pilot workload on multi-domain operations. Honeywell International Inc. extends its terrain awareness and warning systems into retrofit markets where legacy analog architectures still dominate regional and cargo fleets.
Aircraft avionics encompass the electronic systems governing flight management, navigation, communication, surveillance, and mission execution, typically operating across ARINC 429 and MIL-STD-1553 data buses with deterministic latency below 50 milliseconds for safety-critical functions. These systems enable all-weather operations, airspace compliance, and tactical coordination for civil and military operators. Flight Control Systems represent the most technically demanding segment, with triple-redundant architectures commanding premium engineering margins on new military platforms. Communication Systems are gaining share as Europe mandates secure beyond-line-of-sight datalinks under NATO standardization agreements.
EASA airworthiness directives and EU Green Deal aviation targets are reshaping product roadmaps, with the former mandating ADS-B Out equipage and the latter pressuring fuel-efficiency gains through trajectory optimization avionics. CE marking under the Radio Equipment Directive governs market access for communication and surveillance subsystems sold into European-registered aircraft. Stakeholders must weigh the pace of EU AI Act implementation against the operational tempo of next-generation combat air system programs where autonomous decision aids will face dual certification pathways.
Market Dynamics
Software-defined architectures are decoupling capability upgrades from hardware replacement cycles across European military and civil avionics programs, compressing refresh timelines while extending platform service lives.
Growth Catalysts
- EASA ADS-B Out mandates:Retrofit requirements for legacy regional and cargo fleets are accelerating hardware replacement demand across Spain, Italy, and Poland.
- NATO standardization agreements:Secure beyond-line-of-sight datalink specifications are driving communication system upgrades on tactical transport and fighter platforms.
- EU Green Deal aviation targets:Trajectory optimization avionics face regulatory pressure to deliver fuel-efficiency gains on short-haul routes.
Market Restraints
- Semiconductor supply concentration:Dependence on specialized foundry capacity in Taiwan creates lead-time volatility for safety-critical processors.
- Dual certification pathways:The EU AI Act implementation timeline creates friction against operational tempo demands for autonomous decision aids in next-generation combat programs.
- Legacy analog architecture persistence:Regional operators delay full-glass cockpit conversions due to airframe depreciation schedules and financing constraints.
Strategic Opportunities
- Eastern European defense modernization:Poland, Romania, and the Czech Republic are expanding fighter and tactical airlift procurement under NATO capability targets.
- Synthetic vision retrofits:EASA terrain awareness mandates create aftermarket demand for head-down and head-up display upgrades in business aviation.
- ARINC 664 and Time-Triggered Ethernet convergence:Deterministic networking standards enable consolidated computing platforms that reduce wiring weight and certification burden.
Industry Challenges
- DO-178C and DO-254 certification expertise:The pool of qualified software and hardware verification engineers is tightening across Hamburg, Toulouse, and Munich engineering clusters.
- Legacy MIL-STD-1553 integration:New digital backbone architectures must maintain interoperability with analog-era weapon and sensor interfaces on mid-life fighter platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Avionics Market |
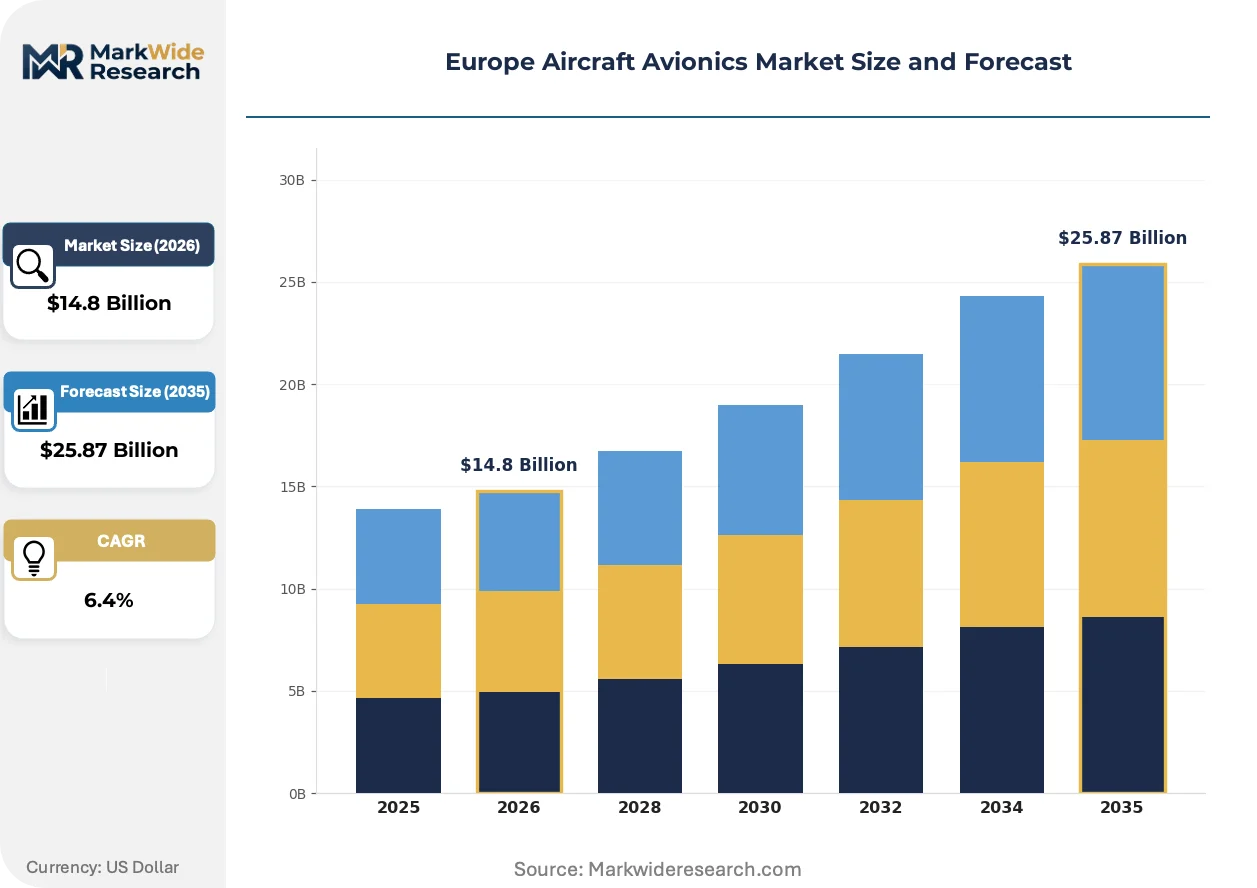
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Systems, Communication Systems, Navigation Systems, Surveillance Systems End User: Civil Aviation, Military Aviation, Helicopters, Unmanned Aerial Vehicles Technology: Digital Avionics, Integrated Avionics, Glass Cockpit Systems, Legacy Systems Application: Passenger Aircraft, Cargo Aircraft, Military Aircraft, Business Jets |
| Companies Covered | L3Harris Technologies Inc., Cobham plc, Safran, Northrop Grumman Corporation, General Electric, Honeywell International Inc., RTX Corporation, Diehl Stiftung & Co. KG, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Avionics Market Shifts & Advancements
Deterministic networking standards and modular open systems architectures are compressing development cycles while fragmenting supplier hierarchies across European defense and civil programs.
Integrated modular avionics based on ARINC 653 partitioning is overtaking federated system architectures on new military platforms. Eurofighter and Rafale upgrade programs are adopting consolidated computing cabinets that host multiple critical functions on shared hardware. This convergence is overtaking traditional single-function line-replaceable units and reducing platform weight by eliminating redundant power and cooling infrastructure.
The EU AI Act risk classification framework is imposing conformity assessment requirements on autonomous flight control and decision-support algorithms. Developers must demonstrate traceability and human oversight protocols for safety-critical AI functions before EASA type certification. Military combat air system programs face dual-track certification pathways that extend development timelines for autonomous wingman and sensor-fusion applications.
Performance-based logistics contracts are displacing traditional spares-provisioning agreements for military avionics sustainment. French and German defense ministries now contract availability metrics rather than component inventories, transferring obsolescence risk to prime contractors. This shift concentrates aftermarket revenue with platform integrators while squeezing component suppliers in the UK and Italian supply chains.
Europe Aircraft Avionics Market Segmentation
Avionics procurement patterns diverge sharply between cost-sensitive retrofit cycles and premium new-platform development. Understanding these tiered demand structures clarifies where engineering margins concentrate versus where volume opportunities materialize across European aerospace programs.
Product Type:
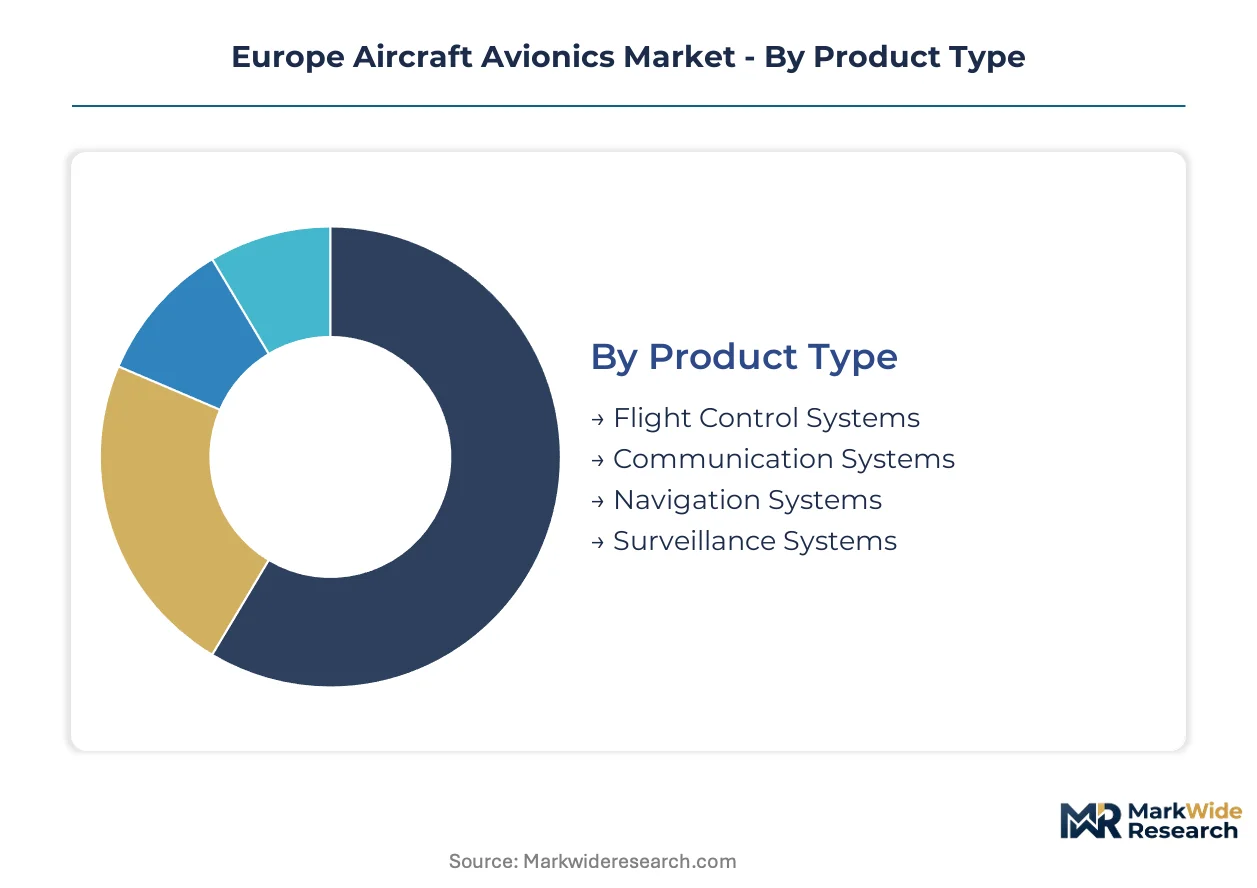
Flight Control Systems command the highest engineering premiums while Communication Systems drive retrofit volume across aging fleets.
- Flight Control Systems:Triple-redundant fly-by-wire architectures with deterministic latency below 50 milliseconds anchor safety-critical functions on Rafale and Eurofighter platforms. German and French defense procurement concentrates demand here, with EASA certification mandates extending similar redundancy requirements into large civil transports.
- Communication Systems:Secure beyond-line-of-sight datalinks operating across NATO standardization agreements are displacing legacy voice-centric radios on tactical transport fleets. Poland and Romania drive retrofit demand as Eastern European operators align with alliance interoperability requirements.
- Navigation Systems:GPS-denied positioning using inertial reference units and celestial backup architectures supports contested-environment military operations.
- Surveillance Systems:ADS-B Out transponders and terrain awareness warning systems face mandatory retrofit timelines under EASA airworthiness directives.
Mature deployment sits with Navigation Systems on legacy regional fleets. Newer deployment is concentrated in Flight Control Systems as next-generation combat air programs advance.
End User:
Civil operators prioritize fuel-efficiency avionics while military buyers emphasize secure datalink and electronic warfare integration.
- Civil Aviation:Commercial carriers and regional operators equip trajectory optimization systems to meet EU Green Deal aviation targets, with short-haul routes in Spain and Italy showing fastest adoption of continuous descent approach avionics.
- Military Aviation:Fighter and tactical airlift procurement across France, Germany, and the UK is expanding under NATO capability targets, with mission computing upgrades outpacing full platform replacement.
- Helicopters:Synthetic vision and degraded visual environment systems address offshore oil-and-gas transport requirements in the North Sea.
- Unmanned Aerial Vehicles:Detect-and-avoid avionics and command-link redundancy face dual certification under EU AI Act risk classifications and EASA special condition frameworks.
Volume concentration rests with Civil Aviation retrofits. Value expansion is climbing fastest in Military Aviation as software-defined architectures extend platform service lives.
Technology:
Integrated architectures are compressing hardware refresh cycles while Glass Cockpit Systems capture aftermarket upgrade spend.
- Digital Avionics:ARINC 429 and MIL-STD-1553 data bus implementations persist on mid-life platforms, with deterministic messaging protocols ensuring interoperability between analog-era sensors and modern mission computers.
- Integrated Avionics:ARINC 653 partitioning enables consolidated computing cabinets that host multiple critical functions on shared hardware, reducing wiring weight and certification burden on Eurofighter upgrade programs.
- Glass Cockpit Systems:Head-down and head-up display suites replace electromechanical instruments on business aviation and regional turboprop fleets.
- Legacy Systems:Analog flight instruments and discrete wiring architectures persist where financing constraints delay full-glass conversions.
Installed base concentration remains with Legacy Systems. Deployment momentum is gaining share fastest in Integrated Avionics as new military platforms enter production.
Application:
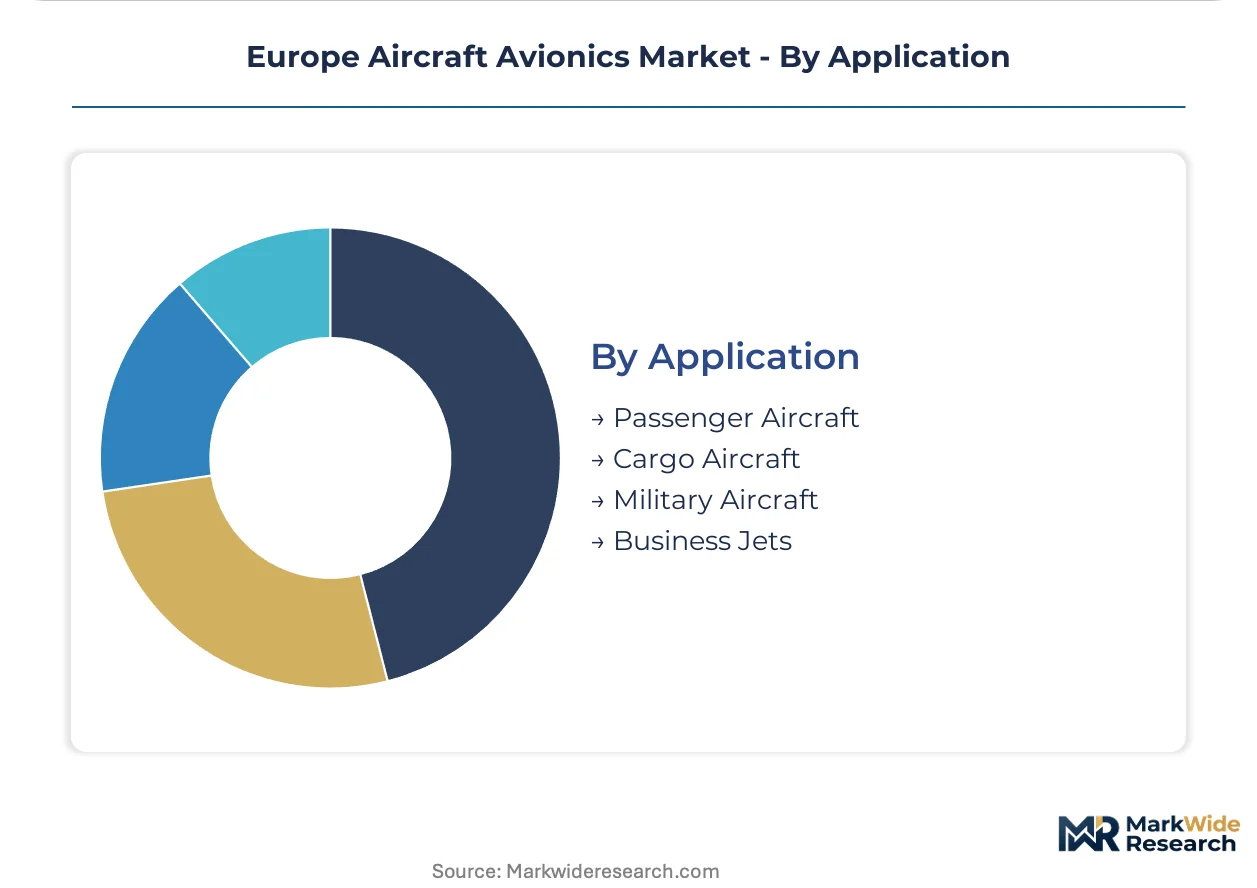
Passenger aircraft drive ADS-B retrofit volume while military platforms concentrate R&D-intensive mission computing development.
- Passenger Aircraft:Single-aisle and regional jet fleets across Lufthansa, Air France-KLM, and IAG group carriers face EASA mandates for surveillance and terrain awareness upgrades, with retrofit scheduling tied to heavy maintenance intervals.
- Cargo Aircraft:Express freight operators in Leipzig and Cologne prioritize fuel-efficiency avionics for short-haul European trunk routes, with trajectory optimization systems delivering measurable fuel burn reductions.
- Military Aircraft:Fighter, transport, and tanker platforms require secure communication and electronic warfare avionics under NATO standardization.
- Business Jets:Synthetic vision and enhanced vision systems address EASA terrain awareness mandates for approach operations at mountain airports.
Fleet penetration is deepest in Passenger Aircraft. Steepest expansion trajectory is emerging in Military Aircraft as Franco-German next-generation combat air system programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European avionics engineering density, hosting Airbus Defence and Space alongside Diehl Aviation's integrated systems development. Toulouse, Munich, and London form secondary poles where flight control and mission computing expertise concentrates.
Germany
Airbus Defence and Space and Diehl Aviation drive military avionics procurement for Eurofighter and tactical transport platforms. EASA certification mandates for synthetic vision systems accelerate retrofit demand across Lufthansa's regional fleet. Bavaria's Munich-Starnberg corridor hosts specialized DO-178C verification engineering clusters serving both civil and defense programs.
France
Safran and Thales anchor Rafale fighter avionics development alongside next-generation combat air system prototyping. Direction Générale de l'Armement procurement contracts emphasize secure datalink standardization under NATO agreements. The Île-de-France aerospace cluster around Paris-Saclay concentrates flight control software architecture expertise.
United Kingdom
BAE Systems and Leonardo UK manage Typhoon avionics upgrade cycles while participating in Franco-German next-generation fighter development. Ministry of Defence availability-based logistics contracts transfer obsolescence risk from military buyers to prime integrators. Southwest England's Bristol-Bath corridor hosts mission computing verification facilities.
Poland
Eastern European defense modernization programs drive F-16 avionics retrofit demand and tactical airlift communication system upgrades. NATO capability targets mandate secure beyond-line-of-sight datalink equipage on legacy platforms. Warsaw's emerging engineering base supports regional MRO integration with Western European prime contractors.
Spain
Airbus Military production in Seville sustains A400M avionics integration demand for tactical transport fleets. EASA ADS-B Out mandates compress retrofit timelines for Iberia and Air Europa regional subsidiaries. Madrid's aerospace technology corridor hosts specialized terrain awareness warning system certification facilities.
Europe Aircraft Avionics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier hierarchy where platform integrators capture aftermarket revenue through performance-based logistics contracts. The market structure concentrates around defense primes with civil avionics divisions, tier-one component specialists, and niche certification engineering boutiques. Three archetypes dominate: integrated platform providers, subsystem modular suppliers, and verification services specialists. Competitive moves center on strategic partnerships for AI-enabled flight control development and backward integration into specialized semiconductor sourcing.
Among French-anchored platform integrators, Safran and Thales exemplify the integrated archetype spanning flight control heritage through digital cockpit suites. L3Harris Technologies Inc. occupies a position within the secure communication subsystem tier, while Honeywell International Inc. anchors terrain awareness retrofit demand across Europe's legacy fleet base. These three represent distinct competitive positioning vectors without overlapping core specializations.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| Cobham plc |
| Safran |
| Northrop Grumman Corporation |
| General Electric |
| Honeywell International Inc. |
| RTX Corporation |
| Diehl Stiftung & Co. KG |
| Thales Group |
| Others |
Supply & Pricing Matrix
Software-defined mission computing architectures are compressing hardware refresh cycles while simultaneously concentrating engineering premiums among qualified suppliers holding EASA and NATO certification credentials. This technological transition rewards incumbents with DO-178C verification expertise while squeezing margins on commodity hardware tiers.
Pricing Analysis
Availability-based contracting anchors pricing logic across European military avionics procurement, with French and German defense ministries contracting uptime metrics rather than component inventories. Price differentiation separates triple-redundant flight control systems from single-channel communication retrofits, with certification grade and after-sales service bundling as primary tiering mechanisms. Cost compression in legacy analog replacement segments is intensifying because regional operators delay full-glass conversions amid airframe depreciation schedules. Cargo operators in Central Europe exhibit highest price sensitivity, while fighter platform integrators accept premium positioning for deterministic latency guarantees.
Supply Chain Analysis
DO-254 hardware qualification and DO-178C software certification requirements gate supplier entry, concentrating qualified capacity across Germany, France, and the United Kingdom. Semiconductor fabrication for safety-critical processors draws from Taiwan and South Korea, with specialized foundry capacity creating lead-time volatility for military-grade components. Single-source vulnerability runs through legacy MIL-STD-1553 interface chip suppliers serving mid-life fighter upgrade programs. Distribution runs through platform integrators capturing aftermarket revenue via performance-based logistics contracts with defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe aircraft avionics market is becoming a vertical-integration race as primes seek captive control over specialized semiconductor sourcing and certification engineering talent pools.
For Market Incumbents: To counter semiconductor supply concentration and qualified verification engineer scarcity, anchor positions through backward integration into safety-critical processor sourcing and expand DO-178C certification capacity in the Munich-Starnberg corridor. Lock in multi-year availability contracts with Eastern European defense ministries before next-generation combat air system prototyping accelerates. For New Entrants and Emerging Players: The premium-to-economy gap in terrain awareness retrofit systems offers entry points for modular suppliers targeting Iberian and Italian regional carriers facing compressed EASA compliance deadlines. White-space concentrates in synthetic vision head-up display upgrades for business aviation operators at mountain airports. Pursue partnership routes with established MRO networks rather than direct airframer certification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with DO-178C/D0-254 verification boutiques given EU AI Act implementation creating dual-track certification demand for autonomous flight control algorithms. Long-term viability favors specialists with military and civil crossover credentials. Monitor NATO standardization agreement ratification velocity as inflection signal for secure datalink upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Semiconductor Sourcing | Captive supply of safety-critical processors insulates against Taiwan foundry lead-time volatility for Eurofighter and Rafale programs. |
| DO-178C Verification Engineering Capacity Expansion | Certification talent scarcity in Hamburg and Toulouse clusters creates moat for qualified software architecture houses. |
| Performance-Based Logistics Contract Conversion | Availability contracting with French Direction Générale de l'Armement transfers obsolescence risk from buyers to platform integrators. |
| ARINC 653 Partitioning Platform Development | Consolidated computing cabinets reduce wiring weight and certification burden on Eurofighter upgrade programs. |
| Eastern European Defense Modernization Partnership | Polish and Romanian NATO capability targets drive F-16 avionics retrofit demand and tactical airlift communication upgrades. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with platform integration engineers, EASA certification specialists, defense procurement officers, and avionics aftermarket directors. EASA airworthiness directives, NATO standardization agreements, EU AI Act implementation timelines, and semiconductor trade flows provided validation benchmarks. Bottom-up segmentation modeling triangulated against top-down defense budget allocation data across France, Germany, the United Kingdom, Poland, and Spain.
Data-stream reconciliation across production volume disclosures, fleet retrofit scheduling, and platform upgrade program announcements enabled cross-validation of demand estimates across the projection horizon. Segmentation dimensions modeled include product type, end user, technology architecture, and application category, with additional granularity on certification tier and military-civil crossover capability. CAGRs derived from weighted average of platform delivery schedules, regulatory mandate effective dates, and fleet age distribution analysis. Fuel-efficiency avionics adoption curves and secure datalink equipage rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; military aviation procurement with disclosed program budgets carries tighter precision than civil retrofit demand subject to airline financing cycles. Forecasts reflect assumptions on NATO capability target adherence, EASA mandate enforcement timelines, and semiconductor supply normalization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Display for Avionics Application Market
Avionics
Aircraft Computers Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Aerospace Avionics Market
Avionics
Global Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Customized Avionic Systems Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Commercial Electronic Flight Bag Market