
 Middle East Commercial Aircraft in-Flight Entertainment System Market | 2026-2036
Middle East Commercial Aircraft in-Flight Entertainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Aircraft in-Flight Entertainment System Market Foresight
Full-service carriers is rotating toward immersive seat-back and wireless streaming architectures as low-cost operators in the Middle East defer heavy IFE capex. Panasonic Avionics Corporation dominates long-haul embedded deployments across Emirates and Etihad fleets. Thales Group leverages its AVANT platform to anchor premium cabin differentiation in the Gulf. Collins Aerospace competes through integrated connectivity-entertainment bundles that reduce airline supplier complexity.
Commercial aircraft in-flight entertainment systems comprise seat-back displays, overhead screens, wireless streaming servers, and content distribution networks operating at altitudes above 10,000 feet with MIL-STD-810G shock and vibration tolerance. These systems generate ancillary revenue through premium content and advertising while reducing perceived flight duration for passengers. Embedded systems retain the largest installed base across Middle Eastern flag carriers with extensive wide-body operations. Streaming solutions represent the fastest-expanding category as airlines retrofit narrow-body fleets with bring-your-own-device architectures. Content type segmentation shows movies commanding the highest licensing expenditure, though live television and interactive gaming are gaining traction on routes exceeding eight hours.
The UAE's GCAA, Saudi Arabia's GACA, and EASA through its MDR framework govern cabin equipment certification, electromagnetic compatibility, and cybersecurity protocols for IFE hardware deployed on aircraft registered in the Middle East. These regulators mandate crashworthiness testing and data privacy safeguards that extend product development cycles and favor established suppliers with dedicated certification teams. Stakeholders must monitor spectrum allocation decisions for Ka-band satellite connectivity across Gulf national airspace, as these rulings will determine which technology platforms achieve route-wide coverage without regulatory interruption.
Market Dynamics
The Middle East commercial aircraft in-flight entertainment system market is being fundamentally restructured by the migration from embedded seat-back hardware to wireless bring-your-own-device architectures, a shift accelerated by Saudi Arabia's fleet expansion and the UAE's connectivity mandates for wide-body operations.
Growth Catalysts
- Saudia and Riyadh Air fleet expansion:Saudi Arabia's national carriers are commissioning over one hundred long-haul aircraft requiring premium IFE configurations, creating concentrated demand for embedded and streaming systems.
- GCAA connectivity mandates:The UAE's General Civil Aviation Authority now requires enhanced passenger connectivity standards for wide-body fleets operating under its registry, forcing retrofit cycles.
- Ka-band satellite deployment:High-throughput satellite coverage across Gulf airspace enables streaming architectures that reduce hardware weight and maintenance burdens for narrow-body operators.
Market Restraints
- Avionics-grade display panel costs:MIL-STD-810G certified LCD and OLED panels for seat-back systems carry aerospace certification premiums that compress airline margins on retrofit programs.
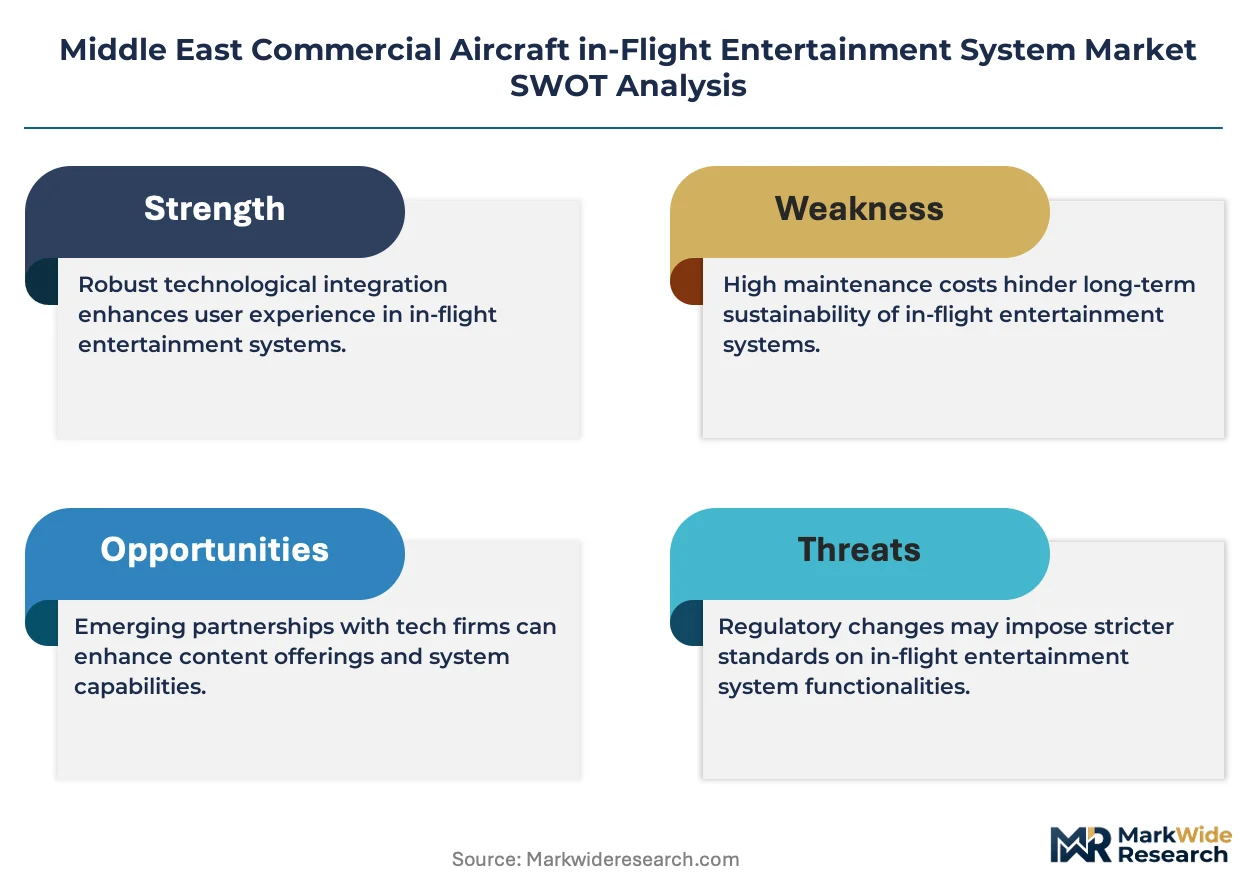
- Supplier concentration in European certification:EASA's MDR framework and delegated oversight create bottlenecks where only established vendors maintain dedicated certification engineering teams.
- Content licensing fragmentation:Studio rights for Hollywood and Bollywood catalogs require territory-by-territory negotiations that inflate operating expenditure for Middle Eastern carriers serving diverse route networks.
Strategic Opportunities
- Oman and Bahrain underpenetration:These smaller GCC aviation markets lack dedicated IFE retrofit infrastructure, creating first-mover advantage for system integrators establishing local maintenance partnerships.
- Advertising-integrated streaming platforms:Targeted passenger analytics tied to wireless IFE architectures open ancillary revenue streams that offset hardware capital expenditure for low-cost carriers.
- GACA localization incentives:Saudi Arabia's General Authority of Civil Aviation offers procurement preferences for maintenance, repair and overhaul providers with domestic technical workforce development commitments.
Industry Challenges
- Embedded-to-streaming retrofit integration:Airlines must reconcile legacy ARINC 429 data buses with modern wireless access points without airworthiness certificate suspension.
- Cybersecurity certification timelines:EASA's evolving airworthiness criteria for passenger-facing network isolation extend product qualification cycles beyond eighteen months.
- Content engineering talent scarcity:The GCC lacks sufficient avionics software engineers familiar with DO-178C safety-critical development standards for IFE operating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Aircraft in-Flight Entertainment System Market |
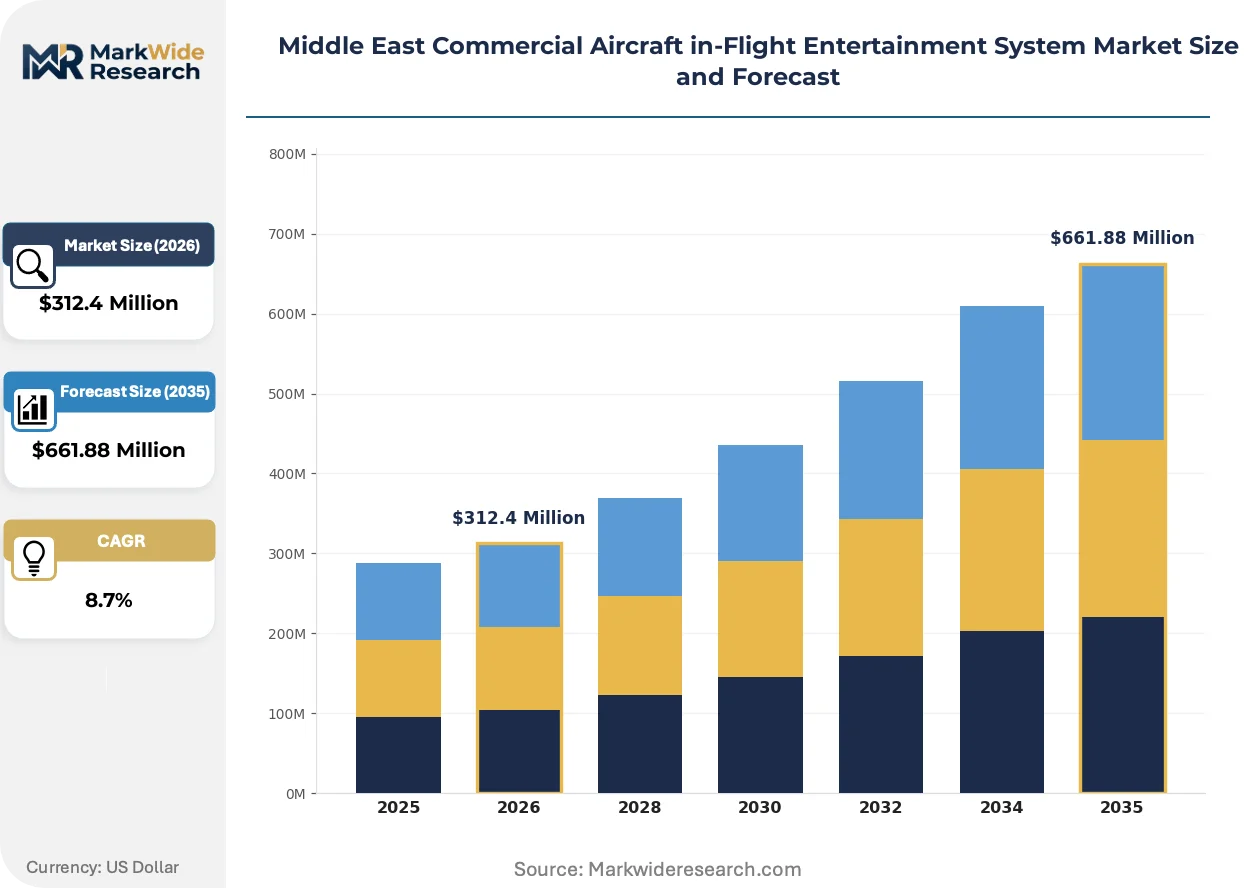
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Embedded Systems, Portable Systems, Streaming Solutions, Wireless Systems Content Type: Movies, TV Shows, Music, Games End User: Airlines, Charter Companies, Private Jets, Leasing Firms Technology: Wi-Fi, Bluetooth, Satellite, LAN |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Safran, Gogo Inc., Honeywell International, Viasat Inc., Global Eagle Entertainment Inc., Inmarsat plc, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Aircraft in-Flight Entertainment System Market Shifts & Advancements
Wireless streaming architectures are compressing the traditional embedded IFE supply chain while regulatory pressure on data privacy and electromagnetic compatibility intensifies certification requirements across Gulf aviation authorities.
Bluetooth Low Energy and Wi-Fi 6E access points are supplanting seat-back display units as the primary passenger interface on narrow-body aircraft. Saudi low-cost carriers are adopting these architectures for their incoming A320neo and 737 MAX fleets. This shift is supplanting the historical hardware-centric revenue model with recurring software and content licensing structures that reduce airline capital intensity.
EASA's MDR cybersecurity annex and the UAE GCAA's emerging data protection guidelines for passenger connectivity systems now mandate hardware-level network segregation. These rules extend type certification timelines and favor suppliers with pre-approved security architectures. Wide-body retrofit programs across Emirates and Etihad operations face the most acute compliance burden as they integrate next-generation connectivity suites.
Airline technical procurement teams now unbundle hardware acquisition from content provisioning and maintenance contracts, shifting from single-source integrated agreements toward multi-vendor ecosystems. This fragmentation disrupts traditional Panasonic-Thales duopoly structures in the Gulf. The trend is most visible among Saudi carriers seeking to diversify supplier risk ahead of Vision 2030 fleet scaling targets.
Middle East Commercial Aircraft in-Flight Entertainment System Market Segmentation
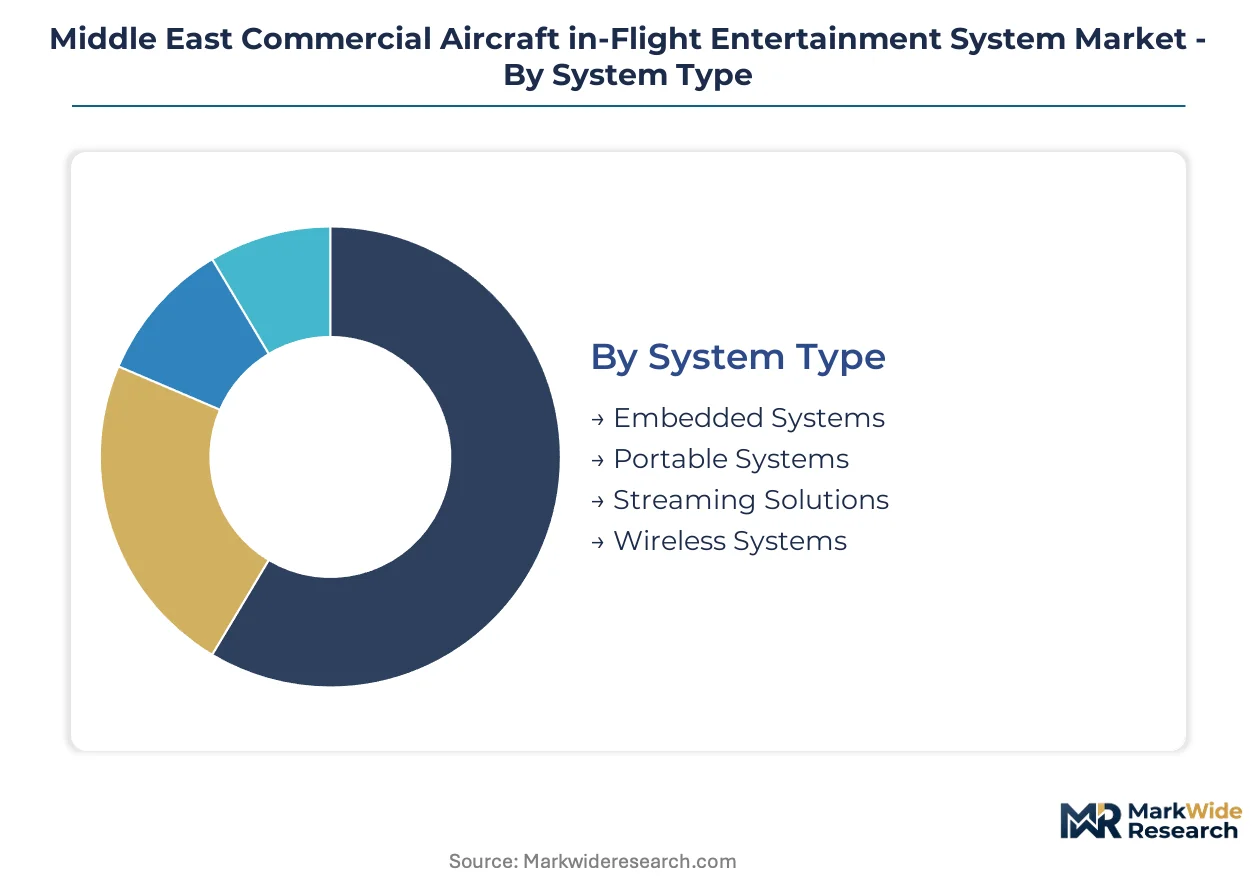
IFE purchasing patterns across the Middle East diverge sharply by fleet composition and regulatory jurisdiction. Saudi Arabia's flag carriers drive embedded system demand while UAE mandates reshape connectivity technology selection across wide-body operations.
System Type:
Domestic fleet renewal concentrates demand in Saudi Arabia and the UAE, with export-oriented sales flowing to Qatar and Kuwait through lessor intermediaries.
- Embedded Systems:Seat-back display units with ARINC 429 connectivity and MIL-STD-810G certification anchor premium cabin configurations. Saudia and Riyadh Air specify these for long-haul Boeing 787 and Airbus A350 deliveries, though avionics-grade panel costs compress retrofit margins.
- Streaming Solutions:Wireless server architectures enabling bring-your-own-device consumption are gaining traction fastest. Saudi low-cost carriers deploy these on A320neo and 737 MAX fleets to avoid seat-back hardware weight and maintenance burdens while satisfying GACA connectivity guidance.
- Portable Systems:Tablet-based loaner devices serve charter operators and seasonal lease fleets requiring rapid cabin reconfiguration.
- Wireless Systems:Dedicated access point hardware supporting Wi-Fi 6E and Bluetooth Low Energy protocols enables hybrid embedded-streaming architectures.
Embedded systems command the established base across Gulf flag carriers. The steepest expansion runs through streaming solutions as narrow-body operators pursue capital-light cabin refreshes.
Content Type:
Cost tier differentiation separates premium long-haul offerings from budget carrier minimalism, with licensing expenditure scaling directly with route duration.
- Movies:Hollywood and Bollywood catalog rights command the highest per-passenger licensing fees. Territory-by-territory negotiations inflate operating expenditure for Emirates and Etihad serving diverse route networks across Europe, South Asia, and North America.
- Games:Interactive entertainment is expanding fastest on ultra-long-haul sectors exceeding eight hours. Qatar Airways deploys multiplayer architectures on Doha-Auckland and Doha-Santiago rotations to reduce perceived flight duration.
- TV Shows:Serialized content supports binge-viewing patterns on medium-haul routes to European destinations.
- Music:Audio streaming incurs lower bandwidth costs and serves as a fallback when satellite connectivity degrades over oceanic airspace.
Movies retain the dominant licensing share. Games are climbing the fastest as airlines compete on passenger experience metrics for ultra-long-haul market positioning.
End User:
Customer type determines procurement complexity, with scheduled carriers negotiating multi-year integrated contracts while private operators prioritize rapid installation flexibility.
- Airlines:Scheduled carriers dominate volume, with Saudia, Riyadh Air, Emirates, Etihad, and Qatar Airways collectively driving fleet-wide specification trends. These operators unbundle hardware from content and maintenance contracts to diversify supplier risk.
- Private Jets:High-net-worth individual owners in the UAE and Saudi Arabia demand bespoke cabin entertainment with minimal certification lead times. This segment accepts premium pricing for expedited EASA MDR compliance.
- Charter Companies:Seasonal operators serving Hajj and Umrah traffic require rapid cabin reconfiguration capabilities between pilgrimage and commercial deployments.
- Leasing Firms:Aircraft lessors based in Dubai and Shannon specify transferable IFE architectures that preserve residual value across multiple airline operators.
Airlines absorb the dominant installation volume. Private jets are gaining share fastest as Saudi wealth concentration drives VIP cabin retrofit demand.
Technology:
Supply concentration for certification-capable hardware favors established vendors with dedicated EASA engineering teams, fragmenting procurement options for newer connectivity protocols.
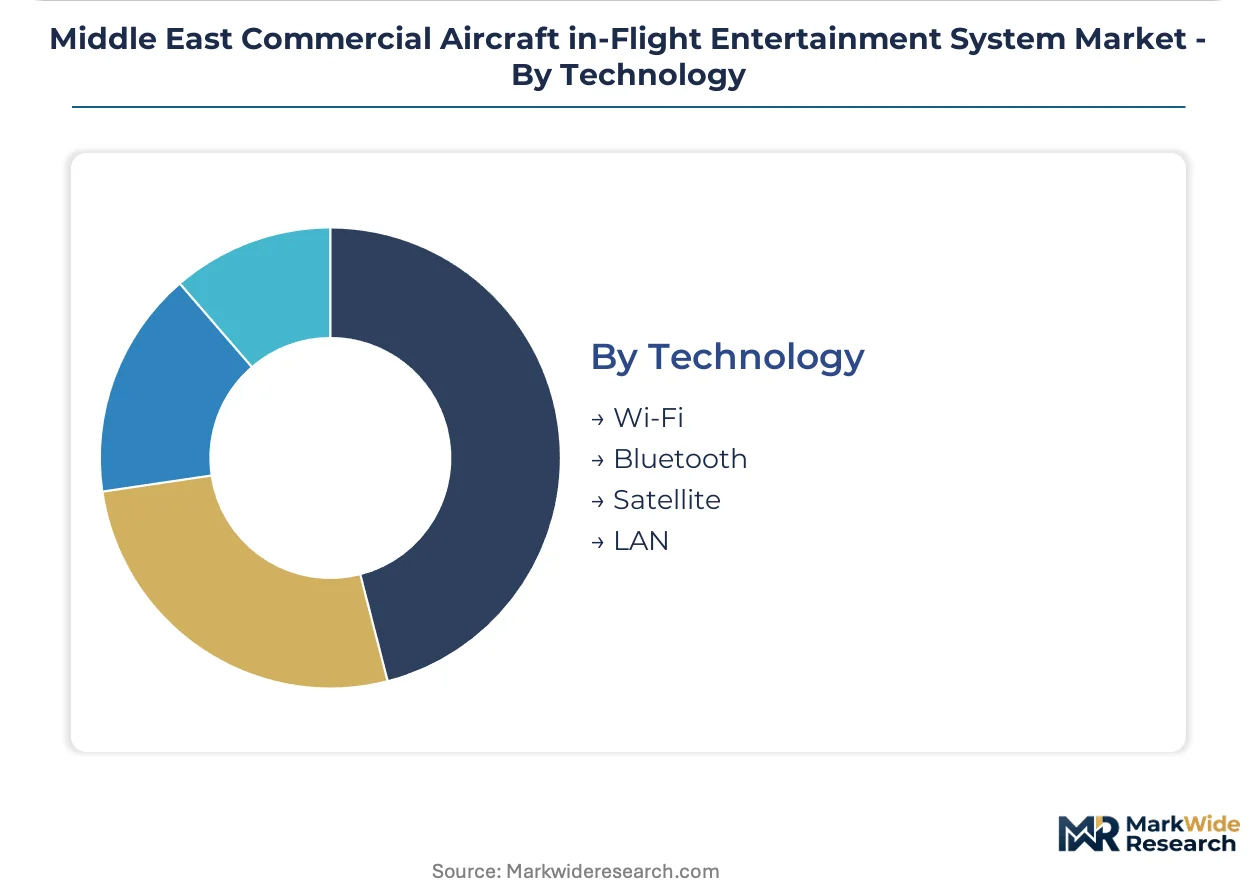
- Satellite:Ka-band and Ku-band terminals enable streaming coverage across Gulf airspace and oceanic routes. The UAE GCAA and Saudi GACA spectrum allocation decisions determine which platforms achieve route-wide regulatory approval without interruption.
- Wi-Fi:802.11ax and emerging Wi-Fi 6E access points are displacing legacy seat-back units as primary passenger interfaces. Narrow-body retrofits across flydubai and Air Arabia fleets prioritize these architectures for passenger satisfaction metrics.
- Bluetooth:Low Energy protocols support wireless headphone pairing and crew communication headsets with minimal electromagnetic interference.
- LAN:Wired Ethernet backbone infrastructure persists in wide-body embedded systems requiring deterministic bandwidth for 4K video distribution.
Satellite retains the connectivity backbone for long-haul operations. Wi-Fi is expanding most quickly as narrow-body operators bypass embedded hardware entirely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports IFE system integration services to UAE-based wide-body retrofit programs, while Dubai's leasing firms re-export certified cabin equipment to North African and South Asian carriers.
Saudi Arabia
Riyadh Air and Saudia are commissioning over one hundred long-haul aircraft requiring premium IFE configurations. GACA offers procurement preferences for MRO providers with domestic technical workforce development commitments. Riyadh anchors the kingdom's IFE demand concentration as Vision 2030 fleet scaling targets reshape technical procurement patterns.
United Arab Emirates
Emirates and Etihad drive embedded system demand across extensive wide-body operations. GCAA mandates enhanced passenger connectivity standards for wide-body fleets operating under its registry. Dubai International Airport's MRO cluster hosts concentrated retrofit infrastructure serving Gulf Cooperation Council carriers.
Qatar
Qatar Airways deploys multiplayer gaming architectures on ultra-long-haul Doha-Auckland and Doha-Santiago rotations. The country's civil aviation authority aligns with EASA MDR frameworks for cabin equipment certification. Doha's Hamad International Airport supports technical staging for IFE system installations across African and Asia-Pacific routes.
Kuwait
Kuwait Airways maintains legacy embedded systems across narrow-body fleets with selective streaming retrofits. The Directorate General of Civil Aviation enforces electromagnetic compatibility standards mirroring EASA protocols. Kuwait City lacks dedicated IFE retrofit infrastructure, creating procurement dependency on Saudi and UAE technical service providers.
Oman
Oman Air pursues hybrid embedded-streaming architectures for regional and long-haul network differentiation. The Public Authority for Civil Aviation regulates Ka-band satellite terminal approvals across mountainous terrain and coastal airspace. Muscat's underpenetrated MRO sector attracts system integrators establishing first-mover maintenance partnerships.
Middle East Commercial Aircraft in-Flight Entertainment System Market Competitive Landscape
Player mix skews toward avionics conglomerates with dedicated certification engineering teams, creating a consolidated structure where EASA MDR compliance capabilities filter market access. Three archetypes dominate: full-stack embedded system suppliers, connectivity-entertainment bundle providers, and satellite service integrators. Competitive moves concentrate on strategic partnerships with Gulf flag carriers and technology licensing agreements that reduce airline supplier complexity.
Among the established tier, Panasonic Avionics Corporation and Thales Group exemplify full-stack embedded specialists with long-haul deployment track records across Middle Eastern flag carriers. Collins Aerospace occupies a position within the integrated bundle archetype, competing through combined connectivity-entertainment offerings. These three anchors reflect the market's supplier concentration around vendors maintaining pre-approved security architectures and dedicated EASA certification teams.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Collins Aerospace |
| Safran |
| Gogo Inc. |
| Honeywell International |
| Viasat Inc. |
| Global Eagle Entertainment Inc. |
| Inmarsat plc |
| Others |
Supply & Pricing Matrix
Eighteen-month certification timelines for EASA MDR cybersecurity compliance concentrate supplier power among established vendors while compressing margins for airlines negotiating retrofit programs across Gulf flag carrier fleets.
Pricing Analysis
Next-generation streaming architectures command 40-60% hardware cost reductions against legacy embedded seat-back systems, yet certification-grade MIL-STD-810G panels sustain premium pricing tiers. Three-tier pricing structure across premium, standard, and economy levels separates ARINC 429 embedded systems from wireless BYOD architectures and portable tablet solutions. Cost compression in narrow-body streaming retrofits is intensifying because Saudi low-cost carriers prioritize capital-light cabin refreshes. Low-cost carriers exhibit highest price sensitivity, while Emirates and Etihad absorb premium embedded system costs for brand differentiation.
Supply Chain Analysis
France and the United States anchor avionics-grade display panel fabrication and EASA certification engineering, while Taiwan and South Korea feed semiconductor components for wireless access point hardware. The supply chain draws from aerospace-certified LCD foundries, DO-178C compliant software houses, and Ka-band satellite terminal manufacturers. Single-source vulnerability concentrates in EASA-delegated oversight bottlenecks where only Panasonic, Thales, and Collins maintain dedicated certification teams. Distribution runs through Dubai International Airport's MRO cluster serving GCC carrier retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Saudi Arabia's Vision 2030 fleet scaling creates concentrated demand for both embedded and streaming architectures ahead of mature market saturation.
For Market Incumbents: Compound certification advantage by embedding cybersecurity architectures ahead of EASA MDR enforcement timelines. Acquire specialized DO-178C software engineering teams in Saudi Arabia to capture GACA localization incentives. Threat substitution from Chinese connectivity vendors demands pre-emptive channel control across Oman and Bahrain MRO partnerships.
For New Entrants and Emerging Players: Differentiate on advertising-integrated streaming platforms with passenger analytics capabilities that offset hardware capex for price-sensitive low-cost carriers. Target Oman's underpenetrated MRO sector through maintenance joint ventures with Muscat technical service providers. White-space exists in hybrid embedded-streaming architectures for Oman Air's regional network positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EASA MDR compliance capabilities filter market access to three established vendors across the analysis window. Acquisition targets include wireless IFE software specialists with pre-approved security architectures and Saudi-based MRO providers with GACA workforce development credentials. Signal to watch is Ka-band spectrum allocation rulings from UAE GCAA and Saudi GACA determining platform route coverage.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | EASA MDR cybersecurity annex compliance accelerates type certification timelines for Panasonic and Thales platforms. |
| Localization Partnership | GACA technical workforce commitments unlock procurement preferences for Riyadh Air and Saudia retrofit programs. |
| Wireless Platform Launch | BYOD architectures reduce seat-back hardware weight for flydubai and Air Arabia narrow-body fleet refreshes. |
| Spectrum Allocation Engagement | UAE GCAA Ka-band rulings determine Viasat and Inmarsat terminal route-wide coverage without regulatory interruption. |
| Content Licensing Integration | Studio territory negotiations consolidate Hollywood and Bollywood rights for Emirates' diverse European and South Asian networks. |
Research Methodology
The analysis maps embedded systems, streaming solutions, portable devices, and wireless architectures, each validated through airline technical procurement officers, avionics certification engineers, MRO operations directors, and satellite connectivity specialists. Primary interviews with fleet planning executives at Saudia, Riyadh Air, Emirates, and Etihad combined with secondary validation against EASA MDR framework documents, GCAA regulatory filings, GACA procurement guidelines, and aircraft delivery databases. Bottom-up installation forecasts triangulate against top-down fleet expansion projections from OEM order books.
Consistency checks validated volume outputs against external benchmarks including wide-body delivery schedules, narrow-body retrofit announcements, and connectivity mandate enforcement timelines. Segmentation dimensions modeled span system type, content category, end-user archetype, and technology protocol across the projection horizon. CAGRs derive from fitted growth curves anchored to fleet scaling targets and regulatory compliance deadlines. Industry-specific inputs include avionics-grade panel cost trajectories and content licensing expenditure patterns by route duration.
Material uncertainties — spectrum allocation delays, certification timeline extensions, content rights renegotiations — sit outside the modeled envelope. Forecasts reflect assumptions regarding GACA localization incentive continuity and EASA MDR enforcement consistency. Recalibration cycles align with material shifts in Saudi fleet delivery schedules and UAE connectivity mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Europe Aircraft Avionics Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Aircraft EMI Shielding Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Military Aircraft Avionics Market
Avionics
Global Avionics Market
Avionics
Electronic Flight Instrument System Market
Avionics
Display for Avionics Application Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Customized Avionic Systems Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Global Helicopter Avionics Market
Avionics
Aerospace Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market