
 Asia-Pacific Semiconductor in Military and Aerospace Market | 2026-2036
Asia-Pacific Semiconductor in Military and Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor in Military and Aerospace Market Analytics
The capability gap between captive foundry operators and fabless designers is bifurcating competitive returns across the Asia-Pacific semiconductor defense supply base. Intel Corporation leverages its Arizona-to-Ireland manufacturing footprint to sustain packaging dominance for radiation-hardened processors bound for Japanese satellite programs. Samsung Electronics Co. Ltd anchors South Korean aerospace foundry output through in-house EUV lithography capacity that controls advanced node access for indigenous fighter avionics.
The Asia-Pacific Semiconductor in Military and Aerospace encompasses integrated circuits engineered to withstand extreme thermal cycling, electromagnetic pulse exposure, and ionizing radiation across operating temperatures from minus 55 to 125 degrees Celsius, serving mission-critical functions in guidance, communications, and sensor fusion architectures. Memory Chips and RF Components concentrate margin pools where radiation-hardened requirements and gallium nitride process complexity limit qualified supplier pools. System-on-Chip designs lead technology migration as aerospace OEMs consolidate multi-function payloads onto single die to reduce size, weight, and power constraints in next-generation platforms.
Japan's METI administers JIS standards for defense procurement qualification while South Korea's MFDS coordinates dual-use export control classifications with allied frameworks, tightening market access for non-domestic component vendors. China's SAMR enforces GB standards and anti-foreign dependency catalogues that redirect military semiconductor sourcing toward domestic champions. Stakeholders must monitor evolving national security review thresholds for cross-border wafer fabrication partnerships as sovereignty claims over critical chip capacity harden across the region.
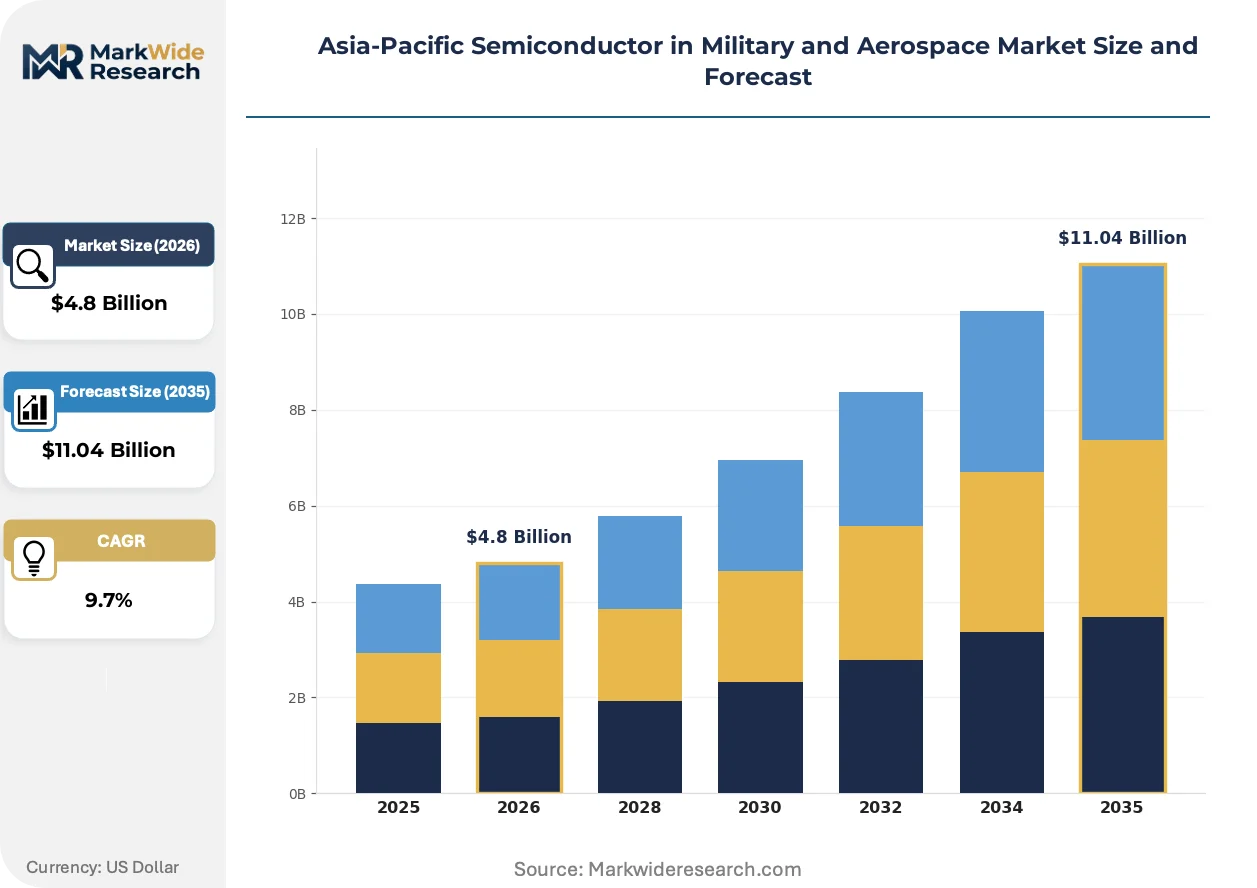
Market Dynamics
Defense procurement cycles across Asia-Pacific are compressing qualification timelines for radiation-hardened components, forcing foundries to accelerate process certification without compromising military-grade reliability standards. This structural pressure is redrawing competitive boundaries between captive military fabs and commercial foundries seeking dual-use revenue streams.
Growth Catalysts
- Unmanned Aerial Systems:Defense ministries in Australia, Japan, and South Korea are expanding drone fleet procurement, driving component demand for guidance processors and RF front-ends that operate across contested electromagnetic environments.
- China's Dual Carbon Goals:Beijing's energy efficiency mandates under GB standards are redirecting state funding toward domestic foundry upgrades for military-grade silicon carbide and gallium nitride processes.
- JIS Standards Modernization:Japan's METI is streamlining defense procurement qualification pathways, reducing time-to-contract for qualified component vendors serving satellite and fighter avionics programs.
Market Restraints
- EUV Lithography Concentration:Advanced node access depends on equipment supply chains centered in the Netherlands and Japan, creating single-source vulnerability for aerospace SoC production.
- Gallium Nitride Substrate Costs:Raw material volatility for GaN-on-SiC wafers compresses margin pools in RF power amplifier segments where radiation-hardening requirements already limit supplier pools.
- SAMR Anti-Foreign Dependency Catalogues:China's redirection of military semiconductor sourcing toward domestic champions is fragmenting regional supply chains and raising compliance costs for foreign component vendors.
Strategic Opportunities
- Vietnam and Indonesia:Emerging defense modernization programs in Southeast Asia present first-mover advantages for qualified component vendors establishing local technical support infrastructure.
- System-in-Package Convergence:Heterogeneous integration of chiplets with 2.5D interposers is opening white space for packaging houses to capture value previously concentrated at monolithic foundries.
- South Korea's K-Chips Act:Seoul's tax incentives and R&D subsidies for strategic semiconductor technologies are lowering capital barriers for aerospace-focused foundry expansion.
Industry Challenges
- Radiation-Hardening Design Expertise:The scarcity of engineers proficient in single-event upset mitigation and total ionizing dose hardening is extending development cycles for next-generation satellite processors.
- Dual-Use Export Control Alignment:South Korea's MFDS coordination with allied frameworks is creating classification complexity that delays contract execution for components with ambiguous military-civilian applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor in Military and Aerospace Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Memory Chips, Power Management ICs, RF Components Technology: Analog, Digital, Mixed-Signal, System-on-Chip End User: Defense Contractors, Aerospace OEMs, Military Agencies, Simulation Providers Application: Communication Systems, Navigation Systems, Surveillance Equipment, Avionics |
| Companies Covered | Intel Corporation, STMicroelectronics NV, NXP Semiconductors NV, Samsung Electronics Co. Ltd, Toshiba Corporation, Infineon Technologies AG, Renesas Electronics, Texas Instruments, Analog Devices, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor in Military and Aerospace Market Evolving Landscape
Monolithic integration architectures are yielding to disaggregated chiplet strategies across Asia-Pacific defense programs, compressing development timelines while introducing new interposer reliability requirements for extreme environment operation.
Chiplet-based system-in-package designs are decomposing traditional monolithic aerospace SoCs into function-specific dies interconnected through silicon interposers. Japanese satellite OEMs are adopting this approach for payload processors to isolate radiation-sensitive logic from hardened I/O functions. The technology is decomposing value concentration at leading-edge foundries by enabling advanced packaging houses to capture margin previously locked at monolithic nodes.
China's SAMR enforcement of GB standards and anti-foreign dependency catalogues is mandating domestic sourcing ratios for military semiconductor procurement. This policy is fragmenting regional supply chains and accelerating capital deployment into indigenous foundry capacity. Foreign component vendors are responding by establishing joint ventures with Chinese packaging houses to maintain access to defense programs.
Defense procurement offices are consolidating vendor qualification lists and demanding multi-year supply commitments with fixed pricing mechanisms. This behavioral shift is displacing spot-market purchasing for radiation-hardened components and favoring foundries with captive military capacity. The pattern is most visible in South Korea, where aerospace OEMs are awarding sole-source contracts to Samsung's foundry division for indigenous fighter avionics programs.
Asia-Pacific Semiconductor in Military and Aerospace Market Segmentation
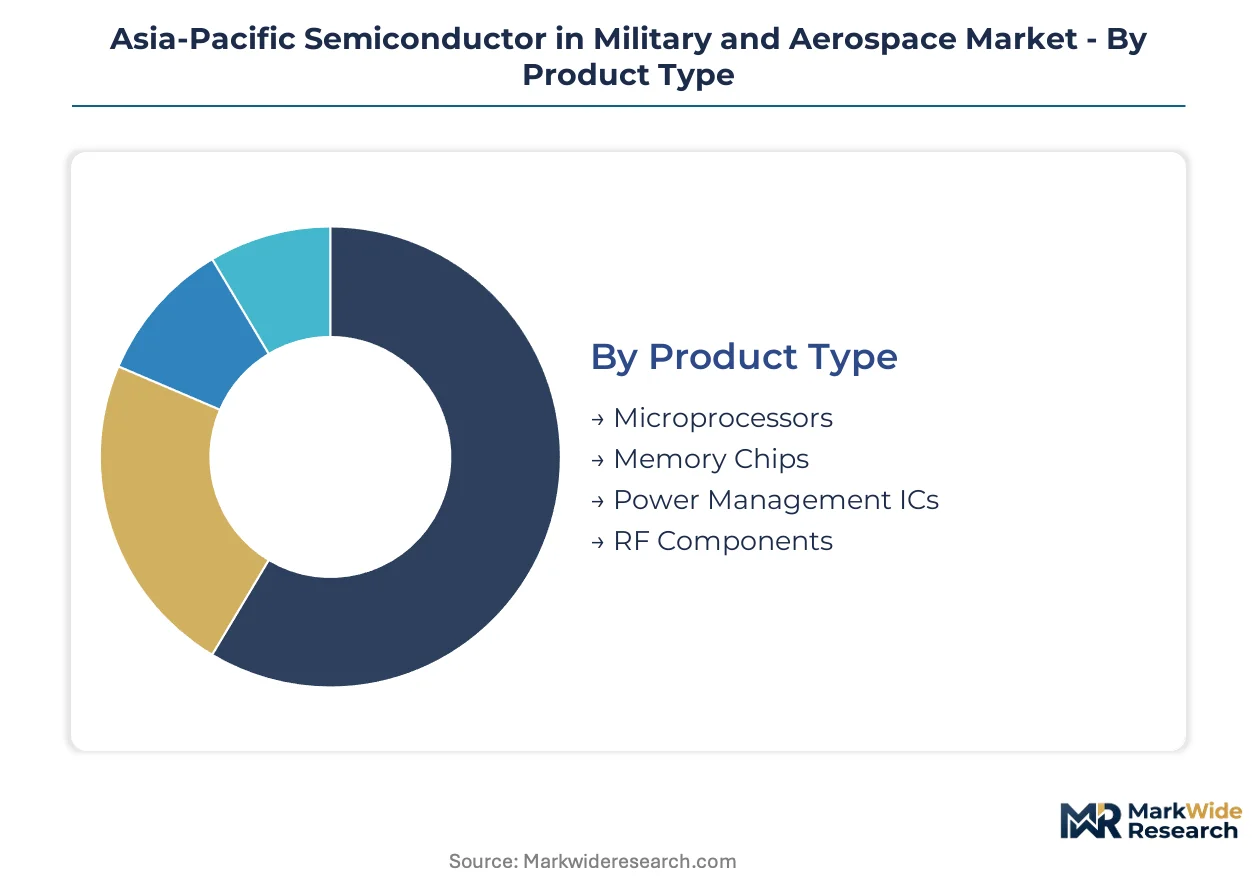
The Asia-Pacific semiconductor defense supply base fragments across product architectures, process technologies, procurement channels, and mission applications. Each segmentation axis carries distinct qualification pathways and margin structures that shape vendor competitive positioning.
Product Type:
Regulatory differentiation across Japan's METI, South Korea's MFDS, and China's SAMR creates divergent certification requirements for each product category, with radiation-hardening standards tightening most aggressively for mission-critical compute and RF functions.
- Microprocessors:Radiation-hardened CPUs and GPUs fabricated on mature nodes (28nm-65nm) with triple-modular redundancy and error-correcting memory controllers. Demand concentrates in Japan's satellite guidance systems and South Korea's indigenous fighter avionics, where METI and DAPA procurement offices mandate domestic packaging for classified programs.
- Memory Chips:SRAM and MRAM devices engineered for total ionizing dose tolerance above 300 krad(Si) with single-event upset rates below 10⁻¹² errors per bit-day. South Korean aerospace OEMs are consolidating sourcing toward Samsung's captive foundry for indigenous programs, while Japanese satellite builders qualify multiple vendors under streamlined JIS pathways.
- Power Management ICs:Wide-bandgap silicon carbide and gallium nitride converters handling 600V-1700V bus architectures for radar and electronic warfare systems.
- RF Components:GaN-on-SiC power amplifiers and phased-array transceivers operating across L-band through Ka-band for contested electromagnetic environments.
Memory Chips handle the majority of throughput across regional defense procurement; RF Components are expanding most quickly on share as electronic warfare modernization accelerates.
Technology:
Cost tier separation between mature-node analog processes and leading-edge digital integration is redrawing foundry customer relationships across the region's defense industrial base.
- Analog:Bipolar and BiCMOS processes on 180nm-350nm nodes for precision voltage references, operational amplifiers, and sensor signal conditioning. China's SAMR anti-foreign dependency catalogues are redirecting military analog sourcing toward domestic foundries in Wuxi and Hefei, fragmenting supplier pools for foreign component vendors.
- Digital:CMOS logic families with radiation-hardened cell libraries for discrete logic and FPGA fabric implementations. Australian defense contractors are accelerating digital component qualification timelines under compressed procurement cycles for unmanned aerial systems.
- Mixed-Signal:Data converters and PLLs integrating precision analog front-ends with digital calibration engines on 65nm-130nm nodes.
- System-on-Chip:Heterogeneous integration of CPU, DSP, RF, and power management functions onto single die for size-weight-power constrained payloads.
Analog dominates current procurement volumes; System-on-Chip shows the steepest expansion trajectory as aerospace OEMs consolidate multi-function architectures.
End User:
Customer type determines contract structure, with defense agencies demanding multi-year supply commitments and fixed pricing that commercial foundries struggle to accommodate.
- Defense Contractors:Tier-1 system integrators in Japan, South Korea, and Australia managing platform-level procurement for satellites, fighters, and naval systems. Japan's METI streamlines vendor qualification for contractors serving satellite programs, reducing time-to-contract for radiation-hardened component suppliers.
- Aerospace OEMs:Airframe and engine manufacturers specifying chip-level requirements for avionics subsystems. South Korean aerospace OEMs are awarding sole-source foundry contracts to Samsung for indigenous fighter programs, concentrating supply relationships.
- Military Agencies:Direct procurement offices in China's PLA and India's DRDO setting technical specifications and domestic sourcing ratios.
- Simulation Providers:Hardware-in-the-loop test equipment vendors requiring commercial-grade silicon with extended temperature ranges for training systems.
Defense Contractors manage the bulk of component procurement volume; Military Agencies are gaining share fastest as direct sourcing expands under sovereignty mandates.
Application:
Application-specific reliability requirements create divergent qualification cost structures, with space-grade components demanding 10-100x testing intensity versus aviation-qualified alternatives.
- Communication Systems:Software-defined radios and satellite transponders requiring wideband ADCs/DACs and GaN power amplifiers. Australia's defense ministry is expanding drone fleet procurement with hardened communication processors for contested electromagnetic environments.
- Navigation Systems:GPS/GNSS receivers and inertial measurement units with radiation-tolerant DSP cores for precision guidance. China's BeiDou military terminals are driving domestic MEMS foundry investment under SAMR localization mandates.
- Surveillance Equipment:EO/IR sensors and synthetic aperture radar with high-speed data converters and FPGA-based signal processing.
- Avionics:Flight control computers and engine management systems with DO-178C certifiable software stacks and ARINC 664 networking.
Communication Systems absorb the largest share of regional component procurement; Navigation Systems are climbing the fastest as precision-strike modernization spreads across Asia-Pacific militaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in Australia and Japan exhibit the highest price elasticity for radiation-hardened components, while China's military agencies prioritize domestic sourcing ratios over unit cost considerations.
China
PLA-directed satellite constellation expansion and indigenous fighter programs are absorbing gallium nitride power amplifiers from domestic foundries. SAMR enforces GB standards and anti-foreign dependency catalogues that mandate localization ratios above 70% for military semiconductor procurement. Wuxi and Hefei clusters concentrate state-funded capacity upgrades for silicon carbide process nodes.
Japan
Space agency satellite launches and maritime patrol drone procurement are accelerating demand for radiation-hardened memory devices. METI administers JIS standards that streamline defense qualification pathways for domestic packaging houses. Tokyo-Osaka corridor foundries dominate satellite processor output through captive EUV lithography partnerships.
South Korea
KF-21 fighter avionics and naval combat system modernization are consolidating component sourcing toward indigenous suppliers. MFDS coordinates dual-use export control classifications with allied frameworks, tightening market access for non-domestic vendors. Seoul Capital Area system-on-chip foundry clusters control advanced node access for aerospace OEMs.
Australia
MQ-28 Ghost Bat and maritime surveillance drone fleet expansion are driving RF component demand for contested electromagnetic environments. Defence Department procurement offices compress qualification timelines under accelerated modernization schedules. Melbourne-Canberra corridor system integrators are establishing technical support infrastructure for unmanned aerial programs.
India
DRDO-directed missile guidance and satellite navigation programs are expanding domestic MEMS foundry investment under strategic electronics mission mandates. Defence Procurement Procedure revisions prioritize indigenous design and development contracts for semiconductor subsystems. Bengaluru-Hyderabad clusters concentrate fabless design houses serving military agency specifications.
Asia-Pacific Semiconductor in Military and Aerospace Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operators commanding premium pricing for radiation-hardened qualification while fabless designers compete on development velocity. The structure bifurcates returns across packaging-dominant and lithography-dominant business models. Three archetypes prevail: IDM houses with in-house EUV capacity, radiation-hardening specialists with captive military fabs, and advanced packaging houses capturing chiplet integration value. Capacity expansion and strategic partnerships represent the dominant competitive vectors as sovereignty claims over critical chip capacity harden.
Within the integrated device manufacturer tier, Intel Corporation and Samsung Electronics Co. Ltd exemplify scale-driven positioning through captive manufacturing footprints spanning multiple geographies. STMicroelectronics NV occupies a specialist position bridging commercial automotive and defense-qualified process lines. These three anchors illustrate how lithography access and packaging depth determine competitive boundaries in radiation-hardened component supply.
| Leading Market Players |
|---|
| Intel Corporation |
| STMicroelectronics NV |
| NXP Semiconductors NV |
| Samsung Electronics Co. Ltd |
| Toshiba Corporation |
| Infineon Technologies AG |
| Renesas Electronics |
| Texas Instruments |
| Analog Devices |
| Others |
Value Network & Pricing Analysis
Multi-year sole-source contracts with fixed-price escalation clauses dominate defense procurement in Asia-Pacific, locking in wafer capacity at Samsung's Pyeongtaek complex and Intel's Kiryat Gat facility while insulating buyers from gallium nitride substrate volatility. Australia's Defence Department accelerates drone fleet procurement under compressed timelines that compress supplier qualification windows and concentrate pricing power with radiation-hardening specialists possessing captive military fabs.
Pricing Analysis
After-market technical support and long-term reliability warranties drive lifetime value for radiation-hardened component vendors serving Japanese satellite programs. Three-tier pricing structure across space-grade, aviation-qualified, and industrial-extended-temperature levels reflects certification intensity differentials, with space-grade processors commanding 10-15x premiums over commercial equivalents. Pricing pressure stems from China's SAMR localization mandates redirecting PLA procurement toward domestic foundries, compressing margin pools for foreign suppliers. Defense contractors in South Korea exhibit lowest price sensitivity due to sole-source dependencies for KF-21 avionics, while Australian system integrators show highest elasticity as they qualify multiple vendors for MQ-28 Ghost Bat programs.
Supply Chain Analysis
Strategic stockpiling of EUV lithography equipment and gallium nitride substrates supersedes just-in-time preferences across Asia-Pacific defense procurement offices confronting single-source vulnerabilities. Supply concentrates in South Korea's Seoul Capital Area for advanced-node system-on-chip production, Japan's Tokyo-Osaka corridor for satellite processors, and China's Wuxi-Hefei clusters for silicon carbide power devices. Raw material dependencies encompass high-purity silicon wafers, rare-earth elements for GaN substrates, and photoresist chemicals from Japanese suppliers. Tariff exposure intensifies as China's anti-foreign dependency catalogues fragment regional trade flows. Distribution runs through defense contractor tier-1 system integrators with direct military agency contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers proficient in single-event upset mitigation and total ionizing dose hardening number fewer than five hundred across the entire Asia-Pacific region, creating a chokepoint that extends satellite processor development cycles by eighteen to twenty-four months. This capability scarcity concentrates competitive returns with foundries possessing captive radiation-hardening design teams.
For Market Incumbents: Secure multi-year supply commitments with Japan's METI-qualified packaging houses before JIS standards modernization completes, locking in satellite program access against emerging domestic competitors. Expand in-house EUV lithography partnerships to defend advanced node access for aerospace SoC production as South Korea's K-Chips Act subsidizes rival capacity additions. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia's emerging defense modernization programs where first-mover advantages remain available for qualified component vendors establishing local technical support infrastructure. Target system-in-package convergence opportunities in heterogeneous chiplet integration, capturing value previously concentrated at monolithic foundries through 2.5D interposer specialization. For Investors and Strategic Acquirers: Radiation-hardening specialists with captive military fabs and established DAPA or METI qualification pathways represent the most defensible acquisition targets in a market where certification timelines stretch five to seven years. Monitor South Korea's MFDS dual-use export control alignment with allied frameworks as the inflection signal; accelerated coordination would elevate compliance costs for non-domestic vendors and widen moats around indigenous suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardening Certification Investment | Accelerates DAPA and METI qualification timelines for satellite processor vendors. |
| EUV Lithography Partnership Expansion | Secures advanced node access for KF-21 fighter avionics SoC production. |
| System-in-Package Capability Buildout | Captures chiplet integration value from monolithic foundries through 2.5D interposers. |
| Southeast Asia Technical Support Infrastructure | Establishes first-mover positioning in Vietnam and Indonesia drone procurement. |
| Domestic Foundry Joint Venture Formation | Maintains PLA program access under SAMR anti-foreign dependency enforcement. |
Research Methodology
Desk research of customs filings, defense procurement registries, and foundry capacity disclosures preceded structured interviews with DAPA program managers, METI standards administrators, radiation-hardening design engineers, and aerospace OEM procurement directors. Primary intelligence was cross-validated against secondary sources including MFDS export control classifications, SAMR localization mandates, and satellite launch manifests. Bottom-up wafer demand estimates were triangulated with top-down defense budget allocations across the analysis window.
Variance decomposition across product type, technology node, end-user contracting structure, and mission application segments shaped the analytical framework. Modeled dimensions encompassed microprocessor architecture, memory density requirements, RF frequency bands, and radiation-hardening grade tiers. CAGRs were derived from segment-level demand build-ups validated against historical procurement patterns and announced platform production schedules. Forecast inputs incorporated gallium nitride substrate cost trajectories and EUV equipment delivery lead times.
Decision-makers should treat outputs as directional under assumptions of sustained defense modernization budgets and stable export control alignments; material deviation would warrant model refresh. Revision becomes warranted when China's SAMR enforcement intensity or South Korea's MFDS coordination pace crosses thresholds that alter qualified supplier pool dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Customized Avionic Systems Market
Avionics
Military Aircraft Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Aircraft EMI Shielding Market
Avionics
Electronic Flight Instrument System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Europe Military Aircraft Communication Avionics Market