
 Avionics LRU Repair and Test Services Market | 2026-2036
Avionics LRU Repair and Test Services Market Size, Share, and Industry Trends Forecast 2026-2036
Avionics LRU Repair and Test Services Market Insights
Defense operators are gaining share as military fleet sustainment budgets expand, and the avionics LRU repair and test services market is reorganizing around long-term performance-based logistics contracts. Honeywell International leverages its integrated supply chain to capture overhaul volumes for legacy cockpit systems. L3Harris Technologies sustains deep ties with US Department of Defense depots through proprietary test program sets. Safran anchors European military LRU workflows with its Bordeaux and Istres facilities.
Avionics LRU repair and test services encompass the diagnostic evaluation, fault isolation, component-level remediation, and recertification of line-replaceable units to manufacturer specifications and airworthiness standards, typically involving automated test equipment running BIT (built-in test) routines against parameters such as MTBF thresholds and environmental stress screening protocols. Functional testing commands premium pricing due to capital-intensive ATE requirements and scarce technician certification pools, while overhaul services generate recurring revenue streams tied to flight-hour accumulation. Component repair competes primarily on turnaround time and OEM authorization status, with margin pools concentrated among DER-approved specialty shops.
FAA airworthiness directives and EASA continuing airworthiness program requirements mandate documented traceability for all repair and test outcomes, compressing market access for uncertified providers. Military operators face additional DFARS flow-down clauses and MIL-STD-810 test compliance for mission-critical LRUs. Stakeholders must monitor how DO-178C software update validation standards propagate from commercial to military platforms, as this will reshape competency requirements and capital deployment across repair station networks.
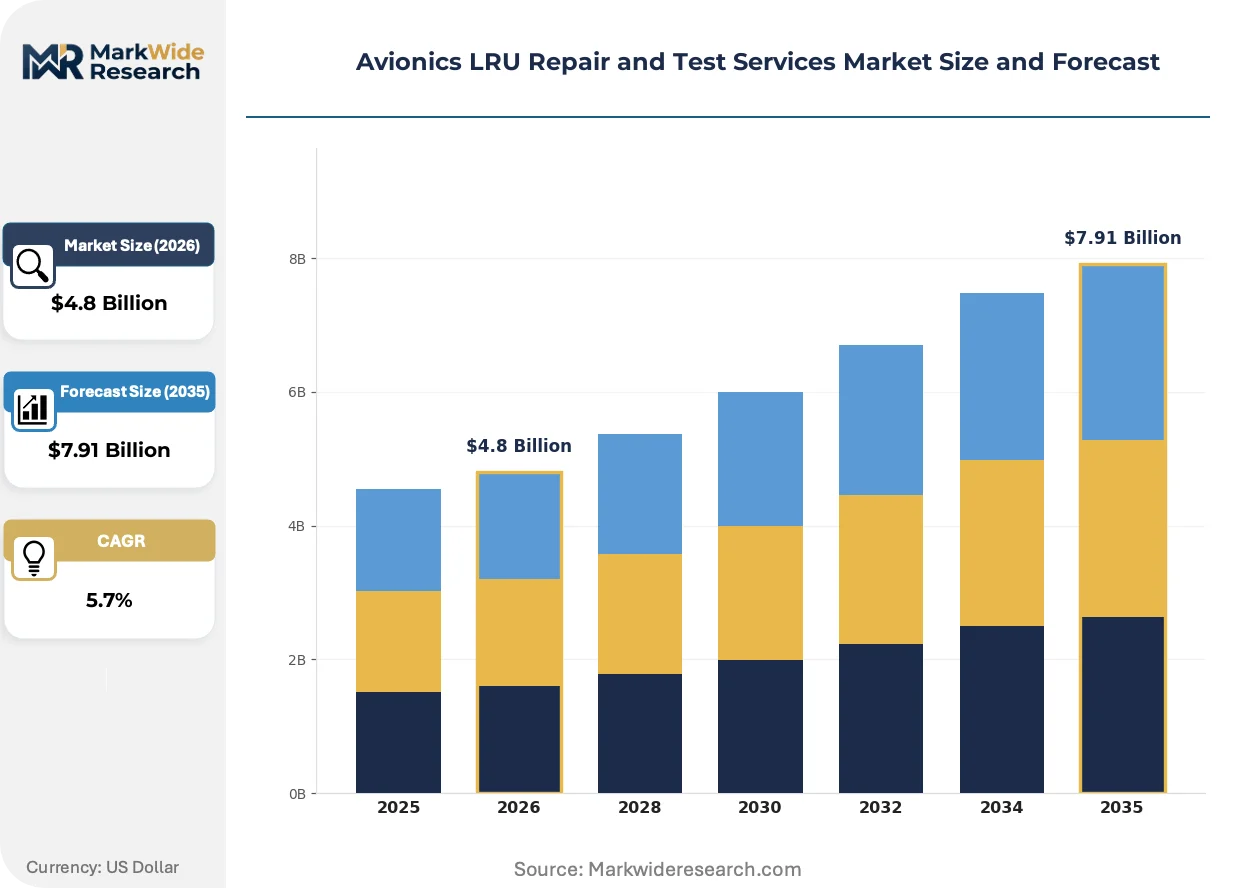
Market Dynamics
Performance-based logistics contracts are consolidating avionics LRU repair and test services around depot-level providers with captive automated test equipment and proprietary test program sets, compressing access for independent repair stations lacking military authorization.
Growth Catalysts
- FAA Airworthiness Directives:Tighter documentation mandates for traceability and repair outcomes are elevating demand for certified repair stations with DER-approved specialty capabilities.
- Military Fleet Sustainment:Aging platform fleets across defense operators are extending overhaul intervals and expanding long-term repair contracts for mission-critical line-replaceable units.
- ATE Capital Deployment:Automated test equipment investments in Oklahoma and Arizona MRO clusters are concentrating regional repair capacity and shortening turnaround times for commercial aviation operators.
Market Restraints
- Scarce Technician Certification Pools:Functional testing commands premium pricing due to capital-intensive ATE requirements and limited FAA-certified avionics technician availability.
- DFARS Flow-Down Compliance:Military operators face additional MIL-STD-810 test compliance burdens for mission-critical LRUs, extending qualification timelines for commercial repair stations.
- Component-Level Margin Compression:Component repair competes primarily on turnaround time and OEM authorization status, with margin pools concentrated among narrow DER-approved specialty shops.
Strategic Opportunities
- DO-178C Software Validation:Propagation of software update validation standards from commercial to military platforms will reshape competency requirements and capital deployment across repair station networks.
- EASA Continuing Airworthiness Program:European regulatory tightening creates documented traceability requirements that favor established providers with Bordeaux and Istres facility footprints.
- Built-In Test Routine Integration:Convergence of BIT protocols with environmental stress screening is enabling predictive maintenance models that extend LRU service life and reduce unscheduled removals.
Industry Challenges
- ATE Obsolescence Management:Capital-intensive automated test equipment requires continuous calibration and software updates to maintain alignment with evolving LRU configurations.
- Multi-Standard Certification Burden:Repair stations must simultaneously maintain FAA, EASA, and military depot authorizations, each with distinct audit cycles and documentation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avionics LRU Repair and Test Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Component Repair, Functional Testing, Calibration, Overhaul, Software Update End User: Original Equipment Manufacturers, Tier-1 Suppliers, Maintenance Providers, Airlines, Airframe Integrators Technology: Line Replaceable Units, Modular Avionics, Embedded Systems, Digital Signal Processing, Fault Detection Systems Application: Commercial Aircraft, Business Jets, Military Aircraft, Unmanned Aerial Vehicles, Cargo Planes |
| Companies Covered | Honeywell International, L3Harris Technologies, Safran, Thales, Teledyne Technologies, Garmin, BAE Systems, Astronics, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avionics LRU Repair and Test Services Market Trends and Innovations
Diagnostic architectures are splitting between legacy analog test benches and software-defined measurement systems, with implications for technician training paths and facility capital planning.
Modular automated test equipment is bifurcating repair station investment strategies. PXI-based instrumentation reduces footprint and reconfiguration costs for high-mix LRU portfolios. Commercial MRO operators in the United States are adopting these platforms aggressively to handle diverse cockpit system generations. Military depots retain legacy ATE architectures, creating a two-tier capability landscape where commercial providers gain flexibility and defense stations maintain deep program-specific expertise.
REACH substance restrictions and RoHS compliance deadlines are forcing component-level material substitutions in European-sourced LRUs. Repair stations must validate alternative solder alloys and conformal coatings against original MTBF thresholds. Safran's Bordeaux facility has established dedicated environmental screening protocols to manage this transition, while smaller independent shops face qualification cost barriers.
Flight-hour-based contracting is displacing transactional repair orders among major commercial operators. Airlines now demand guaranteed availability commitments with penalty clauses for AOG events. This concentrates repair volume with vertically integrated providers capable of spare LRU pooling and exchange programs, particularly visible among US-based carriers operating narrow-body fleets with high dispatch reliability requirements.
Avionics LRU Repair and Test Services Market Segmentation
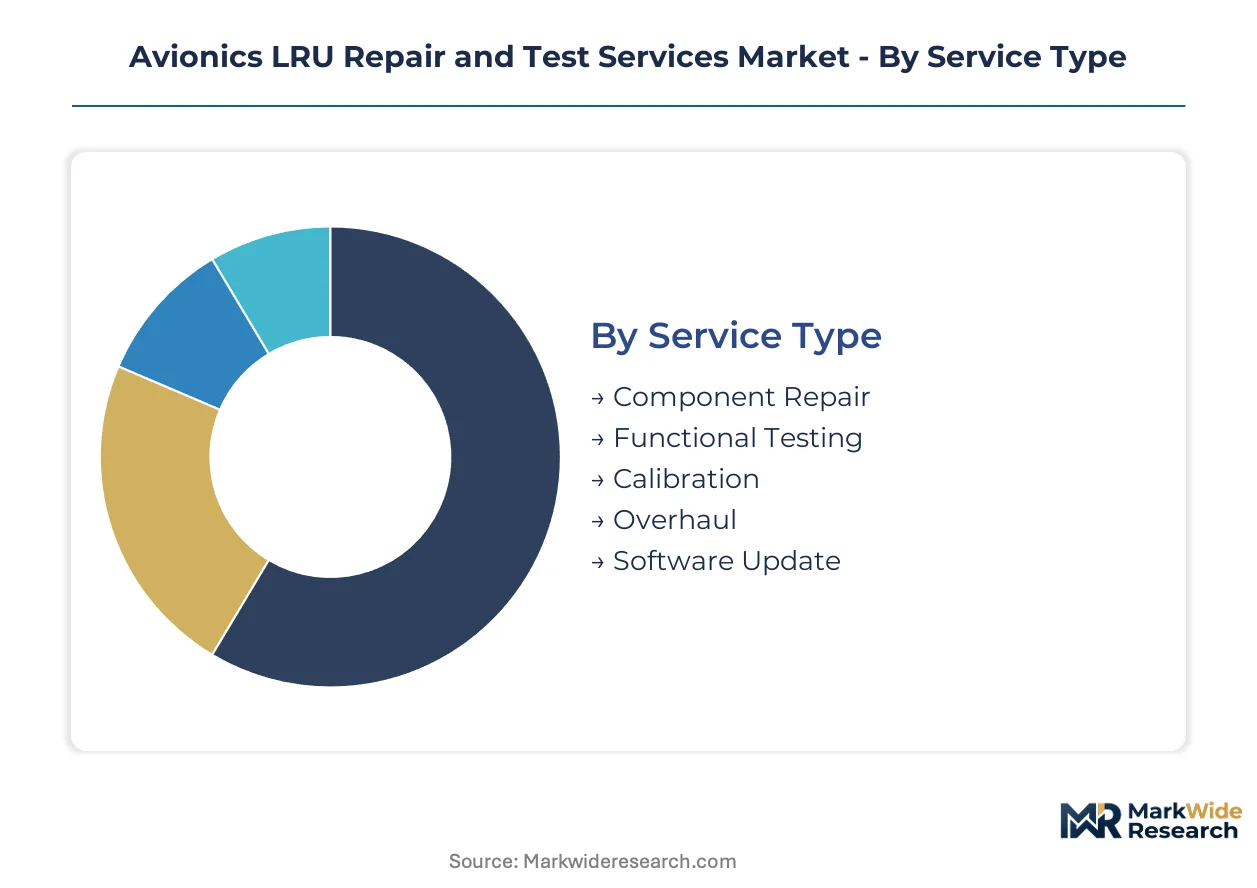
Segmentation in avionics LRU repair and test services reveals how margin pools concentrate around certification tiers and platform complexity. Service type and end-user dynamics determine capital deployment strategies across repair station networks.
Service Type:
Margin pools concentrate in functional testing and overhaul services where ATE ownership creates defensive moats against independent competitors.
- Component Repair:Discrete circuit card and semiconductor remediation at the board level, requiring DER-approved specialty shops with micro-soldering capabilities and conformal coating restoration. Demand clusters at Oklahoma and Arizona MRO hubs where commercial airlines prioritize turnaround time over unit cost.
- Functional Testing:Automated test equipment validation against manufacturer specifications using proprietary test program sets and BIT routine execution. Military depot contracts in the United States drive premium pricing due to MIL-STD-810 compliance burdens and scarce technician certification pools.
- Calibration:Precision alignment of sensor and measurement circuits to maintain airworthiness traceability under FAA and EASA mandates.
- Overhaul:Complete LRU disassembly, inspection, and rebuild to extend service life for aging platform fleets.
- Software Update:DO-178C validation and firmware loading for embedded avionics systems.
The dominant share belongs to functional testing, while software update services are closing the gap fastest as DO-178C standards propagate across military platforms.
End User:
Procurement authority determines contract structure, with airlines driving flight-hour-based availability models and OEMs controlling proprietary test program access.
- Original Equipment Manufacturers:Honeywell and Safran leverage captive repair networks to protect intellectual property around legacy cockpit system architectures. Their authorization status gates independent shop access to proprietary test program sets and BIT protocols.
- Tier-1 Suppliers:Collins Aerospace and Thales Avionics intermediate between OEMs and airlines, aggregating LRU volumes for depot-level economies.
- Maintenance Providers:Third-party MRO operators compete on turnaround time and EASA/FAA dual certification.
- Airlines:US-based narrow-body fleet operators demand guaranteed availability with AOG penalty clauses.
- Airframe Integrators:Boeing and Airbus channel warranty-period repairs through authorized networks.
Airlines command the largest contract value, though maintenance providers are expanding share fastest through flight-hour-based service agreements.
Technology:
Technology segmentation tracks the shift from discrete analog LRUs toward software-defined architectures with embedded diagnostics.
- Line Replaceable Units:Self-contained avionics boxes with standardized form factors for rapid aircraft-level substitution. Aging military platform sustainment in the United States sustains overhaul demand for legacy analog and early digital generations.
- Modular Avionics:Integrated Modular Avionics cabinets with partitioned software functions reduce LRU count but increase test complexity. PXI-based ATE investments by commercial MRO operators target high-mix reconfiguration for diverse cockpit generations.
- Embedded Systems:Microcontroller-based control units with firmware-dependent functionality.
- Digital Signal Processing:Software-defined radio and radar processing modules.
- Fault Detection Systems:Built-in test equipment and prognostic health monitoring circuits.
Line replaceable units retain the installed base majority, while modular avionics is climbing the fastest as IMA architectures penetrate new platform designs.
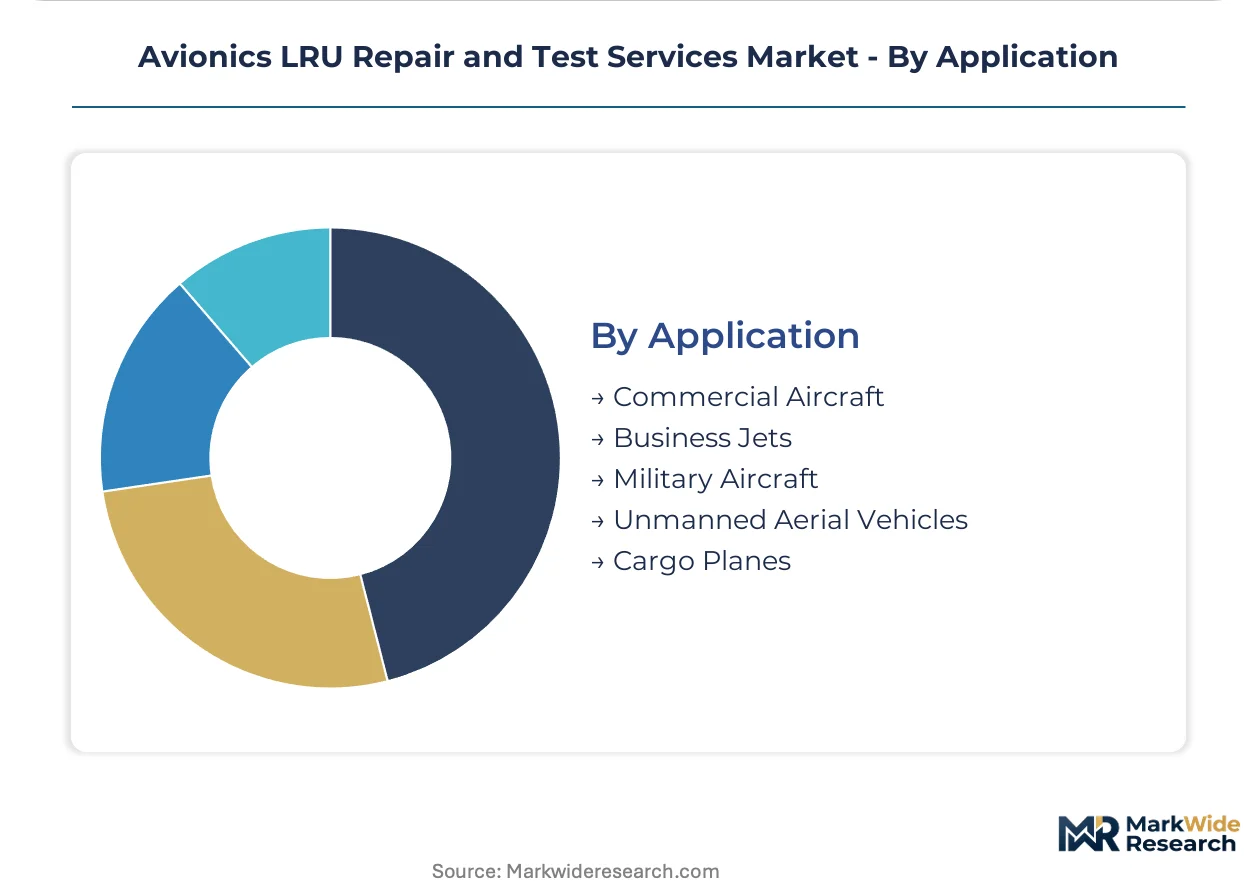
Application:
Application segmentation reflects divergent regulatory burdens between commercial airworthiness mandates and military mission-critical requirements.
- Commercial Aircraft:Narrow-body and wide-body fleet sustainment governed by FAA airworthiness directives and EASA continuing airworthiness programs. US-based carriers operating high-cycle routes concentrate repair volume with vertically integrated providers capable of spare LRU pooling.
- Military Aircraft:Platform-specific sustainment contracts with DFARS flow-down clauses and MIL-STD-810 environmental stress screening. Defense depot maintenance networks in Oklahoma and Arizona handle classified program LRUs with restricted commercial access.
- Business Jets:Part 135 operator maintenance with premium dispatch reliability requirements.
- Unmanned Aerial Vehicles:Emerging class with evolving certification standards.
- Cargo Planes:Freighter conversion and heavy-check LRU replacement cycles.
Commercial aircraft generate the highest absolute revenue, though military applications are expanding most quickly as aging fleet sustainment budgets rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense depot networks and commercial MRO clusters concentrate repair capacity in specific metropolitan zones. FAA and EASA regulatory divergence shapes where providers locate certification assets. Each geography presents distinct authorization barriers and fleet sustainment demand profiles.
United States
Military sustainment contracts and narrow-body fleet operations drive substantial LRU volumes. FAA airworthiness directives mandate documented traceability for all repair outcomes. Oklahoma and Arizona host concentrated MRO clusters where automated test equipment investments shorten turnaround times for commercial operators.
France
Safran's Bordeaux and Istres facilities anchor European military LRU workflows with proprietary environmental screening protocols. EASA continuing airworthiness program requirements tighten test documentation standards. REACH substance restrictions and RoHS compliance deadlines force component-level material substitutions in locally sourced units.
Germany
Rohde & Schwarz leverages domestic precision instrumentation expertise to serve test program set development. KBA oversight intersects with military export control frameworks for classified avionics. Southern industrial regions concentrate specialty shops with DER-approved micro-soldering capabilities.
United Kingdom
BAE Systems maintains deep program-specific expertise through legacy military depot architectures. UK Ministry of Defence flow-down clauses extend DFARS-equivalent compliance burdens to subcontractors. Southeast England clusters house dual-certified repair stations serving both commercial and defense LRU streams.
Israel
Defense-focused avionics specialists exploit mission-critical LRU sustainment demand from regional military operators. Israeli Air Force technical standards propagate into commercial test protocol adaptations. Tel Aviv metropolitan engineering talent pools support software-defined measurement system development.
Avionics LRU Repair and Test Services Market Competitive Landscape
Concentration sits with vertically integrated OEMs and authorized depot providers holding captive automated test equipment. Performance-based logistics contracts compress independent repair station access. Three archetypes dominate: integrated avionics OEMs with proprietary test program sets, defense depot operators with classified program authorization, and commercial MRO specialists with PXI-based flexible instrumentation. Competitive moves center on long-term service agreement capture and multi-standard certification stacking.
Among US-based integrated suppliers, Honeywell International and L3Harris Technologies exemplify the OEM-depot hybrid archetype, each leveraging proprietary supply chain control and military authorization status to gate independent competitor access. Safran represents the European equivalent, anchoring Bordeaux and Istres facility networks against REACH-driven qualification cost barriers that exclude smaller independent shops.
| Leading Market Players |
|---|
| Honeywell International |
| L3Harris Technologies |
| Safran |
| Thales |
| Teledyne Technologies |
| Garmin |
| BAE Systems |
| Astronics |
| Rohde & Schwarz |
| Others |
Pricing and Supply Chain Analysis
Ninety-day turnaround guarantees for military depot contracts concentrate pricing power with Oklahoma and Arizona MRO clusters holding captive automated test equipment, while commercial operators absorb cost compression through flight-hour-based availability models with penalty exposure.
Pricing Analysis
FAA airworthiness directives dictate the pricing tier structure across the avionics LRU repair and test services market. Three-tier pricing structure across premium, standard, and economy levels separates DER-approved specialty shops from dual-certified commercial stations and uncertified independents. Cost compression in component repair is intensifying because turnaround time competition and OEM authorization status gate margin pools. Airlines operating narrow-body fleets exhibit highest price sensitivity due to guaranteed availability commitments with AOG penalty clauses, while military depot operators prioritize MIL-STD-810 compliance over unit cost.
Supply Chain Analysis
The United States and France anchor automated test equipment production and proprietary test program set development for avionics LRU repair and test services. Semiconductor components and precision instrumentation draw from Taiwan and Germany, while alternative solder alloys and conformal coatings rest on REACH-compliant European sourcing. Single-source vulnerability concentrates around proprietary BIT protocols controlled by integrated OEMs. Distribution runs through performance-based logistics contracts that consolidate volume with vertically integrated providers capable of spare LRU pooling and exchange programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as DO-178C software validation standards propagate from commercial to military platforms, creating competency gaps that specialized repair stations can exploit.
For Market Incumbents: Shield proprietary test program set access through expanded military depot authorization and backward integration into PXI-based flexible instrumentation. Performance-based logistics contract consolidation threatens independent repair station access, while REACH substance restrictions and RoHS compliance deadlines elevate qualification cost barriers against smaller competitors. For New Entrants and Emerging Players: Anchor in software update services for embedded avionics systems, the fastest-closing gap segment as DO-178C standards reshape competency requirements. EASA continuing airworthiness program tightening in European markets creates documented traceability demand that favors new entrants with dedicated environmental screening protocols. Target dual FAA-EASA certification as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a defense-contract annuity play because aging military fleet sustainment budgets expand overhaul intervals and extend repair contract durations. Acquisition target archetype: DER-approved specialty shops with micro-soldering capabilities in Oklahoma or Arizona MRO hubs. The signal to watch is propagation velocity of DO-178C validation standards across military platform upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contract Capture | Long-term service agreements with US Department of Defense depots lock in automated test equipment utilization and proprietary test program set deployment. |
| Multi-Standard Certification Investment | Simultaneous FAA, EASA, and military depot authorization expands addressable contract volume across commercial and defense LRU streams. |
| PXI-Based Flexible Instrumentation Adoption | Modular ATE platforms reduce reconfiguration costs for high-mix LRU portfolios spanning diverse cockpit system generations. |
| DO-178C Competency Development | Software validation capability expansion captures firmware loading demand as military platforms adopt commercial avionics architectures. |
| Environmental Screening Protocol Establishment | REACH and RoHS compliance infrastructure protects margin pools against material substitution qualification barriers affecting smaller competitors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with MRO operations directors, military depot program managers, avionics technician certification bodies, and DER-approved specialty shop owners; and secondary validation through FAA airworthiness directive filings, EASA continuing airworthiness program documentation, MIL-STD-810 test specification archives, and customs records of automated test equipment trade flows. Bottom-up repair station capacity modeling and top-down defense sustainment budget allocation triangulation anchored volume estimates.
Across the analysis window, forecasts deployed service type, end user procurement authority, technology architecture, and application regulatory burden as segmentation dimensions. CAGRs derived from flight-hour accumulation curves, fleet age distributions, and contract renewal velocity observations. Industry-specific inputs included BIT protocol adoption rates and PXI-based ATE investment trajectories in Oklahoma and Arizona MRO clusters.
Material uncertainties — regulatory divergence between FAA and EASA documentation standards, DFARS clause modifications, ATE obsolescence acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around technician certification pool expansion and military depot authorization continuity. Recalibration cycles align with material shifts in DO-178C propagation velocity and REACH compliance deadline enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Global Avionics Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Customized Avionic Systems Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Aircraft Computers Market
Avionics
Aircraft EMI Shielding Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Display for Avionics Application Market