
 Temperature Sensor in the Aerospace & Defense Market | 2026-2036
Temperature Sensor in the Aerospace & Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Sensor in the Aerospace & Defense Market Insights
Qualified aerospace sensor engineering talent is collapsing across Western supply chains, forcing primes to internalize capabilities that tier-two vendors once provided. Honeywell International Inc. leverages its captive foundry network to shield RTD and thermocouple production from external labor shortages. TE Connectivity Ltd. anchors its position through fiber-optic temperature sensing R&D aimed at hypersonic airframes. Meggitt PLC specializes in mineral-insulated cable assemblies that survive extreme thermal cycling in turbine applications.
Temperature sensors in aerospace and defense are transduction devices that convert thermal energy into measurable electrical signals, typically operating across ranges from cryogenic temperatures to over 1,700°C in rocket nozzle environments, with accuracy demands often tighter than ±0.5°C for flight-critical loops. Their primary purpose is to protect propulsion systems, structural components, and avionics from thermal overrun while feeding real-time data to vehicle management computers. Thermocouple architectures still dominate installed base volume due to legacy platform compatibility and wide operational range, though fiber-optic segments are capturing disproportionate R&D investment because electromagnetic immunity matters deeply in directed-energy and electronic warfare environments. Defense contractors as an end-user category concentrate the largest procurement budgets, but aerospace OEMs represent the faster-growing demand pool as commercial-military platform convergence accelerates.
FAA airworthiness directives and EASA CS-25 certification standards govern flight-critical temperature monitoring hardware, while ITAR and EAR export controls constrain cross-border technology transfer for military-grade sensors. The EU AI Act and emerging autonomous systems frameworks are beginning to touch sensor fusion architectures where temperature data feeds machine-learning loops. Stakeholders must decide whether to pursue dual-use certification paths that satisfy both civil aviation and defense procurement channels, or to segregate product lines and absorb duplicated qualification costs.
Market Dynamics
The collapse of qualified aerospace sensor engineering talent across Western supply chains is forcing prime contractors to internalize capabilities that tier-two vendors once provided, reshaping competitive boundaries and supplier relationships throughout the temperature sensing ecosystem.
Growth Catalysts
- FAA airworthiness directives:Tightening certification requirements for flight-critical temperature monitoring hardware are mandating upgraded sensor architectures across commercial and defense platforms, creating replacement demand for legacy installations.
- Hypersonic platform development:Directed-energy and electronic warfare systems require electromagnetic immunity that fiber-optic temperature sensing delivers, pulling R&D investment toward photonic transduction methods.
- NATO military vehicle modernization:Hardened sensing system procurement is accelerating as member states retrofit armored vehicles and next-generation platforms with distributed thermal monitoring networks.
Market Restraints
- Platinum group metal volatility:Thermocouple and RTD production depends on rhodium, platinum, and palladium inputs whose price swings compress sensor manufacturer margins unpredictably.
- ITAR and EAR export controls:Cross-border technology transfer restrictions for military-grade sensors fragment supply chains and prevent scale economies that civilian-only producers capture.
- Calibration infrastructure scarcity:Flight-critical loops demand accuracy tighter than ±0.5°C, yet qualified metrology labs capable of certifying cryogenic-to-1700°C ranges concentrate in three national industrial bases.
Strategic Opportunities
- Commercial-military platform convergence:Dual-use certification paths that satisfy both FAA airworthiness and defense procurement channels unlock volume efficiencies unavailable to segregated product lines.
- EU AI Act sensor fusion requirements:Emerging autonomous systems frameworks mandate temperature data integration into machine-learning loops, creating specification pull for smart sensor architectures.
- Mineral-insulated cable assembly specialization:Extreme thermal cycling survivability in turbine applications represents a defendable niche where engineering depth substitutes for scale.
Industry Challenges
- Foundry engineering talent scarcity:Captive thin-film deposition and ceramic packaging expertise is concentrating at primes, leaving tier-two vendors without access to process development capabilities.
- Dual qualification cost duplication:Segregated civil aviation and defense product lines force manufacturers to absorb parallel certification timelines and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Sensor in the Aerospace & Defense Market |
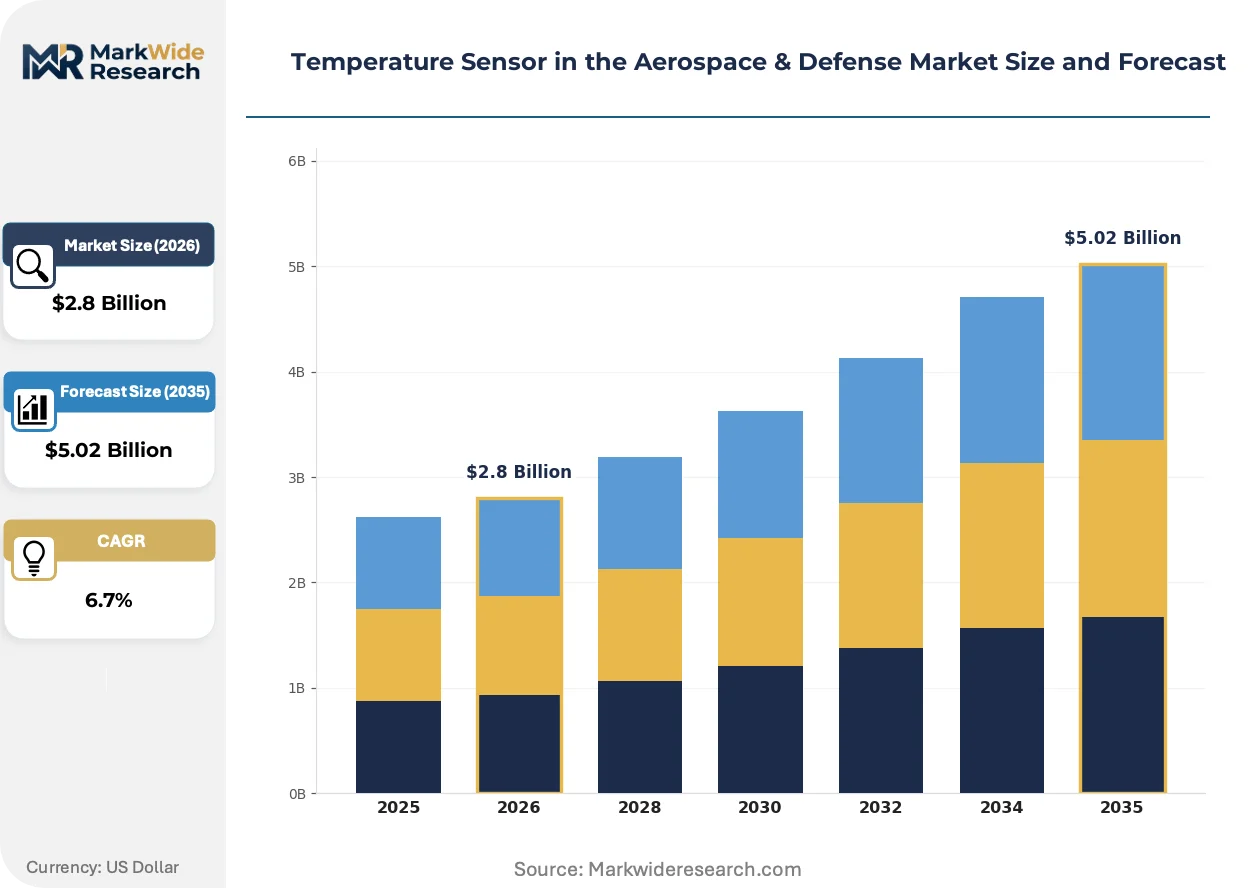
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouple, RTD, Bimetallic, Infrared Technology: Wireless, Digital, Analog, Fiber Optic Application: Aerospace Instruments, Military Vehicles, Satellites, Drones End User: Defense Contractors, Aerospace OEMs, Government Agencies, Research Institutions |
| Companies Covered | Honeywell International Inc., TE Connectivity Ltd., Meggitt PLC, Sensata Technologies Inc., Conax Technologies, Raytheon Technologies Corporation, Safran SA, Ametek Inc., Curtiss-Wright Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Sensor in the Aerospace & Defense Market Trends and Innovations
Electromagnetic immunity requirements from directed-energy weapons programs are accelerating photonic sensing architectures that legacy thermocouple networks cannot satisfy, compressing technology transition timelines across defense procurement.
Fiber-optic temperature sensing converts thermal energy into optical signals immune to radio-frequency interference, enabling distributed monitoring along single fibers rather than discrete wired points. Defense contractors developing hypersonic airframes and electronic warfare suites are adopting these systems at prototype-through-production pace. This photonic architecture is supplanting mineral-insulated thermocouple harnesses in flight-critical zones where electromagnetic pulse survivability determines platform viability.
EASA CS-25 certification standards are tightening material traceability and calibration documentation requirements for temperature monitoring hardware installed in commercial aircraft. The industrial consequence is a documentation burden that favors established primes with captive quality systems over emerging sensor specialists. Turbine engine OEMs in Germany and France are responding by pre-qualifying sensor suppliers through multi-year development contracts rather than transactional procurement.
Buyer concentration around defense primes and aerospace OEMs is compressing supplier negotiation leverage and elongating payment terms. Tier-two sensor vendors are responding by unbundling hardware from calibration services, creating recurring revenue streams that offset hardware margin pressure. This service unbundling is most visible in the United States defense industrial base, where platform integrators dominate procurement specification authority.
Temperature Sensor in the Aerospace & Defense Market Segmentation
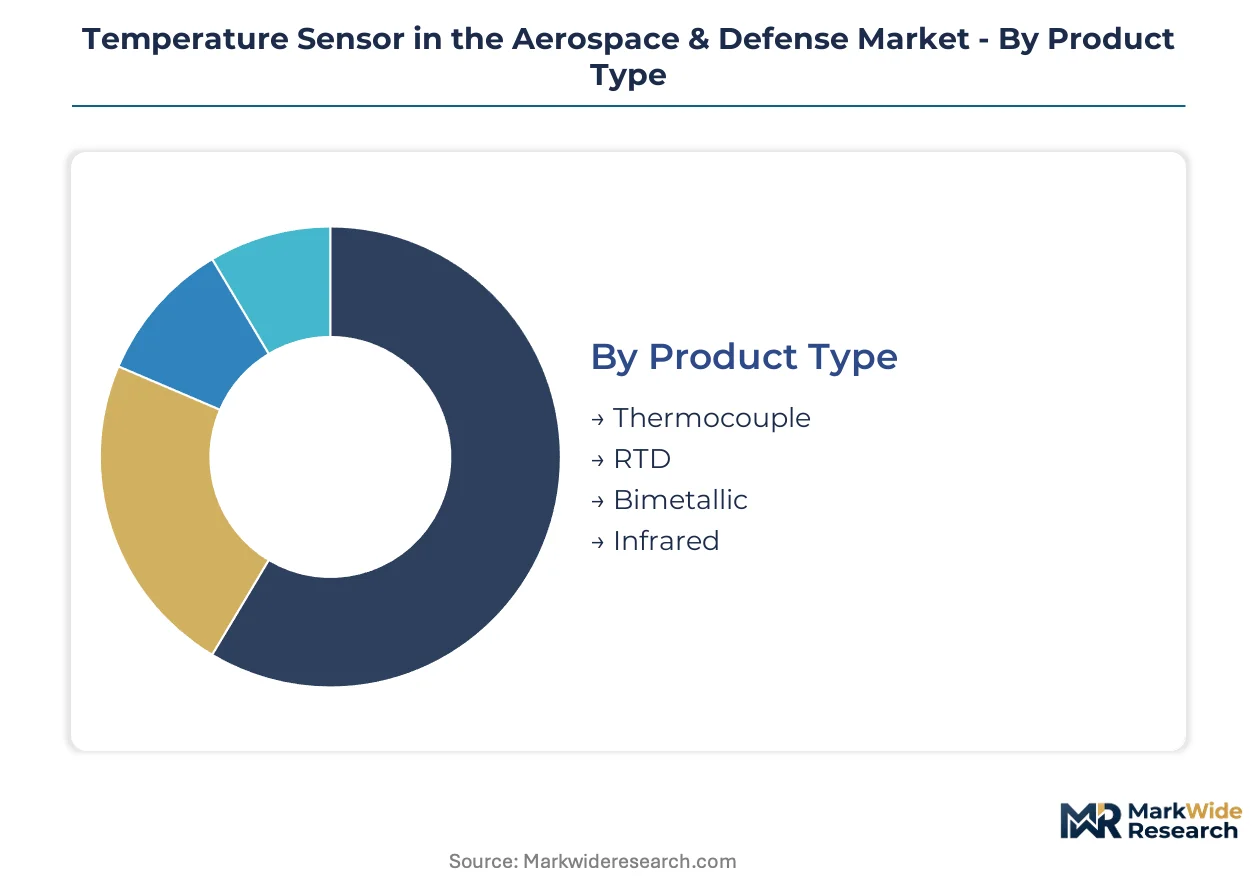
Temperature sensor procurement in aerospace and defense fragments across transduction physics, signal processing architectures, and platform integration requirements. Each segmentation axis carries distinct certification burdens and supply chain concentration patterns that determine vendor selection criteria.
Product Type:
Thermocouple and RTD production clusters in the United States and Germany due to platinum group metal refining infrastructure and captive foundry networks at Honeywell and TE Connectivity. Bimetallic and infrared architectures source more broadly from Asian component suppliers.
- Thermocouple:Mineral-insulated cable assemblies using Type K, J, and S junctions operate across cryogenic to 1,700°C ranges in rocket nozzle and turbine environments. Demand concentrates in United States defense primes executing hypersonic platform contracts where electromagnetic pulse survivability overrides precision requirements. FAA and EASA flight-critical loop specifications mandate these for legacy platform compatibility despite fiber-optic displacement pressure.
- RTD:Thin-film platinum elements deliver ±0.1°C accuracy for avionics thermal management and fuel system monitoring. German turbine engine OEMs in Munich and Stuttgart pre-qualify RTD suppliers through multi-year development contracts rather than transactional procurement, creating documentation barriers for emerging vendors.
- Bimetallic:Mechanical deflection sensors serve non-flight-critical HVAC and auxiliary system monitoring in ground support equipment and armored vehicle compartments.
- Infrared:Non-contact thermal imaging arrays monitor satellite bus thermal distribution and drone propulsion health without physical intrusion into sealed systems.
Thermocouple holds the largest share; momentum sits with RTD as digital engine control architectures proliferate.
Technology:
Cost tier separation is pronounced: fiber-optic and wireless systems command 3-5x unit premiums over analog equivalents, restricting deployment to flight-critical and directed-energy applications where electromagnetic immunity justifies expenditure.
- Wireless:RF telemetry eliminates harness weight in satellite and drone platforms where every gram determines launch economics. United States Space Force prototyping programs in Colorado Springs and Los Angeles Air Force Base are standardizing wireless sensor networks for rapid reconfiguration between mission profiles.
- Digital:Integrated ADC and compensation algorithms reduce calibration labor while feeding directly to vehicle management computers. European aerospace OEMs in Toulouse and Hamburg specify digital outputs to simplify EU AI Act compliance for autonomous system sensor fusion.
- Analog:Millivolt and resistance outputs persist in legacy military vehicle retrofit programs where platform electronics cannot accommodate protocol conversion.
- Fiber Optic:Photonic transduction survives electromagnetic pulse and high-radiation environments that disable electrical sensors. TE Connectivity's fiber-optic R&D targets hypersonic airframe integration where plasma sheath effects block RF communications.
Analog retains the largest installed base; fiber optic is expanding most quickly around directed-energy weapons programs.
Application:
Volume concentration varies sharply: aerospace instruments generate the highest unit volumes per platform, while satellites impose the most stringent qualification timelines and radiation-hardening requirements.
- Aerospace Instruments:Engine, environmental, and fuel system monitoring in commercial and military aircraft. German MTU Aero Engines and French Safran Aircraft Engines specify temperature sensors through exclusive supplier agreements that lock out tier-two vendors without captive turbine test facilities.
- Military Vehicles:Distributed thermal monitoring networks in armored personnel carriers and next-generation combat vehicles. NATO member states in Poland, Romania, and Norway are accelerating procurement through the European Defence Fund and national modernization budgets.
- Satellites:Bus thermal control and propulsion system monitoring in geostationary and low-earth-orbit platforms. ITAR restrictions fragment supply chains between United States, European, and Israeli satellite prime contractors.
- Drones:Compact, low-power sensors for unmanned aerial system propulsion and battery management. Commercial-military platform convergence is pulling civilian drone sensor specifications toward defense-grade electromagnetic immunity.
Aerospace instruments hold the largest share; military vehicles are gaining share fastest around NATO modernization acceleration.
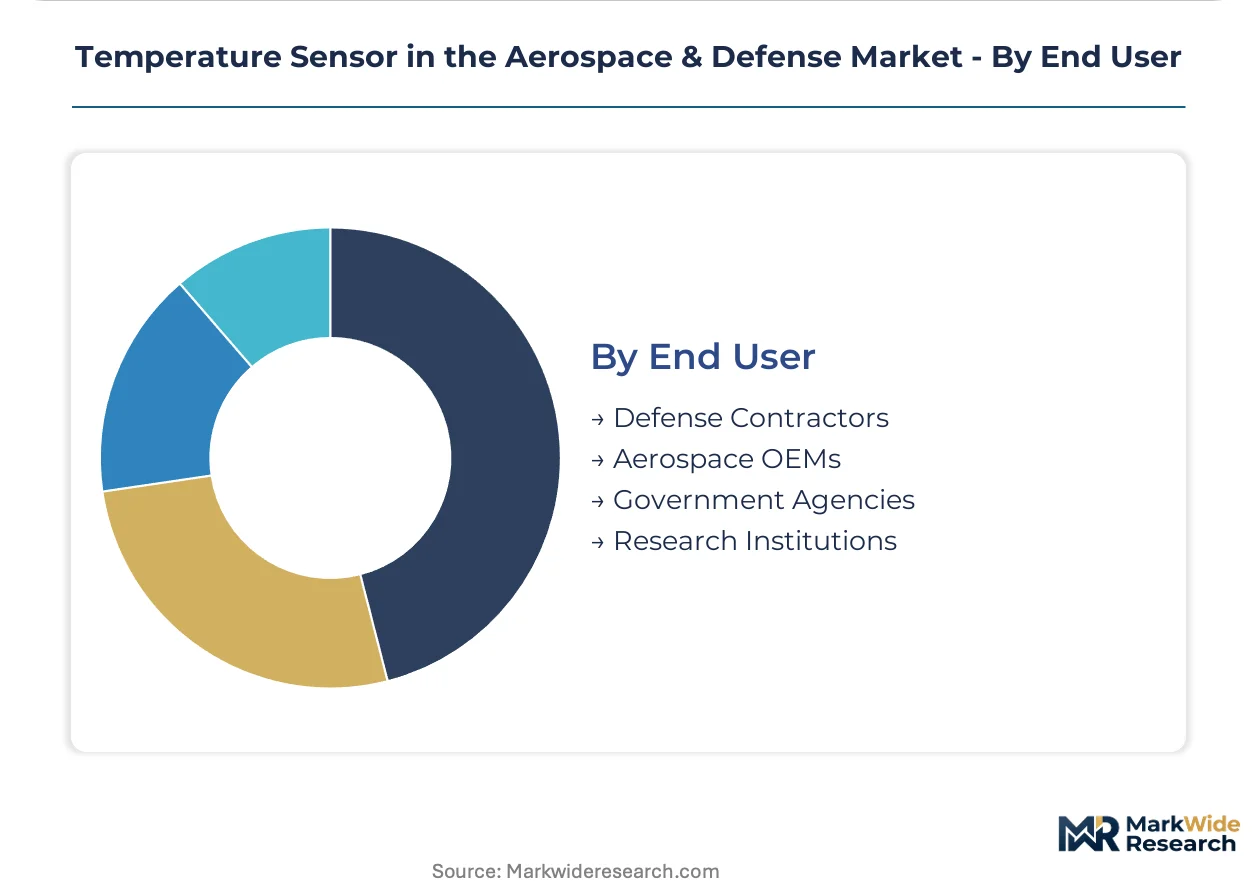
End User:
Procurement authority concentration determines supplier negotiation leverage: defense contractors and aerospace OEMs control specification writing, while government agencies and research institutions influence standards and early-stage technology validation.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and Raytheon integrate temperature sensors into platform bids where sensor costs are buried in system pricing. United States defense industrial base concentration in Maryland, Virginia, and Texas creates geographic supplier clustering.
- Aerospace OEMs:Boeing, Airbus, and Bombardier specify sensors through multi-year sole-source agreements that require dual FAA-EASA qualification. These customers represent the faster-growing demand pool as commercial-military platform convergence accelerates.
- Government Agencies:DARPA, NASA, and national space agencies fund early-stage fiber-optic and wireless sensor development through Small Business Innovation Research contracts.
- Research Institutions:MIT Lincoln Laboratory, German Aerospace Center, and French ONERA validate sensor performance in extreme environment simulation facilities that tier-two vendors cannot access independently.
Defense contractors hold the largest procurement budgets; aerospace OEMs are climbing the fastest as platform production rates recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification requirements anchor the United States as the dominant geography for flight-critical temperature sensor qualification. Defense procurement concentration and commercial aviation recovery are pulling investment toward specific national industrial bases.
United States
Hypersonic platform development and directed-energy weapons programs drive electromagnetic-immune sensor demand. ITAR export controls fragment supply chains between domestic primes and foreign component sources. Maryland and Virginia host concentrated defense contractor clusters where Lockheed Martin and Northrop Grumman specify distributed thermal monitoring networks.
Germany
MTU Aero Engines and turbine OEMs in Munich pre-qualify RTD suppliers through multi-year development contracts. EASA CS-25 certification standards tighten material traceability requirements that favor established primes. Stuttgart and Hamburg anchor European aerospace sensor engineering talent pools.
France
Safran Aircraft Engines and Airbus Toulouse operations specify temperature sensors through exclusive supplier agreements. EU AI Act emerging frameworks touch autonomous system sensor fusion architectures. The Île-de-France and Occitanie regions concentrate avionics and propulsion system integration expertise.
United Kingdom
BAE Systems and Rolls-Royce procurement drives hardened sensing system demand for next-generation combat aircraft. UK Defense and Security Industrial Strategy prioritizes domestic sensor qualification capabilities. The Midlands and Southwest England host mineral-insulated cable assembly specialists.
Israel
Electronic warfare and drone platform exports create specification pull for compact, radiation-hardened temperature sensors. Israeli Ministry of Defense procurement bypasses ITAR through bilateral agreements. Tel Aviv and Haifa clusters specialize in fiber-optic sensing for electromagnetic-pulse survivability.
Temperature Sensor in the Aerospace & Defense Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the temperature sensor ecosystem. The market structures around three tiers: primes with captive foundry networks, tier-two specialists in mineral-insulated assemblies, and component suppliers feeding broader instrumentation portfolios. Two strategic archetypes dominate: electromagnetic-immune photonic specialists and legacy thermocouple volume producers. Competitive moves concentrate on backward integration into thin-film deposition and strategic partnerships for calibration infrastructure access.
Among United States-based primes, Honeywell International Inc. and TE Connectivity Ltd. occupy positions where captive manufacturing networks shield production from external labor shortages. Meggitt PLC exemplifies the specialist archetype focused on extreme thermal cycling survivability. These three companies anchor competitive positioning across the transduction physics spectrum from legacy thermocouple architectures to fiber-optic displacement.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| TE Connectivity Ltd. |
| Meggitt PLC |
| Sensata Technologies Inc. |
| Conax Technologies |
| Raytheon Technologies Corporation |
| Safran SA |
| Ametek Inc. |
| Curtiss-Wright Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive foundry utilization rates at Honeywell and TE Connectivity create scale barriers that tier-two vendors cannot replicate, compressing price floors for thermocouple and RTD architectures while elevating premiums for fiber-optic and wireless systems where electromagnetic immunity justifies expenditure. This concentration of thin-film deposition capacity in the United States and Germany directly shapes procurement negotiation leverage across NATO defense primes and commercial aerospace OEMs.
Pricing Analysis
Unit price spreads between United States and German suppliers exceed 15-20% for flight-critical RTD assemblies due to EASA CS-25 documentation burdens and captive calibration infrastructure. Pricing stratifies across MIL-SPEC certified, FAA-EASA dual-qualified, and commercial-grade tiers, with platinum group metal volatility compressing margins unpredictably. Cost pressure intensifies in legacy thermocouple segments where mineral-insulated cable commoditization attracts Asian component suppliers. Defense contractors exhibit lowest price sensitivity due to buried sensor costs in system bids, while tier-two commercial retrofitters face acute margin compression.
Supply Chain Analysis
Extended lead times for rhodium and platinum feedstocks stretch sensor production schedules to 26-32 weeks, forcing primes to hold strategic inventory buffers against aerospace OEM just-in-time demands. Supply concentrates in the United States, Germany, and Japan due to ITAR restrictions, EASA qualification infrastructure, and platinum group metal refining capacity. Production draws from rhodium wire, alumina ceramic substrates, and mineral-insulated cable sheathing. Single-source vulnerability concentrates in qualified metrology labs certifying cryogenic-to-1700°C ranges. Distribution runs through prime contractor specification authority rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality and commercial aviation production rate recovery are converging to lift sensor demand through the mid-2030s, with NATO modernization budgets and FAA fleet replacement directives providing synchronized uplift.
For Market Incumbents: Compound captive foundry advantages by internalizing fiber-optic photonic packaging capabilities that tier-two vendors cannot access, while securing multi-year calibration service contracts to offset hardware margin erosion from platinum price volatility. Backward integration into thin-film platinum deposition shields RTD production from external supply shocks. For New Entrants and Emerging Players: Lead with wireless sensor network architectures for Space Force rapid reconfiguration programs, where RF telemetry demand outpaces established vendor capacity. Target drone battery management applications where commercial-military convergence relaxes qualification barriers. Pursue EU AI Act sensor fusion specifications as a specification wedge against legacy analog suppliers. For Investors and Strategic Acquirers: Mineral-insulated cable assembly specialists with turbine test facility access represent acquisition targets with defendable engineering moats. Long-term viability hinges on electromagnetic immunity technology transitions rather than legacy thermocouple volume. Watch directed-energy weapons program funding trajectories as the inflection signal for fiber-optic displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Expansion | Internalizing thin-film deposition shields Honeywell and TE Connectivity from platinum supply volatility. |
| Dual-Use Certification Investment | Simultaneous FAA-EASA qualification unlocks volume efficiencies unavailable to segregated product lines. |
| Fiber-Optic R&D Partnership | Photonic transduction alliances with DARPA programs accelerate hypersonic airframe integration timelines. |
| Calibration Infrastructure Acquisition | Capturing qualified metrology labs addresses the chokepoint certifying cryogenic-to-1700°C sensor ranges. |
| Wireless Sensor Network Development | RF telemetry architectures eliminate harness weight for Space Force rapid reconfiguration mission profiles. |
Research Methodology
Desk research of FAA airworthiness directive filings, EASA certification databases, and NATO procurement disclosures preceded structured interviews with sensor engineering directors at defense primes, calibration lab technical leads, and procurement officers at turbine engine OEMs. Primary fieldwork with platform integrators in Maryland, Virginia, and Stuttgart validated secondary trade data on platinum group metal flows and foundry capacity utilization. Bottom-up unit demand modeling triangulated against top-down defense budget appropriation analysis.
Variance decomposition across transduction physics, signal processing architecture, and platform integration requirements shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include thermocouple versus RTD versus fiber-optic product categories, analog versus digital versus wireless technology tiers, and aerospace instrument versus military vehicle versus satellite application clusters. CAGRs derived from production rate forecasts at Boeing, Airbus, and Lockheed Martin platform programs, cross-referenced with NATO member state modernization budget trajectories and FAA fleet replacement schedules.
Forecasts assume regulatory continuity in FAA Part 25, EASA CS-25, and ITAR export control regimes; material policy shifts would require re-modeling. Outputs reflect assumptions regarding platinum group metal price stability and qualified engineering talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Aerospace Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Customized Avionic Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Global Avionics Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Global Helicopter Avionics Market
Avionics
Aircraft EMI Shielding Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Display for Avionics Application Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Military Aircraft Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Aircraft Computers Market
Avionics
Global Commercial Avionics Systems Market