
 Global Helicopter Avionics Market | 2026-2036
Global Helicopter Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Helicopter Avionics Market Foresight
The EU Green Deal's aviation decarbonization benchmarks are repositioning supplier priorities toward lightweight, power-efficient avionics architectures. Honeywell International Inc. leverages its integrated flight deck portfolio to sustain aftermarket revenue across legacy military rotorcraft platforms. Thales dominates European sovereign helicopter programs through national industrial partnerships. Garmin Ltd. competes aggressively in the civil retrofit segment with certified glass cockpit solutions for aging light-twin fleets.
Helicopter avionics encompass the electronic systems governing flight management, navigation, communication, and situational awareness in rotary-wing aircraft, typically operating across MIL-STD-1553 and ARINC 429 data bus architectures with redundant processing channels for mission-critical functions. These systems enable all-weather operations, terrain avoidance, and precision approach capability in degraded visual environments. The flight control systems category anchors OEM new-build contracts through fly-by-wire integration on next-generation combat helicopters. Synthetic vision technology leads growth in the emergency medical services application segment where single-pilot IFR operations demand enhanced spatial awareness. Glass cockpit configurations occupy the mature commercial transport end user base with replacement cycles tied to airframe overhaul intervals.
The FAA mandates TCAS II and ADS-B Out equipage under 14 CFR 91.225, while EASA's CS-29 certification standards govern large rotorcraft avionics reliability. Military procurement channels require NIST cybersecurity framework compliance for connected mission systems. India's DGCA adoption of ICAO Global Aeronautical Distress and Safety System standards is opening retrofit demand for satellite-linked flight tracking. Stakeholders must weigh sovereign content requirements against modular open systems architecture investments when structuring long-term supplier agreements.
Market Dynamics
The FAA's NextGen ADS-B Out mandate compresses retrofit timelines for legacy rotorcraft, forcing operators to accelerate avionics replacement cycles while military procurement channels concentrate demand in NATO-aligned defense modernization programs.
Growth Catalysts
- Emergency Medical Services IFR Expansion:Single-pilot instrument flight rules operations in degraded visual environments drive synthetic vision system upgrades across air ambulance fleets.
- EU Green Deal Aviation Benchmarks:Decarbonization targets reposition supplier R&D toward lightweight, power-efficient avionics architectures for reduced fuel consumption.
- India's GADSS Adoption:DGCA implementation of ICAO Global Aeronautical Distress and Safety System standards opens satellite-linked flight tracking retrofit demand.
Market Restraints
- Semiconductor Supply Concentration:Critical chip fabrication for MIL-STD-1553 processors concentrates in East Asian foundries, exposing defense contractors to geopolitical supply disruption.
- Certification Cost Escalation:EASA CS-29 reliability validation for large rotorcraft avionics imposes multi-year testing burdens that freeze out mid-tier system integrators.
- Skilled Technician Scarcity:ARINC 429 and 1553 bus architecture expertise concentrates in aging workforce cohorts with limited pipeline replenishment.
Strategic Opportunities
- Unmanned Rotorcraft Convergence:Optionally piloted vehicle programs create demand for human-machine interface avionics bridging manned and unmanned control architectures.
- Brazilian Offshore Oil & Gas:ANVISA-equivalent offshore helicopter safety mandates in Latin America's pre-salt basin drive glass cockpit retrofits for aging S-92 and AW139 fleets.
- Modular Open Systems Architecture:US DoD acquisition reform enables non-traditional suppliers to displace proprietary legacy flight control systems through standardized interfaces.
Industry Challenges
- Fly-by-Wire Integration Complexity:Next-generation combat helicopter programs demand real-time software certification for flight-critical control laws that exceed current validation tool capabilities.
- Cybersecurity Compliance Burden:NIST framework mandates for connected military mission systems require continuous vulnerability patching across fielded platforms with limited bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Helicopter Avionics Market |
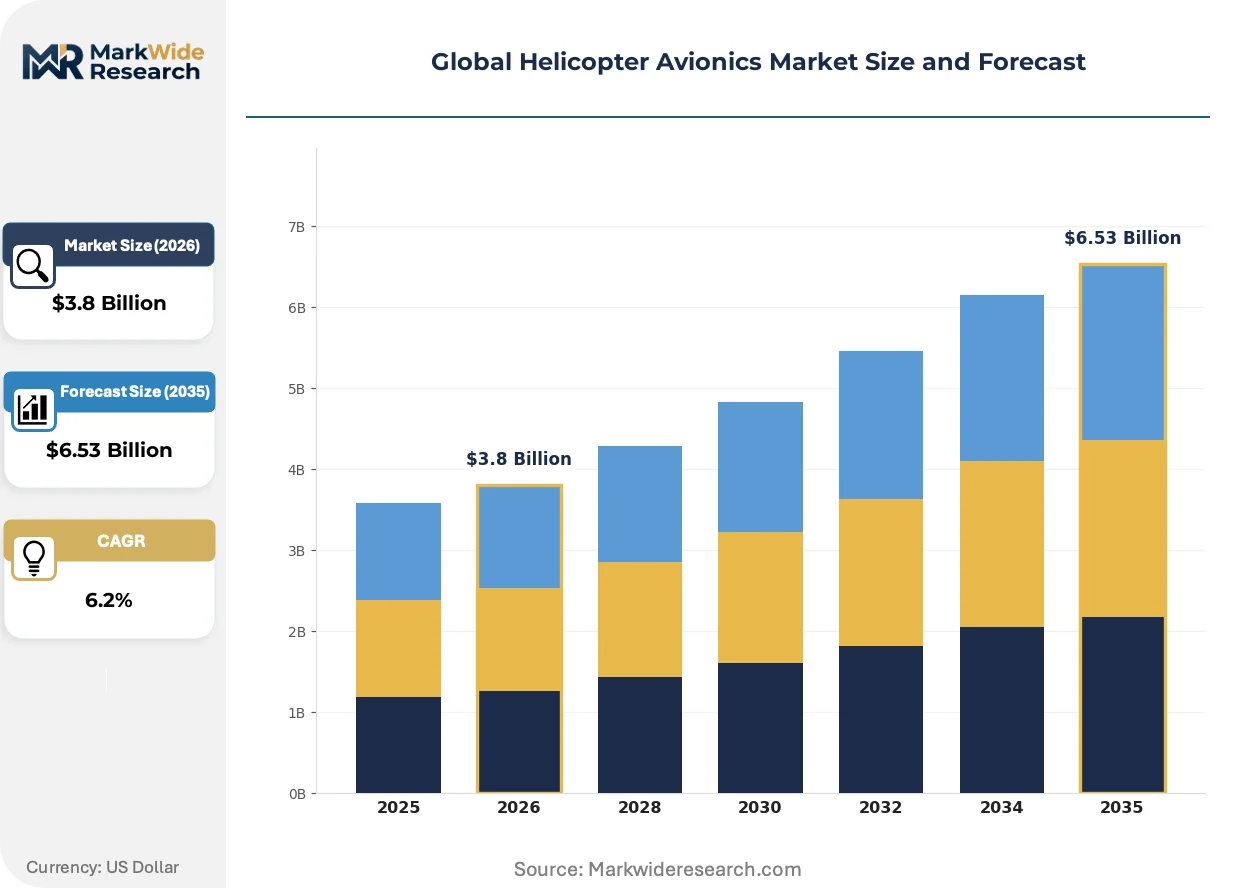
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Systems, Communication Systems, Navigation Systems, Weather Radar, Collision Avoidance Systems, Autopilot Systems Technology: Digital Cockpit, Glass Cockpit, Fly-By-Wire, Synthetic Vision, Enhanced Vision Systems, Magnetic Heading Reference Application: Commercial Transport, Emergency Medical Services, Search and Rescue, Law Enforcement, Offshore Transport, Agricultural Aviation End User: Military Operators, Private Owners, Corporate Aviation, Government Agencies, Flight Training Organizations, Charter Services |
| Companies Covered | Honeywell International Inc., RTX, L3Harris Technologies Inc., Thales, Rockwell Collins, Garmin Ltd., Leonardo S.p.A., General Electric, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Helicopter Avionics Market Shifts & Advancements
Avionics architectures are fragmenting between legacy analog retrofit paths and digital-native integrated flight decks, with regulatory mandates acting as the forcing function for technology transition timelines.
Synthetic vision systems are converging with terrain awareness warning databases to create unified spatial awareness displays. Emergency medical services operators in mountainous regions adopt these fused systems fastest. The technology is converging with head-up display formats to reduce single-pilot workload during night vision goggle operations.
EU AI Act risk classification rules now capture autonomous decision-support algorithms in helicopter flight management systems. Developers must document training data provenance and algorithmic transparency for safety-critical functions. Large commercial transport operators face the steepest compliance costs as they retrofit predictive maintenance analytics.
Defense procurement offices now unbundle long-term avionics support from initial platform acquisition, creating standalone performance-based logistics contracts. Original equipment manufacturers resist this shift while specialized third-party maintenance providers expand market access. The United Kingdom's Ministry of Defence helicopter fleet exhibits this pattern most clearly through its rotary-wing support public-private partnership structures.
Global Helicopter Avionics Market Segmentation
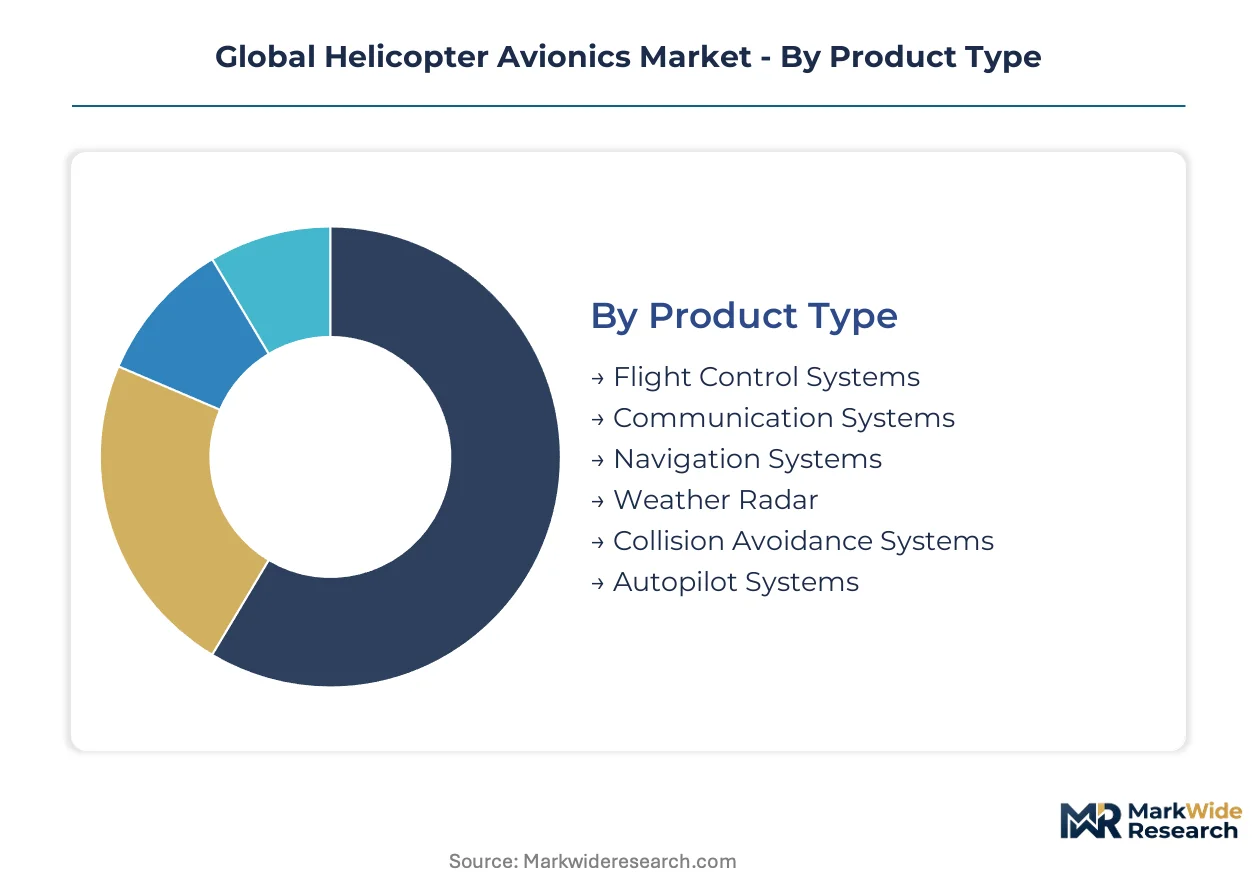
Helicopter avionics procurement patterns diverge sharply across mission profiles, with military operators prioritizing MIL-STD-1553 interoperability while commercial fleets chase FAA NextGen compliance deadlines. Segmentation reveals how technology adoption cascades from sovereign defense programs through corporate aviation retrofit cycles.
Product Type:
Military procurement channels favor integrated flight control suites with redundant processing architectures, while civil operators unbundle systems to manage certification costs.
- Flight Control Systems:These architectures govern rotorcraft stability through fly-by-wire actuation and mechanical backup channels. NATO-aligned defense modernization programs in the United States, United Kingdom, and Germany anchor OEM new-build contracts for these mission-critical platforms.
- Communication Systems:Military variants integrate encrypted SATCOM and tactical data links alongside civil VHF/HF transceivers. Demand concentrates in United States Army and Marine Corps fleet upgrades where network-centric warfare requirements mandate interoperable waveforms.
- Navigation Systems:GPS/INS hybrid units with RNP-0.3 capability for offshore oil platform approaches.
- Weather Radar:X-band and Ku-band units with turbulence detection algorithms for all-weather EMS dispatch.
- Collision Avoidance Systems:TCAS II and ACAS Xa implementations driven by FAA 14 CFR 91.225 mandates.
- Autopilot Systems:Three-axis stability augmentation for single-pilot IFR operations in degraded visual environments.
Volume sits with Flight Control Systems; growth tilts toward Collision Avoidance Systems.
Technology:
Architecture choices reflect airframe age more than operator size, with legacy analog fleets facing compressed retrofit timelines against digital-native platforms.
- Digital Cockpit:Integrated display processing consolidates formerly federated instruments into modular computing lanes with ARINC 664 backbone connectivity. United States-based emergency medical services operators in Colorado and Utah mountain corridors adopt these configurations fastest for single-pilot safety margins.
- Glass Cockpit:Multi-function displays replacing electromechanical flight instruments dominate civil retrofit economics. Aging light-twin fleets in Brazil's São Paulo state and Australia's Queensland offshore sector drive replacement cycles tied to airframe overhaul intervals.
- Fly-By-Wire:Digital flight control with no mechanical reversion path, requiring real-time software certification.
- Synthetic Vision:Terrain database rendering for brownout and whiteout recovery maneuvers.
- Enhanced Vision Systems:Infrared and millimeter-wave sensors for night vision goggle compatibility.
- Magnetic Heading Reference:Solid-state flux gate units replacing mechanical gyrocompasses in legacy airframes.
Glass Cockpit configurations command the installed base; Synthetic Vision expands most quickly in terrain-challenged applications.
Application:
Mission-criticality determines avionics redundancy levels, with search and rescue programs demanding MIL-STD-1553 fault tolerance absent in agricultural spraying configurations.
- Emergency Medical Services:Single-pilot IFR operations in degraded visual environments require fused synthetic vision and terrain awareness databases. Operators in the Swiss Alps and Italian Dolomites lead adoption of unified spatial awareness displays for night hoist operations.
- Offshore Transport:Rig approach automation and satellite-based augmentation system precision for North Sea and Gulf of Mexico oil platform servicing.
- Commercial Transport:Glass cockpit standardization across airline-affiliated helicopter services.
- Search and Rescue:Mission management computers with interoperable NATO STANAG data links.
- Law Enforcement:Downlink-equipped electro-optical turret integration and encrypted communications.
- Agricultural Aviation:GPS-guided spray pattern automation with flow rate telemetry.
Commercial Transport holds the revenue base; Emergency Medical Services gains share fastest through IFR route expansion.
End User:
Procurement authority structures separate sovereign defense acquisition from owner-operator decision-making, with radically different vendor relationship dynamics.
- Military Operators:Connected mission systems requiring NIST cybersecurity framework compliance and modular open systems architecture interoperability. United States Department of Defense unbundling of long-term support contracts from platform acquisition reshapes supplier economics across NATO-aligned fleets.
- Corporate Aviation:Fractional ownership and managed fleet operators standardize on manufacturer-agnostic avionics suites.
- Private Owners:Cost-driven ADS-B Out mandate compliance with minimal capability expansion.
- Government Agencies:Non-military public safety and border patrol programs with civilian certification paths.
- Flight Training Organizations:Glass cockpit familiarization platforms for rotary-wing pilot pipeline development.
- Charter Services:Passenger experience differentiation through cabin management system integration.
Military Operators dominate absolute spending; Corporate Aviation shows the steepest expansion trajectory through fleet professionalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for helicopter avionics clusters in defense-industrial corridors, while consumption spreads across NATO-aligned military operators and civil retrofit markets. The United States absorbs the largest share of military procurement, with European sovereign programs and Asian-Pacific fleet modernization expanding the demand base.
United States
Department of Defense unbundling of long-term support contracts from platform acquisition reshapes supplier economics across Army and Marine Corps rotorcraft fleets. FAA mandates for ADS-B Out equipage under 14 CFR 91.225 compress retrofit timelines for legacy civil helicopters. The Dallas-Fort Worth aerospace corridor concentrates avionics integration facilities serving both military and commercial channels.
Germany
Sovereign helicopter programs through the Bundeswehr anchor European demand for MIL-STD-1553 interoperable flight control systems. EU Green Deal aviation decarbonization benchmarks redirect supplier R&D toward power-efficient architectures. The Bavarian aerospace cluster around Munich hosts system integrators serving NATO standardization requirements.
United Kingdom
Ministry of Defence rotary-wing support public-private partnerships unbundle avionics maintenance from initial platform acquisition. EASA CS-29 certification standards for large rotorcraft impose multi-year reliability validation burdens. The South West England aerospace corridor around Bristol concentrates flight control system engineering for military applications.
India
DGCA adoption of ICAO Global Aeronautical Distress and Safety System standards opens satellite-linked flight tracking retrofit demand across commercial and government fleets. Defense procurement channels require increasing indigenous content under offset agreements. The Bangalore-Hyderabad corridor hosts emerging system integrators serving both civil and military operators.
Brazil
ANVISA-equivalent offshore helicopter safety mandates in the pre-salt basin drive glass cockpit retrofits for aging S-92 and AW139 fleets serving oil platform logistics. Agricultural aviation GPS-guided spray automation expands the light-rotorcraft avionics base. São Paulo state's aviation maintenance cluster concentrates retrofit capability for Latin American operators.
Global Helicopter Avionics Market Competitive Landscape
The competitive structure tilts toward integrated system providers with established defense procurement relationships. Tiered specialization separates full-flight-deck integrators from component suppliers focused on narrow certification domains. Two strategic archetypes dominate: diversified aerospace conglomerates leveraging platform-level contracts, and avionics specialists capturing civil retrofit economics. Consolidation through defense program joint ventures and technology licensing agreements reshapes vendor positioning.
Within the diversified systems tier, Honeywell International Inc. and Thales exemplify contrasting geographic anchoring strategies. Honeywell sustains aftermarket revenue across legacy military rotorcraft platforms through integrated flight deck portfolios. Thales dominates European sovereign programs through national industrial partnership structures. Garmin Ltd. occupies a distinct position as a civil-specialist challenger, competing aggressively in certified glass cockpit solutions for aging light-twin fleet retrofits.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX |
| L3Harris Technologies Inc. |
| Thales |
| Rockwell Collins |
| Garmin Ltd. |
| Leonardo S.p.A. |
| General Electric |
| Elbit Systems Ltd. |
| Others |
Supply & Pricing Matrix
Captive semiconductor fabrication for MIL-STD-1553 processors anchors both supply security and pricing power for tier-one avionics integrators, while outsourced ARINC 429 board production exposes mid-tier suppliers to margin compression. Defense procurement channels reward backward integration with multi-year performance-based logistics contracts that lock in aftermarket revenue streams.
Pricing Analysis
Margin tightening in civil retrofit tiers traces to compressed FAA ADS-B Out mandate timelines that eliminate operator negotiation leverage. Three-tier pricing structure across integrated flight decks, modular subsystems, and component-level spares differentiates by certification grade and after-sales bundling. Cost-down pressure on legacy analog replacements accelerates because semiconductor foundry allocation favors military-grade wafer starts. Private owner segments exhibit highest price sensitivity; military operators accept premium positioning for NIST cybersecurity compliance.
Supply Chain Analysis
Freight cost volatility for mil-spec component shipments between East Asian foundries and NATO assembly facilities has prompted inventory pre-positioning at regional military depots. Critical chip fabrication concentrates in Taiwan, South Korea, and Japan; rare earth magnet supply for avionics actuators draws from China and Myanmar. Single-source vulnerability for radiation-hardened processors creates procurement risk. Distribution runs through OEM-direct military channels and specialized avionics distributors serving civil retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital-native integrated flight decks are displacing federated analog architectures across both military and civil helicopter fleets, with synthetic vision technology replacing electromechanical attitude indicators as the primary cockpit upgrade pathway.
For Market Incumbents: Deploy modular open systems architecture roadmaps to counter proprietary legacy flight control displacement by non-traditional suppliers. Deepen certification investment in EU AI Act algorithmic transparency documentation for predictive maintenance analytics. Fortify aftermarket revenue through performance-based logistics contract structures that unbundle long-term support from platform acquisition. For New Entrants and Emerging Players: Synthetic vision system certification for single-pilot IFR emergency medical services operations offers the most penetrable white-space target. Geographic entry through India's DGCA-mandated GADSS retrofit wave captures satellite-linked flight tracking demand before indigenous integrators scale. Pursue channel partnerships with São Paulo state maintenance clusters for Brazilian offshore glass cockpit retrofits. For Investors and Strategic Acquirers: Exit pathways concentrate in defense program joint ventures and technology licensing agreements to tier-one platform OEMs. Long-term viability favors specialists with NIST cybersecurity framework compliance credentials and modular open systems architecture IP. Watch for FAA mandate deadline extensions as inflection indicator for civil retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Open Systems Architecture Adoption | Enables non-traditional suppliers to displace proprietary Honeywell and Thales legacy flight control systems through standardized military interfaces. |
| Synthetic Vision System Certification | Captures emergency medical services single-pilot IFR demand in Swiss Alps and Italian Dolomites terrain-challenged corridors. |
| Performance-Based Logistics Contracting | Reshapes supplier economics across United Kingdom Ministry of Defence rotary-wing public-private partnership structures. |
| GADSS-Compliant Flight Tracking Retrofit | Opens satellite-linked avionics demand across India's DGCA-mandated commercial and government helicopter fleets. |
| EU AI Act Algorithmic Documentation | Imposes compliance cost barriers that freeze out mid-tier integrators from predictive maintenance analytics in large commercial transport. |
Research Methodology
Document review covered FAA ADS-B Out mandate filings, EASA CS-29 certification standards, and United States Department of Defense procurement databases, complemented by interviews with avionics integration engineers, military program acquisition officers, emergency medical services fleet managers, and aftermarket maintenance directors. Secondary validation drew from MIL-STD-1553 specification updates, ARINC 429 protocol revisions, and NATO STANAG interoperability guidelines. Bottom-up platform-level demand estimates triangulated against top-down defense budget allocation analysis.
Cross-referencing historical retrofit cycle patterns with expert panel input on mandate compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology maturity tier, mission application profile, and end-user procurement authority structure. CAGRs derived from installed base age distribution analysis and regulatory deadline clustering. Industry-specific inputs incorporated semiconductor foundry capacity allocation trends and sovereign content requirement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical semiconductor supply disruption or extended FAA mandate waiver scenarios. Forecasts reflect documented assumptions regarding defense modernization program pacing and civil retrofit operator liquidity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Aircraft Computers Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Military Aircraft Avionics Market
Avionics
Aircraft EMI Shielding Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Global Avionics Market
Avionics
Display for Avionics Application Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Aerospace Avionics Market