
 Global Avionics Market | 2026-2036
Global Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Avionics Market Analysis
Avionics engineering talent is rotating toward software-defined systems and AI-enabled flight controls, tightening the labor pool for legacy hardware specialists. Honeywell International Inc. leverages its integrated flight management portfolio to dominate the commercial retrofit segment. Thales Group sustains European defense contracts through sovereign avionics platforms. Safran SA anchors narrowbody OEM supply chains with cockpit system integration.
Avionics encompasses the electronic systems used for communication, navigation, flight management, and surveillance aboard aircraft, typically operating across ARINC 429 and MIL-STD-1553 data buses with hardened components rated for temperatures from -55°C to 125°C. These systems enable safe aircraft operation, airspace integration, and mission execution under instrument flight rules. Navigation Systems and Communication Systems command the largest installed bases, though Surveillance Systems generates outsized margins from ADS-B mandates and TCAS upgrades. Digital Avionics is displacing analog architectures fastest in the retrofit channel, while Integrated Avionics captures premium pricing from fifth-generation fighter programs and advanced business jet platforms.
The FAA mandates equipage timelines that compress retrofit demand cycles, while EASA's CS-25 certification standards shape product development costs for suppliers seeking European market access. China's CAAC and NMPA jointly steer domestic avionics substitution through COMAC supplier qualification requirements. Stakeholders must weigh certification jurisdiction against production location as sovereign content rules tighten across the United States, Europe, and China.
Market Dynamics
Software-defined architectures are compressing hardware refresh cycles across commercial and defense platforms, forcing suppliers to restructure engineering teams around AI-enabled flight controls while maintaining certification continuity for legacy analog systems.
Growth Catalysts
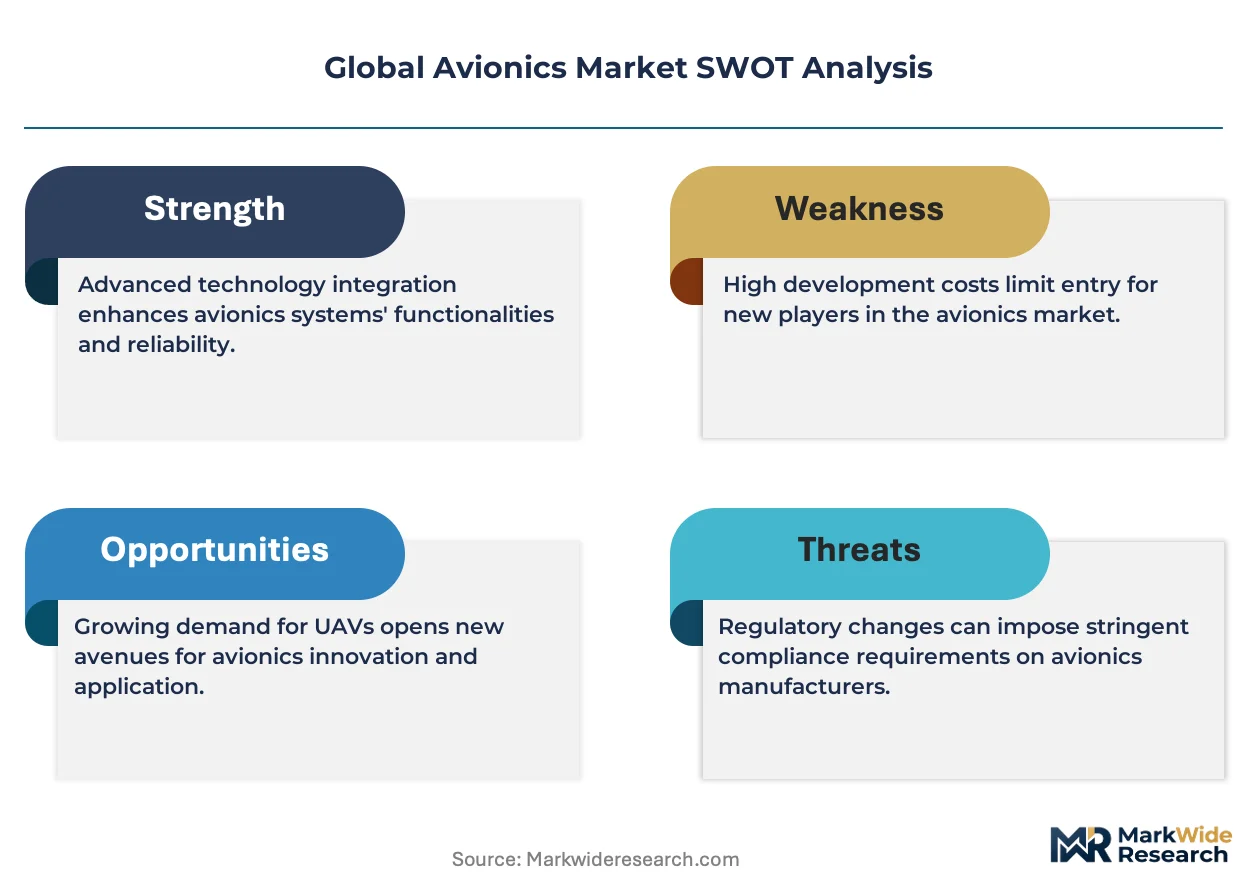
- FAA NextGen ADS-B Mandates:The FAA's Automatic Dependent Surveillance-Broadcast equipage requirements for controlled airspace access are forcing fleet-wide retrofits across Part 121 and Part 135 operators, concentrating demand in the narrowbody and regional jet installed base.
- China COMAC Supplier Qualification:The CAAC and NMPA joint domestic content requirements for C919 and ARJ21 programs are redirecting subsystem procurement toward indigenous avionics integrators, creating parallel certification pathways outside traditional FAA-EASA channels.
- Integrated Flight Deck Suites:Commercial airlines are consolidating previously discrete navigation, communication, and surveillance functions into unified glass cockpit architectures, reducing unit count per aircraft while raising system-level contract values.
Market Restraints
- Semiconductor Hardening Costs:Radiation-tolerant and high-reliability component sourcing for -55°C to 125°C operating ranges carries 3-5x cost premiums versus commercial-grade equivalents, compressing margins on volume production contracts.
- Dual Certification Burden:Suppliers seeking simultaneous FAA and EASA approval for ARINC 664 and MIL-STD-1553-based systems face divergent test protocols and documentation standards, extending program timelines without commensurate revenue recognition.
- Legacy Fleet Entrenchment:Analog avionics in aging cargo and military trainer aircraft demonstrate functional longevity beyond economic replacement thresholds, delaying retrofit demand compression in the 20-40 year installed base segment.
Strategic Opportunities
- Unmanned Traffic Management Integration:Urban air mobility platforms and cargo drones require purpose-built detect-and-avoid avionics absent from manned aircraft certification frameworks, opening greenfield system architecture competitions.
- India Defense Modernization:The country's PLI scheme for aerospace components and offset requirements under Rafale and C-295 programs are creating first-tier supplier opportunities for cockpit integration work previously concentrated in US and European houses.
- Predictive Maintenance Convergence:Edge computing on flight management computers combined with satellite datalink connectivity enables real-time health monitoring, shifting revenue models toward subscription-based fleet analytics services.
Industry Challenges
- DO-178C Software Verification Bottleneck:The FAA's Level A certification standard for safety-critical code requires exhaustive test coverage documentation, stretching qualified engineering capacity across competing commercial and military programs.
- ARINC 429 to AFDX Migration Complexity:Hybrid architectures bridging legacy 100 kbit/s databuses with modern switched Ethernet backbones introduce integration risk during retrofit installations, demanding specialized interoperability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Avionics Market |
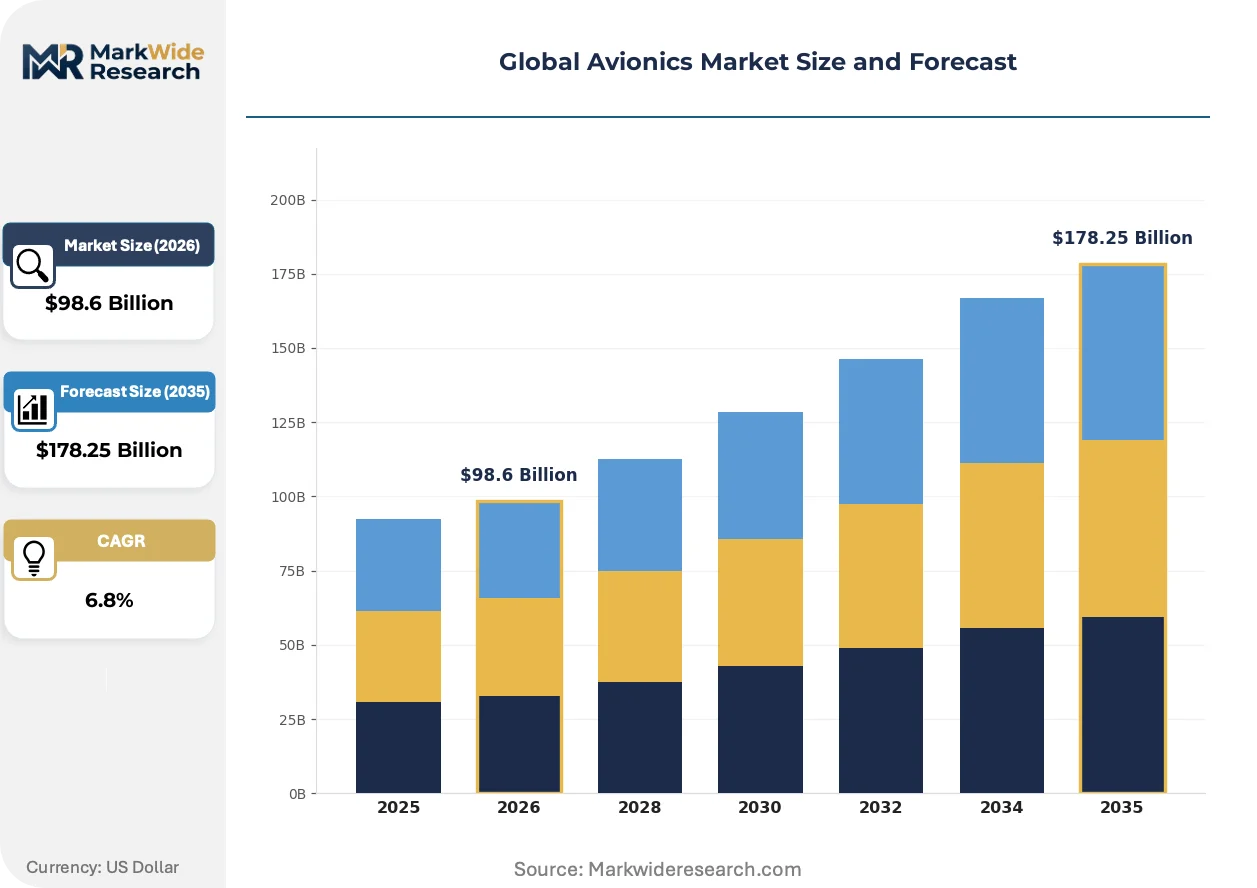
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management Systems, Navigation Systems, Communication Systems, Surveillance Systems End User: Civil Aviation, Military Aviation, OEMs, Aftermarket Providers Technology: Digital Avionics, Analog Avionics, Open Systems, Integrated Avionics Application: Commercial Aircraft, Military Aircraft, Drones, Business Jets |
| Companies Covered | Safran SA, L3Harris Technologies Inc., Honeywell International Inc., Leonardo S.p.A., BAE Systems plc, Raytheon Technologies Corporation, General Electric Company, Curtiss-Wright Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Avionics Market Emerging Trajectories
Open systems architectures are dismantling proprietary avionics stacks that locked operators into single-source maintenance contracts, enabling competitive subsystem sourcing and modular upgrade paths across fleet types.
Model-based systems engineering is supplanting document-centric design methodologies in cockpit development programs. Tier-one suppliers including Thales and Safran have adopted digital thread approaches linking requirements to verification artifacts. This compression of design iteration cycles is enabling first-flight milestones 18-24 months earlier than legacy paper-based processes permitted.
EASA's CS-25 Amendment 25-157 for cybersecurity certification imposes airworthiness requirements on connected avionics previously exempt from explicit hacking resilience standards. Suppliers must now demonstrate threat mitigation for flight-critical functions exposed to passenger Wi-Fi and satellite communications gateways. The business jet and helicopter segments are experiencing the steepest compliance cost escalation due to fragmented fleet sizes and limited cybersecurity engineering resources.
Airline technical procurement departments are consolidating avionics purchasing under power-by-the-hour arrangements that bundle hardware, installation, and maintenance into single contract vehicles. Lessors and flag carriers in the Middle East and Southeast Asia have pioneered this shift, transferring obsolescence risk from operator balance sheets to OEM service organizations. The model compresses upfront capital requirements while extending supplier revenue recognition timelines across 10-15 year contract horizons.
Global Avionics Market Segmentation
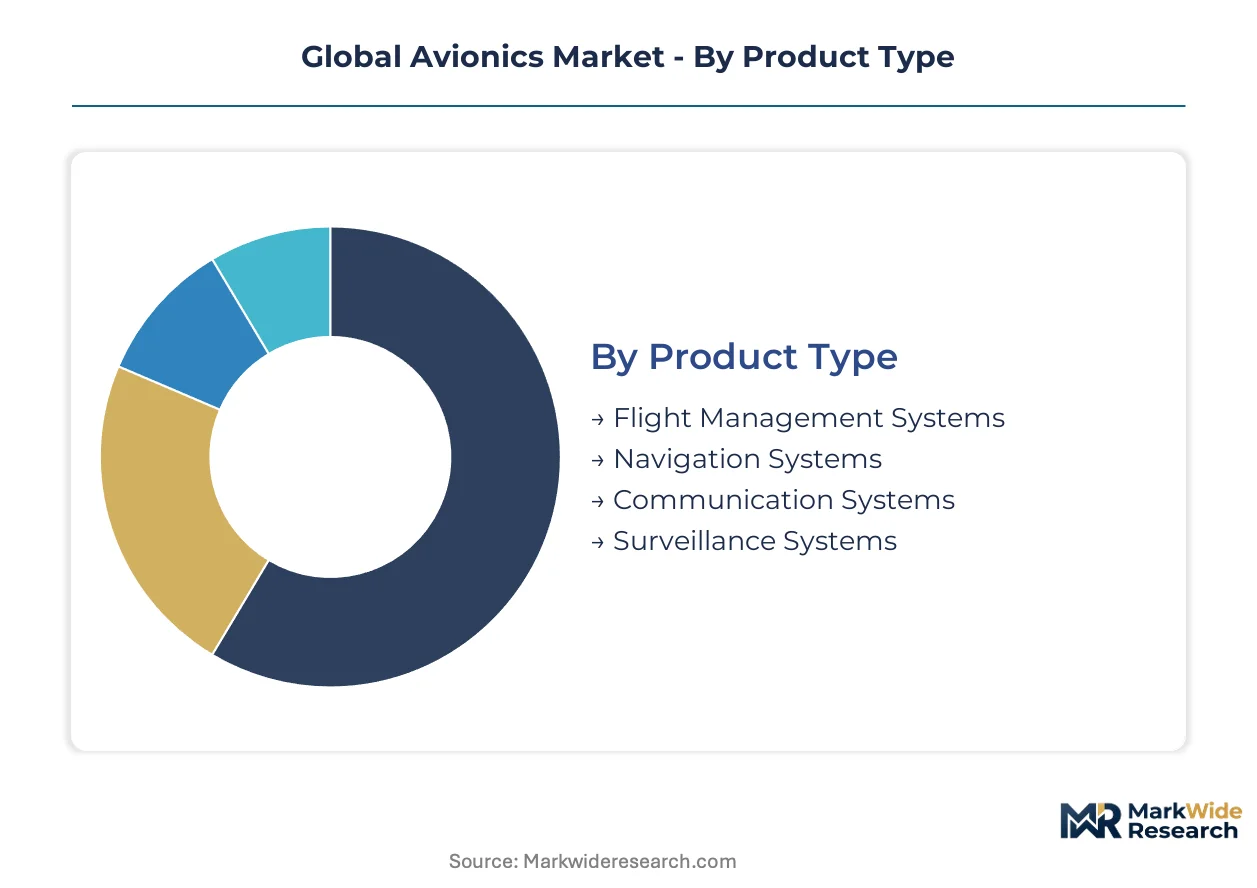
Avionics purchasing decisions split across airworthiness mandates, sovereign content requirements, and fleet modernization cycles. Suppliers must align certification pathways with each segment's procurement rhythm to capture contract flow.
Product Type:
Margin pools concentrate in surveillance retrofits driven by regulatory equipage deadlines and integrated suites commanding system-level pricing power.
- Navigation Systems:GPS-augmented inertial reference units and multi-mode receivers process satellite and ground-based signals for precision approach operations. Demand clusters in narrowbody fleet renewals across the United States and China as airlines replace aging VOR/ILS equipment to meet RNP-AR mandates.
- Surveillance Systems:ADS-B Out/In transponders and TCAS II processors enable airspace access under FAA NextGen and EASA CS-ACNS rules. Mandate-driven retrofit waves across Part 121 operators in the United States and European low-cost carriers sustain premium pricing despite semiconductor hardening costs.
- Flight Management Systems:Performance-based navigation computers with required navigation performance authorization.
- Communication Systems:VHF datalink and satellite communications transceivers for controller-pilot data link.
Navigation Systems holds installed capacity across legacy fleets. Surveillance Systems is rotating up the share rankings on regulatory compression.
End User:
Volume concentrates in civil aviation procurement, though military programs deliver longer contract horizons and sovereign technology transfer requirements.
- Civil Aviation:Commercial airlines and cargo operators purchasing line-fit and retrofit avionics under airworthiness directives. Fleet-wide mandates from FAA and EASA compress decision timelines for narrowbody and widebody operators in the United States, Germany, and China.
- Military Aviation:Defense ministries procuring mission computers, electronic warfare suites, and tactical datalinks through national security classified channels. India's Ministry of Defence offset requirements and France's DGA sovereignty clauses reshape supplier qualification.
- OEMs:Airframe manufacturers integrating supplier-furnished equipment at final assembly.
- Aftermarket Providers:Independent maintenance organizations performing depot-level repair and modification.
Civil Aviation commands current procurement volume. Military Aviation is expanding most quickly on Indo-Pacific rearmament cycles.
Technology:
Cost tier differentiation separates hardened digital architectures from analog legacy support and premium integrated platforms.
- Digital Avionics:Software-defined processors and solid-state sensors replacing electromechanical instruments. Commercial airlines in the United States and China accelerate displacement of analog gauges to reduce weight and maintenance burden.
- Integrated Avionics:Federated or modular architectures consolidating multiple functions on shared processing resources. Fifth-generation fighter programs and ultra-long-range business jets in the United States and France specify these platforms for crew workload reduction.
- Analog Avionics:Electromechanical flight instruments and discrete wire-based systems requiring continued sustainment.
- Open Systems:Standards-based architectures enabling competitive subsystem sourcing beyond proprietary stacks.
Digital Avionics captures the steepest expansion trajectory on fleet renewal. Integrated Avionics defends premium positioning in defense and business aviation.
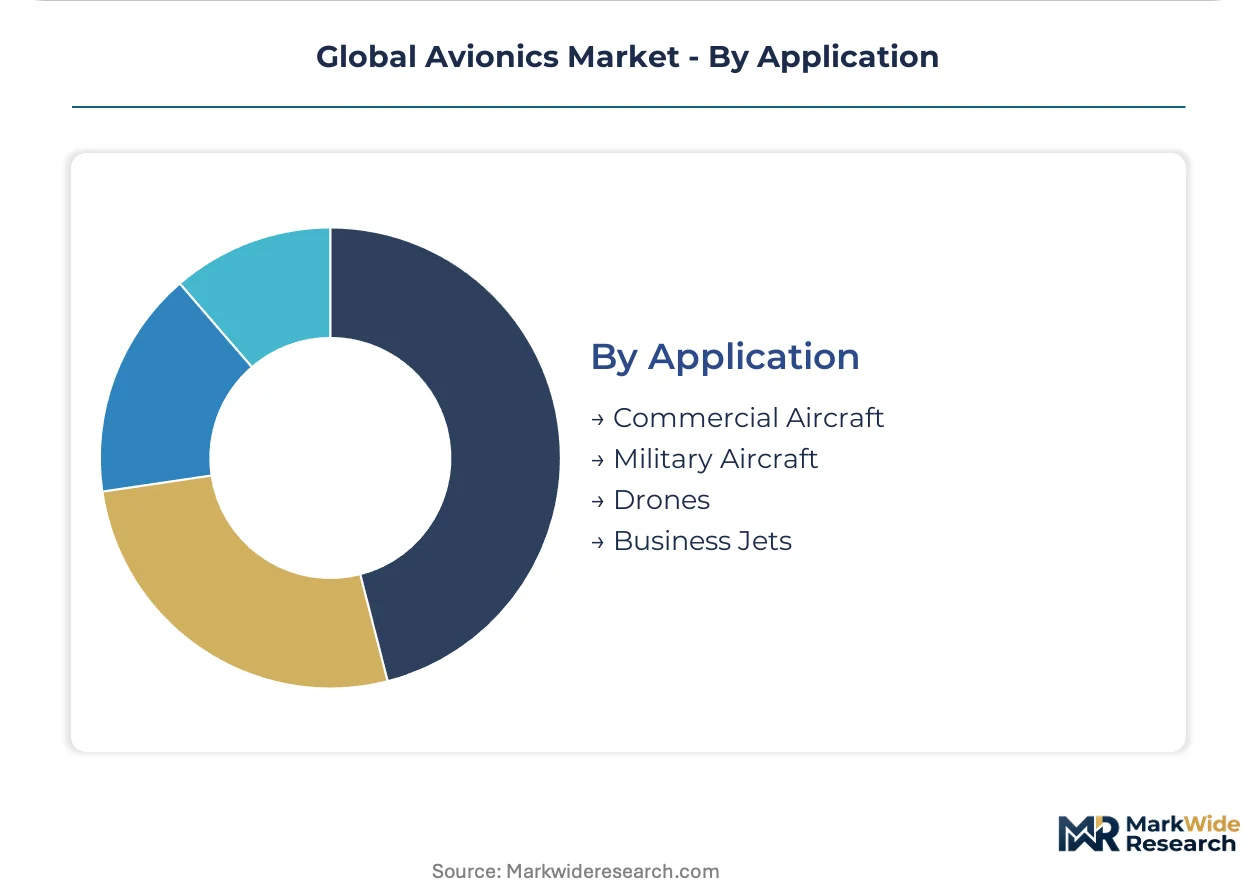
Application:
Customer type fragmentation spans scheduled service economics, mission readiness requirements, and emerging unmanned certification frameworks.
- Commercial Aircraft:Narrowbody and widebody platforms operated under Part 121 and EASA Part-CAT rules. Airlines in China and Indonesia drive volume through COMAC C919 and Airbus A320neo fleet inductions.
- Drones:Uncrewed aerial systems requiring detect-and-avoid avionics absent from manned certification baselines. Urban air mobility developers in the United States and Germany prototype purpose-built flight control computers.
- Military Aircraft:Tactical and strategic platforms with mission-specific electronic warfare and communications.
- Business Jets:Part 135 and corporate operators specifying integrated flight decks and cabin connectivity.
Commercial Aircraft anchors current revenue. Drones is climbing the fastest on regulatory framework development for beyond-visual-line-of-sight operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Avionics consumption patterns diverge sharply by airspace maturity. Mature markets prioritize retrofit mandates and cybersecurity compliance, while emerging aviation economies emphasize sovereign production capacity and import substitution.
United States
FAA NextGen equipage deadlines drive narrowbody retrofit intensity. The agency's ADS-B Out mandates compress decision timelines for Part 121 operators. Seattle-Tacoma and Wichita clusters concentrate integrated flight deck engineering for Boeing and business jet programs.
China
COMAC C919 production ramp and ARJ21 fleet expansion redirect procurement toward domestic integrators. CAAC and NMPA joint qualification requirements create parallel certification pathways outside FAA-EASA channels. Shanghai and Xi'an aerospace zones anchor indigenous cockpit system development.
Germany
EASA CS-25 Amendment 25-157 cybersecurity rules impose compliance costs on connected avionics. The country's national aerospace regulator shapes European airworthiness standards for flight-critical software. Munich and Hamburg house major cockpit integration engineering centers serving Airbus programs.
India
Ministry of Defence offset requirements under Rafale and C-295 acquisitions create tier-one supplier opportunities. The country's PLI scheme for aerospace components incentivizes local cockpit integration work. Bangalore and Hyderabad clusters develop flight management software for military and civil platforms.
France
DGA sovereignty clauses mandate domestic avionics content for defense programs. EASA certification standards shape product development costs for suppliers seeking European market access. Toulouse and Paris-Saclay anchor Thales and Safran engineering for integrated mission systems.
Global Avionics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in avionics supply. Tier-one integrators consolidate flight management, navigation, and surveillance functions into unified architectures. Specialist suppliers concentrate on radiation-hardened components, software verification services, and legacy analog sustainment. Competitive dynamics center on M&A for software capabilities and strategic partnerships for unmanned traffic management.
Within the integrated systems tier, Honeywell International Inc. and Thales Group exemplify full-flight-deck providers spanning commercial and defense channels. Safran SA occupies a position in narrowbody OEM supply chains. These three anchors represent divergent geographic bases—US, French, and French respectively—reflecting the market's transatlantic structure.
| Leading Market Players |
|---|
| Safran SA |
| L3Harris Technologies Inc. |
| Honeywell International Inc. |
| Leonardo S.p.A. |
| BAE Systems plc |
| Raytheon Technologies Corporation |
| General Electric Company |
| Curtiss-Wright Corporation |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
FAA DO-178C Level A certification requirements gate both supplier qualification and price differentiation simultaneously, forcing tier-one integrators to absorb software verification costs that commodity hardware vendors cannot shoulder while creating three distinct contract-value tiers based on airworthiness criticality.
Pricing Analysis
Long-term power-by-the-hour contracts dominate commercial airline procurement, bundling hardware, installation, and predictive maintenance into decade-spanning service agreements. Price differentiation separates FAA-EASA dual-certified platforms from single-jurisdiction equivalents and legacy analog sustainment packages. Cost compression in narrowbody retrofit channels is intensifying because semiconductor hardening premiums persist despite volume scale. Regional jet operators exhibit the highest price sensitivity; defense ministries and ultra-long-range business jet buyers demonstrate the least.
Supply Chain Analysis
Radiation-hardened semiconductor fabrication capacity in the United States, Japan, and South Korea anchors tier-one avionics production. ARINC 664 network switches and MIL-STD-1553 databus components draw from captive aerospace-grade foundries with limited commercial crossover. Single-source vulnerability concentrates in gallium nitride high-power amplifiers and space-qualified memory modules. Distribution runs through OEM line-fit channels, airline direct procurement, and authorized aftermarket depots with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined flight control architectures are disrupting traditional hardware refresh cycles, with FAA NextGen mandates and EASA cybersecurity amendments compressing supplier adaptation windows to 18-24 months.
For Market Incumbents: Fortify certification continuity investments across FAA-EASA dual pathways to defend against indigenous Chinese integrators capturing COMAC supply chain slots. Deepen backward integration into radiation-tolerant semiconductor sourcing to offset foundry margin compression. Prioritize AI-enabled flight control R&D to maintain engineering talent retention against software-defined competitors. For New Entrants and Emerging Players: Differentiate on unmanned traffic management avionics purpose-built for urban air mobility detect-and-avoid functions absent from manned certification baselines. Target India's defense offset procurement under Rafale and C-295 programs where sovereign content requirements have opened tier-one integration slots previously closed to foreign entrants. Pursue predictive maintenance SaaS partnerships with regional airlines seeking to transfer obsolescence risk from balance sheets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated flight deck suites as software verification and cybersecurity compliance costs displace hardware bill-of-materials dominance. Acquisition targets should exhibit captive DO-178C engineering capacity and established CAAC qualification pathways for COMAC supplier status. Watch for ADS-B mandate deadline extensions or compression as the signal indicating retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Migration | Enables AI flight controls while collapsing hardware refresh cycles across Boeing and Airbus platforms. |
| Dual Certification Investment | Secures FAA-EASA approval pathways essential for narrowbody OEM line-fit contracts. |
| Unmanned Traffic Management Partnership | Positions suppliers for urban air mobility greenfield architectures beyond manned certification baselines. |
| Predictive Maintenance Platform Launch | Shifts revenue models toward subscription analytics with airline power-by-the-hour adopters. |
| Indigenous Qualification Pathway | Opens COMAC C919 and ARJ21 supplier status under CAAC-NMPA joint requirements. |
Methodological Framework
Cross-validation between primary interviews with avionics engineering directors, airline technical procurement officers, and defense ministry acquisition leads and secondary validation through FAA certification databases, EASA CS-25 amendment filings, and COMAC supplier qualification records anchors the qualitative findings. Bottom-up triangulation against customs data for ARINC component trade flows and top-down reconciliation with airframe production schedules complete the data architecture.
Sensitivity analysis across the projection horizon tests demand assumptions against ADS-B mandate enforcement variability and COMAC production ramp scenarios. Segmentation dimensions modeled include product type, end user, technology tier, and application with regional regulatory cluster overlays. CAGRs derive from installed base replacement cycles, fleet expansion schedules, and airworthiness directive compliance deadlines. Forecast inputs incorporate semiconductor lead time volatility and sovereign content rule evolution.
Forecasts assume regulatory continuity in FAA NextGen, EASA CS-ACNS, and CAAC-NMPA joint qualification regimes; material policy shifts would require re-modeling. Specific risk factors include ADS-B deadline extensions, cybersecurity standard escalation, and indigenous substitution acceleration in China. Practitioners should keep alternative scenarios live as unmanned traffic management frameworks and urban air mobility certification pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Global Helicopter Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Aircraft EMI Shielding Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Military Aircraft Avionics Market
Avionics
Electronic Flight Instrument System Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Display for Avionics Application Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Military Avionic Systems Market
Avionics
Aerospace Avionics Market