
 Asia-Pacific Aircraft Avionics Market | 2026-2036
Asia-Pacific Aircraft Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Avionics Market Outlook
Market Context
South Korean avionics subsystem producers is broadening export capacity for regional jet programs. Honeywell International Inc. leverages its integrated flight deck architecture to anchor positions across multiple Asian airframe programs. Collins Aerospace sustains R&D intensity in next-generation connected cockpit solutions for the region's expanding airline fleets. Safran competes through specialized landing and navigation systems tailored to high-density Asian air traffic corridors.
Technical Definition and Segments
Asia-Pacific aircraft avionics encompasses the electronic systems governing flight control, navigation, communication, and mission management, typically operating across ARINC 429 and ARINC 664 databus architectures with DO-178C software assurance levels. These systems enable safe aircraft operation in complex Asia-Pacific airspace characterized by monsoon weather patterns, high terrain, and dense route structures. Flight control systems command the largest installed base as airlines prioritize fly-by-wire retrofits on aging narrowbodies, while software-defined technology represents the fastest-evolving dimension as operators seek modular upgrade paths without full hardware replacement. Communication systems retain stable margins from regulatory mandates for satellite-based voice and data link compliance across ICAO-approved oceanic routes.
Regulatory Framework
India's DGCA, Australia's CASA, and Japan's JCAB collectively enforce airworthiness standards that shape avionics certification timelines and retrofit obligations across the region. China's CAAC imposes indigenous certification requirements that influence supplier selection for domestically assembled COMAC airframes. Stakeholders must monitor divergent national airspace modernization schedules to align product roadmaps with country-specific mandate windows.
Market Dynamics
Flight deck modernization mandates from Asia-Pacific aviation regulators are compressing retrofit timelines and forcing simultaneous hardware and software upgrades across mixed-generation fleets.
Growth Catalysts
- India's DGCA RNP mandates:Required Navigation Performance airspace rules are forcing domestic carriers to accelerate avionics retrofits on narrowbody aircraft operating high-density corridors.
- Software-defined avionics:Modular upgrade paths allow operators to refresh functionality without full hardware replacement, reducing downtime and extending platform lifecycles.
- COMAC C919 production ramp:China's civil aviation manufacturing clusters around Shanghai and Tianjin are generating sustained demand for indigenous and foreign-certified subsystem integration.
Market Restraints
- Semiconductor supply concentration:Critical flight control processors depend on concentrated East Asian foundry capacity, exposing programs to allocation volatility.
- CAAC indigenous certification:China's airworthiness requirements create friction for foreign suppliers seeking access to domestically assembled airframe programs.
- DO-178C compliance costs:Software assurance verification for Level A criticality systems consumes 40-60% of development budgets, elevating barriers for new entrants.
Strategic Opportunities
- Vietnam and Indonesia LCC expansion:Low-cost carriers across Southeast Asia are modernizing leased fleets, creating retrofit demand for cost-optimized flight deck architectures.
- Connected cockpit convergence:Integration of satellite communications with predictive maintenance analytics is enabling new aftermarket revenue streams for subsystem providers.
- Australia CASA ADS-B mandates:Automatic Dependent Surveillance-Broadcast requirements across oceanic routes are driving communication system upgrades for international operators.
Industry Challenges
- DO-178C software engineering talent scarcity:Qualified verification engineers with multi-domain expertise in ARINC protocols and safety-critical coding standards command premium compensation.
- Legacy analog-to-digital integration:Mixed-architecture fleets require complex gateway solutions to bridge ARINC 429 and ARINC 664 databus environments.
- Fragmented national airspace schedules:Divergent modernization timelines across JCAB, CASA, and DGCA jurisdictions complicate product roadmap alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Avionics Market |
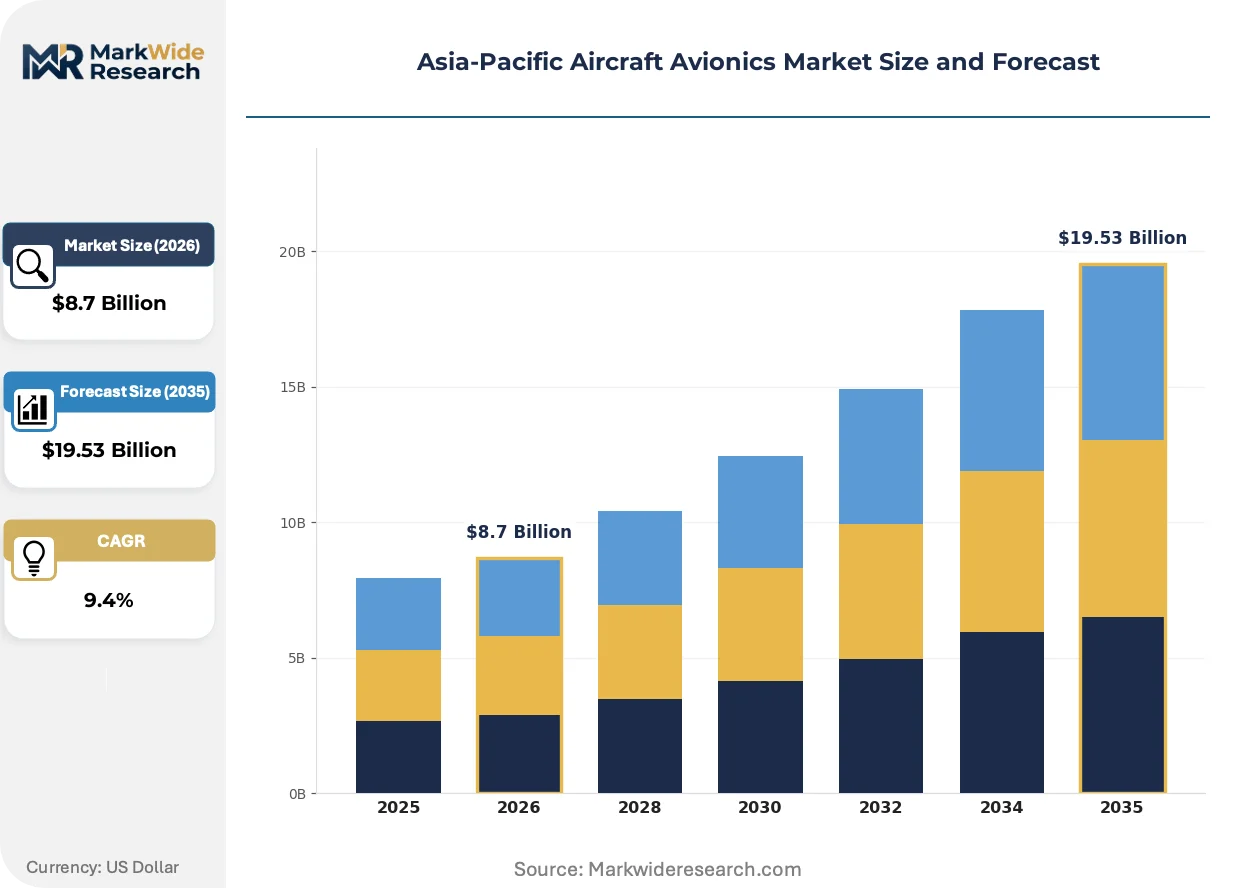
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
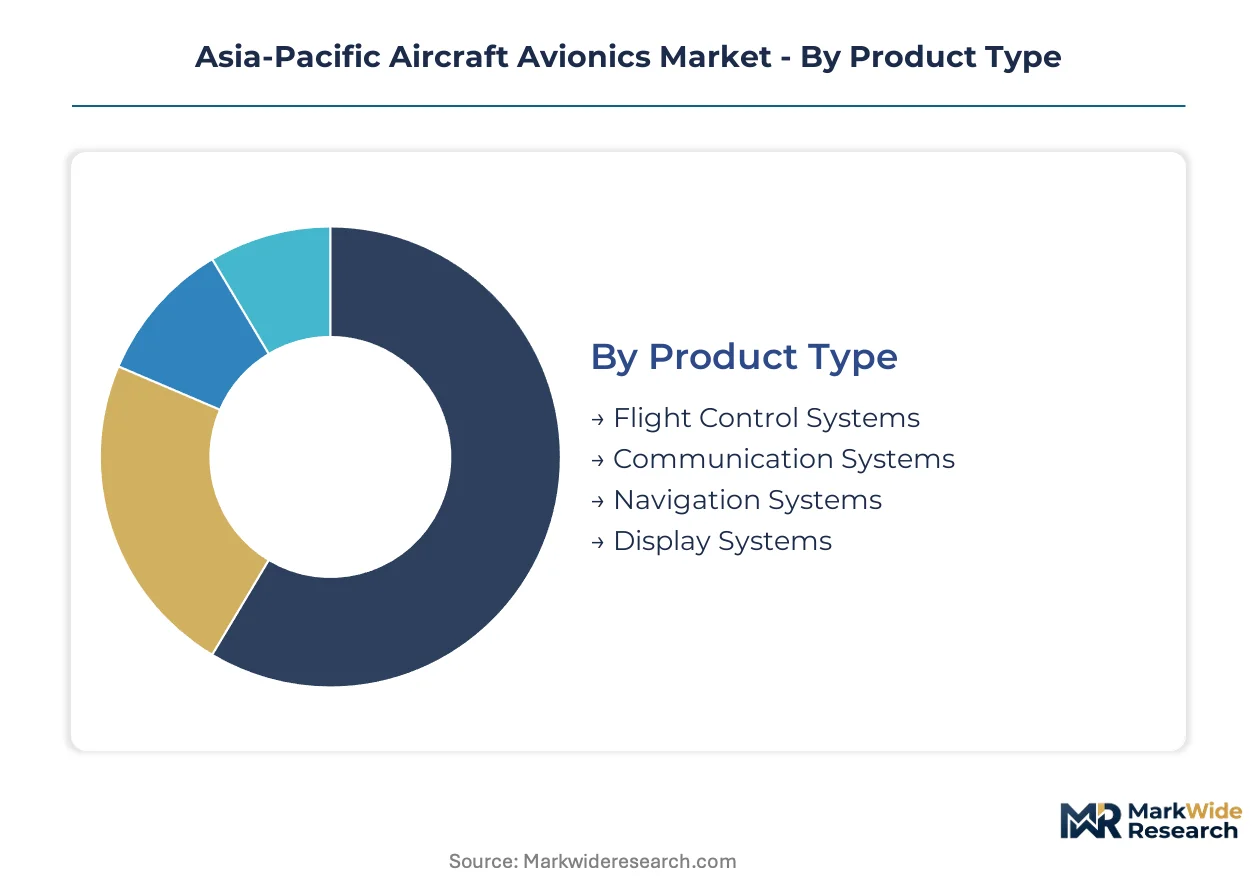
| Segmentation | Product Type: Flight Control Systems, Communication Systems, Navigation Systems, Display Systems End User: Commercial Aviation, Military Aviation, General Aviation, Cargo Aviation Technology: Analog, Digital, Hybrid, Software-Defined Application: Passenger Transport, Cargo Transport, Surveillance, In-Flight Entertainment |
| Companies Covered | Honeywell International Inc., Collins Aerospace, Thales, L3Harris Technologies, Inc., Safran, Garmin Ltd., BAE Systems, Northrop Grumman, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Avionics Market Strategic Shifts
Avionics architecture is shifting from federated boxes toward integrated computing platforms, compressing hardware footprints while expanding software functionality across flight-critical and non-critical domains.
Integrated modular avionics (IMA) architectures are replacing discrete line-replaceable units with shared computing resources partitioned for safety isolation. Asia-Pacific airlines operating high-utilization narrowbodies are adopting IMA faster than global peers to minimize spare inventory and reduce line maintenance burden. This consolidation is unifying previously separate flight control, navigation, and communication processing into common hardware substrates, forcing suppliers to compete on software differentiation rather than box-level specifications.
Japan's JCAB has aligned with ICAO Global Aviation Safety Plan timelines to mandate performance-based navigation across all terminal airspace by 2028. This regulatory compression is accelerating fleet-wide retrofit programs for regional carriers operating aging turboprop fleets. Communication and navigation subsystem providers are responding with bundled upgrade packages that combine GPS/WAAS receivers with satellite data link terminals to satisfy single-installation compliance.
Airlines are unbundling avionics maintenance from airframe heavy checks, establishing direct subsystem service contracts with OEMs and specialized MRO providers. This disintermediation of traditional airframe maintenance agreements is visible across Singapore, Hong Kong, and Australian flag carriers seeking operational data ownership. Component-level service agreements now include predictive algorithm access, shifting supplier revenue from hardware sales toward recurring analytics subscriptions.
Asia-Pacific Aircraft Avionics Market Segmentation
Avionics procurement across Asia-Pacific follows distinct technical and operational logics. Buyers prioritize certification alignment with national airworthiness authorities, lifecycle cost trajectories, and retrofit compatibility with existing fleet architectures.
Product Type:
Airlines evaluate subsystem replacement cycles against regulatory mandate windows and heavy check schedules.
- Flight Control Systems:Fly-by-wire architectures with triple-redundant processing cores dominate new installations. India's DGCA RNP mandates and Japan's JCAB performance-based navigation deadlines are compressing retrofit timelines for narrowbody operators across Mumbai, Delhi, and Tokyo hubs.
- Communication Systems:Satellite-based voice and data link terminals ensure ICAO oceanic route compliance. Australia's CASA ADS-B mandates across the Brisbane and Melbourne FIRs are forcing communication stack upgrades for international carriers serving trans-Pacific corridors.
- Navigation Systems:GPS/WAAS multi-constellation receivers with RNP-AR capability.
- Display Systems:Large-format LCD and OLED primary flight displays replacing CRT heritage units.
Volume sits with flight control systems; growth tilts toward communication systems.
End User:
Operator type dictates procurement scale, certification stringency, and upgrade frequency.
- Commercial Aviation:Full-service and low-cost carriers across Southeast Asia drive fleet-wide modernization programs. Vietnam and Indonesia LCCs are accelerating leased narrowbody retrofits to meet lessor return conditions and local airspace requirements.
- Military Aviation:Indigenous fighter and transport programs in South Korea and Australia demand sovereign-certified mission systems with export-controlled encryption.
- General Aviation:Business jet operators in Singapore and Hong Kong pursuing connectivity upgrades.
- Cargo Aviation:Express freight carriers optimizing payload-range through weight-reduced avionics suites.
Commercial aviation commands installed base; military programs show steepest expansion trajectory.
Technology:
Architecture choices determine hardware refresh cycles, software upgrade pathways, and regulatory re-certification burden.
- Software-Defined:Modular processing platforms enable functionality refresh without line-replaceable unit replacement. Airlines operating high-utilization narrowbodies from Shanghai and Tianjin clusters are adopting software-defined architectures faster than global peers to minimize spare inventory and reduce line maintenance burden.
- Digital:Federated digital systems with ARINC 664 backbone infrastructure.
- Hybrid:Mixed analog-digital architectures bridging legacy and modern databus environments.
- Analog:Heritage electromechanical instruments retained in select turboprop and rotary-wing platforms.
Digital systems anchor current revenue; software-defined platforms are climbing the fastest.
Application:
Mission profile shapes subsystem specification, redundancy requirements, and connectivity integration depth.
- Passenger Transport:Integrated flight decks with predictive maintenance analytics and passenger connectivity. Flag carriers in Singapore, Hong Kong, and Australia are unbundling avionics maintenance from airframe heavy checks, establishing direct subsystem service contracts with OEMs.
- Surveillance:Maritime patrol and airborne early warning platforms requiring multi-sensor fusion and secure datalinks.
- Cargo Transport:Weight-optimized minimal crew alerting systems for dedicated freighter operations.
- In-Flight Entertainment:Cabin management systems interfacing with flight deck connectivity infrastructure.
Passenger transport generates dominant volume; surveillance applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing clusters in China's Inner Mongolia and Jiangxi provinces supply critical magnetic materials for flight control actuators across the region's avionics supply chain.
China
COMAC's C919 production ramp in Shanghai and Tianjin is generating sustained subsystem demand from domestic and foreign-certified suppliers. CAAC indigenous certification requirements create friction for foreign suppliers seeking access to domestically assembled airframe programs. The Yangtze River Delta avionics corridor concentrates flight control and navigation system integration facilities serving both commercial and military programs.
India
DGCA Required Navigation Performance mandates are forcing domestic carriers to accelerate narrowbody retrofits on high-density corridors. The regulator's compressed compliance timelines are compressing hardware and software upgrade schedules across mixed-generation fleets. Bangalore and Hyderabad host emerging avionics software development centers supporting both civil and defense programs.
Japan
JCAB performance-based navigation deadlines are accelerating fleet-wide retrofit programs for regional carriers operating aging turboprop fleets. The regulator's 2028 terminal airspace mandate aligns with ICAO Global Aviation Safety Plan timelines. Nagoya's aerospace manufacturing belt sustains precision component production for integrated flight deck systems.
South Korea
KF-21 fighter and transport programs are driving sovereign-certified mission system demand with export-controlled encryption requirements. The national aerospace agency's indigenous platform push is elevating local subsystem integration capabilities. Sacheon and Seoul metropolitan clusters specialize in avionics subsystem production for regional jet export programs.
Australia
CASA ADS-B mandates across Brisbane and Melbourne FIRs are forcing communication stack upgrades for trans-Pacific international operators. The regulator's oceanic route requirements are driving satellite-based voice and data link terminal installations. Melbourne and Brisbane maintenance hubs are unbundling avionics service contracts from traditional airframe heavy check agreements.
Asia-Pacific Aircraft Avionics Market Competitive Environment
Global majors compete with regional champions across certification alignment and indigenous platform access. The market structures around three tiers: integrated flight deck architects, specialized subsystem providers, and software-defined platform specialists. Strategic moves concentrate on regulatory pre-positioning for national mandate windows and technology licensing for indigenous airframe programs.
Among the integrated flight deck architects, Honeywell International Inc., Collins Aerospace, and Safran occupy positions defined by their regulatory footprint breadth and airframe program anchoring. Honeywell exemplifies the vertically integrated systems house with multi-platform architecture deployment. Collins Aerospace represents the connected cockpit convergence specialist with predictive maintenance analytics integration. Safran sits within the high-density corridor optimization tier, with specialized landing and navigation systems tailored to Asian air traffic patterns.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| Thales |
| L3Harris Technologies, Inc. |
| Safran |
| Garmin Ltd. |
| BAE Systems |
| Northrop Grumman |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
DO-178C software verification engineers concentrated in Bangalore and Hyderabad drive labor-cost spreads between premium-certified and standard-grade avionics tiers, with tier-one suppliers capturing margin through bundled long-term service agreements while emerging integrators compete on unbundled hardware pricing.
Pricing Analysis
Warranty and predictive maintenance bundling separates tier-one OEM pricing from pure-hardware quotations, with Honeywell and Collins Aerospace anchoring premium tiers through integrated flight deck architectures and recurring analytics subscriptions. Price differentiation rests on DO-178C certification level and ARINC 664 integration depth. Pricing pressure intensifies in communication systems as satellite data link commoditization erodes hardware margins. Low-cost carriers across Vietnam and Indonesia exhibit highest price sensitivity, demanding cost-optimized retrofit packages with unbundled service terms.
Supply Chain Analysis
Flight control processor fabrication capacity shortages in Taiwan, South Korea, and Japan constrain output scheduling for regional jet programs and narrowbody retrofits. Critical inputs include rare earth magnets from China's Inner Mongolia and Jiangxi provinces, ARINC 429/664 databus components, and radiation-hardened semiconductors. Single-source vulnerability in East Asian foundry exposure creates allocation volatility during demand spikes. Distribution runs through Shanghai and Tianjin civil aviation clusters, with subsystem integrators maintaining direct OEM relationships and specialized MRO channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific aircraft avionics is becoming a vertical-integration race, with subsystem providers pursuing backward control over DO-178C software engineering talent pools to defend margin structures against modular platform disintermediation.
For Market Incumbents: Lock in software-defined architecture roadmaps through exclusive DO-178C engineering partnerships in Bangalore and Hyderabad, while securing CAAC pre-certification for COMAC C919 derivative programs to forestall foreign supplier displacement. Threat of indigenous Chinese subsystem integration demands accelerated localization investments. Backward integration into flight control processor sourcing mitigates foundry allocation risk. For New Entrants and Emerging Players: Capture Vietnam and Indonesia LCC retrofit demand through cost-optimized ARINC 429-to-664 gateway solutions that bridge mixed-generation fleets without full hardware replacement. The most penetrable segment sits with regional turboprop operators facing JCAB 2028 performance-based navigation deadlines. Go-to-market leverage: bundled compliance packages combining GPS/WAAS receivers with satellite data link terminals. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined platform specialists given airline disintermediation of traditional airframe maintenance agreements and direct subsystem service contracting. Long-term viability favors providers owning predictive algorithm IP and operational data access rights. Acquisition target archetype: mid-tier ARINC protocol specialists with CAAC certification pathway progress. Signal to watch: CASA and DGCA mandate synchronization accelerating fleet-wide retrofit program consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Certification Investment | CAAC and DGCA compliance windows compress development timelines for flight-critical software. |
| Software-Defined Platform Launch | Modular architectures enable functionality refresh without line-replaceable unit replacement, extending lifecycle revenue. |
| Regional Engineering Center Expansion | Bangalore and Hyderabad talent pools reduce verification engineering costs while accelerating RNP mandate response. |
| Predictive Maintenance Analytics Partnership | Singapore and Hong Kong flag carriers seek operational data ownership through direct OEM service contracts. |
| Indigenous Airframe Integration Agreement | COMAC C919 subsystem qualification secures access to China's civil aviation manufacturing clusters. |
Study Parameters
Multi-period observation of DGCA mandate compliance timelines, JCAB performance-based navigation adoption curves, and COMAC C919 production ramp rates anchored the trend analysis, supplemented by interviews with flight deck engineering directors at Asia-Pacific flag carriers, avionics subsystem procurement leads at low-cost carriers, DO-178C verification specialists at Bangalore software centers, and MRO operations heads at Singapore and Hong Kong maintenance hubs. Secondary validation drew from CAAC type certification databases, CASA ADS-B mandate filings, ARINC protocol specification releases, and customs records of avionics component trade flows. Bottom-up segment sizing triangulated against top-down fleet projection models.
Segment-weighting applied product type, end user, technology architecture, and application mission profile dimensions across the projection horizon. CAGRs derived from fitted growth curves against regulatory mandate windows and airframe delivery schedules. Industry-specific forecast inputs incorporated airline heavy check cycle timing, lessor return condition requirements, and national airspace modernization expenditure commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAAC indigenous certification policy shifts, East Asian semiconductor foundry capacity allocation, and JCAB-DGCA-CASA mandate synchronization. Forecasts reflect documented assumptions regarding regulatory timeline adherence and fleet replacement rates. Material deviation in COMAC production ramp velocity or DO-178C engineering wage inflation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Aircraft Computers Market
Avionics
Military Avionic Systems Market
Avionics
Electronic Flight Instrument System Market
Avionics
Customized Avionic Systems Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Europe Aircraft Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Display for Avionics Application Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Military Aircraft Avionics Market
Avionics
Commercial Electronic Flight Bag Market