
 Asia-Pacific Aircraft Health Monitoring System Market | 2026-2036
Asia-Pacific Aircraft Health Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Health Monitoring System Market Analytics
The capability gap between sensor-integrated OEM platforms and aftermarket retrofit providers is collapsing as hardware costs fall and software architectures standardize. Honeywell International Inc leverages its integrated avionics heritage to bundle health monitoring with flight management systems across Asian carrier fleets. Safran S.A. sustains competitive positioning through specialized engine diagnostics that anchor long-term service contracts with regional low-cost airlines.
An Aircraft Health Monitoring System comprises networked sensors, data acquisition units, and analytical software that continuously assess airframe, engine, and component condition through vibration, temperature, and pressure telemetry with sampling rates exceeding 1 kHz for critical rotating machinery. Its primary purpose is to shift maintenance from fixed-interval overhauls to condition-based interventions, reducing aircraft-on-ground downtime. Engine Monitoring commands the largest installed base across Asia-Pacific fleets due to high-value rotating equipment and established regulatory reporting protocols, while Predictive Maintenance represents the fastest-expanding segment as airlines deploy machine learning models to anticipate failures before threshold alerts trigger. Big Data Analytics platforms extract margin from fragmented MRO data lakes, though IoT edge devices still dominate new installations by unit volume.
India's DGCA airworthiness directives and China's CAAC continuing airworthiness management requirements both mandate enhanced structural health documentation for aircraft exceeding specified flight cycles, directly expanding monitoring hardware demand. Japan's MLIT coordinates with METI to align domestic health monitoring standards with ICAO Annex 6 performance-based navigation maintenance protocols, creating compliance-driven replacement cycles. Stakeholders must weigh the trade-off between cloud-native analytics architectures and sovereign data residency requirements as Indonesia, Vietnam, and Thailand draft national aviation cybersecurity frameworks.
Market Dynamics
Sensor-to-cloud integration is collapsing the historical separation between flight operations and maintenance planning, forcing airlines to restructure their data governance architectures around real-time telemetry pipelines rather than periodic manual inspections.
Growth Catalysts
- CAAC Continuing Airworthiness Management:China's civil aviation regulator mandates enhanced structural health documentation for high-cycle aircraft, compelling domestic carriers to install continuous monitoring hardware on narrow-body fleets operating above 30,000 cycles.
- Machine Learning Diagnostics:Predictive algorithms trained on vibration and thermal signatures now detect bearing degradation in turbofan engines 200-400 flight hours before traditional threshold alerts, compressing maintenance planning windows.
- Shanghai-Tianjin Manufacturing Clusters:COMAC's production ramp-up at these civil aviation hubs generates integrated health monitoring procurement tied to new aircraft deliveries, embedding sensors at the assembly stage rather than retrofitting post-delivery.
Market Restraints
- Aviation-Grade Sensor Cost Volatility:MEMS accelerometers and fiber-optic strain gauges require aerospace certification batches that command 8-12x consumer electronics pricing, constraining retrofit economics for regional turboprop operators.
- Data Sovereignty Requirements:Indonesia, Vietnam, and Thailand are drafting national aviation cybersecurity frameworks that mandate in-country data residency, fragmenting cloud analytics architectures and raising infrastructure duplication costs.
- Interoperability Limitations:Proprietary data protocols from incumbent avionics suppliers lock airline maintenance systems into single-vendor analytics platforms, delaying fleet-wide standardization.
Strategic Opportunities
- Vietnam and Philippines Fleet Expansion:Low-cost carriers in these markets are adding 100+ narrow-body aircraft through 2030 with health monitoring specified in original equipment contracts, bypassing the retrofit cost barrier entirely.
- Digital Twin Convergence:Integration of physics-based degradation models with live sensor streams enables component-level remaining useful life predictions, opening performance-based maintenance contracts where suppliers assume operational risk.
- DGCA Aging Aircraft Directives:India's airworthiness mandates for aircraft exceeding specified flight cycles create mandatory replacement demand for structural health monitoring hardware on domestic A320 and 737 fleets.
Industry Challenges
- Certification Timeline Compression:Hardware-software integrated systems require coordinated approval from CAAC, DGCA, and JCAB for regional deployment, stretching product launch cycles to 18-24 months.
- Legacy Fleet Integration Complexity:ARINC 429 and MIL-STD-1553 data buses on aircraft delivered before 2010 lack bandwidth for high-frequency vibration telemetry, demanding parallel acquisition unit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Health Monitoring System Market |
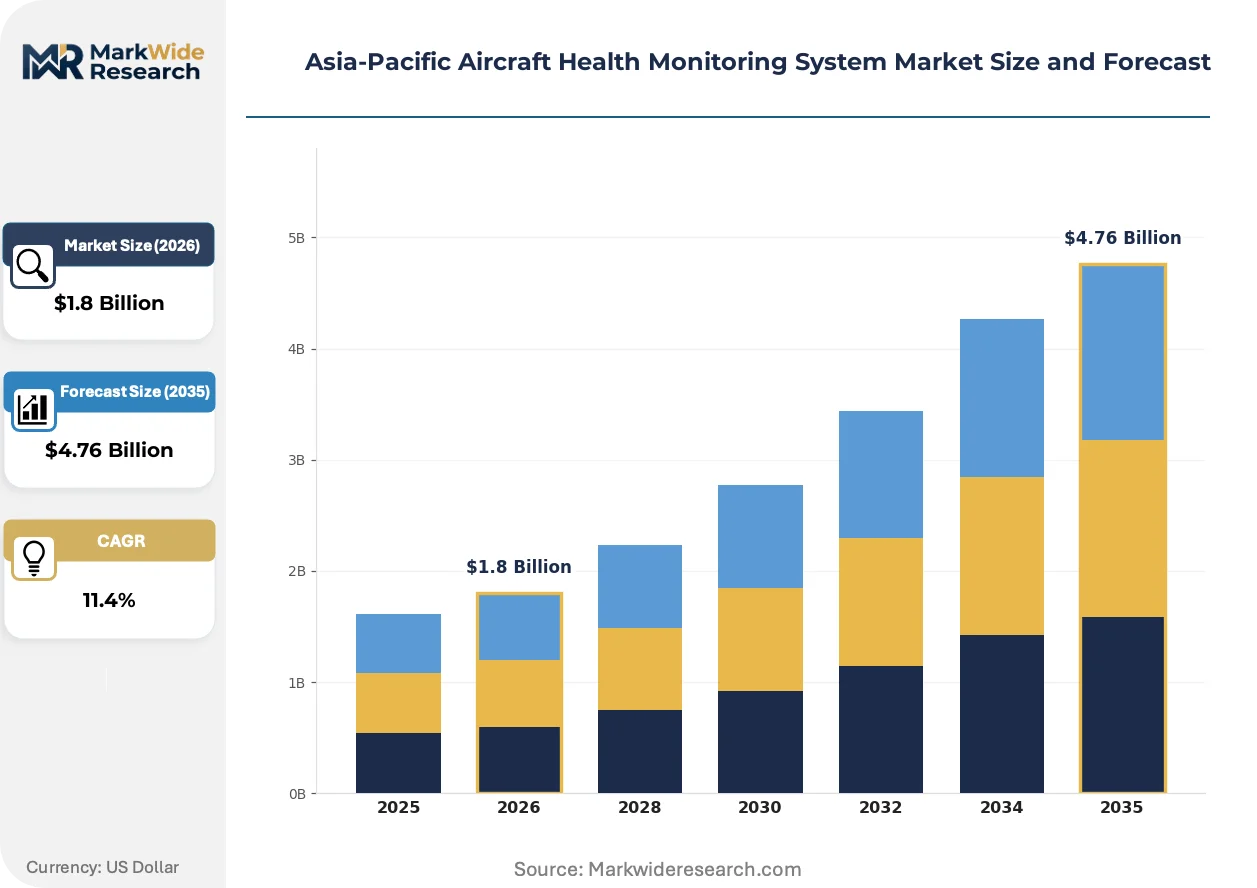
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Monitoring, Structural Monitoring, Component Monitoring, Predictive Maintenance Technology: IoT, AI, Machine Learning, Big Data Analytics End User: Airlines, MRO Providers, OEMs, Military Installation: Onboard Systems, Ground Systems, Hybrid Systems, Cloud-Based Solutions |
| Companies Covered | Honeywell International Inc, Airbus, The Boeing Company, Raytheon Technologies Corporation, GE Aerospace, Rolls-Royce Holdings plc, Safran S.A., Meggitt PLC, Lufthansa Technik, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Health Monitoring System Market Evolving Landscape
Edge computing architectures are redistributing analytical workloads from centralized cloud platforms to onboard data acquisition units, enabling real-time anomaly detection without satellite connectivity dependency during oceanic routes.
Edge-native inference engines are supplanting ground-based batch analytics for critical rotating machinery monitoring. Full-service carriers across Southeast Asia are deploying these systems on wide-body fleets operating transpacific routes where communication latency exceeds 300 milliseconds. This shift compresses the failure detection-to-intervention window from hours to seconds, eliminating the satellite relay bottleneck that previously delayed threshold alerts.
Japan's MLIT alignment with ICAO Annex 6 performance-based navigation maintenance protocols is mandating standardized health data reporting formats across domestic operators. This regulatory harmonization forces MRO providers to retool their analytics platforms for interoperable data exchange. Regional low-cost airlines operating mixed Boeing-Airbus fleets face the steepest compliance costs as they consolidate previously fragmented maintenance record systems.
Airlines are unbundling health monitoring data from traditional engine maintenance service agreements, creating standalone data monetization streams. Lessors and insurers now purchase anonymized fleet-wide degradation patterns to refine residual value models and risk pricing. This procurement model change is most visible in Singapore and Hong Kong, where aircraft leasing concentration has spawned specialized data intermediaries that aggregate and resell health telemetry across operator portfolios.
Asia-Pacific Aircraft Health Monitoring System Market Segmentation
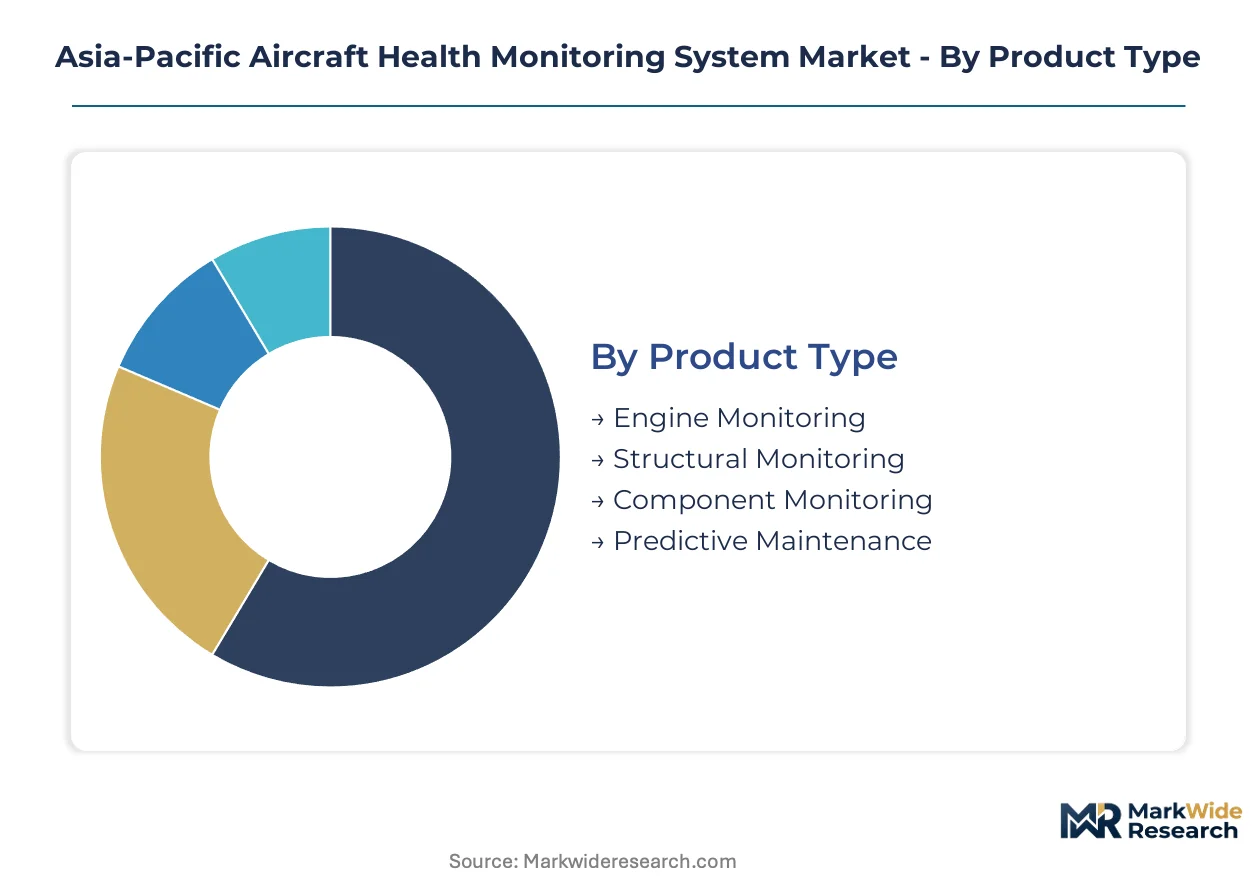
Segmentation in Asia-Pacific Aircraft Health Monitoring System markets reveals how regulatory mandates and fleet modernization priorities reshape procurement patterns across distinct technology tiers and installation architectures.
Product Type:
CAAC continuing airworthiness directives and DGCA aging aircraft mandates create divergent hardware requirements across monitoring categories, with narrow-body fleets in China and India facing the steepest compliance thresholds.
- Engine Monitoring:Continuous vibration and thermal telemetry systems sample critical rotating machinery above 1 kHz, capturing turbofan bearing degradation signatures. Demand concentrates across Southeast Asian full-service carriers operating high-cycle narrow-body fleets, driven by unscheduled maintenance reduction targets and fuel efficiency optimization programs.
- Predictive Maintenance:Machine learning models trained on historical failure patterns anticipate component degradation 200-400 flight hours before threshold alerts trigger. Airlines in Singapore and Hong Kong lead deployment, leveraging these capabilities to compress maintenance planning windows and negotiate performance-based contracts with lessors.
- Structural Monitoring:Fiber-optic strain gauges and accelerometers track airframe fatigue accumulation on aging commercial aircraft.
- Component Monitoring:Discrete sensor networks assess landing gear, avionics, and auxiliary power unit condition through discrete health indicators.
Established volume favors Engine Monitoring; emerging adoption favors Predictive Maintenance.
Technology:
Cost tier differentiation separates capital-intensive edge computing deployments from subscription-based cloud analytics, with regional carriers prioritizing upfront hardware ownership over recurring software fees.
- Big Data Analytics:Platforms aggregate fragmented MRO data lakes across mixed-fleet operators, extracting operational margin from previously siloed maintenance records. Japanese carriers face the steepest implementation costs as MLIT-mandated standardized reporting formats force platform retooling for ICAO Annex 6 compliance.
- IoT:Edge devices dominate new installations by unit volume, with MEMS accelerometers and wireless sensor nodes enabling distributed data acquisition without aircraft wiring modifications. Vietnam and Philippines low-cost carriers specify IoT-enabled health monitoring in original equipment contracts for 100+ narrow-body deliveries.
- Machine Learning:Inference engines trained on regional fleet degradation patterns enable component-level remaining useful life predictions.
- AI:Autonomous anomaly detection systems process multi-parameter sensor streams without ground-based validation.
Volume concentration sits with IoT deployments; value capture is climbing the fastest in Big Data Analytics.
End User:
Customer type determines procurement authority, with airlines controlling fleet-wide retrofit decisions while OEMs embed sensors during assembly at Shanghai and Tianjin manufacturing clusters.
- Airlines:Full-service and low-cost carriers across Southeast Asia, India, and China drive fleet-wide sensor deployment, restructuring data governance architectures around real-time telemetry pipelines. Indonesia's Garuda and Lion Air groups mandate health monitoring specifications in lease-return conditions, shifting supplier accountability to residual value protection.
- MRO Providers:Maintenance organizations in Singapore and Hong Kong aggregate anonymized degradation data across operator portfolios, reselling insights to lessors and insurers for risk pricing refinement.
- OEMs:COMAC embeds integrated health monitoring systems during C919 assembly at Shanghai-Tianjin hubs, bypassing retrofit economics entirely.
- Military:Defense procurement operates through separate certification channels with classified data handling requirements.
Procurement scale favors Airlines; margin expansion favors MRO Providers.
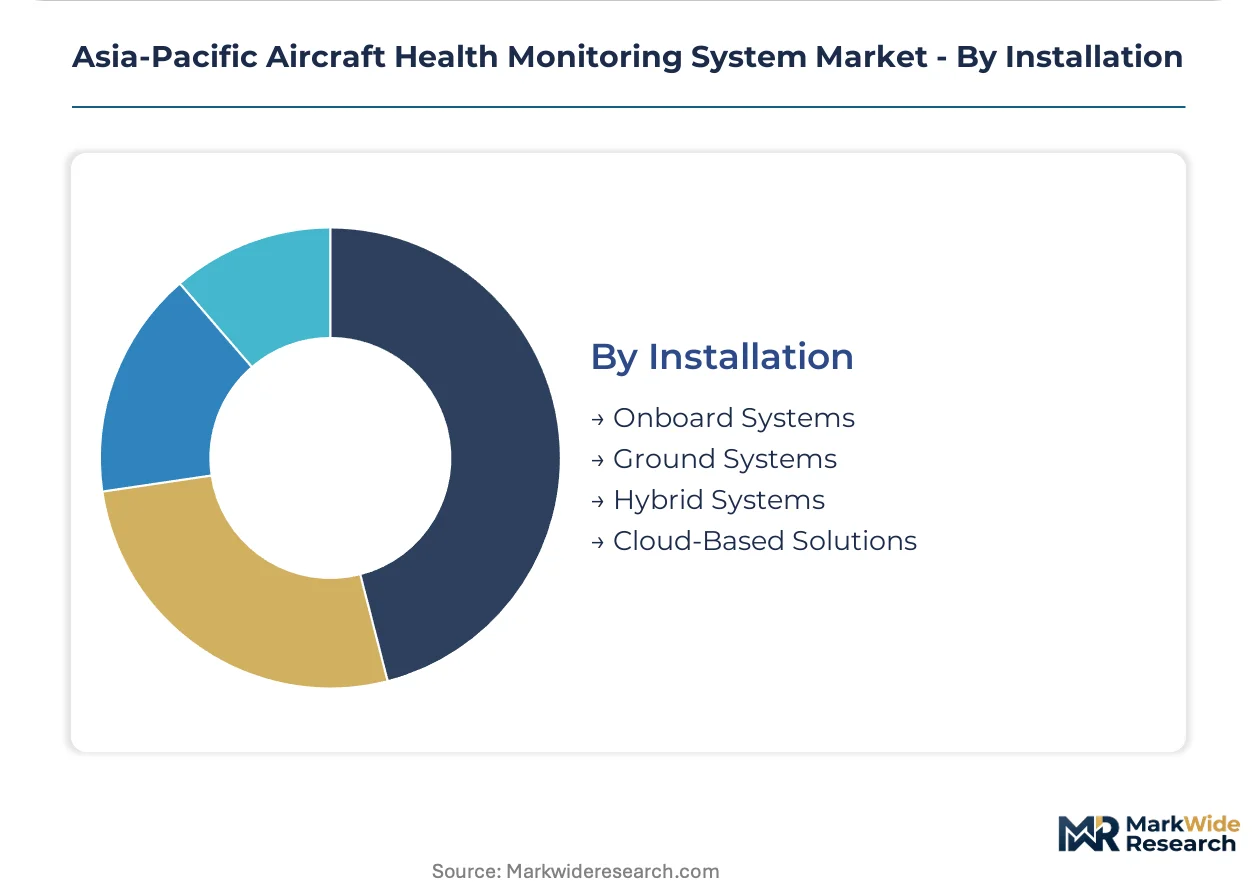
Installation:
Supply concentration in avionics certification creates vendor lock-in, with proprietary data protocols from incumbent suppliers fragmenting fleet-wide standardization efforts across mixed Boeing-Airbus operations.
- Onboard Systems:Data acquisition units with edge-native inference engines process vibration and thermal signatures without satellite connectivity dependency. Southeast Asian wide-body fleets operating transpacific routes deploy these systems to eliminate 300-millisecond communication latency bottlenecks.
- Cloud-Based Solutions:Centralized analytics platforms face fragmentation as Indonesia, Vietnam, and Thailand draft national aviation cybersecurity frameworks mandating in-country data residency, forcing infrastructure duplication.
- Ground Systems:Terrestrial data processing centers handle batch analytics for maintenance planning during scheduled turnarounds.
- Hybrid Systems:Architectures split workloads between onboard preprocessing and cloud-based model training.
Deployment breadth favors Onboard Systems; architectural innovation favors Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional turboprop operators exhibit the highest price elasticity, deferring sensor retrofits until regulatory mandates force compliance, while Singapore and Hong Kong lessors absorb premium analytics costs to protect residual values on narrow-body portfolios.
China
COMAC's C919 production ramp-up at Shanghai-Tianjin manufacturing clusters embeds health monitoring hardware at the assembly stage, bypassing retrofit economics entirely. CAAC continuing airworthiness management requirements mandate enhanced structural health documentation for aircraft exceeding 30,000 flight cycles, compelling domestic carriers to install continuous monitoring systems. These procurement volumes concentrate in civil aviation hubs where integrated sensor-avionics packages ship with new aircraft deliveries.
India
Domestic A320 and 737 fleets face mandatory hardware replacement demand under DGCA aging aircraft directives for high-cycle commercial aircraft. Indigo and Air India expand fleet-wide sensor deployments to reduce unscheduled maintenance events and optimize fuel efficiency across narrow-body operations. Procurement authority rests with airline engineering departments restructuring data governance around real-time telemetry pipelines rather than periodic inspections.
Japan
MLIT coordination with METI aligns domestic health monitoring standards with ICAO Annex 6 performance-based navigation maintenance protocols, forcing MRO providers to retool analytics platforms for interoperable data exchange. ANA and JAL deploy edge-native inference engines on wide-body transpacific fleets to eliminate satellite communication latency bottlenecks exceeding 300 milliseconds. Compliance-driven replacement cycles favor onboard systems with standardized reporting formats.
Singapore
Aircraft leasing concentration has spawned specialized data intermediaries aggregating anonymized fleet-wide degradation patterns for lessors and insurers refining residual value models. Full-service carriers deploy predictive maintenance algorithms trained on historical failure patterns to compress maintenance planning windows and negotiate performance-based contracts. Procurement prioritizes cloud-native analytics platforms despite emerging data sovereignty constraints across Southeast Asian operations.
Vietnam
VietJet and Bamboo Airways specify health monitoring in original equipment contracts for 100+ narrow-body aircraft deliveries through 2030, eliminating retrofit cost barriers entirely. National aviation cybersecurity frameworks drafting in-country data residency requirements fragment cloud analytics architectures and raise infrastructure duplication costs. Low-cost carrier procurement favors IoT-enabled edge devices specified at the manufacturing stage rather than post-delivery installations.
Asia-Pacific Aircraft Health Monitoring System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated avionics heritage conferring systems-level bundling advantages while specialized diagnostics providers capture long-term service contract value. The market structure consolidates around three strategic tiers: diversified aerospace conglomerates with flight management integration capabilities, engine OEMs with proprietary degradation model libraries, and independent sensor-software specialists competing on retrofit economics. Dominant competitive moves include vertical integration into edge computing hardware and strategic partnerships with regional MRO providers to secure fleet-wide deployment mandates.
Within the integrated systems tier, Honeywell International Inc and GE Aerospace exemplify archetypes leveraging avionics heritage to bundle health monitoring with broader flight operations platforms. Safran S.A. occupies a specialized diagnostics position anchoring long-term engine service contracts through proprietary turbofan degradation analytics. These three companies represent the dominant competitive anchors shaping procurement patterns across Asia-Pacific carrier fleets and manufacturing clusters.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Airbus |
| The Boeing Company |
| Raytheon Technologies Corporation |
| GE Aerospace |
| Rolls-Royce Holdings plc |
| Safran S.A. |
| Meggitt PLC |
| Lufthansa Technik |
| Others |
Value Network & Pricing Analysis
CAAC continuing airworthiness certification gates both supplier qualification and price differentiation simultaneously, as aerospace-grade MEMS accelerometers and fiber-optic strain gauges require batch-specific validation that commands 8-12x consumer electronics pricing. This regulatory threshold fragments procurement authority between OEM-embedded systems and aftermarket retrofit providers, with cost compression in sensor hardware collapsing historical capability gaps.
Pricing Analysis
Extended service contracts and long-term maintenance agreements drive lifetime value capture across Asia-Pacific carrier fleets. Three-tier pricing structure across premium avionics-integrated, standard standalone hardware, and economy sensor-only configurations reflects certification grade and after-sales bundling intensity. Cost compression in MEMS components is intensifying because semiconductor manufacturing scale benefits are penetrating aerospace certification batches. Regional turboprop operators exhibit highest price sensitivity, while Singapore and Hong Kong lessors absorb premium analytics costs to protect narrow-body residual values.
Supply Chain Analysis
China and Japan anchor precision sensor fabrication and avionics integration for Asia-Pacific health monitoring systems. Supply chains draw from Taiwanese semiconductor foundries for edge computing chipsets, Japanese fiber-optic component specialists, and domestic Chinese assembly for COMAC-integrated systems. Single-source vulnerability concentrates in aerospace-grade MEMS certification batches where alternative qualification timelines stretch 18-24 months. Distribution runs through OEM direct procurement for new aircraft deliveries and specialized avionics distributors for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among full-service carriers and lessors aggregating fleet-wide deployment mandates, fragmenting procurement authority previously held by fragmented regional operators. This consolidation forces suppliers to restructure pricing and service architectures around multi-airline enterprise contracts.
For Market Incumbents: Fortify proprietary data protocol ecosystems to lock maintenance systems into single-vendor analytics platforms, delaying fleet-wide standardization that would commoditize hardware margins. Invest in CAAC-DGCA-JCAB coordinated certification pipelines to compress 18-24 month product launch cycles and preempt emerging sensor-software specialists. Vertical integration into edge computing hardware manufacturing secures captive supply of inference engines for transpacific route deployments. For New Entrants and Emerging Players: CAAC fast-track certification for narrow-body retrofit applications opens procurement windows among Chinese domestic carriers facing 30,000-cycle compliance thresholds. Target Vietnam and Philippines low-cost carriers specifying health monitoring in original equipment contracts for 100+ aircraft deliveries, bypassing retrofit economics entirely. Lead with IoT-enabled wireless sensor nodes that eliminate aircraft wiring modifications, reducing installation downtime from weeks to days. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native analytics platforms as software architectures standardize and hardware costs fall. Focus acquisition screening on independent sensor-software specialists with established CAAC or DGCA certification pipelines and existing fleet deployment relationships. Watch for inflection when Indonesia, Vietnam, and Thailand finalize national aviation cybersecurity frameworks mandating in-country data residency, fragmenting cloud architectures and raising infrastructure duplication costs that favor hybrid-system specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Onboard inference engines eliminate satellite latency bottlenecks exceeding 300 milliseconds on transpacific routes. |
| Regulatory Certification Pipeline Investment | Coordinated CAAC-DGCA-JCAB approval compresses product launch cycles from fragmented sequential filings. |
| Data Sovereignty Infrastructure Buildout | In-country server deployments capture Indonesia, Vietnam, and Thailand cybersecurity framework mandates. |
| Performance-Based Maintenance Contracting | Suppliers assume operational risk through physics-based digital twin integration with live sensor streams. |
| MRO Provider Strategic Partnership | Singapore and Hong Kong maintenance organizations aggregate anonymized degradation data across operator portfolios. |
Research Methodology
The analysis maps engine monitoring, predictive maintenance, structural monitoring, and component monitoring sub-sectors, each validated through airline engineering directors, MRO procurement leads, avionics integration specialists, and regulatory affairs officers at CAAC and DGCA. Primary interviews combined with secondary validation from aircraft production databases, airworthiness directive filings, customs import records for aerospace sensors, and SEC filings from listed avionics suppliers. Bottom-up unit deployment estimates triangulated against top-down fleet modernization expenditure projections.
Consistency checks validated volume and value outputs against external benchmarks including regional aircraft delivery schedules, MRO capacity expansion announcements, and documented compliance timelines for aging aircraft directives. Segmentation dimensions modeled include product type, technology tier, end-user category, and installation architecture across the projection horizon. CAGRs derived from fitted growth curves incorporating fleet expansion trajectories, regulatory mandate effective dates, and technology substitution elasticities between retrofit and OEM-embedded systems.
Decision-makers should treat outputs as directional under assumptions of sustained CAAC and DGCA enforcement intensity and stable semiconductor supply for aerospace-grade components; material deviation in regulatory timelines or trade restrictions would warrant model refresh. Recalibration cycles align with material shifts in national aviation cybersecurity framework finalizations and COMAC production ramp milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Aircraft Computers Market
Avionics
Military Aircraft Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Global Avionics Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Electronic Flight Instrument System Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Customized Avionic Systems Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Display for Avionics Application Market