
 North America Military Aircraft Communication Avionics Market | 2026-2036
North America Military Aircraft Communication Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Military Aircraft Communication Avionics Market Analytics
Market Context
Defense prime manufacturing capacity across the southwestern United States is restructuring to accommodate classified communication avionics production lines. L3Harris Technologies leverages its Rochester, New York heritage in tactical radio systems to sustain long-term military contracts. RTX anchors its position through integrated sensor-communication portfolios spanning multiple aircraft platforms. Northrop Grumman Corporation differentiates via specialized low-observable communication suites tailored for stealth aircraft applications.
Technical Definition and Segment Structure
North America Military Aircraft Communication Avionics encompasses the integrated electronic systems enabling secure voice, data, and navigation transmission between airborne platforms, ground stations, and satellite networks, typically operating across HF through Ka-band frequencies with embedded encryption and anti-jam protocols. These systems serve the primary purpose of maintaining tactical situational awareness and command continuity in contested electromagnetic environments. Software-Defined Radio technology leads growth trajectories as programmable waveforms displace fixed-architecture hardware, while Secure Communication protocols command premium margin pools due to classified certification requirements. Radio Communication remains the largest installed base category, though Data Link Systems exhibits the fastest expansion as networked warfare concepts mature across US and Canadian forces.
Regulatory Framework
The Department of Defense, FAA, and NIST cybersecurity frameworks collectively shape procurement standards, mandating zero-trust architectures and supply chain traceability for all airborne communication hardware. ITAR export controls and CMMC certification requirements restrict vendor participation to domestic and cleared foreign entities, compressing the addressable supplier base. Stakeholders must monitor evolving spectrum allocation decisions by the NTIA and FCC, as commercial 5G expansion threatens to encroach on historically protected military frequency bands.
Market Dynamics
Software-Defined Radio architectures are compressing hardware refresh cycles across US and Canadian fighter modernization programs, forcing prime contractors to restructure production lines around reprogrammable waveform engines rather than fixed-function radio sets.
Growth Catalysts
- Fighter Jet Modernization:The US Air Force F-35 and F-22 upgrade pipelines are mandating next-generation communication suites with embedded anti-jam protocols.
- CMMC Certification Mandates:The Department of Defense's Cybersecurity Maturity Model Certification requirements are filtering supplier pools toward cleared domestic entities with traceable supply chains.
- Southwestern US Defense Clustering:Arizona and California flight test ranges concentrate demand pull for integrated sensor-communication systems undergoing live-fire validation.
Market Restraints
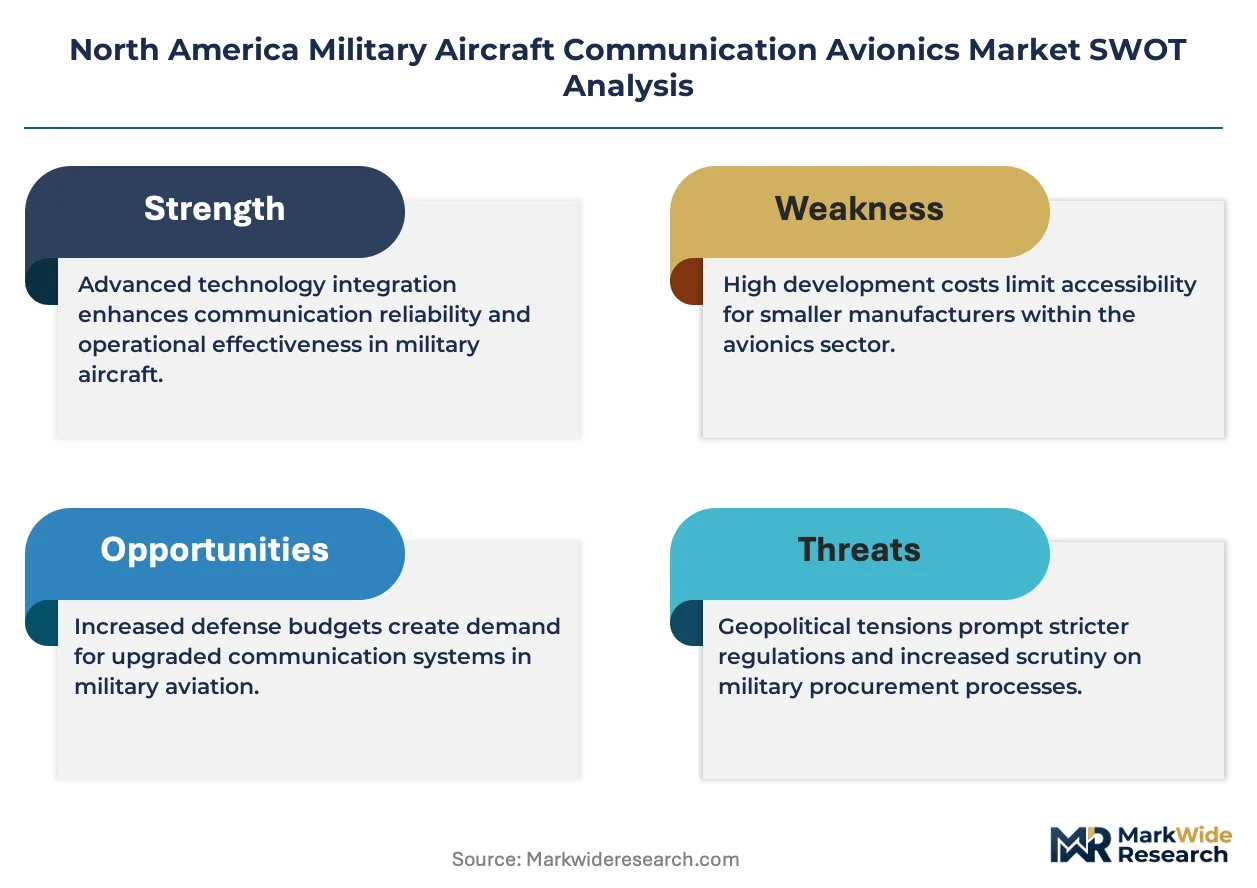
- ITAR Export Controls:International Traffic in Arms Regulations restrict component sourcing to domestic and specifically cleared foreign suppliers, compressing vendor options.
- GaN Substrate Costs:Gallium nitride semiconductor substrates essential for high-power RF amplification face concentrated supply from limited foundry capacity.
- Spectrum Encroachment:FCC and NTIA allocation decisions permitting commercial 5G expansion threaten historically protected military frequency bands in the L-band and C-band ranges.
Strategic Opportunities
- Canadian Arctic Operations:NORAD modernization initiatives are driving demand for beyond-line-of-sight communication systems hardened for polar electromagnetic conditions.
- Zero-Trust Architecture Mandates:NIST cybersecurity framework adoption across DoD platforms creates certified-upgrade pathways for legacy aircraft communication backbones.
- Satcom-Ka Band Convergence:Integration of tactical radio terminals with protected satellite communication waveforms opens integrated air-ground-space network architectures.
Industry Challenges
- Cleared Workforce Scarcity:TS/SCI-cleared RF engineers and embedded software developers face acute shortages in Arizona, California, and Texas defense corridors.
- Legacy Bus Integration:MIL-STD-1553 and newer IEEE 1394b data bus architectures require complex protocol bridging for new communication avionics retrofit.
- Type Certification Timelines:FAA and military airworthiness qualification processes for software-intensive communication systems extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Military Aircraft Communication Avionics Market |
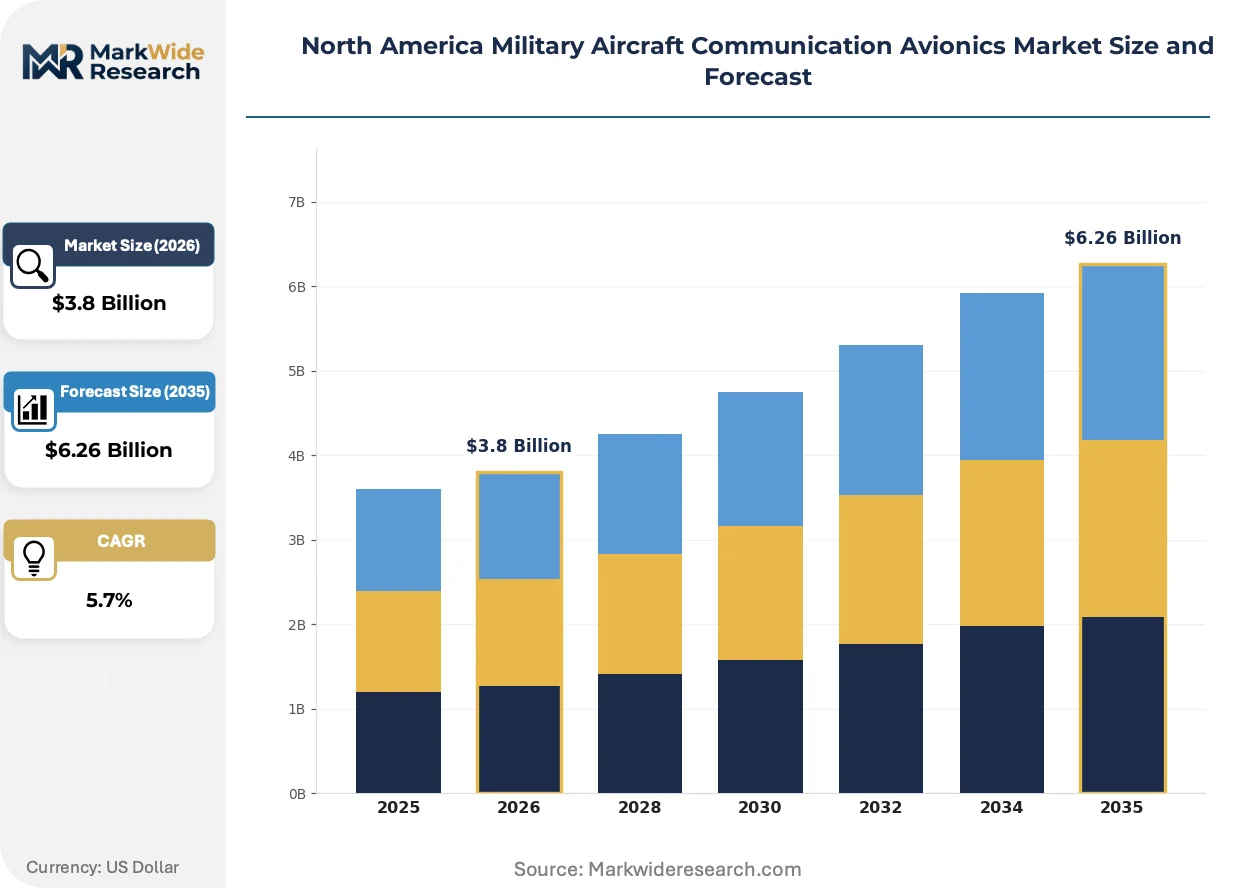
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Communication, Data Link Systems, Voice Communication, Navigation Systems Technology: Digital Processing, Analog Processing, Software-Defined Radio, Secure Communication End User: Military, Defense Contractors, Government Agencies, Security Forces Installation: In-Flight, Ground Support, Upgrade Programs, New Aircraft Deployment |
| Companies Covered | L3Harris Technologies Inc, RTX, Honeywell International Inc, BAE Systems, Northrop Grumman Corporation, Lockheed Martin Corporation, Collins Aerospace, Thales Group, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Military Aircraft Communication Avionics Market Evolving Landscape
Programmable radio architectures are collapsing the traditional boundary between hardware-defined and software-defined communication systems, with waveform portability becoming the decisive competitive variable.
Software-Defined Radio technology enables single hardware platforms to host multiple waveforms through firmware updates rather than physical module swaps. US Navy and Air Force procurement offices are prioritizing SDR-native platforms for all new-start aircraft programs. This capability is overtaking fixed-architecture radio procurement, compressing vendor margins on hardware while expanding recurring software sustainment revenue pools.
The FAA and DoD are jointly mandating zero-trust network architectures for all airborne systems handling classified data transmissions. Hardware vendors must now demonstrate supply chain provenance down to the chip level under CMMC Level 3 requirements. Fighter and bomber platforms with legacy trusted computing bases face the steepest retrofit obligations.
Platform primes are unbundling communication avionics from airframe contracts, creating direct procurement relationships between military program offices and subsystem specialists. This disintermediation is visible across F-35, F/A-18, and CH-53K programs where communication suites compete on standalone merit. Southwestern US test ranges are piloting this model most aggressively, with Edwards AFB and Yuma Proving Ground serving as evaluation gates.
North America Military Aircraft Communication Avionics Market Segmentation
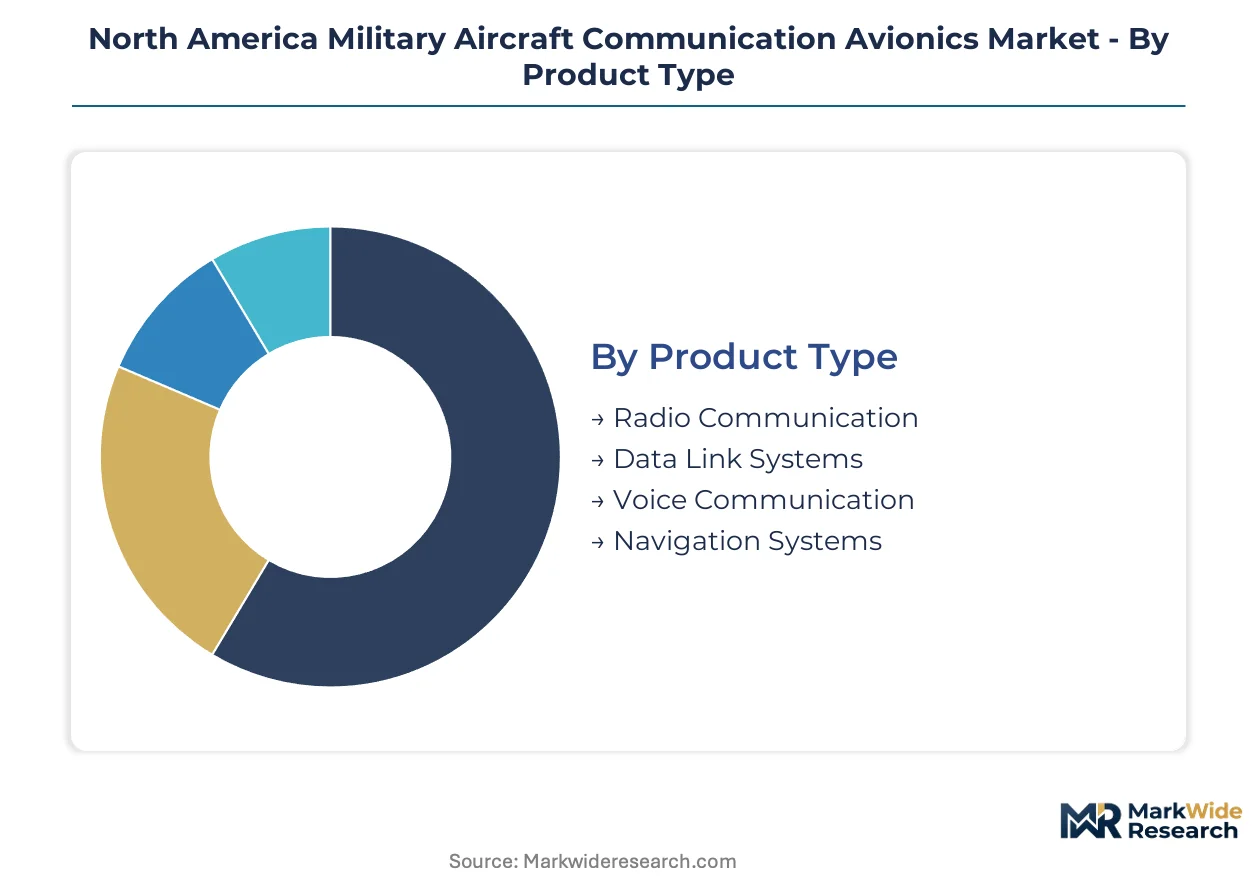
Segmentation reveals how upgrade cycles and platform modernization priorities concentrate procurement across distinct technical and operational categories. Understanding these divisions exposes where defense budgets flow and which system architectures face replacement pressure.
Product Type:
Replacement cycles vary sharply across communication hardware categories, with legacy radio systems facing accelerated displacement as networked warfare requirements intensify.
- Radio Communication:Traditional HF through UHF transceivers remain the installed base anchor across US and Canadian tactical aircraft fleets. Demand concentrates in southwestern US test ranges where legacy F-16 and F/A-18 platforms undergo communication suite refreshes ahead of retirement timelines.
- Data Link Systems:Network-centric waveform terminals enabling machine-to-machine data exchange between airborne and ground nodes. Procurement accelerates around Arizona and California flight test corridors where Link-16 and TTNT protocol validation occurs for next-generation fighter programs.
- Voice Communication:Secure cockpit and cabin audio distribution systems with embedded encryption modules.
- Navigation Systems:Integrated GPS/INS receivers with anti-spoofing protections for contested electromagnetic environments.
Radio Communication sits at the top of the volume ranking, with Data Link Systems climbing the fastest.
Technology:
Cost tiers separate programmable architectures from fixed-function hardware, with premium pricing attached to classified certification pathways.
- Software-Defined Radio:Reprogrammable waveform engines hosting multiple communication protocols through firmware updates rather than physical module swaps. US Air Force F-35 and F-22 upgrade pipelines are mandating SDR-native architectures for all new communication procurements.
- Secure Communication:NSA-certified encryption modules and anti-jam waveform processors commanding premium margins due to Type-1 certification requirements. CMMC Level 3 supply chain mandates restrict this tier to cleared domestic vendors with traceable component provenance.
- Digital Processing:FPGA-based signal processing chains replacing legacy analog filtering stages.
- Analog Processing:Legacy mixer and filter architectures persisting in cost-constrained upgrade programs.
Secure Communication commands the highest margin tier, while Software-Defined Radio gains share fastest across new-start aircraft programs.
End User:
Customer type determines procurement authority and certification rigor, with direct military acquisition carrying stricter airworthiness requirements than contractor-led integration.
- Military:Direct procurement by US Air Force, Navy, Army, and Canadian Armed Forces for operational aircraft fleets. Demand clusters around NORAD modernization initiatives requiring beyond-line-of-sight systems hardened for Arctic electromagnetic conditions.
- Defense Contractors:Platform primes including Boeing, Lockheed Martin, and Northrop Grumman sourcing communication avionics for airframe integration. Southwestern US manufacturing corridors concentrate this procurement as primes restructure around disintermediated subsystem competition.
- Government Agencies:Department of Defense research laboratories and test ranges validating prototype communication architectures.
- Security Forces:Coast Guard and border patrol aviation units with specialized surveillance communication requirements.
Military end users dominate absolute volume, with Defense Contractors expanding procurement autonomy fastest as platform primes unbundle subsystem contracts.
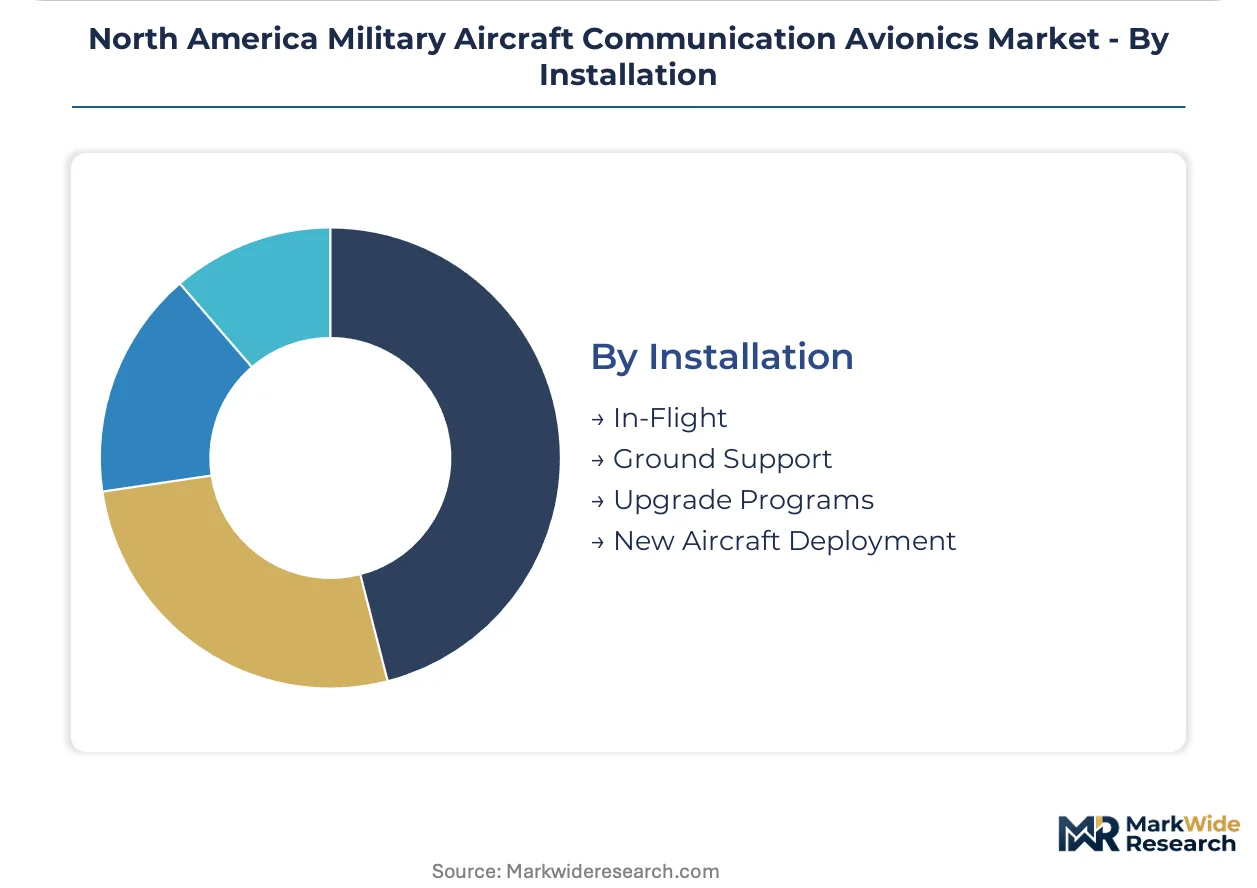
Installation:
Maturity gradients separate fresh production line integration from retrofit complexity, with upgrade programs facing steeper certification burdens than new aircraft deployment.
- Upgrade Programs:Retrofit of communication avionics into legacy platforms with MIL-STD-1553 or IEEE 1394b data bus constraints. F-35 and F/A-18 modification lines across California and Texas defense corridors drive concentrated demand for protocol bridging solutions.
- New Aircraft Deployment:Factory-integrated communication suites in F-35, B-21, and CH-53K production. Clean-sheet installation avoids legacy bus integration penalties and enables native SDR architecture from initial airworthiness qualification.
- In-Flight:Operational deployment and field maintenance of installed communication systems.
- Ground Support:Test bench and flight line maintenance equipment for communication avionics verification.
Upgrade Programs carry the heaviest engineering burden, while New Aircraft Deployment offers the cleanest integration pathway for emerging waveform standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of classified communication avionics is migrating toward southwestern US corridors where cleared workforce density and flight test infrastructure compress compliance costs relative to northeastern legacy centers.
United States
F-35 and F-22 upgrade pipelines are mandating next-generation communication suites with embedded anti-jam protocols across multiple Air Force bases. The Department of Defense's CMMC Level 3 certification requirements are filtering supplier pools toward cleared domestic entities. Arizona and California defense corridors concentrate manufacturing restructuring around reprogrammable waveform engines.
Canada
NORAD modernization initiatives are driving procurement of beyond-line-of-sight communication systems hardened for Arctic electromagnetic conditions. The Canadian Armed Forces are aligning procurement standards with US cybersecurity frameworks under bilateral defense agreements. Quebec and Ontario manufacturing bases are upgrading to meet ITAR-compliant production protocols.
Southwestern US Cluster
Edwards AFB and Yuma Proving Ground serve as evaluation gates for integrated sensor-communication systems undergoing live-fire validation. FAA and DoD joint mandates for zero-trust network architectures are accelerating retrofit programs across legacy fighter fleets. California and Arizona flight test ranges concentrate demand pull for Link-16 and TTNT protocol validation.
Southeastern US Corridor
F/A-18 modification lines across Texas defense centers drive concentrated demand for protocol bridging solutions between MIL-STD-1553 and newer IEEE 1394b data bus architectures. The Navy's software-intensive communication procurement is extending development cycles through airworthiness qualification processes. Texas-based prime contractors are restructuring around disintermediated subsystem competition.
North America Military Aircraft Communication Avionics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined radio architectures and zero-trust cybersecurity specializations. The vendor base stratifies across three maturity tiers: legacy radio manufacturers with fixed-function hardware portfolios, integrated platform primes unbundling subsystem contracts, and cleared specialists commanding premium margins on Type-1 certification pathways. Dominant competitive moves include strategic partnerships around waveform portability standards and vertical integration into GaN semiconductor foundry capacity.
Within the integrated platform tier, L3Harris Technologies and RTX exemplify archetypes restructuring around reprogrammable communication engines rather than fixed-architecture radio sets. Northrop Grumman Corporation occupies a position representing specialized low-observable communication suites tailored for stealth aircraft applications.
| Leading Market Players |
|---|
| L3Harris Technologies Inc |
| RTX |
| Honeywell International Inc |
| BAE Systems |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Collins Aerospace |
| Thales Group |
| General Dynamics Corporation |
| Others |
Value Network & Pricing Analysis
DoD CMMC Level 3 certification mandates are compressing supplier pools toward cleared domestic entities, forcing procurement offices to absorb premium pricing for traceable component provenance while squeezing margin pressure onto uncertified vendors.
Pricing Analysis
Direct-to-OEM channels handle classified communication suite procurement with volume discounts tied to multi-year fighter modernization contracts. Three-tier pricing structure across Type-1 certified secure modules, SDR-native programmable architectures, and legacy analog replacements separates NSA-certified encryption from commercial-grade alternatives. Cost compression in the analog tier is intensifying because SDR displacement eliminates hardware refresh revenue. Defense contractors show highest price sensitivity for commoditized radio sets, while military program offices accept premium positioning for anti-jam waveform processors.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from F-35 and B-21 production lines, with component sourcing concentrated in the United States, Canada, and cleared Israeli facilities. Gallium nitride substrates, FPGA signal processors, and NSA-certified encryption modules constitute critical input dependencies. Single-source vulnerability around limited GaN foundry capacity threatens amplifier production timelines. Distribution runs through prime contractor integration facilities in Arizona and California defense corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in military aircraft communication avionics rests on SDR software sustainment revenue displacing hardware-refresh cycles, with premium tiers consolidating around Type-1 certification pathways.
For Market Incumbents: Lock in waveform portability standards through strategic partnerships with DoD research laboratories, securing proprietary protocol integration that emerging SDR specialists cannot replicate. Backward integration into GaN semiconductor foundry capacity mitigates single-source substrate risk while creating captive supply advantages. CMMC Level 3 certification investment creates moats against uncertified foreign competitors. For New Entrants and Emerging Players: Capture Canadian Arctic communication modernization contracts where NORAD beyond-line-of-sight requirements outpace incumbent capacity allocation. The penetrable white-space sits in polar-hardened SDR terminals for contested electromagnetic environments. Go-to-market positioning through direct relationships with Canadian Armed Forces procurement offices bypasses US prime contractor gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with cleared specialists holding Type-1 certification and reprogrammable waveform IP rather than legacy radio hardware portfolios. Long-term viability favors vendors with software-defined architectures that compound recurring revenue through firmware update cycles. Watch F-35 Block 4 communication suite award decisions as inflection indicator for SDR-native platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Level 3 Certification Investment | Type-1 encryption module production locks out uncertified competitors from DoD procurement pools. |
| GaN Foundry Backward Integration | Captive substrate supply secures high-power RF amplification capacity against concentrated foundry bottlenecks. |
| Software-Defined Radio Platform Launch | Reprogrammable waveform engines displace fixed-architecture hardware across F-22 and F-35 upgrade pipelines. |
| Canadian Arctic Communication Partnership | NORAD modernization contracts open beyond-line-of-sight procurement outside US prime contractor channels. |
| Zero-Trust Architecture Integration | NIST cybersecurity framework compliance creates retrofit pathways for legacy fighter fleet communication backbones. |
Research Methodology
Bottom-up platform-level modeling reconciled against top-down defense budget tracking forms the analytical core of this study. Primary interviews with F-35 program office procurement leads, CMMC certification auditors, RF systems engineers at southwestern test ranges, and Canadian Armed Forces communication directors combined with secondary validation from DoD budget justification documents, FAA airworthiness certification databases, SEC contractor filings, and NTIA spectrum allocation records. Triangulation across installation data and production line disclosures verified volume estimates.
Historical trendline analysis of fighter modernization spending patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and installation pathway. CAGRs derived from platform-specific upgrade timelines and new aircraft production schedules. Industry-specific forecast inputs incorporated CMMC implementation pacing and SDR adoption curves from Navy and Air Force procurement directives.
Defense budget reallocation, CMMC enforcement delays, and GaN supply disruptions are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Aircraft Computers Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Military Avionic Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Display for Avionics Application Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Global Helicopter Avionics Market
Avionics
Global Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Military Aircraft Avionics Market
Avionics
Aircraft EMI Shielding Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Asia-Pacific Aircraft Avionics Market